
 Helianthus Annuus (Sunflower) Market | 2026-2036
Helianthus Annuus (Sunflower) Market Size, Share, and Industry Trends Forecast 2026-2036
Helianthus Annuus (Sunflower) Market Foresight
Agronomic expertise in sunflower breeding is collapsing across Eastern European growing belts, constraining yield gains just as food manufacturers seek higher oleic acid profiles. Cargill Ltd. leverages its Black Sea crushing infrastructure to sustain origination volumes despite logistical volatility. Archer Daniels Midland Co. anchors North American processing capacity through its River System assets. Syngenta AG competes on hybrid seed genetics that differentiate drought tolerance in semi-arid zones.
Helianthus annuus is an annual oilseed crop of the Asteraceae family, typically containing 40-50% oil by weight in commercial hybrids, with fatty acid profiles ranging from traditional linoleic to high-oleic variants exceeding 80% monounsaturated content. The plant serves industrial and commercial purposes primarily through crude and refined oil extraction for food frying, emulsion cosmetics, and biodiesel feedstock. Oil dominates product type value capture due to its integration into packaged food manufacturing and biofuel blending mandates, while confectionery seeds occupy a narrower but defensible premium tier in snack channels. Cosmetics application is expanding fastest among end-use segments as formulators substitute sunflower-derived emollients for mineral oil bases.
EU REACH and the EU Green Deal impose traceability and deforestation-free sourcing requirements on vegetable oil imports entering European food and cosmetic supply chains. The US FDA governs nutritional labeling and trans-fat restrictions that redirect food service demand toward high-oleic sunflower alternatives. Ukraine's State Service of Ukraine on Food Safety and Consumer Protection and Russia's national standards body regulate export quality parameters for oilseeds crossing Black Sea terminals. Stakeholders must monitor how sustainability certification schemes and origin-based trade restrictions reshape procurement geography and crushing margin structures.
Market Dynamics
Black Sea origination concentration is tightening export availability just as EU REACH and the EU Green Deal impose traceability mandates on vegetable oil imports, forcing food manufacturers to reconfigure procurement geography while crushing margins compress across Eastern European infrastructure.
Growth Catalysts
- High-Oleic Acid Profiles:Food service operators reformulate frying oils to meet FDA trans-fat restrictions, redirecting volume toward sunflower variants exceeding 80% monounsaturated content.
- EU Green Deal Deforestation-Free Mandates:The regulation requires geolocated sourcing data for oilseeds entering European cosmetic and food supply chains, advantaging Black Sea crush facilities with established traceability systems.
- Biodiesel Blending Requirements:National biofuel mandates in Germany and France are absorbing refined sunflower oil into renewable diesel feedstock pools.
Market Restraints
- Input Cost Volatility:Natural gas and electricity price swings at Ukrainian and Russian crushing plants destabilize processing economics.
- Supply Concentration Risk:Over 70% of exportable sunflower seed volume originates from farms within 500 kilometers of Black Sea ports, exposing trade flows to port closure contingencies.
- Substitution Threat:Rapeseed oil and palm oil fractions compete for packaged food frying applications on price and oxidative stability metrics.
Strategic Opportunities
- Cosmetics Emollient Substitution:Formulators in France and Germany are displacing mineral oil bases with sunflower-derived emollients in skin-care and hair-care products.
- Semi-Arid Zone Expansion:Drought-tolerant hybrid genetics enable cultivation extension into Kazakhstan and western China where irrigation infrastructure remains limited.
- Clean-Label Channel Penetration:Direct-to-retailer sourcing contracts bypass traditional commodity brokers, capturing premium positioning in European organic and non-GMO segments.
Industry Challenges
- Agronomic Expertise Collapse:Sunflower breeding programs across Romania and Bulgaria have shed technical staff, constraining yield improvement trajectories for commercial hybrids.
- Certification Timeline Compression:EU REACH dossier preparation for novel seed treatments now exceeds 18 months, delaying variety commercialization.
- Logistics Reconfiguration Friction:Alternative overland routing through Polish and Romanian rail terminals requires cold-chain infrastructure investments that crush operators have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helianthus Annuus (Sunflower) Market |
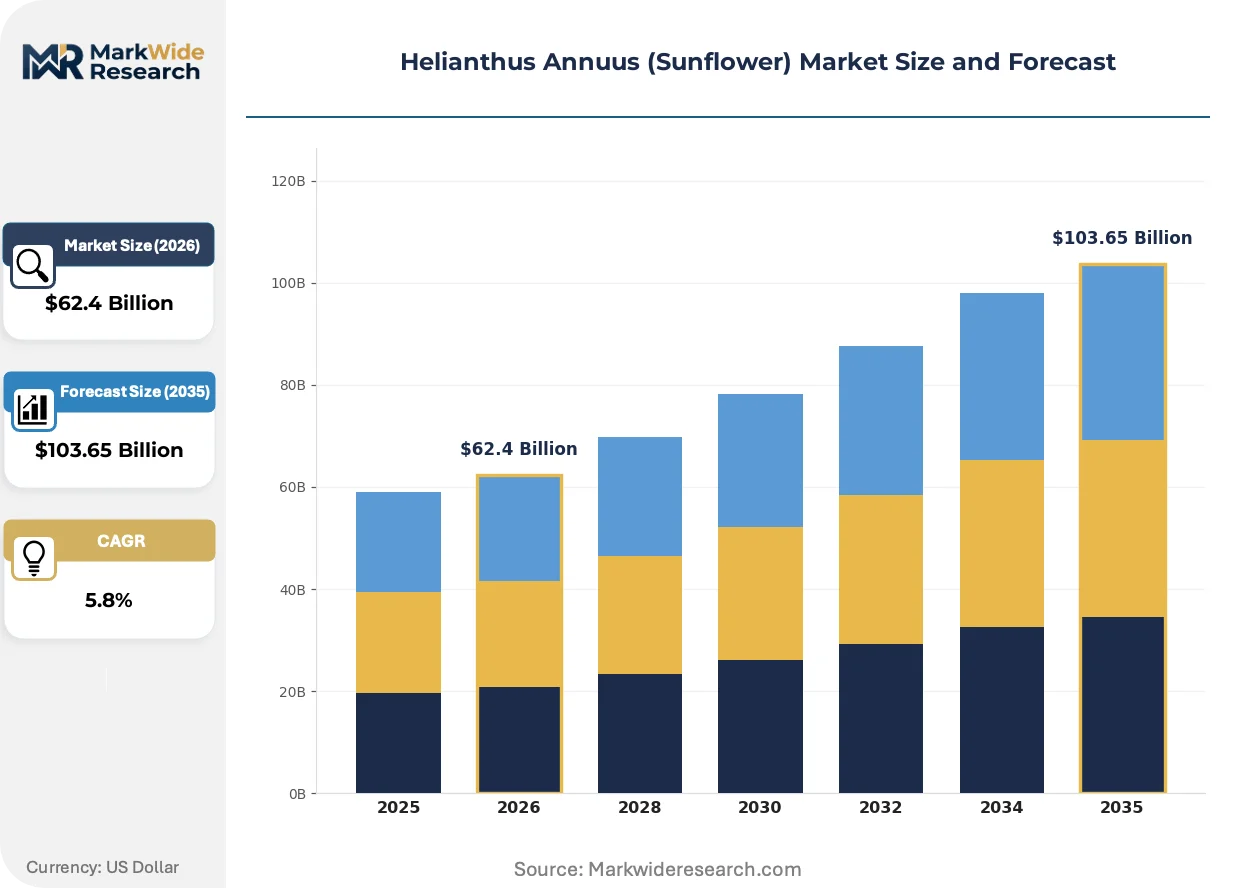
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Seeds, Snacks, Confectionery Application: Cosmetics, Food Industry, Animal Feed, Biofuel Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores End User: Food Manufacturers, Health Enthusiasts, Cosmetic Companies, Farmers |
| Companies Covered | Cargill Ltd., Archer Daniels Midland Co., Syngenta AG, Monsanto, DuPont, Corteva, Inc., KWS AG, Kernel Ltd., SunOpta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helianthus Annuus (Sunflower) Market Shifts & Advancements
Seed genetics and oil processing technology are diverging toward specialized end-use applications while regulatory frameworks fragment compliance requirements across import jurisdictions.
High-oleic sunflower oil is bifurcating the commodity oil market into functional frying grades and premium cosmetic emollient streams. Food manufacturers in North America and Western Europe are accelerating adoption of variants with oxidative stability exceeding 20 hours AOM, displacing partially hydrogenated alternatives. This technical segmentation is compressing margins on traditional linoleic grades while enabling price premiums for identity-preserved high-oleic supply chains.
EU REACH authorization procedures for seed treatment chemistries are extending regulatory lead times for new hybrid commercialization. The ECHA evaluation process now requires extended environmental fate data, delaying variety launches by 12-24 months. Ukrainian and Russian seed producers are responding by prioritizing chemistries with existing Annex XIV inclusion, constraining innovation pipelines to established active ingredient classes.
Cosmetic formulators are consolidating supplier relationships around vertically integrated crush-to-refinery operators with certified sustainability credentials. Premium skin-care brands in France and Germany now require mass balance documentation through the supply chain, displacing spot-market commodity sourcing. This preference shift is concentrating procurement volume with Black Sea processors that have invested in ISCC and RSPO-RED certification infrastructure.
Helianthus Annuus (Sunflower) Market Segmentation
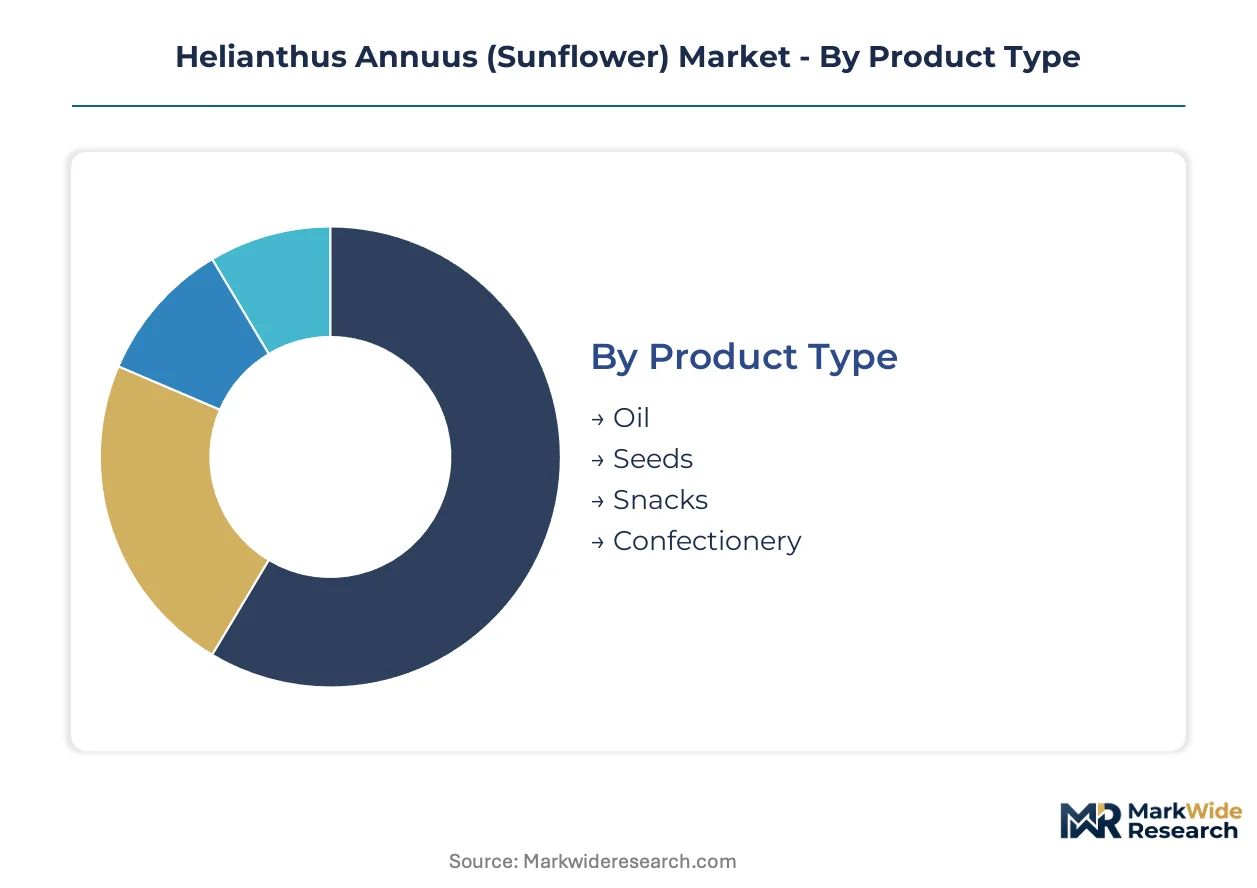
Sunflower market segmentation reflects divergent margin structures across extraction channels and end-use specifications. Food manufacturers and cosmetic formulators impose distinct purity and traceability requirements that reshape how each product type flows through distribution infrastructure.
Product Type:
Oil commands the dominant value share through food service and industrial channels, while seeds and snacks circulate through more fragmented retail pathways with divergent margin profiles.
- Oil:Crude and refined grades span traditional linoleic (40-50% oil content) to high-oleic variants exceeding 80% monounsaturated fatty acids. Food manufacturers in Germany and France absorb volume for frying and emulsion applications under EU Green Deal traceability mandates. Biodiesel blending pools in Central Europe increasingly divert refined supply from food channels.
- Seeds:Commercial hybrids bred for crushing efficiency dominate Black Sea origination volumes. Ukraine's State Service on Food Safety regulates export quality parameters for seed shipments crossing Black Sea terminals, constraining availability during port closure contingencies.
- Snacks:Roasted and flavored products target convenience retail in North American and Western European urban markets.
- Confectionery:Premium-tier in-shell and kernel products for direct consumption occupy narrower but defensible positioning in European organic and non-GMO channels.
Oil dominates installed base. Confectionery is where expansion concentrates.
Application:
End-use specifications fragment procurement patterns across regulatory jurisdictions, with EU REACH and FDA requirements diverging on traceability and compositional standards.
- Cosmetics:Formulators in France and Germany displace mineral oil bases with sunflower-derived emollients in skin-care and hair-care products. ISCC and RSPO-RED certification requirements from premium brands concentrate procurement with vertically integrated Black Sea processors.
- Food Industry:Packaged food manufacturers reformulate frying oils to meet FDA trans-fat restrictions, redirecting volume toward high-oleic variants with oxidative stability exceeding 20 hours AOM.
- Animal Feed:De-oiled meal from crushing operations supplies protein supplements for European livestock operations.
- Biofuel:National renewable diesel mandates in Germany and France absorb refined sunflower oil into feedstock pools, competing with food industry offtake.
Food Industry anchors current volume. Cosmetics is climbing the fastest.
Distribution Channel:
Channel selection determines margin capture and certification burden, with direct-to-retailer contracts bypassing traditional commodity brokerage.
- Online Retail:Direct-to-consumer platforms enable clean-label channel penetration for organic and non-GMO segments, capturing premium positioning through bypassed intermediary costs.
- Supermarkets:Mass-market packaged oil and snack products move through consolidated retail networks in Western Europe and North America.
- Wholesale:Bulk crude and refined oil flows through commodity brokers to food manufacturers and biodiesel blenders.
- Specialty Stores:Premium confectionery and identity-preserved high-oleic products target health-conscious urban consumers.
Wholesale channels dominate throughput volume. Online Retail is gaining share fastest.
End User:
User type dictates specification stringency, from bulk industrial buyers to quality-sensitive formulators requiring mass balance documentation.
- Food Manufacturers:Packaged goods producers and food service operators drive demand for high-oleic frying grades and clean-label emulsion ingredients.
- Health Enthusiasts:Direct consumers of organic, non-GMO, and cold-pressed oil products through specialty and online channels.
- Cosmetic Companies:Premium skin-care brands in France and Germany require geolocated sourcing data and sustainability certification, displacing spot-market procurement.
- Farmers:Seed purchasers for cultivation operations in Ukraine, Russia, and expanding semi-arid zones in Kazakhstan.
Food Manufacturers dominate offtake volume. Cosmetic Companies is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukrainian crush margins command premium pricing over Argentine origins due to EU Green Deal traceability requirements, while Russian port logistics volatility forces buyers to absorb alternative routing premiums through Romanian rail terminals.
Ukraine
Black Sea port concentration and high-oleic seed breeding programs drive crushing capacity expansion near Odesa and Mykolaiv. The State Service of Ukraine on Food Safety and Consumer Protection enforces export quality parameters for oilseeds crossing terminals. Crushing clusters along the Dnieper River corridor process identity-preserved seed for EU cosmetic certification schemes.
Russia
Rostov Oblast and Krasnodar Krai anchor sunflower cultivation belts supplying domestic crushers and export terminals. The national standards body regulates seed treatment chemistries under extended environmental fate data requirements. Volgograd-based processing infrastructure diverts volume toward Central Asian markets when Black Sea routes face closure contingencies.
France
Cosmetic formulators in Provence-Alpes-Côte d'Azur displace mineral oil bases with sunflower-derived emollients for premium skin-care brands. EU REACH authorization procedures extend regulatory lead times for novel seed treatments entering the market. Crushing facilities near Marseille supply mass balance documentation for ISCC-certified supply chains.
Germany
Biodiesel blending mandates in Baden-Württemberg and Bavaria absorb refined sunflower oil into renewable diesel feedstock pools competing with food industry offtake. The ECHA evaluation process requires geolocated sourcing data for oilseeds entering cosmetic supply chains. Hamburg port infrastructure handles Black Sea crude oil arrivals for Central European refining.
Argentina
Pampas cultivation belts supply conventional linoleic grades to Brazilian and Chilean food manufacturers on price-competitive terms. The national agricultural regulator oversees phytosanitary certification for seed exports to Asian markets. Rosario crushing clusters process volume for identity-preserved high-oleic contracts when Black Sea availability tightens.
Helianthus Annuus (Sunflower) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with seed genetics specialists commanding premium positioning while commodity crushers compete on origination scale and logistics efficiency. The market structure concentrates around vertically integrated agricultural conglomerates with captive Black Sea infrastructure, mid-tier regional processors dependent on spot seed procurement, and specialized hybrid seed developers licensing drought-tolerant genetics. Dominant competitive moves include backward integration into seed breeding programs and strategic partnerships with sustainability certification bodies to secure EU Green Deal compliance.
Within the integrated agricultural conglomerate tier, Cargill Ltd. and Archer Daniels Midland Co. represent archetypes of scale-driven processors leveraging river and port infrastructure to sustain origination volumes through logistical volatility. Syngenta AG occupies a position exemplifying the genetics-focused specialist model, anchoring competitive differentiation through hybrid seed development for semi-arid cultivation zones. Kernel Ltd. sits within the regional processor category, illustrating how Black Sea-based operators capture margin through proximity to concentrated farm origination.
| Leading Market Players |
|---|
| Cargill Ltd. |
| Archer Daniels Midland Co. |
| Syngenta AG |
| Monsanto |
| DuPont |
| Corteva, Inc. |
| KWS AG |
| Kernel Ltd. |
| SunOpta |
| Others |
Supply & Pricing Matrix
EU REACH dossier requirements gate both supply qualification and price differentiation simultaneously, forcing crush operators to absorb certification costs that stratify sunflower oil into premium identity-preserved tiers versus commodity spot grades. Food manufacturers and cosmetic formulators now pay premiums for mass balance documentation that commodity brokers cannot furnish.
Pricing Analysis
The customization-premium spread separates identity-preserved high-oleic contracts from conventional linoleic spot sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from natural gas cost volatility at Ukrainian crushing plants compressing processing margins. Food service operators show highest price sensitivity, while cosmetic formulators absorb premiums for ISCC-certified supply chains.
Supply Chain Analysis
Black Sea port concentration creates a chokepoint that exposes over seventy percent of exportable seed volume to closure contingencies. Ukraine, Russia, and Romania anchor origination geography. The supply chain draws from hybrid seed genetics, agricultural chemicals, and crushing equipment inputs. Single-source vulnerability concentrates at Odesa and Mykolaiv terminals. Distribution runs through vertically integrated crush-to-refinery operators with certified sustainability credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sunflower market represents high-growth disruption as EU Green Deal deforestation-free mandates reconfigure procurement geography and crush margin structures. High-oleic seed genetics and biodiesel blending requirements accelerate demand bifurcation.
For Market Incumbents: Secure backward integration into drought-tolerant hybrid breeding programs to defend against agronomic expertise collapse across Eastern Europe. Expand crushing capacity near Romanian rail terminals to mitigate Black Sea logistics volatility. ISCC certification investment locks in cosmetic formulator offtake. For New Entrants and Emerging Players: Anchor in Kazakhstan and western China semi-arid zones where irrigation infrastructure constraints limit incumbent cultivation. Target clean-label organic channels through direct-to-retailer sourcing contracts that bypass commodity brokerage. Premium positioning in non-GMO segments offers fastest margin capture. For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape toward vertically integrated crush-to-refinery operators with established traceability systems. Long-term viability favors assets with certified sustainability infrastructure and proximity to Black Sea origination belts. Watch Black Sea port throughput volatility as inflection indicator for alternative routing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hybrid Seed Breeding | Cargill and ADM control drought-tolerant genetics pipelines for semi-arid zone expansion. |
| ISCC Certification Infrastructure Investment | Kernel Ltd. captures cosmetic formulator premiums through mass balance documentation capabilities. |
| Alternative Rail Terminal Capacity Expansion | Romanian and Polish cold-chain investments reduce Black Sea port closure exposure. |
| High-Oleic Identity-Preserved Supply Chains | Syngenta AG licenses genetics enabling oxidative stability premiums for frying oil reformulation. |
| Direct-to-Retailer Clean-Label Contracts | SunOpta bypasses commodity brokers to capture organic and non-GMO channel premiums. |
Research Methodology
The analysis maps oil extraction channels, seed genetics tiers, and end-use specifications, each validated through crushing plant managers, seed procurement leads at food manufacturers, cosmetic formulator R&D directors, and biodiesel blending operators. Primary interview data triangulates against customs and trade records, ECHA REACH dossier filings, FAO production statistics, and SEC 10-K disclosures from agricultural conglomerates. Bottom-up volume estimates and top-down value reconstructions cross-validate segmentation outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, application, distribution channel, and end user dimensions alongside oleic acid profile tiers. CAGRs derive from regression analysis of historical production data and elasticity-adjusted demand projections. Forecast inputs incorporate crush margin trajectories and EU Green Deal compliance cost assumptions.
Material uncertainties — Black Sea port closure contingencies, natural gas price volatility, and EU REACH authorization delays — sit outside the modeled envelope. Forecasts reflect assumptions about seed treatment chemistry availability and biodiesel mandate absorption rates. Practitioners should keep alternative scenarios live as Black Sea logistics reconfiguration and semi-arid zone cultivation expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South America Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
South and Southeast Asia Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Buckwheat Seed Market
Seeds
Global Seed Market
Seeds
Africa Peas Market
Seeds
Faba Beans Market
Seeds
North America Grain Seed Market
Seeds
Chamomile Seeds Market
Seeds
United States Seed Market
Seeds
Russia Forage Seed Market
Seeds
South America Chia Seeds Market
Seeds
South Africa Forage Seed Market