
 Africa Seed Market | 2026-2036
Africa Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Seed Market Outlook
The capital-intensity divergence between multinational breeders and domestic seed houses is rotating competitive dynamics across the continent. Bayer AG leverages its molecular breeding infrastructure to dominate hybrid maize markets in Southern Africa. Seed Co anchors its position through deep backward integration into parent seed production across Zimbabwe and Zambia. East African Seed competes on price-accessible open-pollinated varieties tailored to rain-fed smallholder systems.
Africa seed encompasses reproductive propagules—hybrid, open-pollinated, or genetically improved—selected for germination rate, genetic purity, and trait stability under abiotic stress, serving as the foundational input for crop yield enhancement across rain-fed and irrigated systems. Cereals command the dominant value pool given maize dependency across Eastern and Southern African food systems, while vegetable seed margins concentrate in greenhouse supply chains serving urban retail corridors. Oilseeds represent the fastest-expanding product category as crush capacity expands in Ethiopia and Nigeria, though pulse seed remains structurally underdeveloped outside specific export-oriented zones.
Kenya's national seed regulator and South Africa's Department of Agriculture, Land Reform and Rural Development enforce certification tiers that filter market access, while the African Seed and Biotechnology Association coordinates harmonized variety testing protocols across regional economic communities. These frameworks elevate quality assurance costs for entrants but protect farmer trust in labeled germplasm performance. Stakeholders must monitor evolving national biosafety authority positions on gene-edited varieties, as regulatory clarity will determine whether CRISPR-derived drought tolerance reaches smallholder channels before germplasm obsolescence accelerates.
Market Dynamics
Climate stress is compressing variety replacement cycles across Africa, forcing seed houses to accelerate drought-tolerant germplasm pipelines while Kenya's national seed regulator tightens certification protocols.
Growth Catalysts
- East African Seed Regulation:Kenya's national seed regulator is tightening variety release protocols, pushing commercial farming operations toward certified drought-tolerant hybrids and filtering substandard germplasm from circulation.
- Smallholder Aggregation Programs:Nigeria and Ethiopia are channeling bulk purchases toward improved germplasm through structured aggregation, concentrating demand for certified seed in high-volume procurement corridors.
- Crush Capacity Expansion:Ethiopia and Nigeria are expanding oilseed processing infrastructure, creating pull-through demand for improved soybean and sunflower germplasm with higher oil content traits.
Market Restraints
- Parent Seed Supply Concentration:Southern Africa's parent seed production clusters in Zimbabwe and Zambia create geographic chokepoints that amplify supply risk during regional drought events.
- Certification Cost Escalation:Harmonized variety testing protocols coordinated by the African Seed and Biotechnology Association elevate quality assurance costs for new entrants without established testing infrastructure.
- Informal Seed Substitution:Farm-saved open-pollinated varieties and recycled hybrid seed continue to displace certified purchases in rain-fed smallholder systems where price sensitivity dominates.
Strategic Opportunities
- Gene-Edited Variety Channels:Regulatory clarity from national biosafety authorities on CRISPR-derived drought tolerance will determine whether accelerated breeding timelines reach smallholder distribution before germplasm obsolescence accelerates.
- Vegetable Seed Premiumization:Greenhouse supply chains serving urban retail corridors in Nairobi, Lagos, and Addis Ababa concentrate margins in hybrid tomato, pepper, and onion germplasm.
- Pulse Seed Development:Export-oriented zones in Ethiopia and Tanzania present white space for improved chickpea and common bean varieties with enhanced disease resistance profiles.
Industry Challenges
- Parent Seed Production Talent Scarcity:Skilled breeders and field technicians capable of maintaining genetic purity in hybrid parent lines remain concentrated in Southern Africa, constraining expansion elsewhere.
- Certification Timeline Compression:Multi-season variety testing requirements under regional economic community protocols delay commercialization of climate-adaptive germplasm when farmer need is most acute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Seed Market |
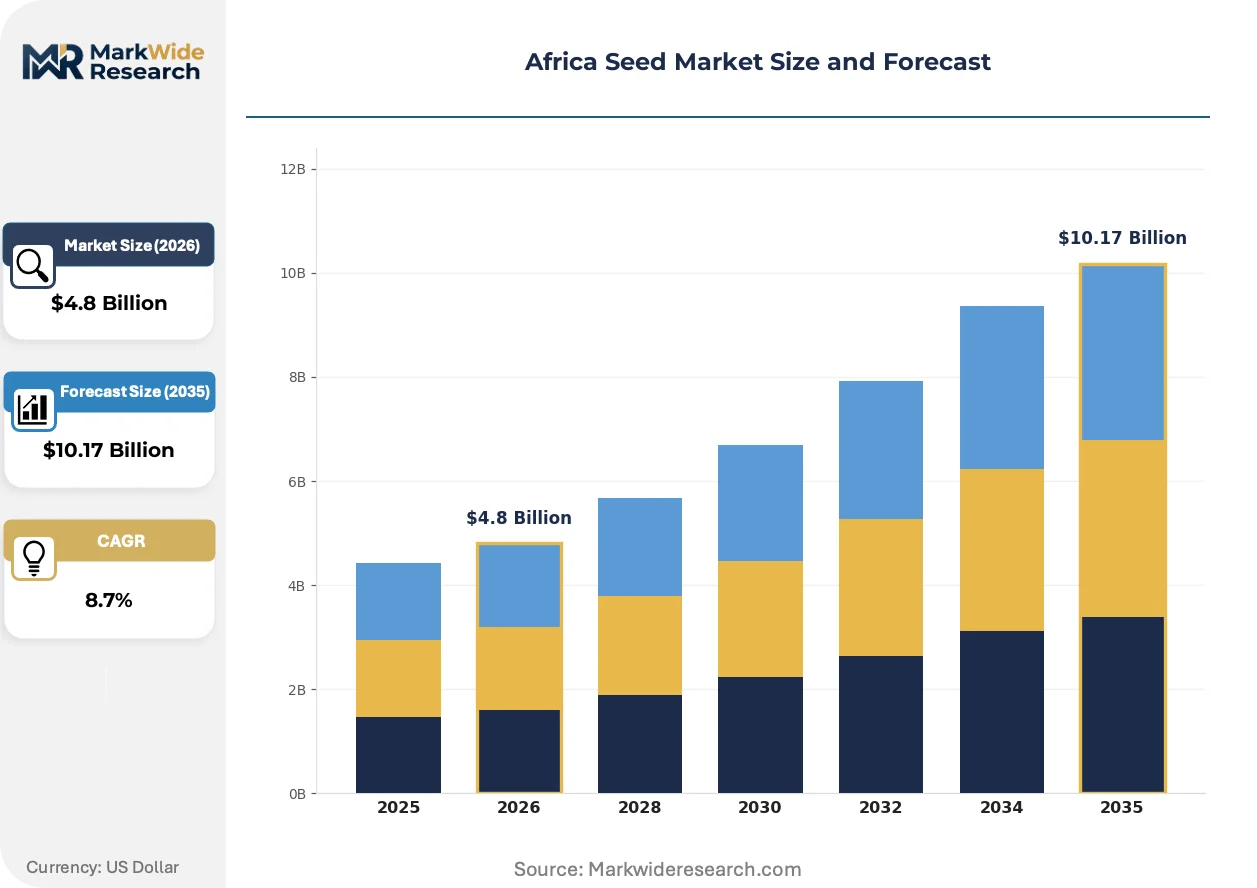
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Pulses, Vegetables, Oilseeds End Use Industry: Agriculture, Horticulture, Commercial Farming, Subsistence Farming Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce Packaging Type: Bags, Bulk, Boxes, Pallets |
| Companies Covered | Bayer AG, Syngenta Group, Corteva Agriscience, East-West Seed, Seed Co, East African Seed, Kenya Seed Company, Groupe Limagrain, BASF SE, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Seed Market Strategic Shifts
Molecular breeding infrastructure is compressing development timelines for climate-adaptive traits, while regulatory positioning on gene-edited varieties determines which seed houses capture first-mover advantage in drought tolerance.
Marker-assisted selection platforms are displacing conventional phenotypic screening in hybrid maize development pipelines across Southern Africa. Bayer AG and established regional breeders are deploying these tools to halve variety development cycles for drought tolerance. This acceleration is compressing competitive windows for domestic seed houses lacking equivalent molecular infrastructure.
Kenya's national seed regulator is enforcing tiered certification standards that filter market access based on germination rate and genetic purity thresholds. These protocols protect farmer trust in labeled germplasm performance but elevate compliance costs for entrants. Smallholder-focused seed houses are responding by concentrating open-pollinated variety portfolios where regulatory burden is lighter.
Urban retail corridor expansion is restructuring vegetable seed demand toward greenhouse-optimized hybrids with extended shelf life and uniform fruit set. Nairobi and Lagos supermarket procurement specifications now prioritize these traits, displacing open-pollinated field varieties in peri-urban supply chains. East African Seed and regional specialists are reconfiguring product portfolios to capture this channel migration.
Africa Seed Market Segmentation
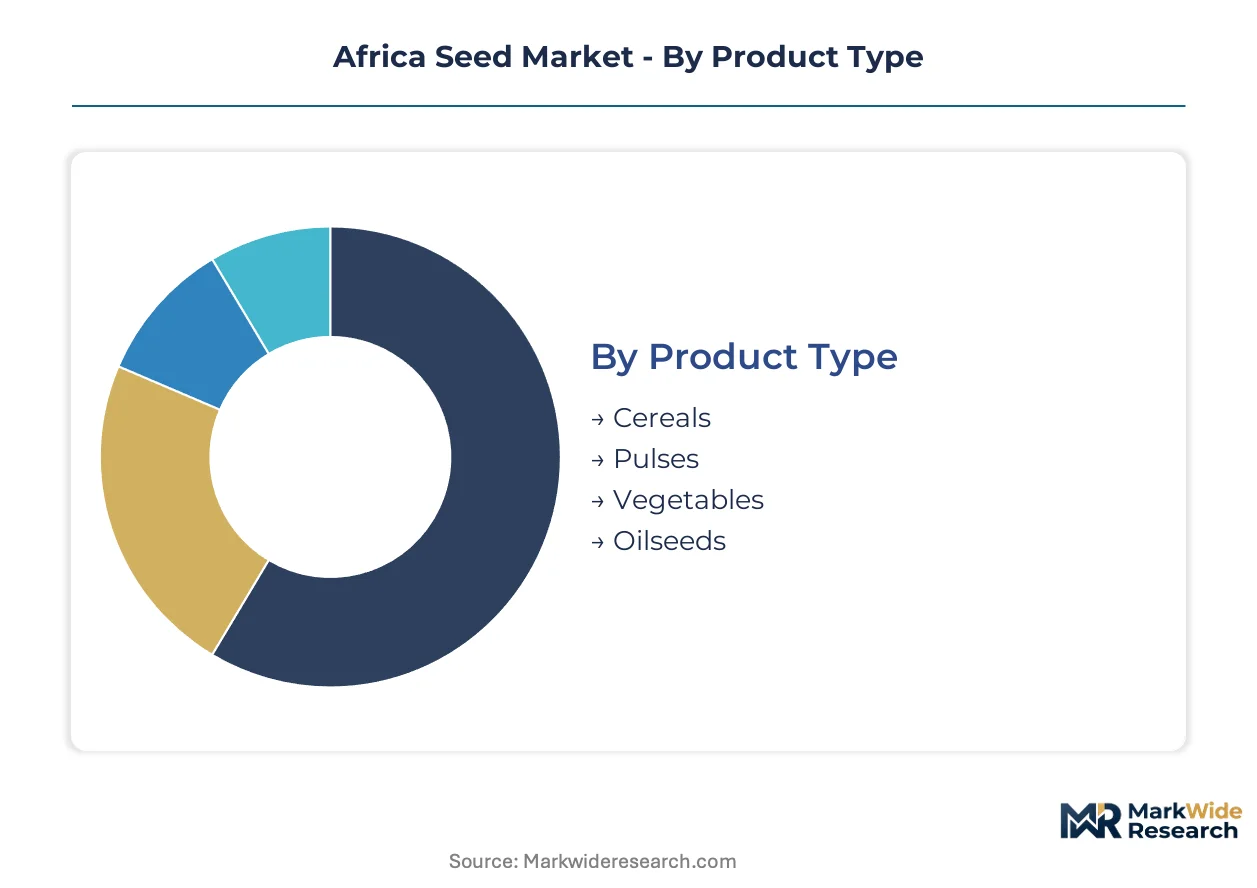
Seed procurement patterns across Africa diverge sharply by crop category and farming system, with substitution threats from farm-saved germplasm reshaping competitive dynamics. Understanding where certified seed displaces informal channels versus where recycled varieties persist determines portfolio allocation and distribution investment priorities for suppliers.
Product Type:
Farm-saved open-pollinated varieties exert the strongest substitution pressure on segments where seed recycling maintains acceptable genetic stability, compressing pricing power and forcing differentiation through trait performance guarantees.
- Cereals:Hybrid and open-pollinated maize, sorghum, and millet varieties engineered for drought tolerance and high germination rates under abiotic stress. Demand concentrates in Kenya's Rift Valley and Nigeria's northern grain belts where commercial farming operations scale certified procurement to meet processor specifications for aflatoxin control and moisture content.
- Oilseeds:Improved soybean, sunflower, and groundnut germplasm selected for oil content, disease resistance, and crush efficiency. Ethiopia's expanding processing infrastructure around Addis Ababa and Nigeria's northern oilseed corridors pull through premium-priced certified seed as crush capacity tightens feedstock supply.
- Vegetables:Hybrid tomato, pepper, onion, and brassica varieties optimized for greenhouse production and extended shelf life. Nairobi and Lagos urban retail corridors concentrate demand for uniform fruit set and post-harvest durability.
- Pulses:Chickpea, common bean, and cowpea varieties with enhanced nitrogen fixation and disease resistance profiles. Export-oriented zones in Ethiopia's highlands and Tanzania's northern corridor present nascent demand for certified germplasm.
Cereals retain volume leadership; oilseeds hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates input-intensive commercial systems from price-constrained subsistence operations, determining where trait premiums command price acceptance versus where basic germplasm suffices.
- Commercial Farming:Large-scale mechanized operations purchasing certified hybrid seed in bulk through structured procurement programs. Kenya's flower farms and South Africa's grain estates demand varietal purity certificates and traceability documentation for export compliance.
- Agriculture:Mid-scale rain-fed crop producers balancing yield improvement against input cost sensitivity. Nigeria's maize belt and Ethiopia's teff-growing highlands channel aggregation program purchases toward improved open-pollinated varieties.
- Horticulture:Peri-urban vegetable producers supplying formal retail and food service channels. Greenhouse clusters around Addis Ababa and Kigali prioritize hybrid germplasm with disease resistance and marketable yield consistency.
- Subsistence Farming:Smallholder systems relying on farm-saved seed and informal exchange networks. Price sensitivity and limited liquidity constrain certified seed penetration across Sahelian and East African rain-fed zones.
Commercial farming commands the highest per-hectare seed expenditure; horticulture is climbing the fastest on unit margin expansion.
Distribution Channel:
Geographic reach and customer density determine channel economics, with infrastructure gaps favoring certain modalities in specific country contexts.
- Retail:Agro-dealer networks stocking certified seed in small package sizes accessible to smallholders. Kenya's agro-dealer certification program and Tanzania's hub-and-spoke rural distribution systems concentrate this channel in East African commercial corridors.
- Wholesale:Bulk procurement through cooperatives, aggregators, and processor-linked input programs. Nigeria's Anchor Borrowers' Program and Ethiopia's Agricultural Transformation Agency channel wholesale volumes toward improved germplasm.
- Direct Sales:Seed house field staff contracting directly with commercial farming operations and estate managers. Southern Africa's hybrid maize markets rely on direct technical support for parent seed coordination and agronomic guidance.
- E-commerce:Emerging digital platforms connecting urban-based input suppliers with peri-urban and rural customers. Kenya's M-Pesa integration and Nigeria's agritech startups pilot last-mile delivery models for vegetable seed and specialty crops.
Retail maintains the broadest smallholder reach; e-commerce is scaling most quickly on mobile payment penetration.
Packaging Type:
Volume scale and handling infrastructure shape packaging preferences, with bulk formats dominating commercial procurement and unitized packages serving fragmented smallholder demand.
- Bulk:Unpackaged seed delivered in loose quantities for large-scale planting operations. Commercial maize and soybean producers in South Africa and Zambia favor bulk delivery to on-farm storage silos.
- Bags:Standard woven polypropylene sacks ranging from 2kg to 50kg for retail and wholesale distribution. Kenya's agro-dealer networks and Nigeria's input subsidy programs standardize on 10kg and 25kg bag formats.
- Boxes:Rigid containers for high-value vegetable seed and specialty germplasm requiring moisture protection. Greenhouse tomato and pepper seed shipments to Nairobi and Lagos horticulture clusters utilize branded box packaging.
- Pallets:Unitized loads for efficient handling in wholesale and export logistics. Seed Co's Zimbabwe parent seed exports and Bayer's Southern Africa distribution leverage palletized consolidation for regional supply.
Bags retain the highest transaction frequency; bulk is gaining share fastest on commercial farming consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the continent diverge sharply between Southern Africa's hybrid-dependent commercial estates and East Africa's rain-fed smallholder systems where open-pollinated varieties retain stubborn penetration.
Kenya
Kenya's Rift Valley commercial farming corridor drives certified maize seed procurement to meet processor specifications for aflatoxin control. The country's national seed regulator enforces tiered certification standards that filter substandard germplasm from circulation. Nairobi's peri-urban greenhouse clusters concentrate demand for hybrid tomato and pepper varieties with extended shelf life traits.
Nigeria
Nigeria's northern grain belts channel bulk purchases toward improved germplasm through the Anchor Borrowers' Program and structured smallholder aggregation. The country's national agricultural transformation agency coordinates input subsidy distribution toward drought-tolerant hybrids. Kano and Kaduna serve as procurement hubs where oilseed crush capacity expansion pulls through certified soybean seed.
Ethiopia
Ethiopia's highland teff-growing zones and emerging oilseed corridors concentrate demand for certified germplasm through the Agricultural Transformation Agency's wholesale procurement programs. The country's biosafety authority positions on gene-edited variety regulation will determine CRISPR-derived drought tolerance access. Addis Ababa's peri-urban greenhouse supply chains prioritize hybrid vegetable seed with uniform fruit set specifications.
South Africa
South Africa's Department of Agriculture, Land Reform and Rural Development enforces certification tiers that protect farmer trust in labeled germplasm performance. The country's grain estates and flower farms demand varietal purity certificates for export compliance. Limpopo and Free State commercial maize operations anchor regional hybrid seed consumption through direct technical support channels.
Zimbabwe
Zimbabwe's parent seed production clusters supply hybrid maize germplasm across Southern Africa, creating geographic concentration that amplifies supply risk during regional drought events. The country's national seed certification framework aligns with regional economic community protocols. Harare and Bulawayo anchor Seed Co's backward integration into parent line maintenance and field technician training.
Africa Seed Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with molecular breeding infrastructure separating premium hybrid developers from price-accessible open-pollinated variety suppliers. Bayer AG and Syngenta Group anchor the upper tier through proprietary trait platforms, while regional seed houses compete on distribution density and local adaptation knowledge. Three archetypes dominate: multinational breeders with gene-editing capabilities, Southern African integrated houses controlling parent seed supply, and East African specialists serving rain-fed smallholder price points. Competitive moves center on regulatory positioning for gene-edited variety approval and backward integration into parent seed production.
Within the multinational tier, Bayer AG and Syngenta Group represent the molecular breeding infrastructure that compresses drought-tolerance development timelines. Seed Co and East African Seed exemplify regional archetypes—Zimbabwe-based integration versus Kenya-focused price accessibility. Corteva Agriscience occupies a position bridging global trait platforms with emerging market distribution adaptation.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| East-West Seed |
| Seed Co |
| East African Seed |
| Kenya Seed Company |
| Groupe Limagrain |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Parent seed production scale economies in Zimbabwe and Zambia anchor regional supply concentration while simultaneously establishing price floors for hybrid maize germplasm across Southern Africa. Kenya's certification tier enforcement and Nigeria's aggregation program procurement collectively compress margins for entrants lacking equivalent backward integration into parent line maintenance.
Pricing Analysis
After-sales agronomic support and replant guarantee programs drive lifetime value for commercial farming accounts in South Africa and Kenya. Three-tier pricing structure across premium certified hybrids, standard open-pollinated varieties, and economy farm-saved seed dominates transactional patterns. Cost compression in the standard tier intensifies as Seed Co and East African Seed compete on distribution density. Subsistence farming systems exhibit highest price sensitivity while Kenya's flower farms and South Africa's grain estates demonstrate lowest sensitivity due to export compliance requirements.
Supply Chain Analysis
Zimbabwe's parent seed production clusters and Zambia's field technician training infrastructure create geographic chokepoints that amplify supply risk during regional drought events. The Africa seed supply chain draws from captive parent line production in Southern Africa, germplasm licensing from multinational breeders, and quality testing infrastructure concentrated in Kenya and South Africa. Single-source vulnerability in parent seed genetics constrains rapid variety replacement when climate stress accelerates obsolescence. Distribution runs through agro-dealer certification programs in East Africa and direct technical support channels for Southern African commercial estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical agronomy services and replant guarantee programs expand faster than germplasm unit sales, converting transactional seed purchases into recurring advisory relationships across Kenya's commercial corridors.
For Market Incumbents: Secure backward integration into parent seed production across Zimbabwe and Zambia to defend against supply disruption during regional drought events. Deepen certification infrastructure investment in Kenya to maintain tiered standard enforcement that filters substandard competitors. Gene-edited variety regulatory positioning represents the critical lever for first-mover capture in drought tolerance segments. For New Entrants and Emerging Players: Lead with pulse seed development in Ethiopia's highland export zones and Tanzania's northern corridor where certified germplasm penetration remains nascent. Target vegetable seed premiumization through greenhouse supply chain partnerships in Nairobi and Lagos peri-urban clusters. Digital platform integration with mobile payment systems offers the most penetrable go-to-market angle for reaching fragmented smallholder demand. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated seed houses controlling parent line production and technical service attach rates. Long-term viability over the projection horizon favors Southern African integrated breeders with captive germplasm supply and East African specialists with agro-dealer certification density. Watch national biosafety authority positioning on CRISPR-derived varieties as the inflection indicator for accelerated breeding timeline competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Parent Seed Production Expansion | Captive supply of hybrid parent lines in Zimbabwe reduces germplasm cost volatility for Southern African markets. |
| Gene-Edited Variety Regulatory Pathway | Early positioning with Kenya's biosafety authority accelerates drought tolerance variety commercialization timelines. |
| Agro-Dealer Certification Program | Kenya's tiered dealer standards build distribution trust barriers against informal seed substitution. |
| Greenhouse Supply Chain Partnership | Direct technical relationships with Nairobi and Lagos peri-urban producers capture vegetable seed margin expansion. |
| Pulse Seed Development Pipeline | Chickpea and common bean variety investment in Ethiopia's highlands addresses structurally underdeveloped export demand. |
Study Parameters
Operator-level perspectives from seed house breeding directors, agro-dealer network managers, national seed regulator certification officers, and commercial farming procurement leads anchored the qualitative base. Secondary validation drew from African Seed and Biotechnology Association harmonized testing protocols, Kenya Plant Health Inspectorate Service variety release records, national agricultural transformation agency procurement disclosures, and regional economic community trade flow documentation. Bottom-up variety-level demand modeling and top-down agricultural input expenditure triangulation produced convergent volume estimates.
Sensitivity analysis across regulatory approval timelines, climate stress severity scenarios, and smallholder aggregation program penetration rates tested forecast robustness. Segmentation dimensions modeled include crop category, farming system intensity, distribution channel density, and packaging format scale throughout the projection horizon. CAGRs derived from trend extrapolation of certified seed displacement rates against farm-saved germplasm persistence, with oilseed crush capacity expansion and vegetable greenhouse cluster development as primary demand pull inputs.
Forecasts assume regulatory continuity in Kenya's tiered certification framework and South Africa's Department of Agriculture enforcement protocols; material policy shifts would require re-modeling variety release timelines and import approval pathways. Practitioners should keep alternative scenarios live as national biosafety authority positions on gene-edited varieties and regional drought frequency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Tallow Tree Seed Market
Seeds
Cover Crop Seed Varieties Market
Seeds
China Seed Market
Seeds
Apple Seed Oil Market
Seeds
Buckwheat Market
Seeds
Sri Lanka Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Native Grass Seeds Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Myanmar Seed Market
Seeds
Europe Flaxseeds Market
Seeds
China Rice Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Agricultural Seeder Market
Seeds
Global Sunflower Market
Seeds
Punnet Market