
 Grass Seed Market | 2026-2036
Grass Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Grass Seed Market Analysis
AOSCA certification is reorganizing competitive access in the grass seed trade, as certified seed lots command premium placement in professional channels. Pennington Seed Inc. leverages extensive R&D networks to sustain varietal leadership in turf-type tall fescue. DLF Pickseed anchors northern European supply through controlled production of perennial ryegrass cultivars. Scotts Miracle-Gro Company competes through retail channel dominance and consumer brand recognition.
Grass seed comprises the dried, mature ovules of Poaceae species selected for germination rate, purity, and specific performance traits such as drought tolerance or wear recovery, serving primarily to establish vegetative ground cover for aesthetic, recreational, or erosion-control purposes. Kentucky bluegrass maintains mature margin pools in residential lawn replacement cycles where homeowners prioritize self-repairing turf. Bermudagrass represents the fastest-growing product type as warm-climate sports facilities convert to hybrid varieties for improved playability.
The USDA and EPA shape US grass seed markets through plant variety protection and pesticide tolerance standards that determine which cultivars reach commercial scale. REACH compliance in Europe restricts chemical coatings on imported seed, altering formulation strategies for suppliers targeting EU turf professionals. Stakeholders must monitor how evolving water-use regulations across municipalities redefine acceptable grass species lists for public landscaping contracts.
Market Dynamics
EU F-Gas Regulation restrictions on synthetic turf refrigerants are redirecting capital toward natural grass systems and certified seed varieties, compressing installation timelines for stadium renovations across European markets.
Growth Catalysts
- Professional Sports Turf Mandates:Stadium renovation specifications increasingly require AOSCA-certified seed lots, locking out uncertified suppliers from premium channels.
- Water-Use Ordinances:Municipal drought restrictions in California, Texas, and Arizona are expanding acceptable species lists toward drought-tolerant cultivars.
- Hybrid Bermudagrass Conversion:Warm-climate sports facilities are replacing traditional surfaces with improved playability varieties.
Market Restraints
- Input Cost Volatility:Nitrogen fertilizer price swings compress margin predictability for turf establishment contractors.
- Supply Concentration Risk:Perennial ryegrass foundation seed production clusters in Oregon's Willamette Valley, creating weather-dependent bottlenecks.
- Regulatory Friction:REACH compliance requirements for seed coatings block non-EU formulated products from European professional channels.
Strategic Opportunities
- Carbon Sequestration Incentives:USDA conservation programs now credit permanent turf establishment, opening public land renovation bids.
- Direct-to-Sports-Facility Distribution:Bypassing traditional distributor layers, suppliers contract directly with municipal park departments and collegiate athletic departments.
- Endophyte-Enhanced Varieties:Converging plant breeding and biologicals research creates premium positioning against commodity seed.
Industry Challenges
- Certification Timeline Compression:AOSCA field inspection and laboratory testing cycles lag behind compressed stadium renovation schedules.
- Genetic Purity Enforcement:Off-type contamination in foundation seed stocks triggers costly lot rejections and replanting obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass Seed Market |
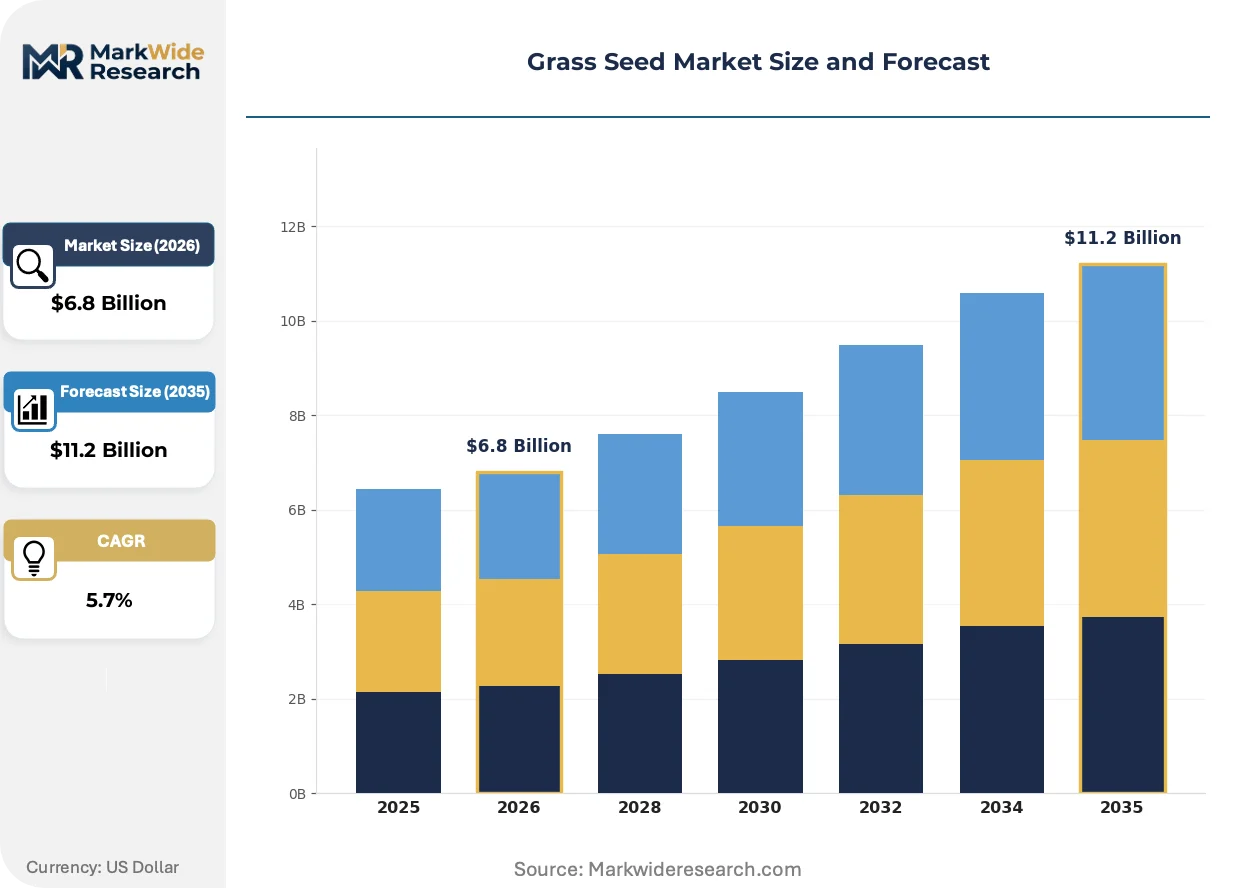
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perennial Ryegrass, Kentucky Bluegrass, Fescue, Bermudagrass Application: Residential Lawns, Commercial Lawns, Sports Fields, Golf Courses Packaging Type: Bulk Bags, Retail Packs, Seed Blends, Eco-Friendly Packaging Distribution Channel: Online Sales, Garden Centers, Home Improvement Stores, Agricultural Suppliers |
| Companies Covered | ICL GROUP, Pennington Seed Inc., Nutrien Ltd., LebanonTurf, Johnston Seed Company, Scotts Miracle-Gro Company, Barenbrug NZ, Seed Research of Oregon, DLF Pickseed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass Seed Market Emerging Trajectories
Synthetic turf cooling limitations and refrigerant phase-downs are accelerating investment in natural grass breeding programs, precision establishment techniques, and climate-adapted cultivar development.
Endophyte-enhanced tall fescue is decomposing the commodity seed market by bundling biological pest resistance with germination guarantees. Professional turf managers at collegiate and municipal facilities are specifying endophyte-positive varieties for reduced chemical input contracts. This biological integration is compressing price premiums for conventional untreated seed in premium channels.
EU F-Gas Regulation phase-down schedules are prohibiting hydrofluorocarbon-based turf cooling systems in new stadium constructions. Facility operators in Germany, France, and the Netherlands are reverting to natural grass specifications with subsurface aeration and drainage upgrades. Seed suppliers are responding with wear-recovery-focused perennial ryegrass blends engineered for shorter renovation windows.
Specification-driven procurement now dominates professional channels, displacing price-first purchasing. Municipal park departments and sports facility managers are pre-qualifying certified seed lots before bid solicitation, locking commodity suppliers out of premium contracts. This shift concentrates procurement authority with certified breeders in the United States and northern Europe.
Grass Seed Market Segmentation
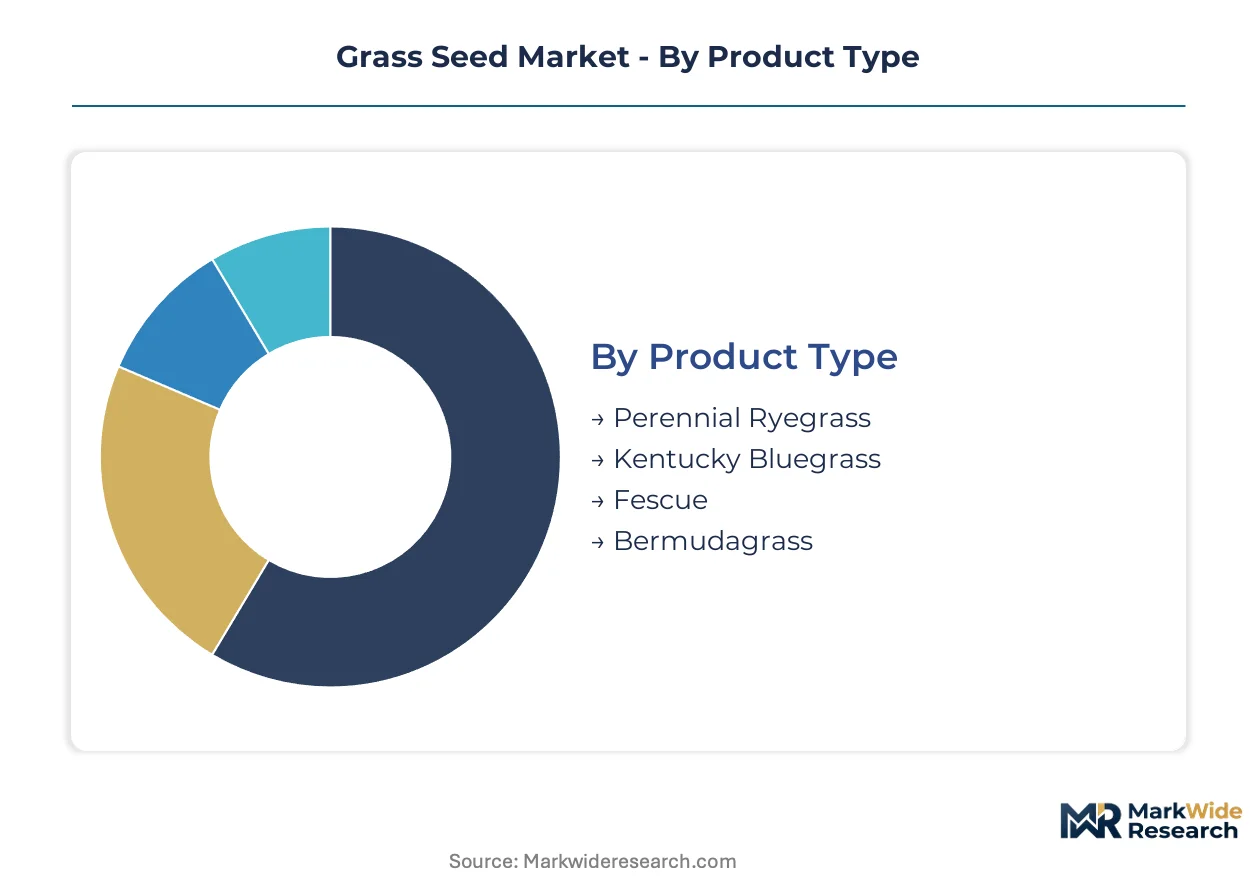
Grass seed procurement patterns diverge sharply across end-use contexts, with certified varieties commanding premium placement in professional channels while commodity lots dominate consumer retail. Specification requirements from sports turf managers and municipal buyers now override price sensitivity in high-value segments.
Product Type:
EU F-Gas Regulation phase-downs and USDA plant variety protection standards create divergent compliance burdens across species, favoring cultivars with established certification pipelines.
- Perennial Ryegrass:Rapid-establishment species with fine texture and wear tolerance. Oregon's Willamette Valley concentrates foundation seed production, exposing supply to weather-dependent bottlenecks that compress availability timelines for European stadium renovations.
- Bermudagrass:Warm-season C4 species with aggressive stoloniferous spread and heat tolerance. Texas, Arizona, and Florida athletic facilities are converting to hybrid varieties for improved playability and reduced irrigation inputs under municipal water-use ordinances.
- Kentucky Bluegrass:Self-repairing rhizomatous cool-season turf with dense mat formation. Maintains mature margin pools in Midwest and Northeast residential replacement cycles where homeowners prioritize recuperative capacity.
- Fescue:Shade-tolerant bunchgrass species including tall fescue and fine fescue. Endophyte-enhanced cultivars are gaining specification in reduced-chemical maintenance contracts.
Established volume favors Kentucky bluegrass; emerging adoption favors Bermudagrass.
Application:
Contract value and input intensity separate segments, with sports facilities tolerating establishment costs that residential consumers reject.
- Sports Fields:High-wear surfaces requiring rapid establishment and recovery protocols. Collegiate and municipal athletic departments now mandate AOSCA-certified seed lots in pre-qualification requirements, excluding uncertified suppliers from bid participation.
- Golf Courses:Precision-managed playing surfaces with cultivar-specific fairway and rough specifications. Renovation timelines compress during shoulder seasons, demanding seed lots with verified germination rates and genetic purity documentation.
- Residential Lawns:Price-sensitive consumer segment with seasonal replacement cycles. Big-box retail and garden center channels dominate, with brand recognition outweighing certification status.
- Commercial Lawns:Corporate and institutional grounds maintenance with moderate wear tolerance requirements. Procurement typically routes through landscape service contractors rather than direct seed purchase.
Margin concentration sits with sports fields; volume scale sits with residential lawns.
Packaging Type:
REACH compliance requirements in Europe and state-level plastic restrictions in California reshape formulation and container strategies.
- Bulk Bags:Professional-channel delivery format for contractors and municipal buyers. Oregon and Washington production facilities ship directly to turf establishment projects, bypassing retail markup layers.
- Seed Blends:Multi-species formulations engineered for specific climate zones and use intensities. Custom blending services command premium positioning against off-the-shelf alternatives.
- Retail Packs:Consumer-facing unit sizes for home improvement and garden center channels. Seasonal demand concentrates in spring and fall replacement windows.
- Eco-Friendly Packaging:Biodegradable or recyclable containers responding to municipal procurement sustainability mandates. Limited penetration outside public sector contracts with explicit environmental scoring.
Operational scale favors bulk bags; differentiation potential favors eco-friendly packaging.
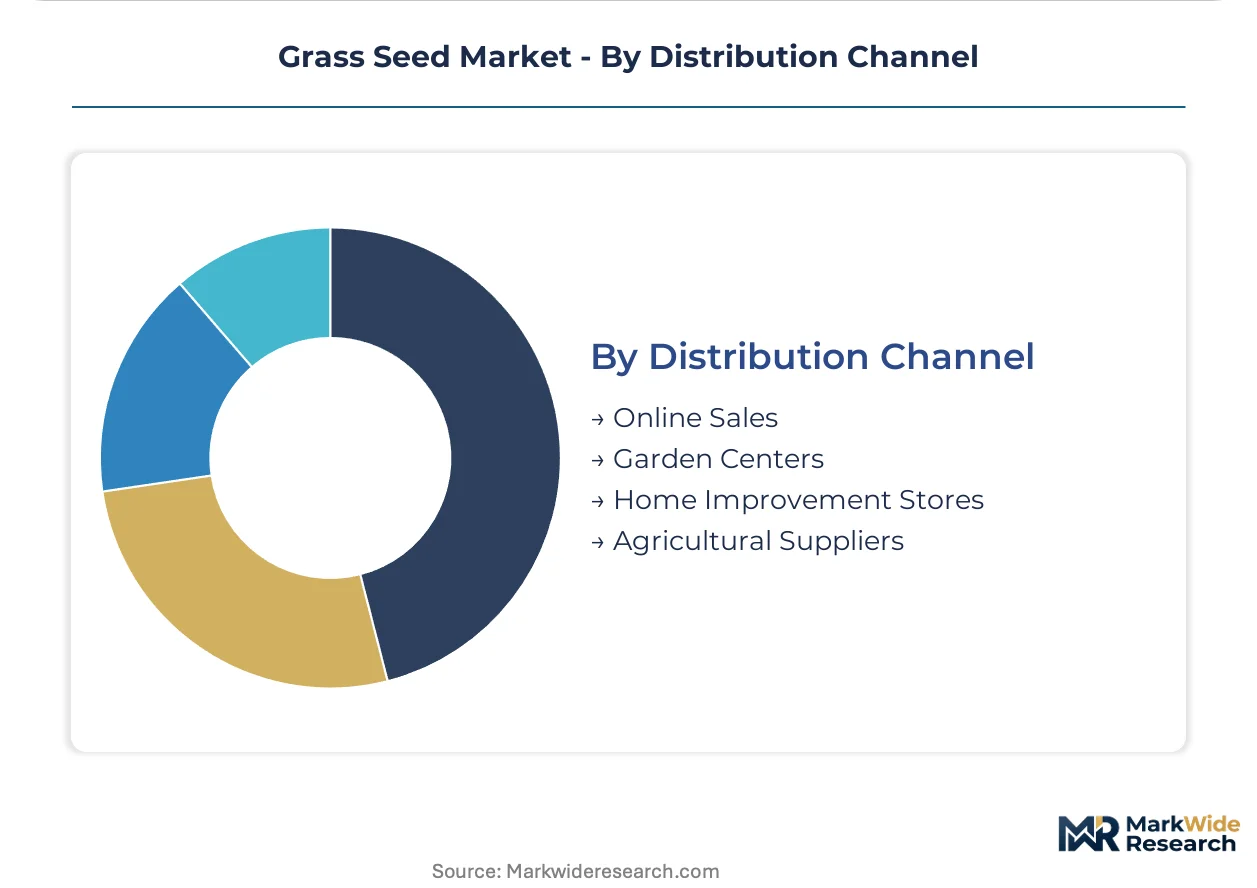
Distribution Channel:
Channel selection determines customer access and margin capture, with direct contracting disrupting traditional wholesale layers.
- Agricultural Suppliers:Professional-focused distributors with technical sales support and certified seed inventory. Field representatives advise turf managers on cultivar selection and establishment protocols.
- Online Sales:Direct-to-consumer and direct-to-facility platforms expanding share in convenience-driven segments. Subscription models for seasonal lawn maintenance products are emerging.
- Garden Centers:Local retail with seasonal staffing and limited technical expertise. Dependent on supplier merchandising support and co-op advertising programs.
- Home Improvement Stores:Mass retail with national footprint and private label programs. Scotts Miracle-Gro and Pennington dominate shelf placement through brand equity and promotional investment.
Relationship depth favors agricultural suppliers; reach expansion favors online sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Portland anchors North American grass seed exports, handling bulk shipments from Oregon's Willamette Valley production cluster to European and Asian markets.
United States
Municipal park budgets in California, Texas, and Arizona drive certified seed procurement for drought-tolerant cultivars. The USDA Plant Variety Protection Office maintains cultivar registration standards that determine commercial eligibility. Oregon's Willamette Valley concentrates perennial ryegrass foundation seed production, exposing supply to weather-dependent bottlenecks.
Germany
Stadium renovation specifications in the Bundesliga market mandate AOSCA-equivalent certified seed lots for natural grass surfaces. The EU F-Gas Regulation prohibits hydrofluorocarbon cooling systems, redirecting capital toward grass breeding programs. Bavaria's agricultural research stations coordinate cultivar trials for wear-recovery-focused perennial ryegrass blends.
Netherlands
Professional turf managers at Eredivisie facilities specify certified seed for pitch renovations under compressed installation timelines. REACH compliance requirements restrict chemical coatings on imported seed, altering formulation strategies. Wageningen University's breeding programs anchor northern European supply of climate-adapted cultivars.
France
Ligue 1 stadium operators revert to natural grass specifications with subsurface aeration upgrades following refrigerant phase-downs. The EU Green Deal influences municipal procurement scoring for sustainable landscaping contracts. The Paris Basin hosts distribution hubs for certified seed lots entering professional channels.
United Kingdom
Premier League pitch renovations drive specification-driven procurement of certified varieties with verified germination rates. The country's national agricultural regulator maintains seed certification standards aligned with OECD schemes. East Anglia's production facilities supply perennial ryegrass blends for sports facility maintenance contracts.
Grass Seed Market Vendor Landscape
Listed leaders compete with private specialists across certification and distribution capabilities. The market structures around three tiers: multinational agrochemical conglomerates with seed divisions, dedicated grass seed breeders with varietal portfolios, and regional distributors with local blending operations. Strategic moves concentrate on direct-to-facility contracting and endophyte-enhanced variety development.
Within the dedicated breeder tier, Pennington Seed Inc. and DLF Pickseed occupy positions defined by R&D network scale and controlled production infrastructure. Scotts Miracle-Gro Company represents the retail-channel archetype through consumer brand recognition and mass-market shelf placement. Seed Research of Oregon exemplifies the regional specialist model with foundation seed production concentrated in the Willamette Valley.
| Leading Market Players |
|---|
| ICL GROUP |
| Pennington Seed Inc. |
| Nutrien Ltd. |
| LebanonTurf |
| Johnston Seed Company |
| Scotts Miracle-Gro Company |
| Barenbrug NZ |
| Seed Research of Oregon |
| DLF Pickseed |
| Others |
Supply Flow & Price Mechanics
Foundation seed production scale in Oregon's Willamette Valley anchors global supply volumes while compressing price floors for commodity-grade lots. This concentration forces smaller breeders toward certification premiums or direct-to-facility contracting to escape margin compression.
Pricing Analysis
Certification level (AOSCA-certified vs. commodity) creates the primary spread, with certified lots commanding placement premiums in professional channels. Pricing stratifies across certified premium, standard commercial, and economy retail tiers. Cost compression in commodity segments is intensifying because nitrogen fertilizer volatility erodes contractor margins. Residential consumers through big-box retail show highest price sensitivity, while municipal sports facility managers prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of foundation seed inventories dominates breeder behavior, buffering against Oregon weather-dependent harvest variability. Geographic supply concentrates in the United States, Denmark, and the Netherlands. Production rests on perennial ryegrass foundation stocks, nitrogen fertilizer inputs, and specialized cleaning equipment. Single-source vulnerability runs through Oregon's Willamette Valley concentration. Distribution runs through agricultural suppliers with technical field support for professional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic turf cooling systems represent the substitution threat that natural grass seed incumbents must navigate as EU F-Gas Regulation phase-downs redirect capital toward natural surfaces.
For Market Incumbents: Shield certified seed premium positioning by accelerating AOSCA field inspection capacity expansion to match compressed stadium renovation timelines. Deepen backward integration into foundation seed production in Denmark and the Netherlands to reduce Oregon weather exposure. Prioritize endophyte-enhanced variety R&D to defend against biological input competitors.
For New Entrants and Emerging Players: Direct-to-sports-facility distribution gaps expose under-served municipal park departments and collegiate athletic departments seeking bypass from traditional distributor markups. Target drought-tolerant cultivar segments in Texas, Arizona, and California where water-use ordinances expand acceptable species lists. Lead with subscription-based seasonal maintenance programs to secure recurring revenue anchoring.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors breeders with captive foundation seed production and established certification pipelines. Long-term viability hinges on climate-adapted cultivar development capacity and direct contracting relationships with professional turf managers. Acquisition targets should demonstrate endophyte integration capabilities. The signal to watch is municipal procurement scoring shifts toward carbon sequestration crediting for permanent turf establishment.
| Strategic Initiative | Industry Significance |
|---|---|
| AOSCA Certification Investment | Unlocks premium channel access for stadium renovation contracts requiring verified seed lots. |
| Endophyte-Enhanced Variety Development | Bundles biological pest resistance with germination guarantees to displace commodity seed. |
| Direct-to-Facility Distribution Buildout | Bypasses traditional agricultural supplier layers to capture margin from municipal park departments. |
| Foundation Seed Production Expansion | Reduces supply concentration risk in Oregon's Willamette Valley through geographic diversification. |
| Carbon Sequestration Program Alignment | Positions certified turf establishment for USDA conservation credit eligibility in public land bids. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA plant variety protection filings, AOSCA certification databases, and EU REACH compliance records. Primary interviews engaged turf managers at collegiate athletic departments, municipal park procurement officers, foundation seed breeders in Oregon and Denmark, and agricultural supplier technical sales representatives. Secondary validation drew from customs trade data, state-level water-use ordinance filings, and stadium renovation specification documents. Bottom-up cultivar shipment estimates triangulate against top-down market value reconstruction.
Segmentation dimensions modeled include product species type, application end-use, packaging format, and distribution channel across the analysis window. CAGRs derive from curve-fitting shipment volumes against specification-driven procurement trends and regulatory compliance timelines. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and municipal drought restriction expansion patterns.
Underlying assumptions cover stable AOSCA certification throughput capacity and continued synthetic turf cooling system prohibitions, with deviation risk concentrated in nitrogen fertilizer price volatility and Oregon harvest weather variability. Revision becomes warranted when EU regulatory enforcement intensity or USDA conservation program funding crosses threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Flax Crop Market
Seeds
Garlic Chive Seeds Market
Seeds
Rapeseed Market
Seeds
China Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Native Grass Seeds Market
Seeds
Europe Seed Market
Seeds
United States Forage Seed Market
Seeds
Spain Forage Seed Market
Seeds
Brazil Forage Seed Market
Seeds
Pasture Seeds Market
Seeds
Commercial Seed Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Russia Seed Market
Seeds
Mexico Seed Market
Seeds
Africa Sorghum Seed Market