
 Australia AI in Fintech Market | 2026-2036
Australia AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Australia AI in Fintech Market Insights
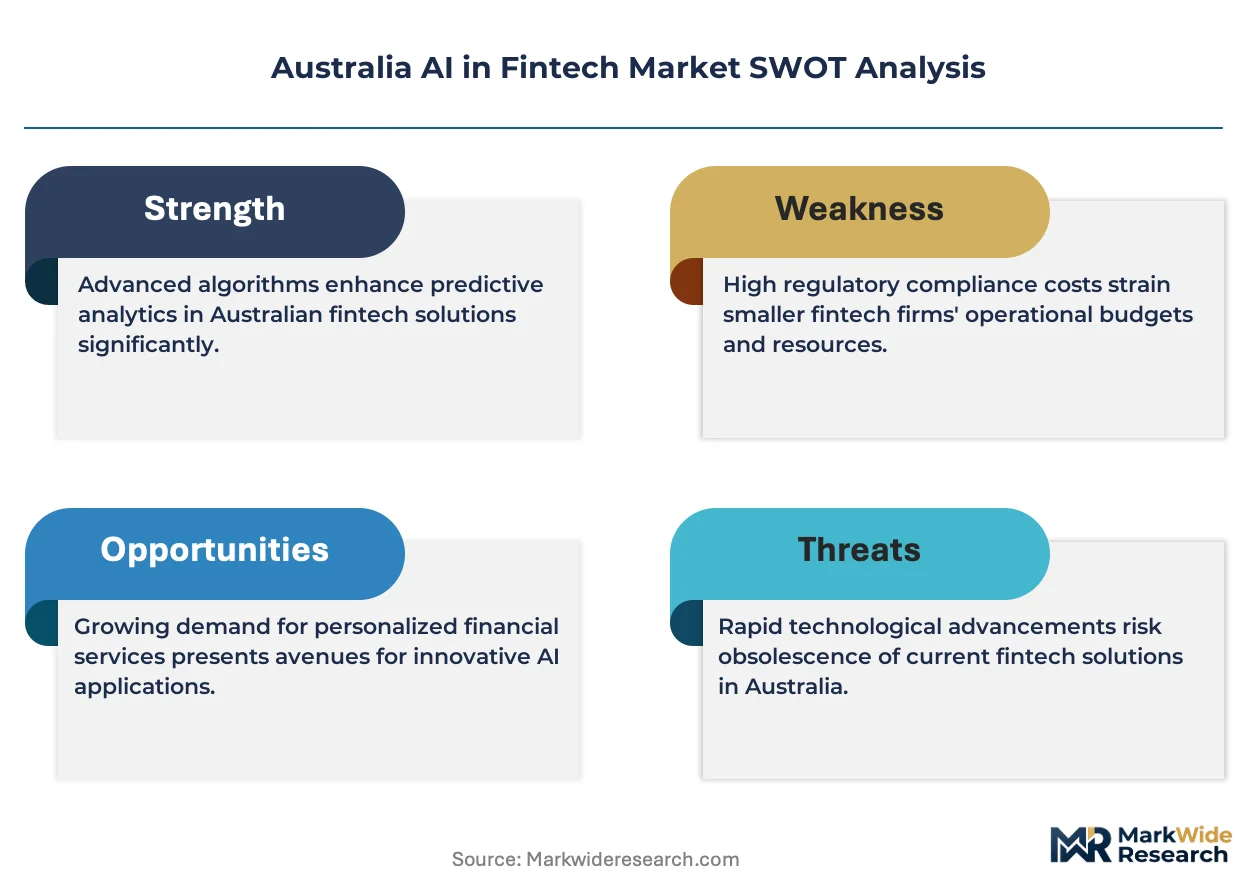
The split between premium AI stacks and commodity automation tools is realigning procurement patterns across Australian financial institutions. Commonwealth Bank of Australia leverages its proprietary machine learning infrastructure to dominate institutional-grade fraud detection. Westpac Banking Corporation anchors its competitive stance through deep integration of natural language processing into customer service channels. Macquarie Group Limited differentiates by specializing in algorithmic trading systems for high-net-worth segments.
AI in fintech encompasses machine learning models, predictive analytics engines, and neural network architectures deployed to automate financial decision-making, risk quantification, and customer interaction at scale. These systems process structured and unstructured data streams to generate real-time credit scores, detect anomalous transactions, and execute algorithmic trades with latency below fifty milliseconds. Fraud Detection applications command the largest current revenue pool due to mandatory breach reporting under the Privacy Act. Robo-Advisors within the Solution Type category represent the fastest-expanding segment as self-managed superannuation funds seek low-cost portfolio optimization. Machine Learning technology occupies the structural center of vendor roadmaps, with Natural Language Processing gaining share in conversational banking interfaces.
The Australian Securities and Investments Commission shapes market access through licensing requirements for algorithmic trading and robo-advisory platforms. The Australian Prudential Regulation Authority imposes capital adequacy and operational risk standards that dictate how banks validate AI-driven credit decisions. The Office of the Australian Information Commissioner enforces Privacy Act obligations that constrain training data usage and model transparency. Stakeholders must monitor how the proposed AI safety obligations under the Department of Industry, Science and Resources will reshape compliance costs for predictive analytics deployments.
Market Dynamics
The Consumer Data Right regime under the ACCC is forcing incumbent banks to open their data vaults to fintech challengers, collapsing traditional information asymmetries that protected legacy profit pools. This regulatory mandate is compressing the competitive moat between established institutions and algorithmic newcomers.
Growth Catalysts
- Open Banking Mandates:The Consumer Data Right compels Australia's four major banks to share customer transaction data via standardized APIs, enabling AI-native lenders to build alternative credit scoring models without proprietary deposit bases.
- ASIC Licensing Framework:The Australian Securities and Investments Commission's streamlined AFSL pathway for robo-advisory platforms reduces regulatory friction for algorithmic wealth management entrants targeting self-managed superannuation funds.
- Cloud Infrastructure Concentration:Sydney and Melbourne host hyperscale data center clusters from AWS, Azure, and Google Cloud, delivering sub-ten-millisecond latency for real-time fraud detection workloads at commodity pricing.
Market Restraints
- Privacy Act Constraints:The Office of the Australian Information Commissioner's enforcement of APP guidelines restricts training data retention periods and mandates explainability for automated credit decisions, increasing model validation costs.
- GPU Supply Concentration:NVIDIA's dominance in AI training accelerators creates procurement vulnerability for Australian fintechs, with lead times extending twelve to eighteen months for A100 and H100 clusters.
- Legacy Core Dependency:Major banks' COBOL-based core banking systems impose middleware complexity that slows neural network deployment into production payment rails.
Strategic Opportunities
- Regulatory Sandbox Expansion:ASIC's Enhanced Regulatory Sandbox permits twelve-month testing of AI-driven lending algorithms without full AFSL compliance, lowering capital barriers for proof-of-concept deployment.
- Natural Language Processing Convergence:Large language model integration with conversational banking interfaces enables hyper-personalized financial coaching for mass-affluent segments previously served only by human advisors.
- Queensland and Western Australia:Mining boom liquidity in Perth and Brisbane generates underserved demand for algorithmic treasury management and commodity-linked robo-advisory products outside Sydney-Melbourne saturation.
Industry Challenges
- Machine Learning Engineering Talent:The domestic pipeline of MLOps specialists with financial services domain expertise remains thin, forcing reliance on expensive contractor markets or offshore development centers.
- Model Risk Management:APRA's CPS 230 operational risk standards require continuous monitoring of AI-driven credit decision drift, mandating expensive second-line-of-defense infrastructure that smaller fintechs struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia AI in Fintech Market |
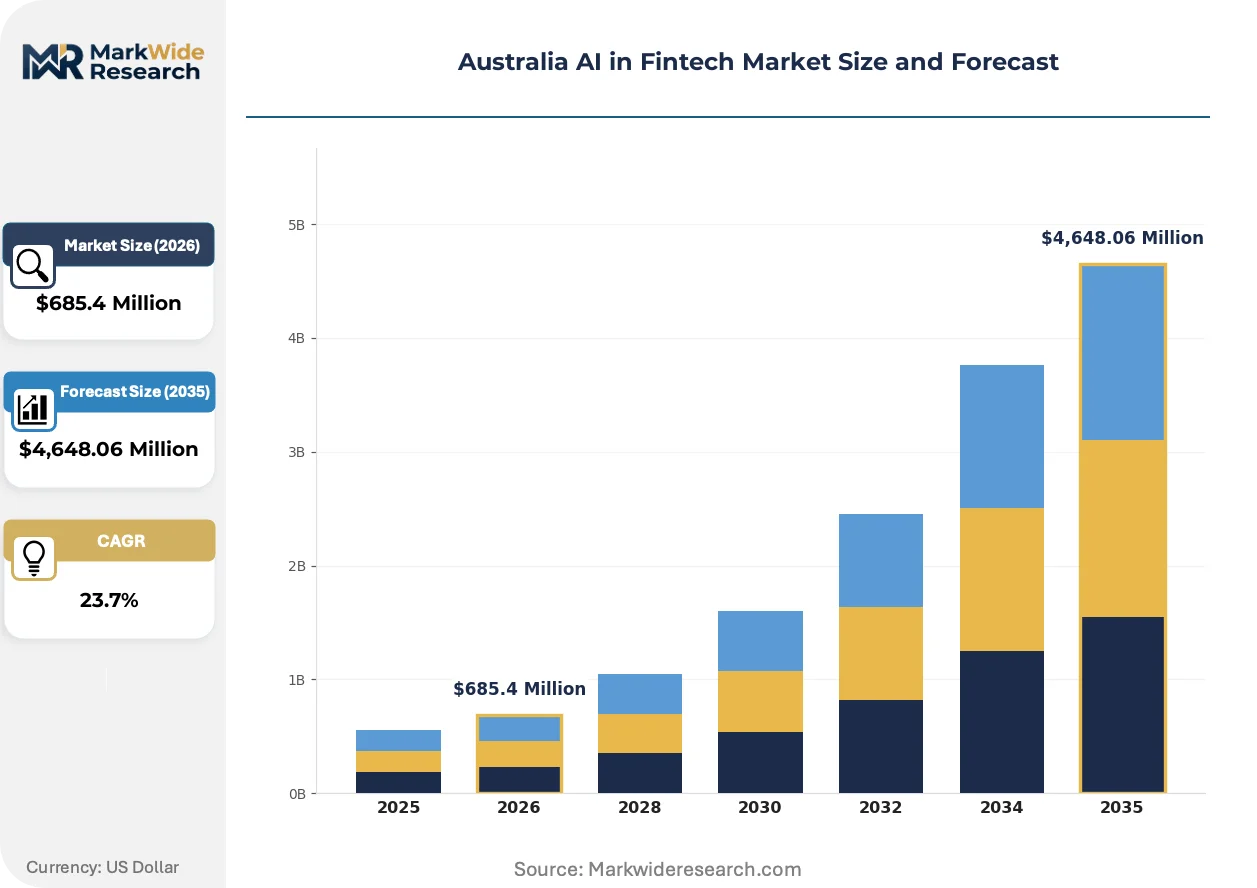
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,648.06 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Assessment, Customer Service, Trading Algorithms Solution Type: Robo-Advisors, Payment Processing, Compliance Automation, Wealth Management Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Neural Networks End User: Banks, Investment Firms, Insurance Companies, Credit Unions |
| Companies Covered | Commonwealth Bank of Australia, Westpac Banking Corporation, National Australia Bank, ANZ Banking Group, Macquarie Group Limited, Airwallex, Zip Co, Tyro Payments, Prospa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia AI in Fintech Market Trends and Innovations
Generative AI architectures are penetrating financial services workflows previously resistant to automation, compressing the gap between experimental pilots and production deployment. Three convergent developments are restructuring how Australian institutions procure, deploy, and monetize algorithmic capabilities.
Transformer-based natural language processing is automating document-intensive compliance workflows including anti-money laundering screening, mortgage origination verification, and insurance claims adjudication. Mid-tier banks and mutuals lacking proprietary NLP infrastructure are adopting API-accessible large language models from cloud providers, collapsing the historical advantage of scale in back-office automation. This technology diffusion is eroding the cost barrier that protected major bank operating efficiency ratios.
The proposed AI safety obligations under the Department of Industry, Science and Resources will mandate algorithmic impact assessments for credit scoring and insurance pricing systems above defined deployment thresholds. Financial institutions are pre-positioning model documentation frameworks and external audit relationships to accelerate compliance certification once regulations finalize. Neobanks with cloud-native architecture and embedded observability tooling are responding faster than legacy institutions constrained by fragmented data lineage systems.
Self-managed superannuation fund trustees are migrating from bundled advisory relationships toward unbundled, algorithm-driven portfolio construction tools accessed through direct mobile interfaces. This behavioral shift is compressing distribution margins for platform providers and redirecting fee pools toward specialized robo-advisory engines with transparent, low-cost indexing strategies. The phenomenon is most visible among trustees aged thirty-five to fifty-five in metropolitan markets where digital financial literacy penetrates deepest.
Australia AI in Fintech Market Segmentation
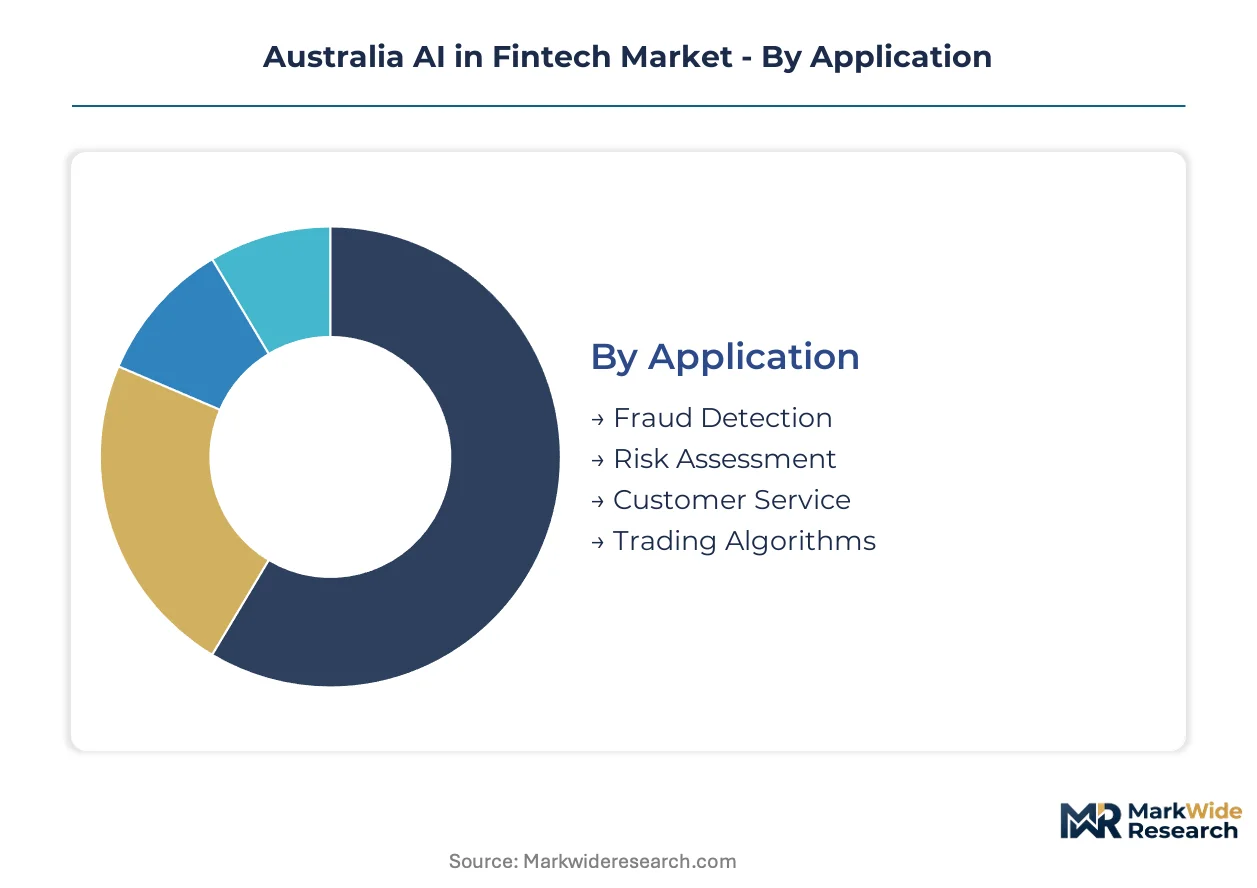
AI deployment patterns across Australian financial institutions diverge sharply by operational function and technical maturity. Procurement cycles for fraud detection systems run on compressed timelines driven by regulatory breach reporting mandates, while robo-advisory platforms follow extended validation paths shaped by ASIC licensing requirements.
Application:
Upgrade cycles for AI applications vary from real-time transactional systems requiring continuous model retraining to episodic compliance workflows refreshed on annual cycles.
- Fraud Detection:Real-time transaction monitoring systems deploy ensemble machine learning models with sub-fifty-millisecond inference latency. Major banks in Sydney and Melbourne dominate procurement volumes as Privacy Act breach reporting obligations accelerate replacement of rule-based detection with neural architectures.
- Risk Assessment:Credit scoring engines process structured bureau data alongside alternative data streams from open banking APIs. Neobanks leverage these systems to compete with incumbent deposit bases, driving fastest adoption among algorithmic lenders without proprietary transaction histories.
- Customer Service:Conversational AI interfaces automate query resolution across digital banking channels.
- Trading Algorithms:High-frequency execution systems specialize in latency-sensitive equity and derivatives markets.
Volume placements concentrate in Fraud Detection; the faster expansion belongs to Risk Assessment.
Solution Type:
Cost tiering separates enterprise-grade platforms with dedicated model governance infrastructure from API-accessible tools priced on transaction volume.
- Robo-Advisors:Algorithmic portfolio construction engines automate asset allocation across exchange-traded funds and direct equities. Self-managed superannuation funds in metropolitan markets drive demand as trustees seek low-cost alternatives to human advisors.
- Payment Processing:Real-time clearing systems deploy AI for anomaly detection and settlement optimization.
- Compliance Automation:Regulatory reporting tools extract structured data from unstructured documents using transformer architectures. Mid-tier mutual banks adopt cloud-hosted solutions to offset documentation burdens from APRA operational risk standards.
- Wealth Management:Holistic financial planning platforms integrate cash flow forecasting with goal-based investing.
Deployment density peaks in Robo-Advisors; Compliance Automation climbs fastest as regulatory documentation burdens intensify.
Technology:
Vendor roadmaps center on machine learning infrastructure while natural language processing gains share in document-intensive workflows.
- Machine Learning:Supervised and unsupervised algorithms form the computational backbone of credit scoring, fraud detection, and customer segmentation systems. Gradient-boosted decision trees and random forests dominate production environments for their interpretability advantages under APRA model risk guidelines.
- Natural Language Processing:Transformer-based architectures automate anti-money laundering screening and mortgage origination verification. Mid-tier institutions lacking proprietary NLP infrastructure adopt API-accessible large language models from hyperscale cloud providers.
- Predictive Analytics:Time-series forecasting engines project cash flows and default probabilities from historical behavioral data.
- Neural Networks:Deep learning architectures power image recognition for identity verification and complex pattern detection in transactional networks.
Installed base concentrates in Machine Learning; Natural Language Processing gains share fastest as document automation expands beyond major banks.
End User:
Customer type determines procurement sophistication, with major banks fielding dedicated MLOps teams while credit unions rely on vendor-managed deployments.
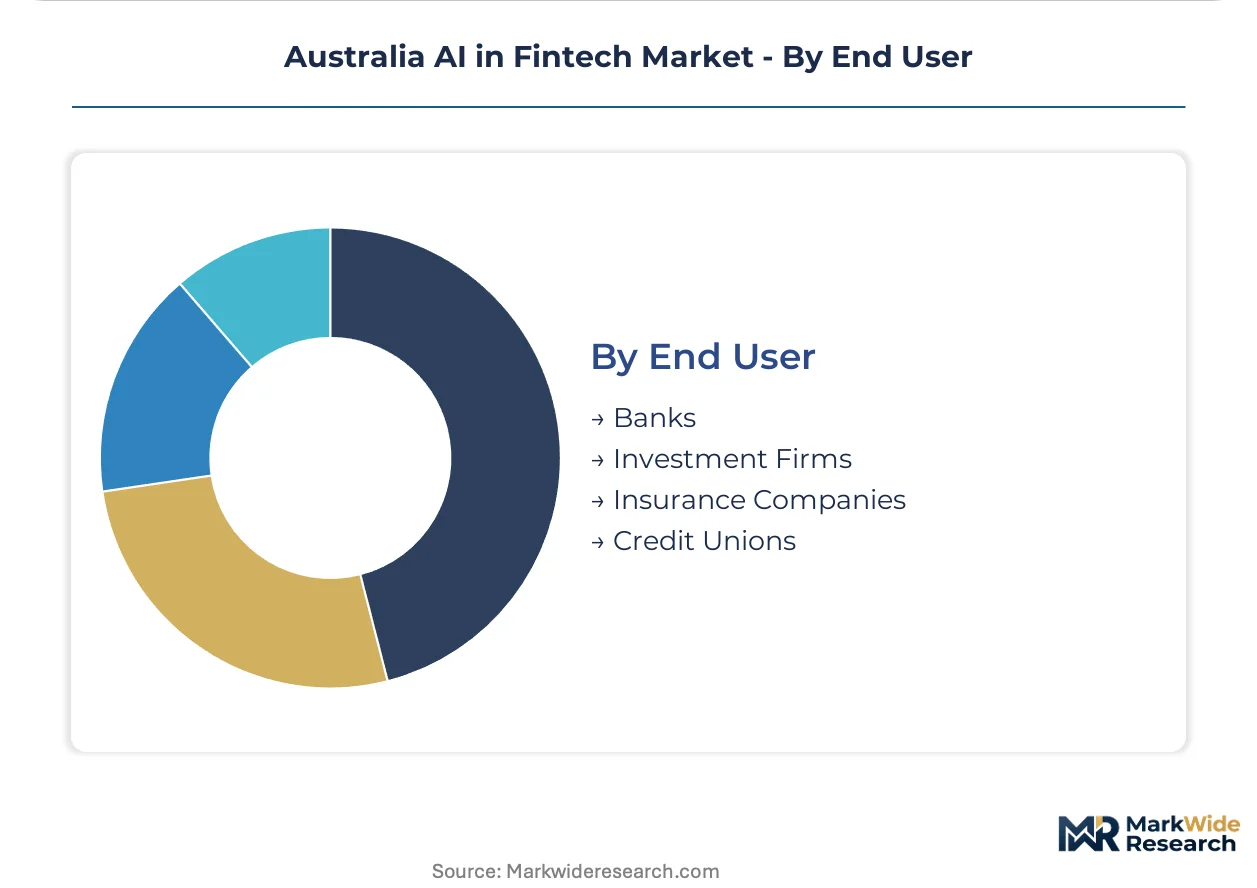
- Banks:Domestic systemically important banks deploy proprietary AI infrastructure across fraud detection, algorithmic trading, and customer service channels. Commonwealth Bank of Australia and Westpac Banking Corporation anchor demand through in-house model development and regulatory sandbox participation.
- Investment Firms:Asset managers and broker-dealers apply AI to execution algorithms and research automation.
- Insurance Companies:General and life insurers deploy predictive models for claims triage, pricing optimization, and underwriting risk selection.
- Credit Unions:Member-owned financial cooperatives adopt cloud-hosted AI tools through consortium procurement arrangements to overcome scale disadvantages in model governance staffing.
Procurement volume clusters with Banks; Credit Unions expand deployment fastest as consortium models democratize access to enterprise-grade capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney anchors Australian fintech AI deployment through its concentration of venture capital, hyperscale cloud infrastructure, and regulatory sandbox operations. Melbourne follows as a secondary hub with strengths in institutional wealth management and algorithmic trading. Geographic expansion beyond these cores is accelerating as mining liquidity and regional banking demand create new deployment zones.
New South Wales
Sydney's fintech corridor drives the majority of AI procurement through Commonwealth Bank of Australia and Westpac Banking Corporation headquarters operations. The Australian Securities and Investments Commission maintains its Enhanced Regulatory Sandbox in this jurisdiction, enabling twelve-month algorithm testing without full licensing. Macquarie Park and Barangaroo host dense clusters of cloud infrastructure from AWS and Azure, delivering sub-ten-millisecond latency for real-time fraud detection.
Victoria
Melbourne's institutional investment sector generates concentrated demand for algorithmic trading and robo-advisory platforms serving self-managed superannuation funds. The Australian Prudential Regulation Authority's CPS 230 operational risk standards shape local model governance practices for credit decision systems. Collins Street and the Docklands precinct house specialist quantitative research teams and natural language processing development centers.
Queensland
Brisbane's mining services economy creates underserved demand for algorithmic treasury management and commodity-linked portfolio tools. The state's financial technology sector benefits from lower operational costs compared to southern capitals while accessing equivalent cloud infrastructure. Fortitude Valley hosts emerging neobank development centers targeting regional banking gaps.
Western Australia
Perth's resource sector liquidity generates specialized demand for AI-driven commodity risk management and high-net-worth advisory automation. The geographic isolation from eastern capital markets has historically limited fintech penetration, creating expansion opportunities for cloud-native challengers. The Perth CBD and Subiaco precincts show accelerating venture investment in mining-adjacent financial technology.
South Australia
Adelaide's smaller institutional base relies on consortium procurement models for AI access, with credit unions adopting shared cloud-hosted tools. The state's defense and technology sectors create niche demand for secure financial automation. Lot Fourteen innovation precinct hosts emerging regtech development focused on compliance automation for smaller financial institutions.
Australia AI in Fintech Market Competitive Landscape
Premium-margin players sit above commodity-margin players across proprietary infrastructure depth, with major banks fielding dedicated MLOps teams while smaller fintechs rent algorithmic capacity through cloud APIs. The market structure reflects a bifurcation between institutional-grade deployments with full regulatory compliance infrastructure and challenger models optimized for speed-to-market. Three archetypes dominate: hyperscale cloud providers supplying foundational models, incumbent banks with captive AI development, and venture-backed neobanks with narrow vertical specialization. Competitive dynamics center on strategic partnerships between legacy institutions and cloud vendors, alongside talent acquisition for machine learning engineering expertise.
Among Australian-headquartered institutions, Commonwealth Bank of Australia and Westpac Banking Corporation occupy positions as archetypal incumbents with proprietary infrastructure, while Airwallex represents the venture-scale challenger model. Commonwealth Bank exemplifies the integrated development approach with in-house fraud detection and customer service automation. Westpac anchors the natural language processing deployment tier through conversational banking interfaces. Airwallex sits within the cross-border payment specialization archetype, leveraging cloud-native architecture to compress deployment timelines.
| Leading Market Players |
|---|
| Commonwealth Bank of Australia |
| Westpac Banking Corporation |
| National Australia Bank |
| ANZ Banking Group |
| Macquarie Group Limited |
| Airwallex |
| Zip Co |
| Tyro Payments |
| Prospa |
| Others |
Pricing and Supply Chain Analysis
GPU cluster procurement costs cascade through three distinct pricing tiers as NVIDIA accelerator lead times stretch from twelve to eighteen months, forcing tier-one banks toward captive infrastructure while mid-tier institutions absorb API-based pricing premiums from hyperscale cloud providers in Sydney and Melbourne.
Pricing Analysis
Outcome-based pricing tied to fraud detection throughput anchors enterprise AI procurement, with Commonwealth Bank and Westpac commanding lowest per-transaction rates through proprietary model development. Price differentiation separates institutions with APRA CPS 230-compliant model governance infrastructure from challengers renting algorithmic capacity. Pricing pressure stems from open banking API commoditization collapsing credit scoring margins. Neobanks exhibit highest price sensitivity; major banks with captive MLOps teams demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for AI training accelerators are emerging as ASIC-licensed fintechs mandate qualification pathways beyond NVIDIA's single-source dominance, though H100 cluster availability remains constrained. Supply concentrates in Taiwan for semiconductor fabrication, USA for chip design, and China for rare earth processing in permanent magnet components. GPU supply vulnerability and cobalt price volatility constitute primary structural risks. Distribution runs through hyperscale cloud provider marketplaces and direct enterprise licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia AI in Fintech Market is becoming a vertical-integration race as institutions pursue backward control over training data pipelines to escape open banking commoditization and API pricing dependency.
For Market Incumbents: Hedge against neobank disintermediation by consolidating proprietary transaction data assets and deepening in-house NLP infrastructure for customer service automation. Acquire specialist MLOps talent pools in Sydney and Melbourne before contractor market rates escalate further under APRA's escalating model validation requirements. For New Entrants and Emerging Players: Capture algorithmic treasury management demand in Perth and Brisbane where mining sector liquidity remains underserved by incumbent digital offerings. Target Queensland and Western Australia credit union consortiums with cloud-native risk assessment tools priced below major bank procurement thresholds. For Investors and Strategic Acquirers: ASIC's Enhanced Regulatory Sandbox expansion beyond twelve-month testing windows is the leading indicator that algorithmic lending infrastructure will consolidate toward vertically integrated platforms. Favor acquisition targets with embedded observability tooling and cloud-native architecture capable of rapid compliance adaptation under pending Department of Industry AI safety obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Model Development | Commonwealth Bank's captive fraud detection infrastructure demonstrates margin protection against API commoditization. |
| Regulatory Sandbox Participation | ASIC's twelve-month testing window accelerates proof-of-concept deployment without full AFSL capital requirements. |
| Cloud Infrastructure Partnership | AWS and Azure sub-ten-millisecond latency commitments in Sydney enable real-time transaction monitoring at scale. |
| MLOps Talent Acquisition | Domestic pipeline scarcity forces reliance on expensive contractor markets or offshore development center establishment. |
| Natural Language Processing Integration | Westpac's conversational banking interfaces compress cost-to-serve ratios in mass-affluent customer segments. |
Research Methodology
Independent corroboration across primary interviews with bank CTOs, neobank founders, ASIC regulatory leads, and hyperscale cloud provider account executives underwrites the qualitative findings, triangulated against secondary validation from APRA operational risk disclosures, ASIC licensing registers, and ACCC Consumer Data Right implementation reports. Bottom-up segmentation modeling and top-down market sizing converge on volume estimates through cross-reference.
Comparable-period anchoring to historical AI deployment trajectories in fraud detection and algorithmic trading established the forecast framework's baseline parameters across the projection horizon. Segmentation dimensions span application function, solution type, technology layer, and end-user archetype with regional adoption patterns. CAGRs derive from regression analysis against venture funding velocity and regulatory sandbox participation rates, incorporating GPU supply constraints and open banking API penetration as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI safety obligation finalization timelines and APRA model risk standard evolution. Deviation in NVIDIA supply chain resolution or Consumer Data Right expansion scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
High Definition HD Voice Market
Information and Communication Technology
Private Branch Exchange Market
Information and Communication Technology
South Korea Digital Transformation Market
Information and Communication Technology
Saudi Arabia Data Center Cooling Market
Information and Communication Technology
North America Augmented Reality Market
Information and Communication Technology
Global Telecom Outsourcing Market
Information and Communication Technology
Intrusion Detection System / Intrusion Prevention System (IDS / IPS) Market
Information and Communication Technology
Industrial Human-Machine Interface Market
Information and Communication Technology
Global Secure Mobile Communications Software Market
Information and Communication Technology
Global Ransomware Protection Market
Information and Communication Technology
Cloud Project Portfolio Management (CPPM) Market
Information and Communication Technology
IoT in Manufacturing Market
Information and Communication Technology
Special Effects (SFX) Software Market
Information and Communication Technology
CLV and Churn Prediction AI Market
Information and Communication Technology
Confidential Computing Market
Information and Communication Technology
Aviation Software Market