
 Autonomic Platform Market | 2026-2036
Autonomic Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomic Platform Market Outlook
Healthcare's surge in patient data volume is realigning procurement priorities across the autonomic platform landscape. IBM Corporation anchors its position through deep R&D intensity in self-healing infrastructure. Microsoft Corporation dominates enterprise hybrid environments with extensive channel control. Amazon Web Services, Inc. competes aggressively on manufacturing scale for cloud-native autonomic workloads.
An autonomic platform constitutes a self-managing computing system that monitors, configures, heals, optimizes, and protects IT resources with minimal human intervention, typically incorporating machine learning inference loops operating below 50-millisecond latency thresholds. These systems automate corrective actions across distributed infrastructure, reducing operational overhead for enterprises running thousands of concurrent workloads. Cloud-based solutions within the solution type dimension currently capture the largest revenue pool, while edge computing deployments under the deployment model are expanding fastest due to latency-sensitive manufacturing and healthcare applications. Large enterprises represent the most mature end-user category, though SMEs are closing the gap through managed services offerings that abstract infrastructure complexity.
The EU AI Act and HIPAA in the United States impose stringent audit and explainability requirements on automated decision systems, directly shaping product roadmaps and procurement checklists for autonomic vendors. ISO 27001 and IEC 62304 standards further govern security and medical device software integrity, creating compliance moats for certified providers. Stakeholders must weigh sovereign data requirements against multi-cloud portability when selecting deployment architectures.
Market Dynamics
Healthcare providers are consolidating patient data infrastructure under self-governing systems that automate compliance with HIPAA and the EU AI Act, forcing vendors to embed audit trails and explainability modules directly into platform architectures.
Growth Catalysts
- EU AI Act mandates:Automated decision systems in healthcare and automotive must maintain full auditability, accelerating procurement of autonomic platforms with built-in governance layers.
- Edge computing latency requirements:Manufacturing floors in Germany demand sub-50-millisecond inference loops for predictive maintenance, pulling hybrid deployment models into production environments.
- Pharmaceutical data orchestration:Clinical trial sponsors require real-time patient data synchronization across multi-site studies, creating pull for self-healing infrastructure that minimizes downtime.
Market Restraints
- Specialized talent scarcity:Machine learning operations engineers with sub-50-millisecond optimization experience command premium compensation, inflating total cost of ownership for enterprise deployments.
- Semiconductor supply concentration:GPU and specialized AI accelerator availability remains concentrated among foundries in Taiwan, creating vulnerability for latency-sensitive inference hardware procurement.
- Legacy system integration friction:Enterprises running decades-old electronic health record systems face prohibitive re-architecture costs when embedding autonomic control loops.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic manufacturing incentives are attracting cloud infrastructure providers to establish regional data centers, creating localized deployment options for autonomic workloads.
- Convergence of digital twin and autonomic control:Industrial asset simulation paired with self-correcting infrastructure enables predictive optimization in automotive and pharmaceutical clusters.
- Managed services channel expansion:SMEs lacking internal platform expertise represent an underpenetrated segment served through subscription-based abstraction of infrastructure complexity.
Industry Challenges
- IEC 62304 certification timelines:Medical device software integrity standards require extensive documentation cycles that delay product launches for healthcare-focused autonomic vendors.
- Multi-cloud portability engineering:Enterprises demand workload mobility across AWS, Azure, and GCP environments, forcing vendors to maintain compatibility matrices that fragment development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomic Platform Market |
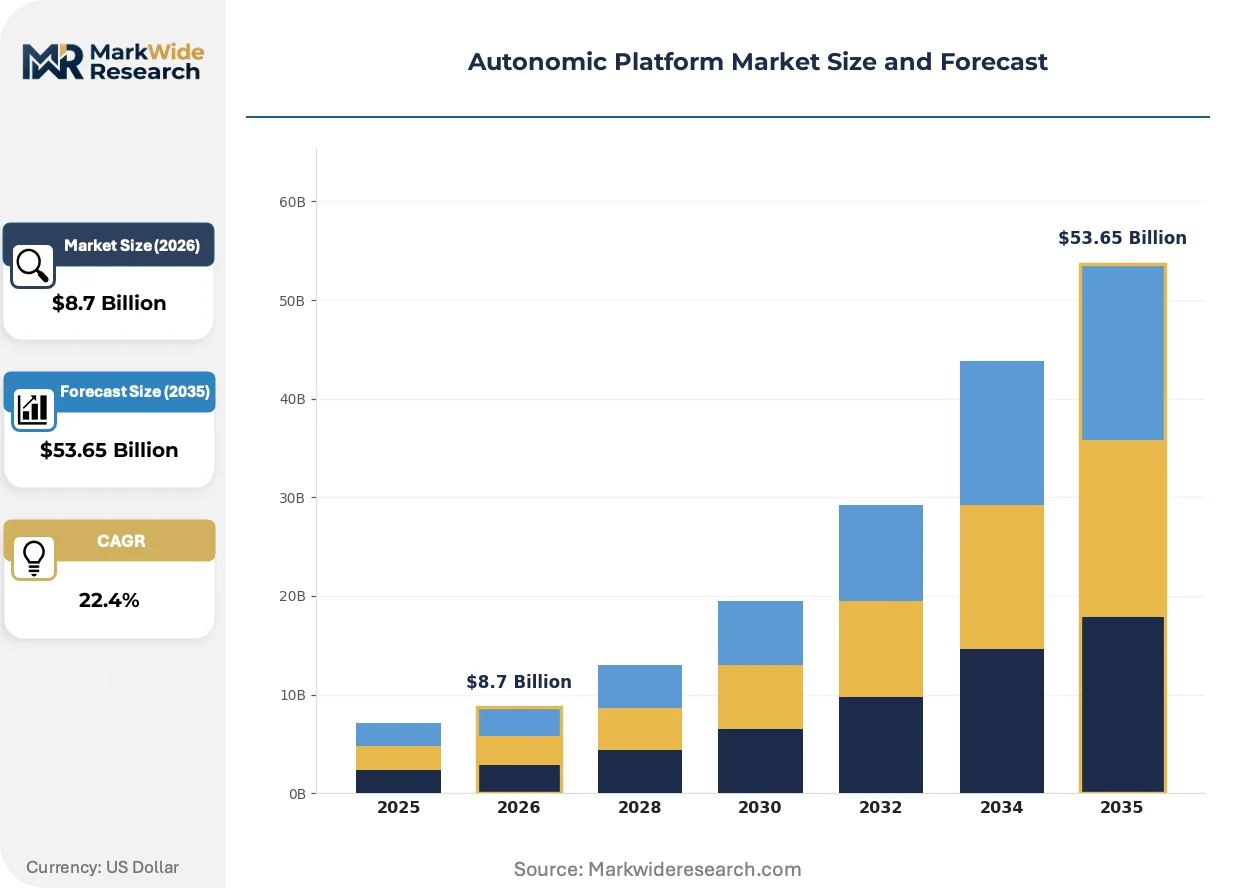
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-based, On-premises, Hybrid, Managed Services Deployment Model: Public Cloud, Private Cloud, Multi-cloud, Edge Computing Industry Vertical: Healthcare, Financial Services, Manufacturing, Retail End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions |
| Companies Covered | Databricks, Inc., IBM Corporation, Amazon Web Services, Inc., Google Cloud Platform, Cloudera, Inc., Microsoft Corporation, Snowflake Inc., Teradata Corporation, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomic Platform Market Strategic Shifts
Self-managing infrastructure is migrating from cloud-centric architectures toward distributed edge deployments that prioritize latency-sensitive inference over centralized resource pooling.
Neuromorphic computing architectures are overtaking conventional GPU-based inference for ultra-low-latency autonomic control loops. These brain-inspired chips process sensory data with event-driven efficiency. Automotive suppliers in Germany are piloting them for real-time manufacturing quality adjustment. The technology is overtaking traditional accelerators in scenarios where millisecond-level response determines operational safety.
The EU AI Act's risk-based classification system imposes mandatory human oversight requirements on high-risk automated decision systems. Healthcare providers must now maintain explainable audit trails for every autonomous action taken on patient data. German hospital networks are responding by restructuring procurement checklists to prioritize vendors with pre-certified governance modules.
Subscription-based consumption models are displacing perpetual licensing for autonomic platform procurement. Large enterprises now prefer operational expenditure structures that align costs with actual workload utilization. This shift is most visible among pharmaceutical sponsors running variable-intensity clinical trials that spike data processing demands unpredictably.
Autonomic Platform Market Segmentation
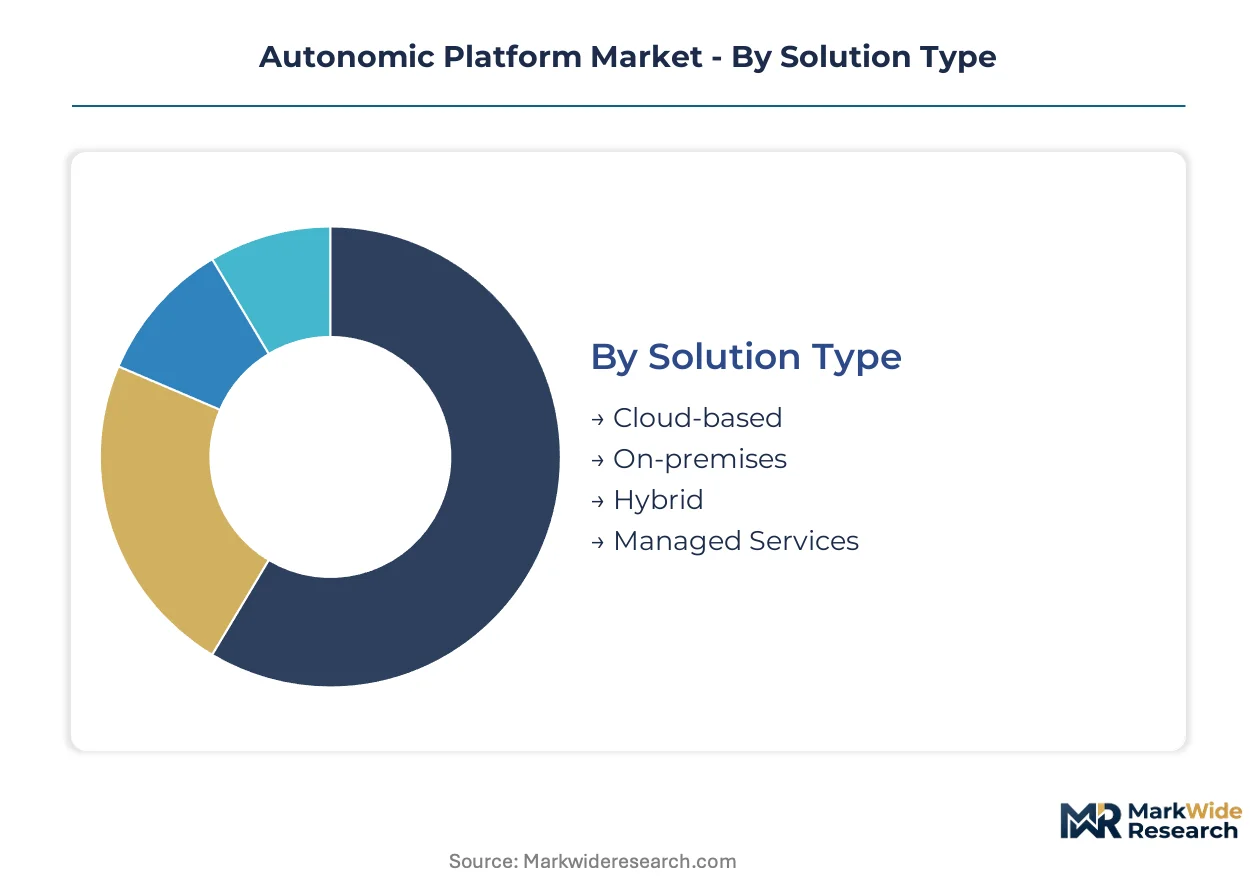
Autonomic platform procurement varies sharply by operational context. Buyers weigh sovereignty requirements against scalability needs, while latency constraints and compliance burdens reshape deployment preferences across verticals.
Solution Type:
Standardization dominates at the infrastructure layer, yet customization intensity rises as control requirements tighten.
- Cloud-based:Fully managed infrastructure with API-driven orchestration layers. Healthcare providers in Germany favor this model for multi-site patient data synchronization, though HIPAA and EU AI Act audit trails must be pre-configured.
- Hybrid:Combines on-premises control planes with burst capacity to public cloud. Automotive clusters in Stuttgart and pharmaceutical sponsors running variable-intensity trials drive demand for this architecture's workload portability.
- On-premises:Self-contained infrastructure for air-gapped environments. Government agencies with classified workloads mandate this deployment mode.
- Managed Services:Vendor-operated platforms with subscription pricing. SMEs lacking MLOps expertise adopt this to abstract infrastructure complexity.
Most installed capacity flows through Cloud-based solutions. Expansion is steepest in Hybrid configurations.
Deployment Model:
Geography shapes deployment preferences, with latency-sensitive applications pulling compute toward endpoints.
- Edge Computing:Distributed inference nodes processing sub-50-millisecond control loops. German manufacturing floors deploy these for real-time quality adjustment on automotive assembly lines.
- Multi-cloud:Workload portability across AWS, Azure, and GCP environments. Financial services firms in Frankfurt require this to avoid vendor lock-in while meeting ECB operational resilience guidelines.
- Private Cloud:Single-tenant infrastructure with dedicated hardware. Healthcare networks handling genomic data select this for patient privacy assurance.
- Public Cloud:Shared infrastructure with consumption-based pricing. Educational institutions with constrained capital budgets default to this model.
Edge Computing is gaining share fastest for latency-critical manufacturing workloads. Private Cloud retains the largest installed base among regulated verticals.
Industry Vertical:
Compliance burden and data sensitivity create tiered adoption patterns across sectors.
- Healthcare:Patient data orchestration with embedded HIPAA and EU AI Act governance. Hospital networks in Germany and the United States consolidate infrastructure under self-healing platforms.
- Manufacturing:Predictive maintenance and digital twin integration. Automotive suppliers in Bavaria pair neuromorphic inference with autonomic control for quality optimization.
- Financial Services:Real-time fraud detection and algorithmic trading infrastructure. Frankfurt-based institutions drive demand for explainable audit trails under ECB supervision.
- Retail:Supply chain optimization and dynamic pricing engines. Demand concentrates in omnichannel inventory synchronization use cases.
Healthcare accounts for the dominant share of current procurement. Manufacturing shows the steepest expansion trajectory as Industry 4.0 investments accelerate.
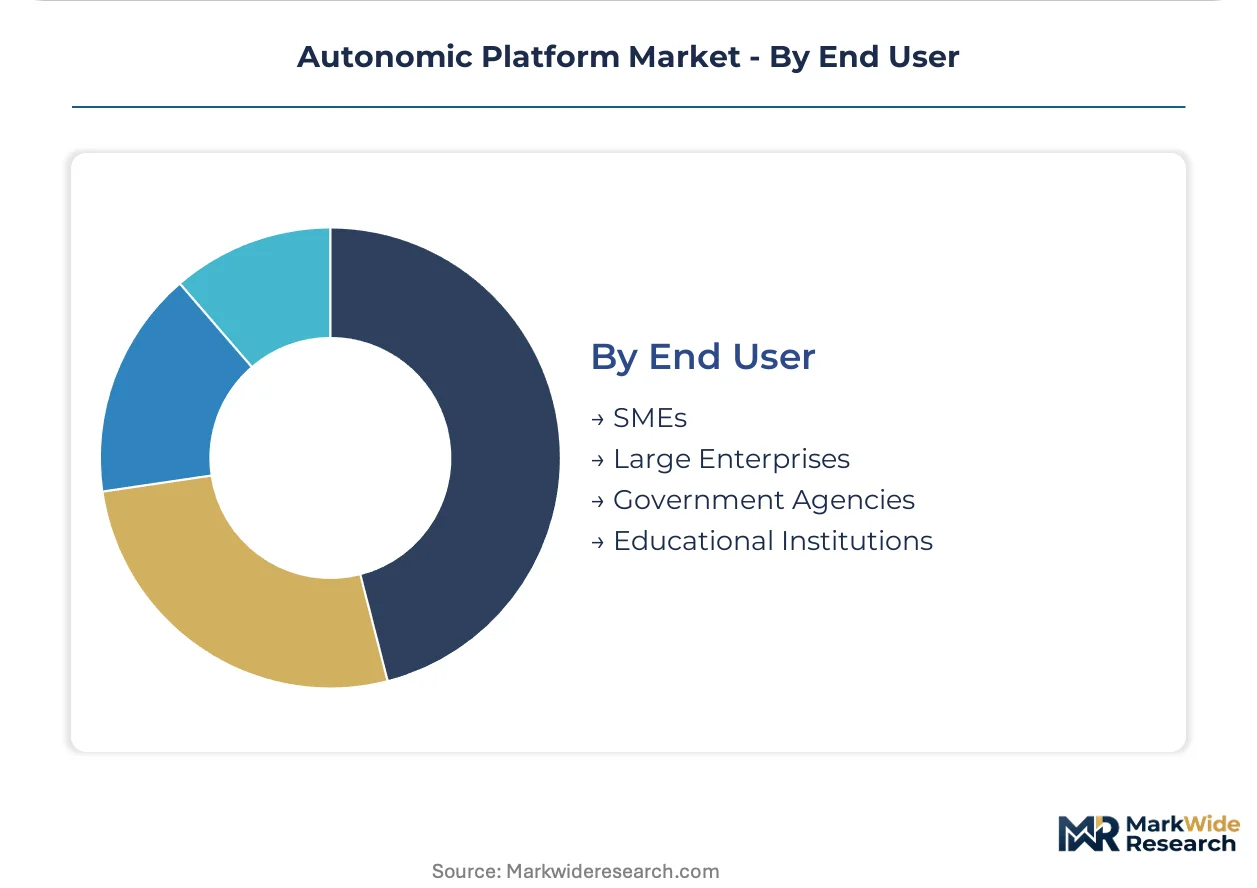
End User:
Internal capability gaps determine whether buyers seek full platforms or abstracted services.
- Large Enterprises:Self-operated platforms with dedicated platform engineering teams. Pharmaceutical sponsors running global clinical trials require this scale for multi-site data harmonization.
- SMEs:Limited internal expertise drives preference for managed consumption models. Subscription pricing aligns costs with actual workload utilization.
- Government Agencies:Sovereign data requirements and classified processing needs. Procurement emphasizes pre-certified compliance with national security standards.
- Educational Institutions:Research computing and administrative automation. Budget constraints favor public cloud deployment with educational pricing tiers.
Large Enterprises command the majority of installed capacity. SMEs are expanding most quickly as managed services lower adoption barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping deployment patterns as vendors migrate infrastructure toward jurisdictions with clearer AI governance frameworks and lower compliance friction. Germany and the United States currently absorb the majority of enterprise procurement, while India's manufacturing incentives and the UAE's data sovereignty policies are emerging as alternative anchors for regional capacity.
United States
Healthcare networks in Massachusetts and California are consolidating patient data infrastructure under self-governing platforms that automate HIPAA audit trails. FDA guidance on software as a medical device is accelerating certification timelines for vendors serving clinical trial sponsors. The Boston-Cambridge biotech corridor represents the densest concentration of pharmaceutical procurement for multi-site data orchestration.
Germany
Automotive suppliers in Stuttgart and pharmaceutical clusters in Munich are driving hybrid deployment models for sub-50-millisecond manufacturing control loops. EU AI Act risk classifications mandate explainability modules that German hospital networks now require in procurement checklists. Bavaria's Industry 4.0 investments pair neuromorphic inference with autonomic quality adjustment on assembly lines.
India
PLI scheme incentives for electronics manufacturing are attracting cloud infrastructure providers to establish regional data centers in Karnataka and Telangana. Domestic enterprises lacking MLOps expertise are adopting managed services models that abstract infrastructure complexity. Mumbai's financial services firms require multi-cloud portability to meet RBI operational resilience guidelines.
United Kingdom
London-based financial institutions demand explainable audit trails for algorithmic trading infrastructure under ECB supervision. NHS trusts are restructuring procurement to prioritize vendors with pre-certified governance modules aligned with GDPR and emerging AI accountability frameworks. The Cambridge-Oxford tech corridor is piloting edge computing deployments for latency-sensitive research computing.
United Arab Emirates
Dubai's smart city initiatives and Abu Dhabi's sovereign wealth deployment are creating localized demand for air-gapped autonomic infrastructure. MOHAP medical device regulations are shaping vendor certification requirements for healthcare applications. The UAE's data residency policies are pulling private cloud deployments away from multi-cloud architectures toward single-tenant regional facilities.
Autonomic Platform Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated control at the infrastructure layer and fragmentation rising toward application-specific customization. Three archetypes dominate: hyperscale cloud providers with manufacturing scale advantages, enterprise software incumbents with deep channel relationships, and vertical specialists with certified compliance moats. Competitive dynamics center on strategic partnerships for edge deployment capacity and portfolio diversification into managed services abstraction.
Among hyperscale infrastructure providers, Amazon Web Services, Inc. and Microsoft Corporation exemplify the manufacturing-scale archetype for cloud-native autonomic workloads. IBM Corporation occupies a position within the enterprise incumbent tier, anchoring R&D-intensive specialization in self-healing infrastructure. These three entities collectively represent the competitive poles around which procurement patterns in healthcare and automotive verticals are reorganizing.
| Leading Market Players |
|---|
| Databricks, Inc. |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Google Cloud Platform |
| Cloudera, Inc. |
| Microsoft Corporation |
| Snowflake Inc. |
| Teradata Corporation |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
Neuromorphic chip fabrication migration from conventional GPU architectures is simultaneously compressing inference hardware costs and concentrating specialized foundry relationships among automotive suppliers in Germany and Taiwan. This transition reshapes procurement economics for sub-50-millisecond control loops while locking buyers into qualified supplier networks.
Pricing Analysis
Direct-to-OEM channel discounts dominate enterprise procurement, with pharmaceutical sponsors and automotive Tier 1s extracting volume-based concessions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU AI Act pre-certified modules commanding sustained premiums. Cost compression in edge computing hardware is intensifying because neuromorphic foundries achieve yield improvements. SMEs exhibit highest price sensitivity, deferring adoption until managed services abstract infrastructure complexity.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and US hospital networks require qualification of secondary neuromorphic foundries and GPU suppliers. Supply concentration rests on Taiwan, South Korea, and the United States for specialized AI accelerators. Raw material dependencies span silicon wafers, advanced packaging substrates, and rare earth elements for magnetic components. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomic platform market compounds steadily as regulatory compliance mandates embed self-governing infrastructure into procurement checklists across healthcare and automotive verticals. This structural demand driver insulates growth from cyclical IT spending volatility.
For Market Incumbents: Anticipate neuromorphic computing disruption by securing early foundry allocation agreements and pre-certifying governance modules for EU AI Act high-risk classifications. Vertical integration into edge hardware design preserves margin structure against commoditizing cloud inference. Channel control through managed services partnerships defends position against hyperscale encroachment in SME segments. For New Entrants and Emerging Players: Cloud-native deployment platforms offer the most penetrable entry vector, with Indian pharmaceutical sponsors and German mid-tier automotive suppliers underserved by incumbent complexity. Target managed services abstraction for MLOps-deficient enterprises lacking platform engineering expertise. Partner with regional data center operators in Karnataka and Telangana to localize latency-sensitive workloads under India's PLI scheme incentives. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical specialists with IEC 62304 certification moats and pre-configured HIPAA audit trail modules. Long-term viability hinges on regulatory compliance automation becoming embedded infrastructure rather than discretionary software spend. Watch for EU AI Act enforcement actions against non-compliant automated decision systems as the inflection signal for certified vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Neuromorphic Hardware Partnership | Secures sub-50-millisecond inference capacity for German automotive quality control applications. |
| EU AI Act Pre-Certification | Accelerates procurement cycles with hospital networks restructuring vendor checklists around explainability modules. |
| Managed Services Channel Expansion | Captures SME demand through subscription pricing that aligns costs with variable clinical trial intensity. |
| India Data Center Localization | Positions platforms for PLI scheme incentives while addressing RBI operational resilience guidelines in Mumbai. |
| Digital Twin Integration | Enables predictive optimization in Bavarian pharmaceutical clusters through self-correcting infrastructure convergence. |
Study Parameters
Direct dialogue with platform engineering directors, healthcare CIOs, automotive IT procurement leads, and MLOps specialists grounded the qualitative foundation. Primary insights combined with secondary validation from SEC filings of hyperscale infrastructure providers, FDA software as medical device guidance documents, EU AI Act regulatory texts, and German BDI Industry 4.0 investment trackers. Bottom-up deployment model sizing and top-down vertical spending analysis achieved triangulation.
Segment-level value outputs emerged from modeling solution type, deployment architecture, industry vertical, and end-user scale dimensions across the projection horizon. CAGRs derived from regression analysis against historical IT infrastructure automation spending and regulatory compliance investment patterns. Neuromorphic chip production roadmaps and EU AI Act implementation timelines served as industry-specific forecast inputs.
Semiconductor foundry yield shortfalls, EU AI Act enforcement variance, and healthcare capital budget freezes are the dominant revision risks. Deviation in neuromorphic chip commercialization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Federated Learning Market