
 VM Service Market | 2026-2036
VM Service Market Size, Share, and Industry Trends Forecast 2026-2036
VM Service Market Insights
GDPR is recalibrating data residency requirements for European VM deployments, raising infrastructure costs for providers without regional data centers. Microsoft Corporation leverages its Azure Stack portfolio to sustain hybrid cloud dominance across regulated industries. IBM Corporation anchors its position through mainframe-integrated virtualization services for financial sector clients. Citrix Systems, Inc. specializes in application delivery controllers that extend VM workloads to remote endpoints.
VM services provision virtualized compute, storage, and networking resources through software-defined abstraction layers that decouple physical hardware from operating environments, typically supporting x86 and ARM architectures with live migration capabilities between host nodes. The primary commercial purpose centers on improving server utilization rates while enabling elastic capacity scaling for variable workloads. Infrastructure as a Service dominates current revenue pools due to raw compute commoditization, while Platform as a Service captures expanding margin as developers demand pre-configured runtime environments. Hybrid Cloud deployment models attract the fastest enterprise migration activity as organizations balance latency-sensitive on-premises workloads with burst capacity from public infrastructure.
FDA guidelines for medical device software validation shape VM configurations in healthcare deployments, while HIPAA mandates encrypted isolation between tenant environments handling protected health information. NIST cybersecurity frameworks influence baseline hardening requirements for government cloud procurements. Stakeholders must evaluate sovereign cloud certifications before committing to cross-border VM infrastructure partnerships.
Market Dynamics
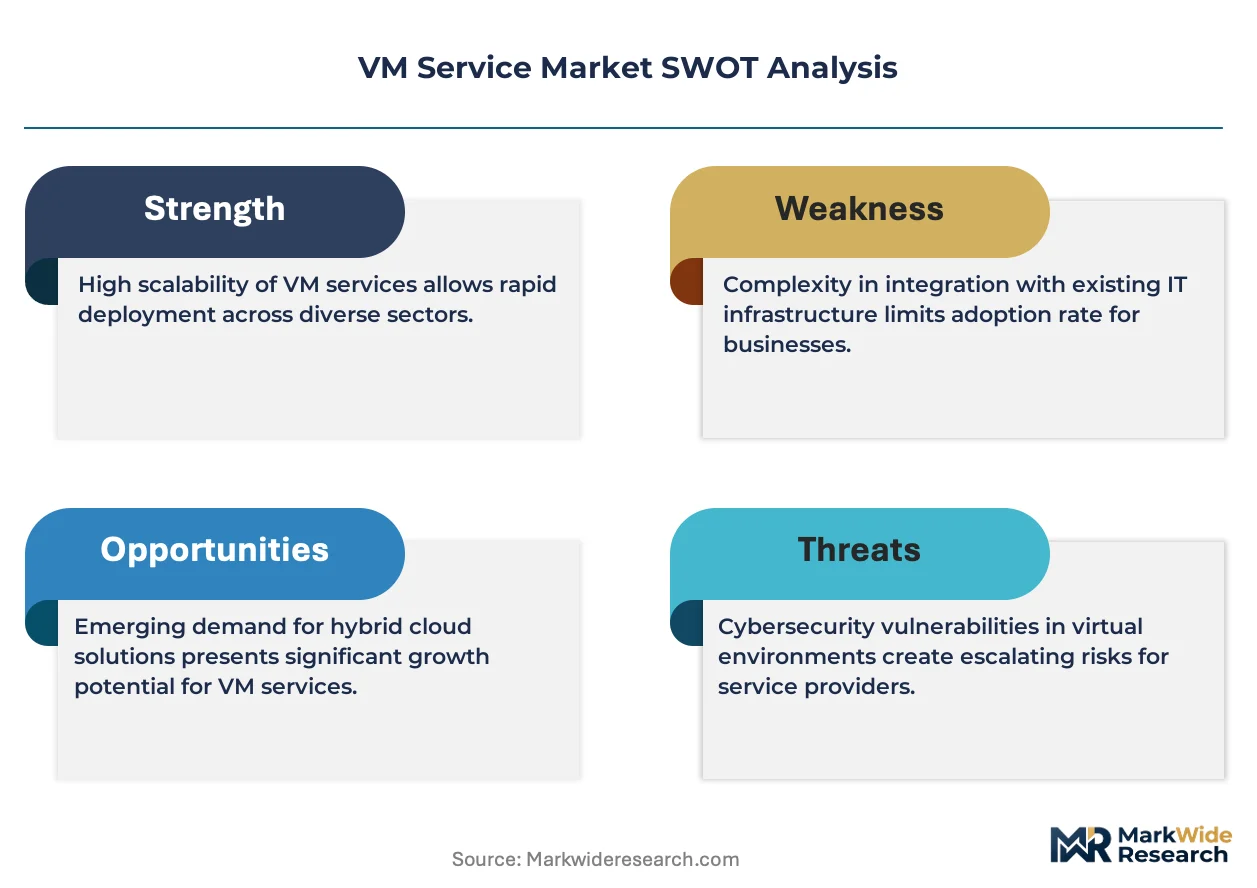
The VM Service Market is experiencing structural pressure from the EU AI Act's recalibration of compliance requirements for automated workload orchestration, forcing providers to re-architect multi-tenant isolation and audit trails.
Growth Catalysts
- Financial Services Expansion:Banks and insurers are deploying secure multi-tenant VM environments to consolidate legacy infrastructure while maintaining regulatory separation between client data pools.
- GDPR Data Residency Mandates:European enterprises now require in-region VM infrastructure, accelerating provider investments in Frankfurt, Amsterdam, and Dublin data center clusters.
- Automotive Private Cloud Clusters:German manufacturers operate large-scale VM deployments for simulation workloads, creating concentrated demand for high-availability virtualization stacks.
Market Restraints
- Energy Input Volatility:VM infrastructure power consumption ties directly to regional electricity pricing, with European providers facing compressed margins from grid cost spikes.
- Hypervisor Supply Concentration:Three vendors control dominant positions in enterprise-grade virtualization layers, creating vendor lock-in risk for large-scale deployments.
- Cross-Border Certification Friction:Sovereign cloud requirements in France, Germany, and Italy force redundant compliance audits, extending sales cycles by 4-8 months.
Strategic Opportunities
- Edge VM Orchestration:Manufacturing facilities in Poland and Czechia require localized VM processing for industrial IoT analytics, creating greenfield deployment opportunities outside saturated Western markets.
- Healthcare Workload Isolation:HIPAA-mandated encrypted tenant separation is driving specialized VM configurations for hospital systems and clinical research organizations.
- Hybrid Cloud Convergence:Azure Stack and equivalent on-premises VM platforms are converging with public cloud bursting, enabling workload portability across latency-sensitive and elastic capacity scenarios.
Industry Challenges
- Legacy Mainframe Integration:Financial sector VM migrations require complex API bridging to COBOL-based core banking systems, extending implementation timelines and requiring scarce specialized talent.
- Live Migration Certification:Healthcare and government VM deployments face extended validation cycles for workload mobility during hardware maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VM Service Market |
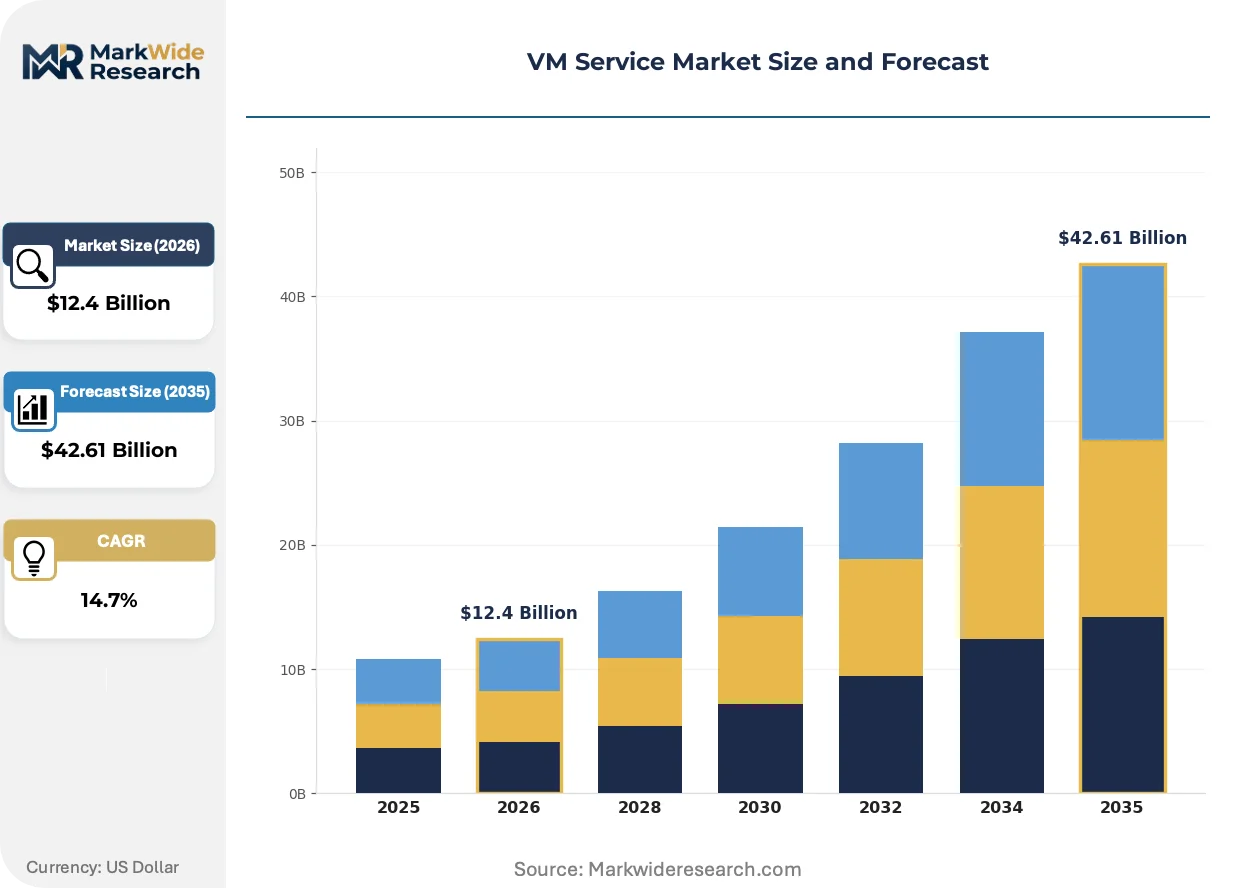
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.61 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions Operating System: Linux, Windows, Unix, MacOS |
| Companies Covered | VMware, Inc., Microsoft Corporation, Citrix Systems, Inc., Oracle Corporation, Amazon.com, Inc., IBM Corporation, Hewlett Packard Enterprise Company, Red Hat, Inc., Nutanix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VM Service Market Trends and Innovations
Container-native virtualization is dissolving traditional boundaries between VM and container workloads, forcing infrastructure providers to unify management planes or cede developer mindshare to Kubernetes-centric alternatives.
Confidential computing using hardware-based trusted execution environments is converging with VM provisioning, enabling encrypted processing of sensitive workloads even from cloud administrators. Financial services firms in Switzerland and Luxembourg are piloting these configurations for wealth management analytics. The technology is converging with regulated multi-tenant requirements, compressing the acceptable security perimeter for cross-border data processing.
The EU AI Act's risk-based classification system is mandating algorithmic audit trails for automated VM orchestration decisions. Providers must now log and explain workload placement logic, particularly for high-risk AI training environments. German automotive manufacturers are requiring these capabilities in procurement specifications ahead of formal enforcement timelines.
Consumption-based VM licensing is displacing perpetual socket-based models across enterprise accounts. Channel partners in the Nordics and Benelux report accelerated transitions to metered billing tied to actual vCPU-hour utilization. Healthcare providers with seasonal research computing peaks represent the most visible adopters of this flexibility.
VM Service Market Segmentation
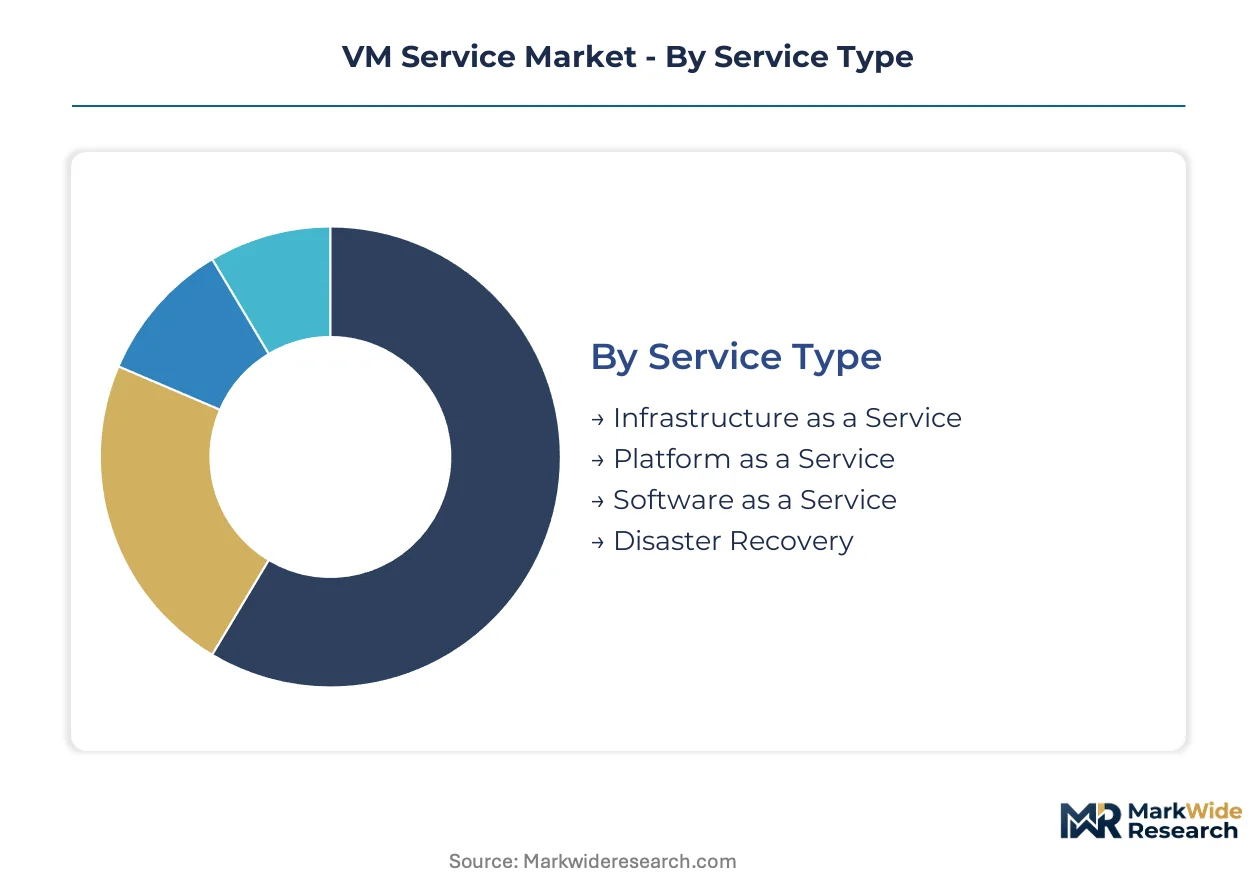
VM service procurement decisions hinge on workload sensitivity, compliance posture, and elasticity requirements. Segmentation reveals where provider investments concentrate and which deployment patterns command premium pricing.
Service Type:
Enterprise buyers select service tiers based on control depth versus operational burden trade-offs.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered through software-defined abstraction layers with full tenant control over the guest operating environment. German automotive manufacturers operate large-scale private IaaS clusters for simulation workloads, driving demand for bare-metal virtualization performance.
- Platform as a Service:Pre-configured runtime environments with managed middleware, database services, and development toolchains that abstract infrastructure management entirely. Financial services firms in Luxembourg and Switzerland are piloting PaaS configurations with confidential computing for wealth management analytics, compressing security perimeters for cross-border data processing.
- Software as a Service:Fully managed application delivery where virtualization operates entirely beneath the service layer, invisible to end users.
- Disaster Recovery:Replication and failover orchestration services maintaining VM state synchronization across geographically separated infrastructure.
Infrastructure as a Service leads on scale; Platform as a Service leads on momentum.
Deployment Model:
Latency sensitivity and data sovereignty requirements determine cloud topology selection.
- Hybrid Cloud:Unified management plane spanning on-premises VM infrastructure with burst capacity into public cloud, enabling workload portability across latency-sensitive and elastic capacity scenarios. Azure Stack and equivalent on-premises platforms are converging with public cloud bursting across regulated industries.
- Private Cloud:Dedicated virtualization infrastructure with single-tenant isolation, typically deployed in enterprise-owned or colocation facilities. German automotive manufacturers require these configurations for proprietary simulation data, creating concentrated demand for high-availability virtualization stacks.
- Public Cloud:Shared multi-tenant infrastructure with standardized VM instance types and consumption-based metering.
- Community Cloud:Collaborative infrastructure shared among organizations with common compliance requirements or sectoral affiliation.
Hybrid Cloud commands the steepest expansion trajectory; Private Cloud retains the highest deal values.
End User:
Organizational scale dictates procurement complexity and customization depth.
- Large Enterprises:Complex multi-workload environments requiring dedicated account architecture and custom SLA negotiation. Banks and insurers are deploying secure multi-tenant VM environments to consolidate legacy infrastructure while maintaining regulatory separation between client data pools.
- SMEs:Standardized VM configurations with self-service provisioning and predictable monthly billing.
- Government:Sovereign cloud certifications with NIST cybersecurity framework alignment for baseline hardening requirements.
- Educational Institutions:Seasonal research computing peaks with flexible consumption-based licensing transitions.
Large Enterprises dominate current revenue; Government verticals are gaining share fastest through sovereign cloud mandates.
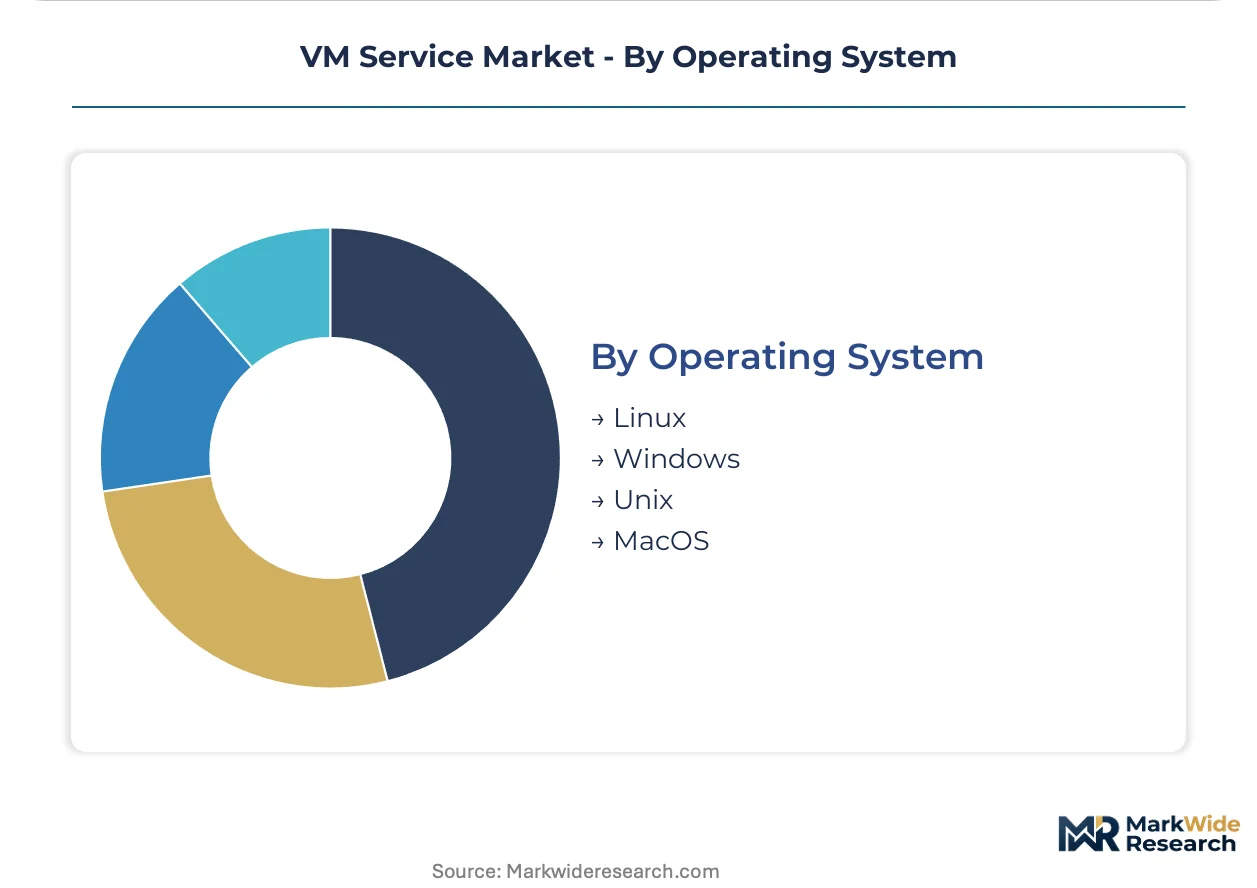
Operating System:
Guest environment selection reflects application legacy and licensing economics.
- Linux:Open-source kernel distributions dominating cloud-native and container-adjacent workloads with minimal licensing friction.
- Windows:Microsoft-proprietary environments with deep integration into enterprise identity and productivity stacks.
- Unix:Legacy RISC-based systems persisting in financial sector core banking infrastructure requiring complex API bridging to modern VM orchestration.
- MacOS:Apple-proprietary environment with limited server virtualization deployment, concentrated in creative industry and iOS development pipeline tooling.
Linux leads on deployment volume; Windows maintains the strongest attach rate to managed services revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virtualization infrastructure traces its commercial roots to early enterprise data center consolidation efforts in the United States, where VMware pioneered x86 server abstraction in the late 1990s. The technology subsequently diffused through European financial centers and German automotive engineering clusters before establishing production-grade deployments across Asia-Pacific cloud hubs.
United States
Financial services firms in New York and Chicago drive demand for secure multi-tenant VM environments that consolidate legacy infrastructure while maintaining regulatory separation. HIPAA mandates encrypted isolation between tenant environments handling protected health information, shaping configurations in healthcare deployments. The Dallas-Fort Worth metro anchors substantial private cloud VM clusters for energy sector simulation workloads.
Germany
Automotive manufacturers operate large-scale VM deployments for proprietary simulation data, creating concentrated demand for high-availability virtualization stacks. The EU AI Act recalibrates compliance requirements for automated workload orchestration, forcing providers to re-architect multi-tenant isolation and audit trails. Stuttgart and Munich host engineering clusters where VM infrastructure supports CAD-intensive workloads and autonomous vehicle testing pipelines.
United Kingdom
London-based financial institutions deploy hybrid cloud VM platforms to balance latency-sensitive trading infrastructure with elastic burst capacity. The Financial Conduct Authority's operational resilience requirements influence baseline hardening specifications for critical VM workloads. The Thames Valley corridor concentrates managed service providers specializing in sovereign cloud certifications for government and defense clients.
France
Healthcare providers with seasonal research computing peaks represent visible adopters of consumption-based VM licensing transitions. ANSM and CNIL guidelines shape encrypted processing requirements for clinical data environments. The Paris-Saclay research cluster drives specialized VM configurations for genomics and pharmaceutical simulation workloads requiring confidential computing capabilities.
Japan
Manufacturing facilities require localized VM processing for industrial IoT analytics, creating greenfield deployment opportunities in precision engineering hubs. METI's data free flow with trust initiatives influence cross-border VM infrastructure partnerships. The Nagoya-Toyota industrial corridor operates private cloud VM clusters for supply chain optimization and predictive maintenance workloads.
VM Service Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with deep enterprise relationships and established virtualization stacks. Three vendors control dominant positions in enterprise-grade hypervisor layers, creating structural barriers for new entrants while channel partners accelerate transitions to metered billing models. Strategic archetypes include cloud-native platform providers extending on-premises VM orchestration, legacy infrastructure vendors integrating mainframe-integrated virtualization services, and specialists in application delivery controllers. M&A activity concentrates on container-native virtualization capabilities, while strategic partnerships focus on confidential computing hardware integration.
Among diversified technology conglomerates, Microsoft Corporation and IBM Corporation exemplify archetypes spanning hybrid cloud and mainframe-integrated virtualization respectively. VMware, Inc. occupies a foundational position in enterprise hypervisor infrastructure. These three entities anchor the competitive terrain through distinct vectors: Azure Stack convergence with public cloud bursting, mainframe API bridging for financial sector migrations, and software-defined abstraction layers decoupling physical hardware from operating environments.
| Leading Market Players |
|---|
| VMware, Inc. |
| Microsoft Corporation |
| Citrix Systems, Inc. |
| Oracle Corporation |
| Amazon.com, Inc. |
| IBM Corporation |
| Hewlett Packard Enterprise Company |
| Red Hat, Inc. |
| Nutanix, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive data center infrastructure in Germany and the Netherlands anchors supply positioning for European VM providers while simultaneously constraining pricing flexibility through fixed asset depreciation schedules. This vertical integration pattern concentrates cost exposure in electricity-intensive compute regions where grid pricing volatility directly compresses service margins.
Pricing Analysis
Bundled managed services with consumption-based metering dominate enterprise procurement while unbundled raw compute instances compete on spot-market transparency. Three-tier pricing structure across premium confidential computing, standard multi-tenant, and economy burstable tiers differentiates by isolation guarantees and audit trail depth. Pricing pressure stems from hyperscaler scale economics in public cloud VM tiers, compressing margins for regional providers without captive renewable energy supply. Healthcare providers with seasonal research peaks exhibit highest price sensitivity through demand elasticity, while financial services firms in Switzerland and Luxembourg accept premium positioning for regulatory-grade tenant separation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive manufacturer demand in Stuttgart and Munich engineering clusters. Hardware supply concentrates in Taiwan for server-grade processors, the United States for virtualization software stacks, and China for commodity storage components. Raw material dependencies span silicon wafers, DDR memory modules, and solid-state storage controllers. Single-source vulnerability in enterprise hypervisor licensing creates procurement concentration risk for large-scale private cloud deployments. Distribution runs through systems integrators and managed service providers across the Nordics and Benelux regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VM service expansion functions as a geographic-arbitrage play where Frankfurt data center operating costs undercut London by approximately one-third while satisfying equivalent GDPR compliance requirements.
For Market Incumbents: Anchor market position through confidential computing certification investments that preempt EU AI Act audit trail mandates before formal enforcement timelines. Defend against container-native virtualization substitution by unifying VM and Kubernetes management planes or ceding developer workloads entirely. Prioritize sovereign cloud accreditation in France, Germany, and Italy to compress 4-8 month sales cycle extensions from redundant compliance audits. For New Entrants and Emerging Players: Launch via edge VM orchestration partnerships with manufacturing facilities in Poland and Czechia industrial IoT corridors where localized processing demand exceeds incumbent coverage. Target healthcare workload isolation configurations for hospital systems and clinical research organizations with HIPAA-mandated encrypted tenant separation requirements. Penetrate through consumption-based licensing transitions for educational institutions with seasonal research computing peaks. For Investors and Strategic Acquirers: Roll-up economics work for regional managed service providers with sovereign cloud certifications because compliance fragmentation across European member states prevents hyperscaler standardization. Target acquisition archetypes with established confidential computing hardware partnerships and automotive sector simulation workload expertise. Watch for inflection signals in German automotive procurement specifications requiring algorithmic audit trail capabilities ahead of EU AI Act enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Hardware-based trusted execution environments enable encrypted processing for Swiss wealth management analytics workloads. |
| Container-Native Virtualization Platform | Kubernetes-centric management planes dissolve traditional VM boundaries and capture developer mindshare from legacy orchestration. |
| Sovereign Cloud Certification Program | ANSM and CNIL alignment in France accelerates hospital system procurement cycles for clinical data environments. |
| Edge VM Orchestration Deployment | Localized processing in Polish manufacturing hubs addresses industrial IoT latency requirements outside saturated Western markets. |
| Consumption-Based Licensing Transition | Metered vCPU-hour billing captures healthcare providers with seasonal research computing peaks in Paris-Saclay research clusters. |
Research Methodology
Multiple input streams — hyperscaler capex disclosures, data center operator interviews, and regulatory filing analysis — were reconciled to construct market estimates. Primary discussions with cloud infrastructure architects, enterprise IT procurement officers, virtualization platform engineers, and managed service provider channel partners informed demand-side validation. Secondary sources included SEC 10-K filings from diversified technology conglomerates, EU regulatory impact assessments for the AI Act, and national data center energy consumption reports. Bottom-up triangulation across service type deployments and top-down reconciliation against aggregate infrastructure spending produced converged market sizing.
Data-stream reconciliation across deployment model adoption curves, end-user vertical penetration rates, and regional compliance requirement intensity shaped the analytical framework. Segmentation dimensions modeled include service tier control depth, cloud topology latency sensitivity, organizational scale procurement complexity, and guest environment licensing economics. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Forecast inputs incorporated EU AI Act implementation timelines and automotive simulation workload growth patterns in German engineering clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated container-native virtualization substitution or prolonged energy input volatility in European grid markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Cloud Database Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Healthcare Cloud Infrastructure Market
Cloud Computing
Commercial Cloud Market
Cloud Computing
Serverless Computing Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Telecom Cloud Market