
 Peru Telecom Market | 2026-2036
Peru Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Telecom Market Insights
OSIPTEL's 3.5 GHz band certification cycle is collapsing the field of qualified 5G infrastructure bidders. Movistar anchors its position through captive fiber backhaul networks spanning the Andean spine. Claro Perú leverages América Móvil's regional procurement scale to compress equipment costs below local rivals. Bitel specializes in low-ARPU prepaid penetration across Peru's Amazonian departments where competitors lack retail density.
Peru telecom encompasses the transmission, switching, and reception of voice, data, and video signals across copper, fiber, and wireless media operating between 700 MHz and 28 GHz spectrum bands. The sector delivers connectivity infrastructure enabling financial inclusion, remote education, and telemedicine across mountainous terrain and rainforest geography. Fiber optic deployment under the technology segment leads capital absorption as submarine cable landings in Lurín and Pascales anchor international bandwidth. Mobile services sustain the largest revenue pool though 5G remains nascent outside Lima, while prepaid pricing models dominate subscriber counts among informal economy workers. Enterprise customer types generate disproportionate margin per account due to managed SD-WAN and cloud connectivity requirements.
OSIPTEL enforces quality-of-service benchmarks and interconnection tariffs that directly constrain retail pricing freedom for operators. The Ministry of Transport and Communications governs spectrum auctions and universal service fund obligations that redistribute resources toward underserved Andean and Amazonian provinces. Peru's Personal Data Protection Law imposes data localization requirements affecting cloud service architecture decisions. Stakeholders must monitor whether pending spectrum harmonization rulings alter the competitive balance between incumbent fiber holders and wireless-first challengers.
Market Dynamics
OSIPTEL's spectrum reallocation mandates are compressing infrastructure deployment timelines while forcing operators to rebalance capital between fiber densification and 5G radio access networks across Peru's challenging topography.
Growth Catalysts
- Mobile banking adoption:Rural agricultural cooperatives are accelerating service uptake as digital financial inclusion mandates from Peru's Ministry of Transport and Communications drive connectivity requirements into previously underserved Andean valleys.
- Fiber submarine cable landings:The Lurín and Pascales cable stations are anchoring international bandwidth expansion that enables cloud service delivery to Lima's enterprise corridor and Arequipa's technology cluster.
- Universal Service Fund obligations:OSIPTEL's redistribution mechanism is channeling resources toward Amazonian provinces where prepaid mobile penetration remains below metropolitan benchmarks.
Market Restraints
- Andean terrain engineering costs:Fiber trenching across Peru's mountainous spine requires specialized labor and equipment that inflates per-kilometer deployment costs versus coastal plains.
- 3.5 GHz certification scarcity:OSIPTEL's collapsing bidder pool for 5G infrastructure concentrates qualified vendor supply among a narrowing field of equipment providers.
- Satellite broadband substitution:Low-earth orbit constellations are emerging as an alternative for remote Amazonian connectivity, threatening fixed wireless access investments in the lowest-density departments.
Strategic Opportunities
- Arequipa technology cluster expansion:Peru's second-largest city is developing specialized data center and software export capacity that demands redundant fiber routes and low-latency international links.
- SD-WAN enterprise migration:Managed software-defined wide area network services are converging with cloud connectivity requirements to create premium-margin revenue pools among mining and financial sector headquarters.
- Data localization compliance:Peru's Personal Data Protection Law is creating architectural mandates that favor domestic data center builds and edge computing nodes over centralized international cloud architectures.
Industry Challenges
- Radio frequency engineering specialization:Peru's 700 MHz to 28 GHz spectrum complexity across diverse propagation environments requires talent pools that remain concentrated in Lima metropolitan universities.
- Legacy copper network integration:Incumbent operators face technical friction migrating last-mile subscribers from aging twisted-pair infrastructure to fiber-to-the-home without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Telecom Market |
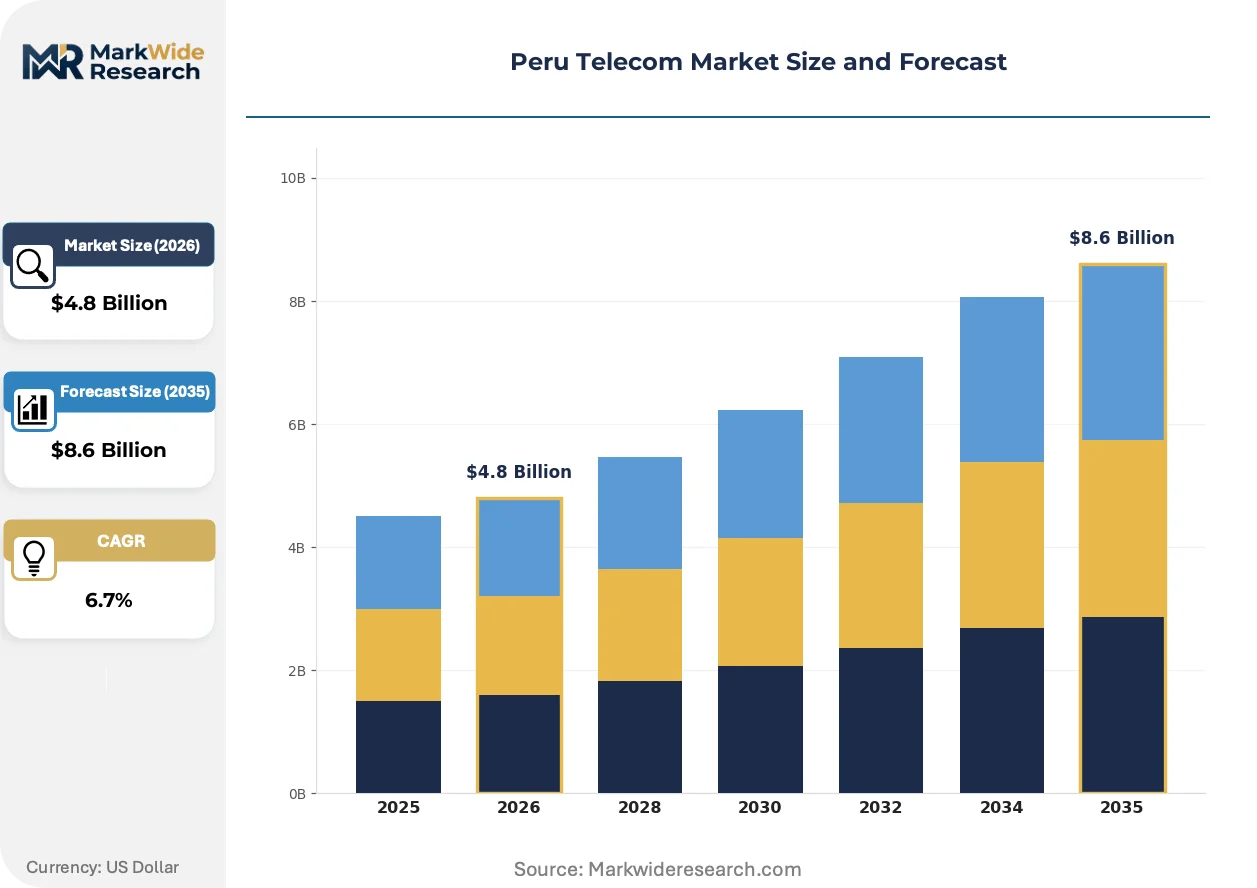
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Internet Services, VoIP Services Customer Type: Residential, Small Business, Enterprises, Government Technology: 4G LTE, 5G, Fiber Optic, DSL Pricing Model: Prepaid, Postpaid, Unlimited Plans, Bundled Offers |
| Companies Covered | Claro Perú (América Móvil), Movistar (Integratel Perú), Entel Perú S.A., Bitel (Viettel Perú S.A.C), Telefónica del Perú, Americatel Peru, MiFibra, Fiberlux, P&D Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Telecom Market Trends and Innovations
Peru's telecom infrastructure is undergoing simultaneous compression of deployment timelines and expansion of service breadth as regulatory pressure intersects with geographic constraints.
Open RAN architectures are displacing traditional integrated base station procurement models across Peru's 5G deployment planning. Regional operators are piloting disaggregated radio access networks to reduce vendor lock-in and accelerate rural site commissioning. This technological shift is displacing established equipment supply relationships that have dominated Peruvian infrastructure markets for two decades.
Peru's Ministry of Transport and Communications spectrum harmonization rulings are reshaping competitive balance between fiber incumbents and wireless challengers. The pending decisions on mid-band allocation will determine whether fixed wireless access can achieve economic parity with fiber in secondary cities. Mobile-first operators are accelerating 3.5 GHz trial networks in anticipation of favorable harmonization outcomes that would reduce backhaul cost burdens.
Enterprise procurement patterns are fragmenting as mining and agribusiness headquarters unbundle connectivity from traditional managed service bundles. Chief information officers in Lima's corporate district are adopting direct cloud interconnect agreements that bypass legacy telecom resale structures. This behavioral shift is most visible among copper and gold mining operations requiring dedicated low-latency links to commodity trading floors.
Peru Telecom Market Segmentation
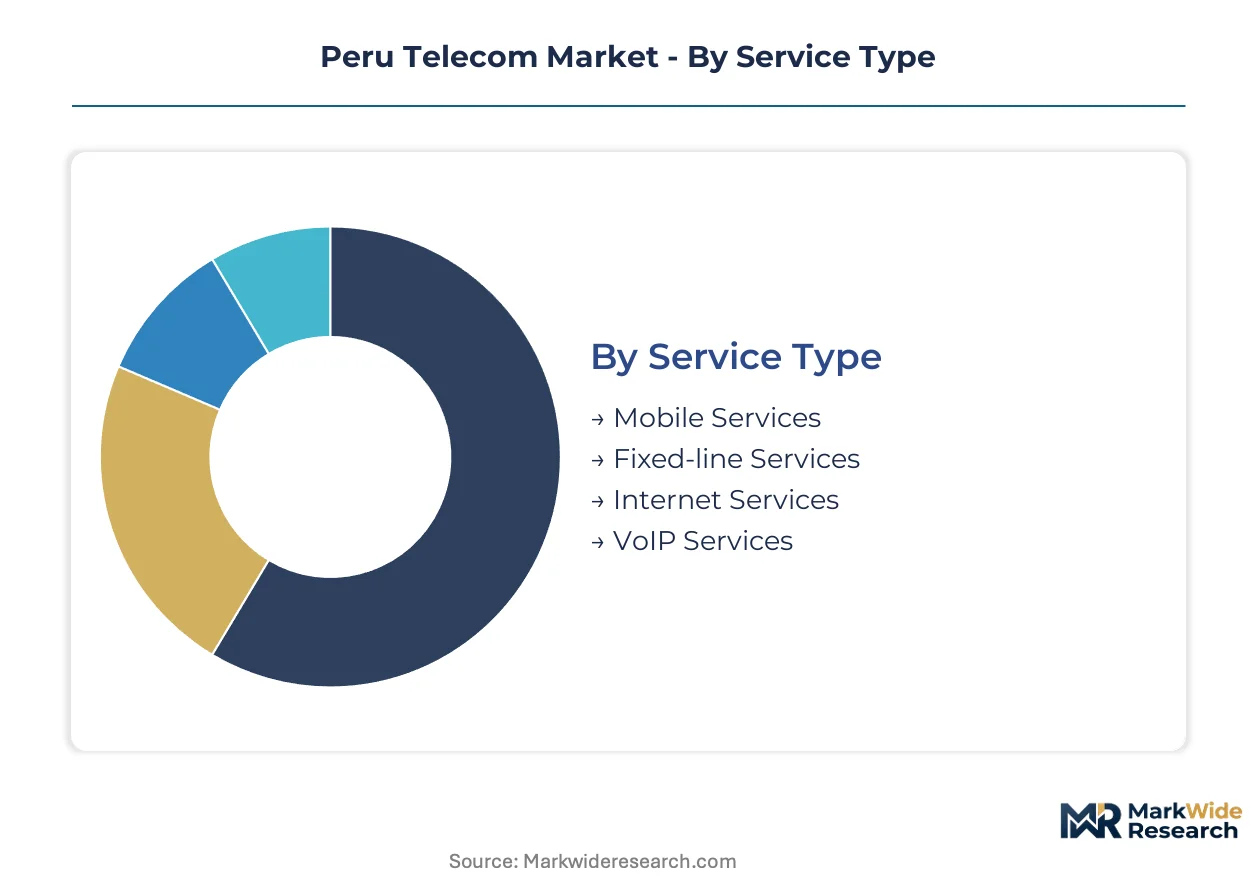
Peru's telecom segmentation reflects divergent regulatory pressures and geographic constraints that fragment operator strategies across service tiers. OSIPTEL's universal service mandates and spectrum reallocation rulings create distinct compliance burdens depending on segment positioning.
Service Type:
OSIPTEL's quality-of-service benchmarks and interconnection tariffs apply differentially across fixed and wireless infrastructure, altering competitive economics by delivery mode.
- Mobile Services:Voice and data transmission across 700 MHz to 3.5 GHz spectrum bands dominates subscriber counts through prepaid penetration in Lima's informal economy corridors and Amazonian departments. Rural agricultural cooperatives are accelerating mobile banking adoption as digital financial inclusion mandates from Peru's Ministry of Transport and Communications drive connectivity requirements into previously underserved Andean valleys.
- Internet Services:Broadband delivery via fiber, fixed wireless, and satellite architectures concentrates revenue generation in metropolitan Lima and Arequipa's emerging technology cluster. The Lurín and Pascales submarine cable landings anchor international bandwidth expansion that enables cloud service delivery to enterprise corridors.
- Fixed-line Services:Legacy copper infrastructure persists in urban centers where twisted-pair networks face technical friction migrating subscribers to fiber-to-the-home without service disruption.
- VoIP Services:Voice-over-IP protocols ride data networks to compress per-minute costs below circuit-switched alternatives for small business customers.
Mobile Services handles the majority of throughput; Internet Services is the fastest mover on share.
Customer Type:
Margin structures diverge sharply between mass-market prepaid subscribers and enterprise accounts requiring managed SD-WAN and cloud connectivity.
- Enterprises:Mining and financial sector headquarters generate disproportionate margin per account through managed software-defined wide area network services converging with cloud connectivity requirements. Chief information officers in Lima's corporate district are adopting direct cloud interconnect agreements that bypass legacy telecom resale structures.
- Residential:Household demand concentrates in Lima's metropolitan corridor where fiber-to-the-home deployment competes with fixed wireless access for last-mile connectivity.
- Government:Public sector procurement under universal service fund obligations channels resources toward Amazonian provinces where prepaid mobile penetration remains below metropolitan benchmarks.
- Small Business:Informal economy workers and micro-enterprises drive prepaid pricing model dominance across Peru's urban periphery.
Enterprises commands the highest margin per connection; Government procurement is expanding most quickly under redistribution mandates.
Technology:
Capital absorption patterns favor fiber densification over 5G radio access networks as OSIPTEL's spectrum reallocation mandates compress infrastructure deployment timelines.
- Fiber Optic:Submarine cable landings in Lurín and Pascales anchor international bandwidth while terrestrial trenching across the Andean spine requires specialized labor and equipment that inflates per-kilometer deployment costs versus coastal plains.
- 5G:Open RAN architectures are displacing traditional integrated base station procurement models across deployment planning, with regional operators piloting disaggregated radio access networks to reduce vendor lock-in and accelerate rural site commissioning.
- 4G LTE:Existing infrastructure sustains coverage across secondary cities where mid-band spectrum harmonization rulings remain pending.
- DSL:Legacy copper-based digital subscriber line technology serves remaining subscribers in areas awaiting fiber overbuild.
Fiber Optic absorbs the largest capital share; 5G deployment is gaining share fastest under spectrum reallocation pressure.
Pricing Model:
Prepaid dominance among informal economy workers contrasts with postpaid and unlimited structures capturing higher lifetime value in enterprise segments.
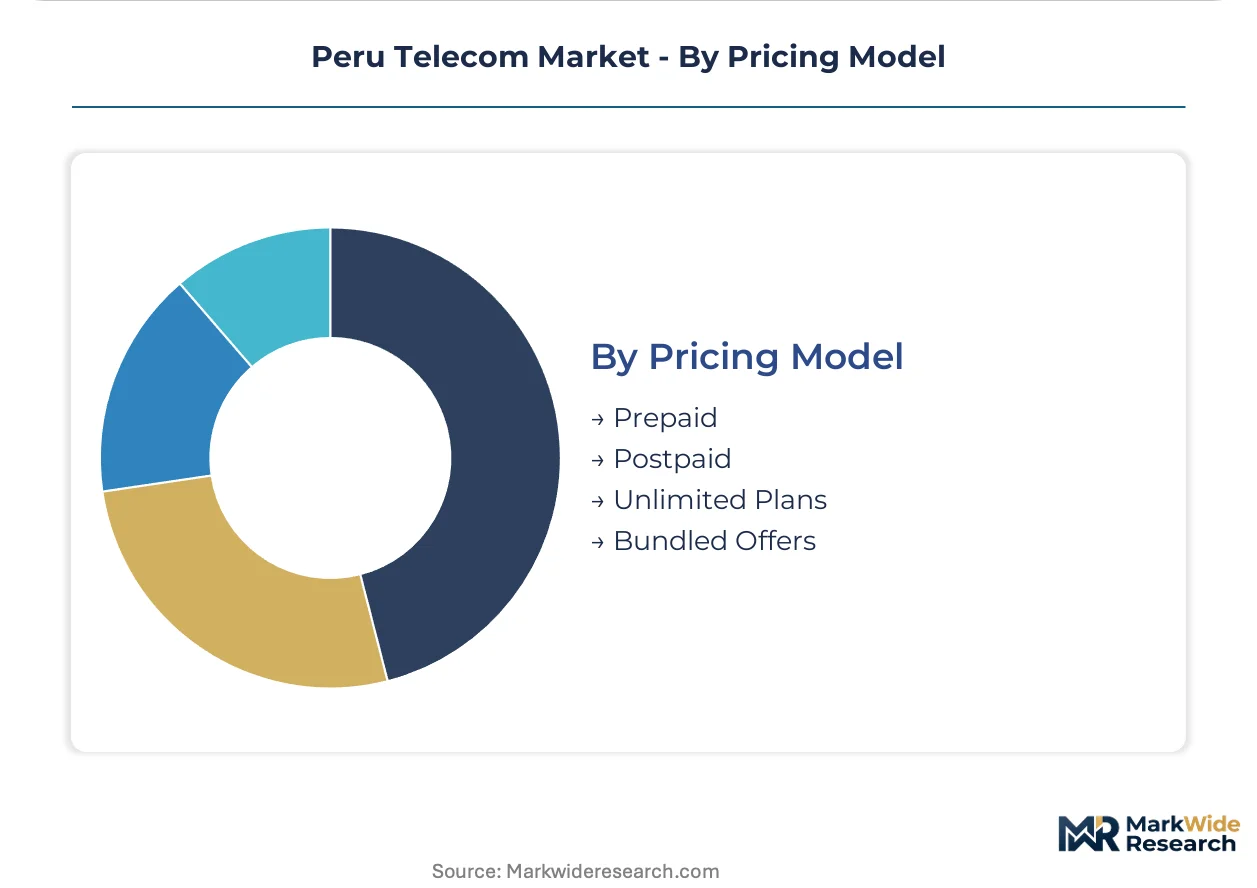
- Prepaid:Low-ARPU penetration across Peru's Amazonian departments where competitors lack retail density sustains Bitel's specialized positioning against metropolitan-focused rivals.
- Postpaid:Contract-based billing with device financing bundles captures higher credit-qualified subscribers in Lima's formal employment corridors.
- Unlimited Plans:Flat-rate data allowances respond to streaming and mobile banking traffic growth among urban residential segments.
- Bundled Offers:Converged fixed-mobile-service packages target household stickiness in fiber-served neighborhoods.
Prepaid handles the majority of subscriber connections; Unlimited Plans are climbing the fastest on revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSIPTEL's universal service fund obligations redistribute capital toward underserved provinces, concentrating infrastructure investment in Lima's metropolitan corridor while channeling resources into Andean valleys and Amazonian departments. Peru's spectrum reallocation mandates compress deployment timelines across these divergent geographies. The analysis examines five sub-regional markets where regulatory pressure intersects with distinct terrain and demand profiles.
Lima Metropolitan Corridor
Enterprise SD-WAN demand from mining and financial headquarters drives premium connectivity procurement in Peru's capital district. OSIPTEL's quality-of-service benchmarks apply most stringently here, constraining retail pricing freedom for operators serving corporate clients. The Lurín submarine cable landing anchors international bandwidth expansion enabling cloud service delivery to Lima's enterprise corridor.
Arequipa Technology Cluster
Data center and software export capacity development demands redundant fiber routes and low-latency international links in Peru's second-largest city. The Ministry of Transport and Communications spectrum harmonization rulings pending for mid-band allocation will determine fixed wireless access economics in this secondary metro. Specialized data center builds favor domestic edge computing nodes over centralized international cloud architectures.
Andean Spine Departments
Rural agricultural cooperatives accelerate mobile banking adoption as digital financial inclusion mandates drive connectivity requirements into previously underserved mountain valleys. Fiber trenching across Peru's mountainous spine requires specialized labor and equipment that inflates per-kilometer deployment costs versus coastal plains. Movistar anchors its position through captive fiber backhaul networks spanning this challenging topography.
Amazonian Departments
Low-ARPU prepaid penetration sustains specialized operator positioning where competitors lack retail density across Peru's rainforest geography. Low-earth orbit satellite constellations emerge as an alternative for remote connectivity, threatening fixed wireless access investments in the lowest-density departments. Universal Service Fund obligations channel resources toward provinces where prepaid mobile penetration remains below metropolitan benchmarks.
Northern Coastal Cities
Secondary urban centers between Lima and Ecuador face pending spectrum harmonization decisions that will determine whether fixed wireless access achieves economic parity with fiber. Legacy copper infrastructure persists where twisted-pair networks face technical friction migrating subscribers to fiber-to-the-home. Open RAN pilot programs accelerate rural site commissioning in anticipation of favorable regulatory outcomes.
Peru Telecom Market Competitive Landscape
Listed leaders compete with private specialists across infrastructure ownership models in Peru's telecom sector. The field compresses around three operators controlling fiber backhaul and spectrum positions, while specialized challengers exploit geographic niches. Market structure reflects a tiered hierarchy: integrated incumbents with captive infrastructure, regional wireless-first operators leveraging group procurement scale, and low-ARPU specialists targeting underserved peripheries. Dominant competitive moves include fiber densification investments in metropolitan corridors and spectrum positioning ahead of harmonization rulings.
Within the integrated incumbent tier, Movistar and Claro Perú exemplify divergent infrastructure strategies. Movistar occupies a position anchored by captive fiber backhaul networks spanning Peru's Andean spine, while Claro Perú sits within a regional procurement architecture that compresses equipment costs below local rivals. Bitel represents the specialized challenger archetype, occupying a position focused on low-ARPU prepaid penetration across Amazonian departments where metropolitan-focused competitors lack retail density. These three operators collectively illustrate how spectrum access, infrastructure ownership, and geographic targeting stratify competitive positioning under OSIPTEL's regulatory framework.
| Leading Market Players |
|---|
| Claro Perú (América Móvil) |
| Movistar (Integratel Perú) |
| Entel Perú S.A. |
| Bitel (Viettel Perú S.A.C) |
| Telefónica del Perú |
| Americatel Peru |
| MiFibra |
| Fiberlux |
| P&D Telecom |
| Others |
Pricing and Supply Chain Analysis
Long-term spectrum licensing agreements lock in both infrastructure access and cost visibility for Peru's operators as OSIPTEL's reallocation mandates compress deployment timelines across fiber and 5G radio access networks.
Pricing Analysis
Service tier differentiation creates the primary spread across Peru's telecom market, separating premium fiber-to-the-home packages from standard fixed wireless and economy prepaid mobile plans. Prepaid dominance among Amazonian departments and Lima's informal economy corridors sustains low-ARPU positioning, while enterprise SD-WAN contracts capture higher lifetime value through managed cloud connectivity bundles. Cost compression in rural fiber deployment intensifies because Andean terrain engineering inflates per-kilometer trenching expenses versus coastal plains. Mining and financial headquarters show least price sensitivity due to dedicated low-latency requirements, while agricultural cooperatives drive highest sensitivity as mobile banking adoption accelerates.
Supply Chain Analysis
Submarine cable landings at Lurín and Pascales concentrate international bandwidth ingress for Peru's domestic networks. Equipment sourcing draws from China, South Korea, and Finland for base station hardware, fiber optic cable, and core network infrastructure. Single-source vulnerability persists in 3.5 GHz radio frequency components where OSIPTEL's collapsing bidder pool narrows qualified vendor supply. Distribution runs through centralized procurement hubs in Lima metropolitan warehouses serving regional operator depots across coastal, Andean, and Amazonian geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's telecom sector sits at an inflection where 5G spectrum harmonization rulings will restructure competitive economics between fiber incumbents and wireless challengers across the next decade.
For Market Incumbents: Shield metropolitan fiber positions through accelerated densification in Lima's enterprise corridor before fixed wireless access achieves economic parity under pending mid-band rulings. Consolidate captive backhaul advantages across the Andean spine where terrain costs deter challenger overbuild. Prioritize Open RAN pilot investments to reduce vendor lock-in exposure as equipment supply concentrates. For New Entrants and Emerging Players: Anchor in Amazonian departments where prepaid penetration gaps persist and satellite broadband substitution remains nascent. Target low-ARPU rural agricultural cooperatives with mobile banking-optimized service bundles. Pursue direct cloud interconnect partnerships with mining headquarters seeking to bypass legacy telecom resale structures. For Investors and Strategic Acquirers: Capital is best deployed toward regional fiber specialists with redundant routes into Arequipa's technology cluster and established edge computing node positions compliant with Peru's data localization mandates. Long-term viability hinges on spectrum positioning ahead of harmonization outcomes and universal service fund capture in underserved provinces. Monitor OSIPTEL certification cycle velocity as the signal for infrastructure vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Densification Investment | Captures enterprise SD-WAN demand in Lima's mining and financial headquarters corridor. |
| Spectrum Positioning | Secures 3.5 GHz allocation ahead of OSIPTEL harmonization rulings reshaping wireless economics. |
| Open RAN Deployment | Reduces vendor lock-in while accelerating rural site commissioning across Amazonian departments. |
| Edge Computing Buildout | Addresses Peru's Personal Data Protection Law localization requirements favoring domestic nodes. |
| Universal Service Fund Capture | Channels subsidized capital toward Andean valleys and Amazonian provinces below metropolitan benchmarks. |
Research Methodology
Cross-validation between operator infrastructure planners and OSIPTEL regulatory filings anchors the qualitative findings in this study. Primary interviews with network engineering directors, spectrum policy specialists, rural cooperative financial officers, and enterprise CIOs in Lima's corporate district combined with secondary validation from submarine cable landing disclosures, universal service fund allocation records, and spectrum auction documentation. Bottom-up site deployment modeling and top-down revenue pool sizing triangulate market estimates across service type, customer segment, and technology dimensions.
Sensitivity analysis on spectrum harmonization timing and fiber trenching cost inflation brackets the projection range across the analysis window. Segmentation dimensions modeled include service delivery mode, customer type, infrastructure technology, and geographic terrain cluster. CAGRs derive from installed base evolution, pricing trajectory assumptions, and technology substitution curves. Key inputs encompass mobile banking transaction growth rates and enterprise cloud connectivity contract values.
Decision-makers should treat outputs as directional under stable regulatory enforcement and spectrum allocation timelines; material deviation in OSIPTEL harmonization rulings would warrant model refresh. Practitioners should keep alternative scenarios live as low-earth orbit satellite coverage expansion and data localization compliance interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Argentina ICT Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Qatar Telecom Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Poland Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Global Relay Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
South Africa MNO - MVNO Market