
 Spain Insulin Drugs and Delivery Devices Market | 2026-2036
Spain Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Insulin Drugs and Delivery Devices Market Analytics
Remote patient monitoring and cloud-connected dose logging is realigning what Spanish providers procure, shifting contracts toward subscription-enabled platforms rather than standalone hardware. Novo Nordisk Pharma S.A. leverages its endocrinology heritage to sustain dominance in long-acting analog formulations. Ypsomed Diabetes, SLU anchors the pen needle and pump consumables segment through pharmacy channel control. Sanofi-aventis SA competes on biosimilar insulin portfolios priced within Spain's SNS reimbursement tiers.
Insulin drugs and delivery devices comprise parenteral protein formulations and electromechanical systems engineered for subcutaneous administration, with pens typically calibrated to 0.5-unit or 1-unit dose increments and pumps operating at basal rates between 0.025 and 35 units per hour. These technologies manage glycemic control in Type 1 and Type 2 diabetes patients by mimicking physiological insulin secretion patterns. Insulin Pens retain the largest installed base among Product Type categories, though Patch Pumps within the Delivery Device dimension represent the fastest-growing configuration as wearable form factors reduce daily intervention burden. Biosimilars within the Formulation segment are capturing margin pools previously held by originator molecules, while Homecare Settings among End Users are displacing hospital-based initiation protocols for stable patients.
Spain's Agencia Española de Medicamentos y Productos Sanitarios (AEMPS) enforces CE marking under EU MDR for all active delivery devices, while the Interterritorial Council of the National Health System coordinates regional reimbursement inclusion. These frameworks determine market access speed and pricing ceilings across Spain's seventeen autonomous communities. Stakeholders must monitor how AEMPS post-market surveillance requirements and evolving SNS tender aggregation rules will reshape competitive positioning for connected delivery platforms.
Market Dynamics
Cloud-connected insulin delivery platforms are restructuring procurement relationships across Spain's autonomous communities, pulling contracts away from standalone device sales toward subscription-enabled monitoring ecosystems that lock in recurring revenue streams.
Growth Catalysts
- EU MDR compliance deadlines:Device manufacturers accelerating CE marking renewals for active delivery systems are expanding certified product portfolios available to Spanish hospital pharmacies.
- Homecare protocols:Regional health services in Madrid and Catalonia are authorizing self-administration training for stable Type 2 patients, multiplying addressable user bases for pen and patch pump formats.
- Biosimilar substitution mandates:Spain's SNS reimbursement tiers now favor interchangeable insulin analogs, compressing originator pricing and expanding patient access volumes.
Market Restraints
- Active pharmaceutical ingredient concentration:Bulk insulin supply chains cluster among three global fermentation facilities, exposing Spanish formulators to input volatility and customs clearance delays.
- Pump consumables cost structure:Infusion set and reservoir replacement cycles impose recurring out-of-pocket burdens on patients outside SNS comprehensive coverage zones.
- EU MDR technical documentation requirements:Extended conformity assessment timelines for software-enabled devices delay market entry for next-generation connected pens.
Strategic Opportunities
- Andalusian and Galician autonomous communities:Underdeveloped specialized diabetes infrastructure in southern and northwestern Spain creates whitespace for hub-and-spoke telemedicine models linking rural primary care to urban endocrinology centers.
- Interoperability mandates:Emerging SNS data portability requirements for glucose monitoring integration create openings for open-platform pump and pen ecosystems.
- Pharmacy channel consolidation:Cooperative purchasing alliances among regional pharmacy networks are creating new gatekeeper roles for device and consumable distribution.
Industry Challenges
- Diabetes educator workforce gaps:AEMPS-certified training capacity for connected device onboarding lags device deployment rates in several autonomous communities.
- Legacy HIS integration:Hospital information system architectures in Valencia and Basque Country regions require custom middleware development for seamless dose data ingestion.
- Reimbursement code fragmentation:Seventeen autonomous communities maintain divergent SNS tariff classifications for patch pump versus conventional pump therapies, complicating national pricing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Insulin Drugs and Delivery Devices Market |
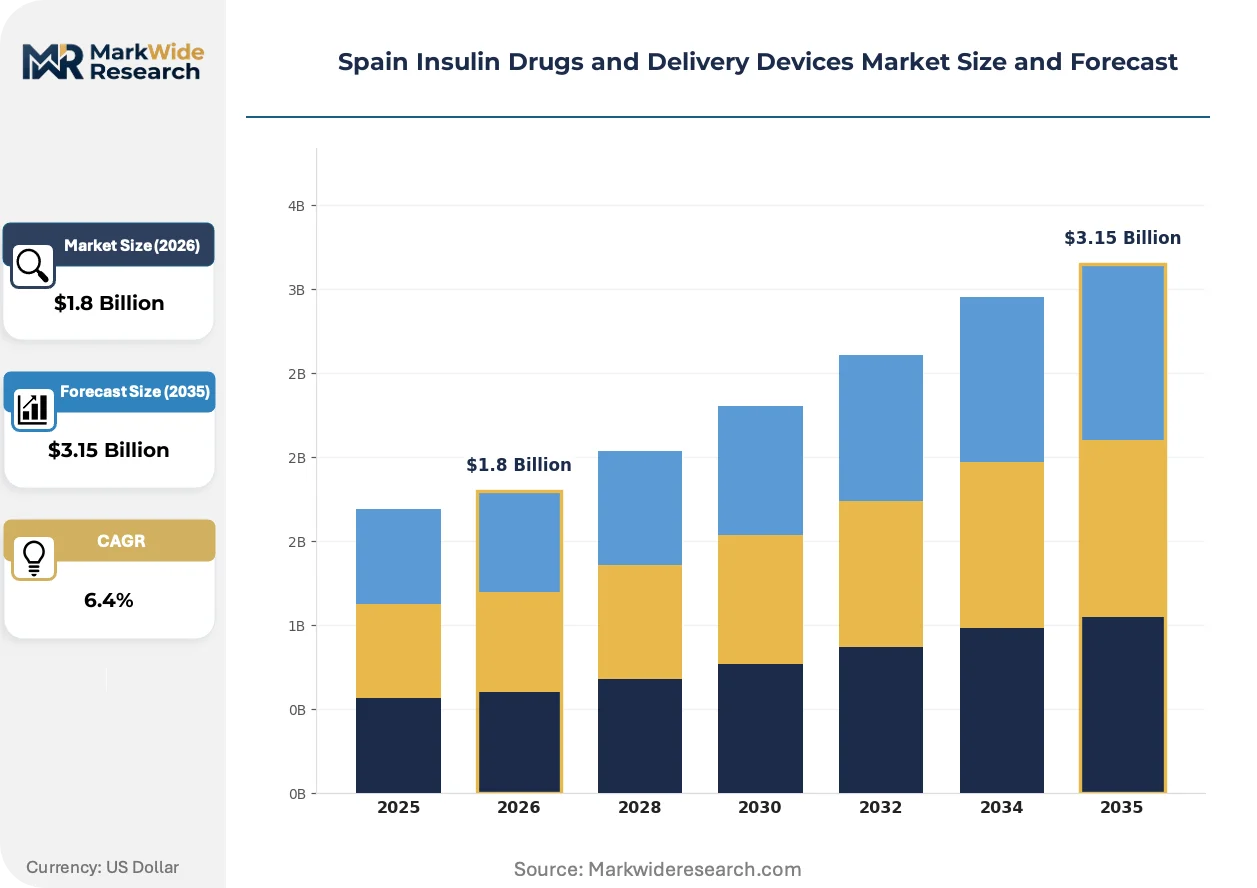
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Syringes, Inhalable Insulin Delivery Device: Smart Insulin Pens, Disposable Pens, Continuous Glucose Monitors, Patch Pumps End User: Hospitals, Clinics, Homecare Settings, Pharmacies Formulation: Rapid-Acting, Long-Acting, Premixed Insulin, Biosimilars |
| Companies Covered | Biocon Biologics Spain S.L.U., Ypsomed Diabetes, SLU, Novo Nordisk Pharma S.A., B. Braun Medical, SAU, Medtronic, Sanofi-aventis SA, BECTON DICKINSON ESPAÑA, SA, Merck Sharp & Dohme de España, SA, Lilly Spain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Insulin Drugs and Delivery Devices Market Evolving Landscape
Connected delivery hardware combined with automated dose optimization algorithms is compressing the gap between patient-administered and provider-managed glycemic control across Spanish diabetes care pathways.
Patch pump form factors with integrated continuous glucose monitoring receivers are overtaking traditional tethered pump configurations among pediatric and adolescent Type 1 cohorts in Barcelona and Madrid hospital networks. These wearable systems eliminate tubing management burdens while enabling caregiver remote oversight through smartphone dashboards. The shift is compressing maintenance revenue pools previously captured by durable medical equipment suppliers.
AEMPS post-market surveillance requirements under EU MDR are mandating real-world performance registries for all active insulin delivery devices marketed in Spain. Manufacturers must submit periodic safety update reports and device malfunction analyses to maintain CE marking validity. Software-enabled pen and pump vendors are responding by embedding automated adverse event logging and cloud-based batch traceability.
Spanish hospital pharmacy committees are consolidating insulin procurement through multi-year framework agreements that bundle drug and device volumes across regional health service footprints. These aggregated tenders favor suppliers offering integrated formularies spanning analogs, biosimilars, and matched delivery systems. The concentration is most visible in Catalonia's CatSalut procurement centralization and Andalusia's SAS tender unification.
Spain Insulin Drugs and Delivery Devices Market Segmentation
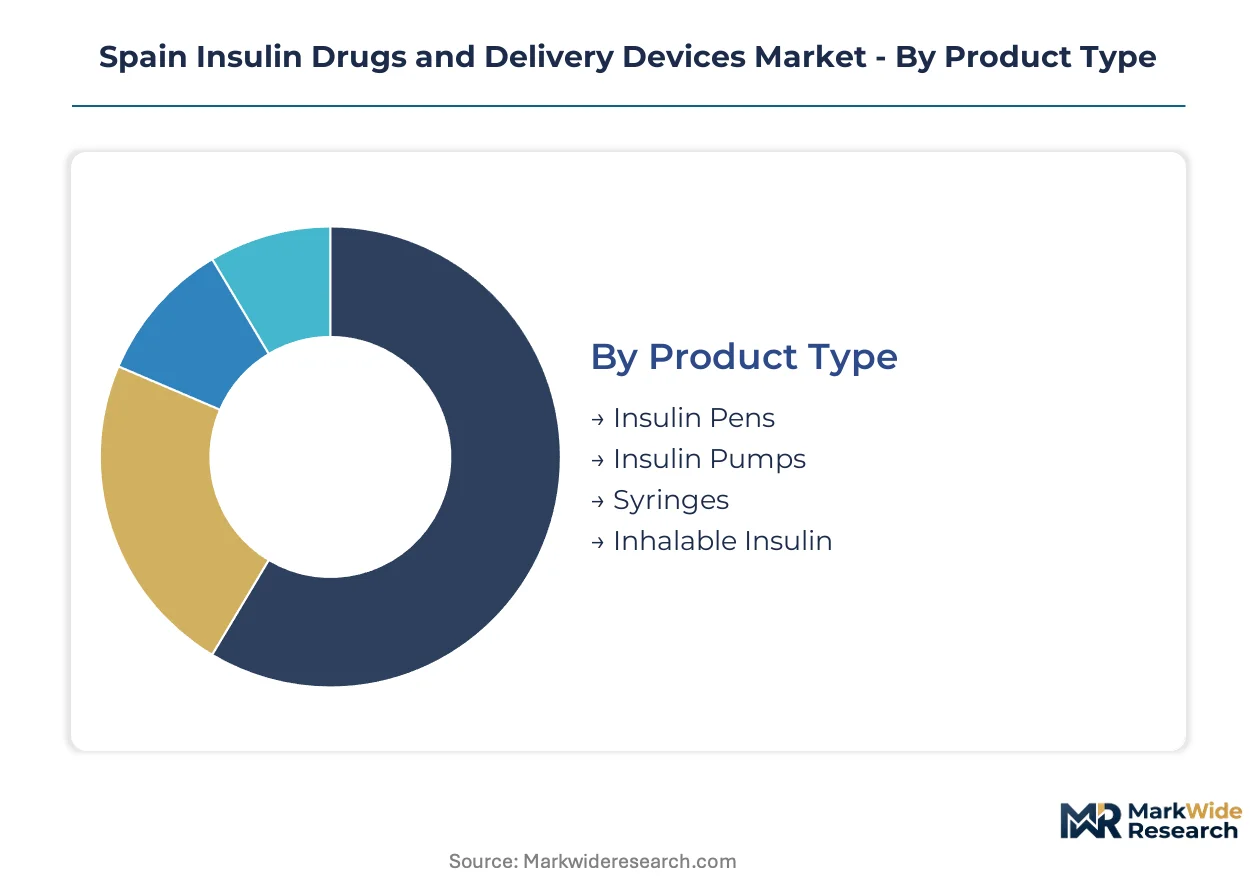
Device replacement cycles and therapeutic protocol shifts drive purchasing concentration across Spain's autonomous communities. Understanding segment boundaries clarifies where procurement budgets migrate between hospital pharmacy networks and homecare reimbursement streams.
Product Type:
Upgrade cadences vary sharply by mechanical complexity and consumable dependency, with durable platforms commanding longer replacement windows than disposable alternatives.
- Insulin Pens:Reusable and disposable pen systems calibrated to 0.5-unit or 1-unit increments dominate Madrid and Barcelona hospital pharmacy formularies. Replacement concentrates in pen body failures and cartridge depletion rather than full system obsolescence.
- Insulin Pumps:Tethered electromechanical devices operating basal rates between 0.025 and 35 units per hour require 4-year warranty cycles. AEMPS post-market surveillance mandates accelerate refresh timelines for software-enabled models in Catalonia's CatSalut network.
- Syringes:Conventional vial-and-syringe protocols persist in Valencia and Andalusia regions with limited pump coverage.
- Inhalable Insulin:Pulmonary delivery systems occupy niche positioning within specialized endocrinology centers.
Insulin Pens sits at the top of the volume ranking, with Insulin Pumps climbing the fastest.
Delivery Device:
Cost tier stratification separates premium connected ecosystems from basic mechanical alternatives, with reimbursement bandwidth determining accessible tiers.
- Smart Insulin Pens:Bluetooth-enabled dose logging and smartphone integration command premium positioning within Madrid's hospital pharmacy committees. Cloud connectivity mandates under EU MDR reshape procurement toward subscription-enabled platforms.
- Patch Pumps:Wearable tubeless configurations with integrated CGM receivers eliminate tubing management burdens. Barcelona pediatric networks drive adoption among adolescent Type 1 cohorts seeking caregiver remote oversight.
- Disposable Pens:Single-use prefilled systems dominate pharmacy channel volume through cooperative purchasing alliances.
- Continuous Glucose Monitors:Sensor-augmented pump ecosystems require interoperability certification under emerging SNS data portability requirements.
Disposable Pens captures the highest unit volume, while Patch Pumps gains share fastest through pediatric and adolescent segments.
End User:
Application context determines device specification, dosing precision requirements, and training infrastructure investment.
- Homecare Settings:Self-administration protocols for stable Type 2 patients multiply addressable user bases across pen and patch pump formats. Regional health services in Madrid and Catalonia authorize training programs that displace hospital-based initiation.
- Hospitals:Acute glycemic management and pump initiation protocols concentrate in specialized diabetes infrastructure corridors. Valencia and Basque Country HIS architectures require custom middleware for dose data ingestion.
- Clinics:Outpatient endocrinology centers bridge primary care and hospital pharmacy networks in underdeveloped southern Spain.
- Pharmacies:Cooperative purchasing alliances create gatekeeper roles for device and consumable distribution across autonomous communities.
Homecare Settings leads patient volume expansion, with Pharmacies deepening channel control fastest.
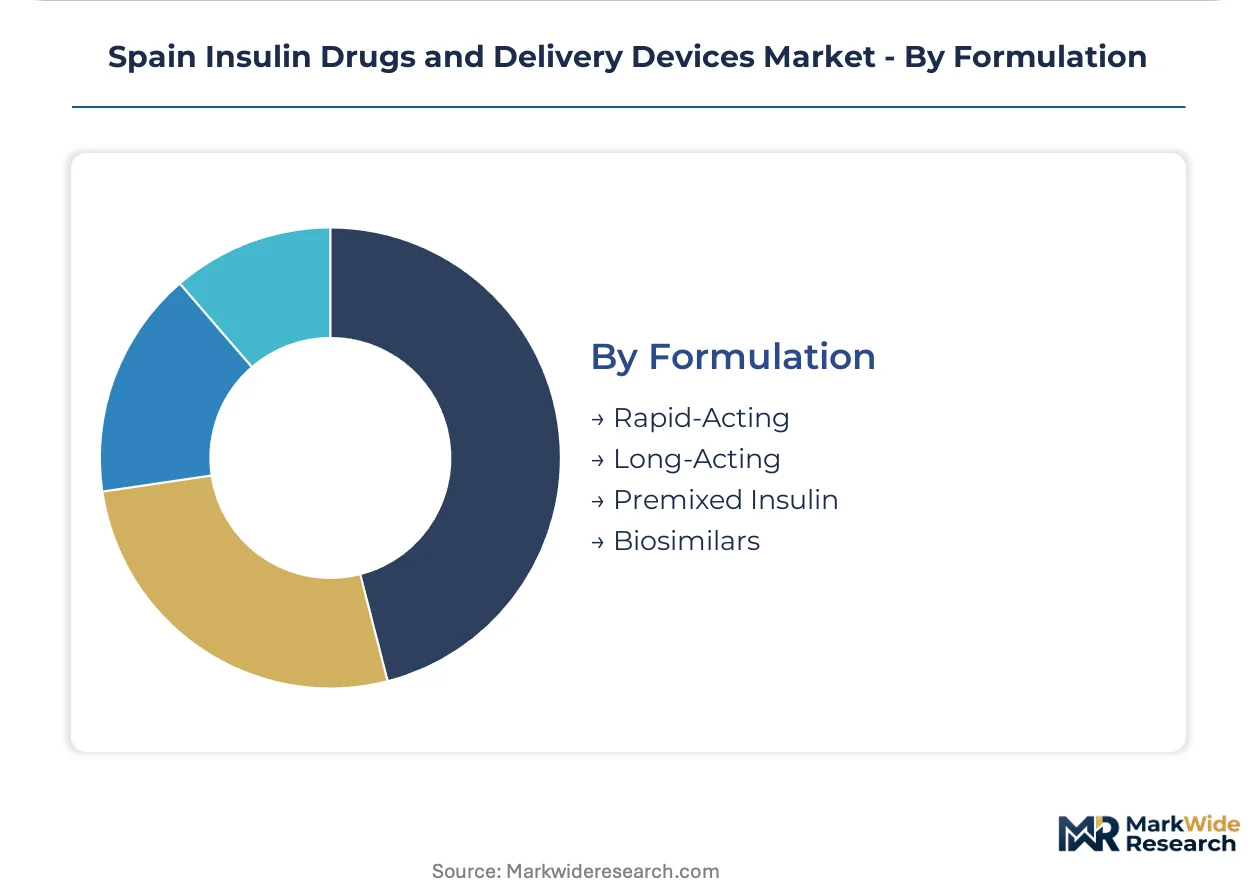
Formulation:
Margin structure separates originator analogs from interchangeable biosimilars, with SNS reimbursement tiers compressing premium positioning.
- Biosimilars:Interchangeable insulin analogs capture margin pools previously held by originator molecules. Spain's SNS reimbursement tiers favor substitution mandates that expand patient access volumes.
- Long-Acting:Basal insulin formulations sustain 24-hour glycemic coverage with reduced injection frequency. Novo Nordisk's endocrinology heritage reinforces dominance in analog portfolios.
- Rapid-Acting:Prandial coverage formulations align with bolus calculator integration in smart pen and pump ecosystems.
- Premixed Insulin:Fixed-ratio basal-bolus combinations serve stable Type 2 populations with limited titration capacity.
Long-Acting maintains the largest prescription base, though Biosimilars expands most quickly through SNS substitution protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's insulin delivery device penetration exceeds Spain's by roughly 15 percentage points among Type 1 patients, yet Spain's patch pump adoption curve is steepening faster than any major EU market. AEMPS regulatory pathways and SNS reimbursement fragmentation create distinct sub-regional competitive dynamics across Spain's autonomous communities.
Madrid
Hospital pharmacy committees in the capital region command the largest procurement budgets for connected pen ecosystems. CatSalut interoperability mandates force device vendors to certify glucose monitoring data portability before contract eligibility. The Madrid metropolitan corridor concentrates specialized endocrinology training capacity that feeds homecare self-administration protocols.
Catalonia
Barcelona pediatric networks drive patch pump volume through adolescent Type 1 cohorts seeking caregiver remote oversight. AEMPS post-market surveillance requirements accelerate software-enabled pump refresh cycles in this region. The city's hospital information system architecture requires custom middleware development for seamless dose data ingestion.
Andalusia
Underdeveloped specialized diabetes infrastructure creates whitespace for hub-and-spoke telemedicine models linking rural primary care to urban centers. SAS tender unification consolidates insulin procurement through multi-year framework agreements. Seville and Málaga hospital pharmacies are consolidating formularies around bundled drug-device volumes.
Basque Country
Legacy HIS integration challenges delay connected device deployment despite strong purchasing power. Regional health services maintain divergent SNS tariff classifications for patch pump versus conventional pump therapies. Bilbao medical device distributors are developing middleware solutions for dose data ingestion.
Valencia
Conventional vial-and-syringe protocols persist here due to limited pump coverage in SNS reimbursement tiers. Regional pharmacy cooperative purchasing alliances are creating new gatekeeper roles for consumable distribution. Valencia's hospital pharmacy committees lag Madrid and Barcelona in smart pen procurement authorization.
Spain Insulin Drugs and Delivery Devices Market Competitive Landscape
Top-tier vendors anchor originator analog and premium delivery device segments, while mid-tier biosimilar specialists and regional device distributors compete on SNS reimbursement tier positioning. The market structure concentrates around three strategic archetypes: multinational pharmaceutical incumbents with endocrinology heritage, Swiss and German precision device manufacturers, and emerging Indian biosimilar producers. Dominant competitive moves include portfolio diversification into connected delivery ecosystems and backward integration into active pharmaceutical ingredient supply.
Among Switzerland-based precision device specialists, Ypsomed Diabetes, SLU exemplifies the pharmacy channel control archetype through pen needle and pump consumables positioning. Novo Nordisk Pharma S.A. and Sanofi-aventis SA represent the multinational pharmaceutical incumbent tier, with the former anchoring long-acting analog formulation dominance and the latter occupying biosimilar portfolio positioning within SNS reimbursement tiers. These three entities collectively illustrate how heritage endocrinology capabilities, device-channel integration, and biosimilar pricing discipline define competitive positioning in Spain's fragmented autonomous community procurement landscape.
| Leading Market Players |
|---|
| Biocon Biologics Spain S.L.U. |
| Ypsomed Diabetes, SLU |
| Novo Nordisk Pharma S.A. |
| B. Braun Medical, SAU |
| Medtronic |
| Sanofi-aventis SA |
| BECTON DICKINSON ESPAÑA, SA |
| Merck Sharp & Dohme de España, SA |
| Lilly Spain |
| Others |
Value Network & Pricing Analysis
Spain's SNS tender aggregation for connected insulin delivery systems is forcing manufacturers to restructure cost bases around subscription-enabled platform economics rather than transactional device sales. This procurement consolidation compresses margins on standalone hardware while rewarding vendors who bundle drug-device volumes across autonomous communities.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for electromechanical pump components, enabling Spanish distributors to negotiate steeper discounts on tethered and patch pump systems. Pricing stratifies across premium connected ecosystems, standard Bluetooth-enabled pens, and economy mechanical alternatives, with AEMPS software certification tiers serving as the primary differentiation driver. Cost compression in the economy tier intensifies because Indian biosimilar producers are flooding vial-and-syringe channels with interchangeable analogs. Hospital pharmacy committees exhibit the highest price sensitivity, while pediatric endocrinology networks in Barcelona maintain willingness to pay for caregiver oversight features.
Supply Chain Analysis
Workforce availability constraints in Switzerland and Germany are limiting precision machining capacity for pen needle and pump consumable production, extending lead times for Spanish pharmacy channel replenishment. Bulk active pharmaceutical ingredient supply clusters in Denmark, the United States, and India, with fermentation capacity expansion lagging demand growth for long-acting analog formulations. Spanish formulators face single-source vulnerability for recombinant insulin crystals, as three global facilities control the majority of pharmaceutical-grade output. Distribution runs through cooperative purchasing alliances among regional pharmacy networks, with Madrid and Barcelona hubs consolidating inbound logistics before autonomous community allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Spain's insulin delivery market rests on capturing recurring revenue from cloud-connected dose logging platforms while originator molecule pricing erodes under biosimilar substitution protocols.
For Market Incumbents: Cement dominance in long-acting analog formulations by deepening backward integration into recombinant protein fermentation capacity, insulating against API supply volatility that threatens Novo Nordisk's margin structure. Accelerate CE marking renewals for software-enabled pens under EU MDR post-market surveillance requirements to lock out mid-tier competitors lacking AEMPS-certified training infrastructure. Channel control through pharmacy cooperative alliances remains the critical defensive lever against emerging Indian biosimilar entrants. For New Entrants and Emerging Players: Enter via hub-and-spoke telemedicine models targeting Andalusia and Galicia's underdeveloped diabetes infrastructure, where rural primary care lacks specialized endocrinology linkages. Patch pump configurations with integrated CGM receivers represent the most penetrable segment among adolescent Type 1 cohorts seeking caregiver remote oversight. A go-to-market angle anchored in open-platform interoperability with existing SNS data portability requirements bypasses Madrid's entrenched hospital pharmacy committees. For Investors and Strategic Acquirers: Asymmetric upside sits with precision device manufacturers possessing captive pen needle production and established AEMPS quality system certifications, as EU MDR technical documentation requirements extend conformity assessment timelines for unproven entrants. Long-term viability favors vendors who have vertically integrated into consumable manufacturing rather than pure-play software developers lacking hardware scale. Watch for inflection in SNS reimbursement code unification across autonomous communities, which would compress pricing arbitrage opportunities currently exploited by regional distributors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | AEMPS software-enabled device certifications accelerate market entry for connected pen ecosystems in CatSalut networks. |
| Backward Integration | Captive recombinant insulin fermentation insulates Spanish formulators from Danish API supply concentration risks. |
| Hospital System Partnership | Framework agreements with Madrid pharmacy committees lock in multi-year drug-device procurement volumes. |
| Software Companion Development | Cloud-connected dose logging platforms shift revenue from transactional hardware to recurring subscription streams. |
| Reimbursement Strategy | SNS tier positioning for interchangeable biosimilars expands patient access while compressing originator pricing power. |
Research Methodology
Direct dialogue with hospital pharmacy directors, AEMPS regulatory affairs specialists, endocrinology department heads, and cooperative purchasing alliance managers grounded the qualitative foundation of this study. Secondary validation drew from AEMPS post-market surveillance registries, SNS tender documentation across seventeen autonomous communities, EU MDR technical file databases, and CatSalut procurement centralization records. Bottom-up patient population modeling and top-down pharmaceutical sales triangulation converged on segment-level estimates.
Output metrics spanning device unit deployments, drug prescription volumes, and subscription platform adoption rates were generated across the projection horizon. Segmentation dimensions encompassed product type, delivery device configuration, end user setting, and formulation category, with regional regulatory cluster differentiation across Spain's autonomous communities. CAGRs were derived from fitted growth curves incorporating AEMPS approval timelines, SNS reimbursement tier migrations, and homecare protocol expansion trajectories.
The model holds under stable EU MDR enforcement and continued SNS biosimilar substitution mandates; deviation in AEMPS software documentation requirements or autonomous community procurement fragmentation would shift competitive positioning and revenue timing. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Antibiotics Market