
 Asian Sea Bass Market | 2026-2036
Asian Sea Bass Market Size, Share, and Industry Trends Forecast 2026-2036
Asian Sea Bass Market Outlook
Fresh fillet portion packs bundled with traceability QR codes is consolidating buyer preference across Asian retail channels. Mowi leverages its integrated feed-to-fillet operations to sustain quality consistency in Singapore and Hong Kong. Charoen Pokphand Foods anchors Thailand's domestic supply through vertically controlled hatchery networks. Barramundi Group differentiates via land-based recirculating aquaculture systems that compete on biosecurity credentials with traditional open-water farms.
Asian sea bass (Lates calcarifer), commonly called barramundi, is a euryhaline perciform fish farmed in brackish water ponds and marine cages, with harvest weights typically reaching 500–800 grams at 8–12 months under intensive conditions. Its firm, white flesh and high omega-3 content position it as a premium whitefish substitute for snapper and grouper in commercial kitchens. Fresh fillets command the dominant margin pool across product types due to shorter shelf-life premiums and chef preference for skin-on portions. Live fish maintains entrenched demand in Chinese and Vietnamese food service, where tank-to-table spectacle supports pricing power. Online platforms represent the fastest-growing distribution channel, bypassing wet-market intermediaries that traditionally controlled price discovery.
Vietnam's Ministry of Agriculture and Rural Development, Thailand's Department of Fisheries, and Indonesia's National Agency for Drug and Food Control each enforce distinct antibiotic residue limits that shape export eligibility and farm certification requirements. Compliance with these overlapping national standards forces producers to maintain multiple testing protocols or risk market access revocation. Stakeholders must monitor how escalating EU border inspection frequency for Vietnamese aquaculture reshapes investment priorities across Mekong Delta processing clusters.
Market Dynamics
Antibiotic residue compliance costs are restructuring capital allocation across Southeast Asian farming clusters, forcing producers to choose between retrofitting pond systems or exiting export channels entirely. Vietnam's tightened monitoring protocols have triggered a wave of biosecurity infrastructure spending that smaller operators cannot absorb.
Growth Catalysts
- Live-tank display programs:Restaurants across Ho Chi Minh City, Bangkok, and Jakarta deploy tank-to-table spectacle to capture premium pricing from freshness-signaling. These installations command menu premiums that offset higher facility capex.
- Traceability QR code bundling:Retail channel buyers in Singapore and Hong Kong now require fillet portion packs with embedded provenance data. This specification is consolidating supplier relationships around integrated feed-to-fillet operators.
- EU border inspection frequency escalation:Vietnamese processors face intensified scrutiny that rewards pre-certified operations. Compliance-ready exporters capture displaced volume from delisted competitors.
Market Restraints
- Fingerling supply concentration:Thailand's hatchery networks control genetic stock distribution across the Mekong Delta. This bottleneck limits farm expansion velocity independent of pond availability.
- Overlapping antibiotic residue limits:Vietnam's Ministry of Agriculture, Thailand's Department of Fisheries, and Indonesia's National Agency for Drug and Food Control enforce non-harmonized maximum residue levels. Producers must maintain parallel testing protocols or forfeit market access.
- Fresh fillet shelf-life compression:Premium whitefish substitutes including frozen pangasius and tilapia fillets extend distribution radius. This substitution pressure constrains pricing power in inland retail channels.
Strategic Opportunities
- Land-based recirculating aquaculture systems:Urban-adjacent production in Singapore and metropolitan Vietnam bypasses coastal land scarcity. These facilities compete on biosecurity credentials unavailable to open-water cage operations.
- Direct-to-consumer online platforms:E-commerce channels bypass wet-market intermediaries that historically controlled price discovery. This disintermediation captures margin previously extracted by layered wholesale networks.
- Omega-3 content certification:Nutritional labeling protocols create premium tiering for fillets meeting specific fatty acid thresholds. Health-positioned retail channels in Hong Kong and Taiwan absorb certified supply at structural premiums.
Industry Challenges
- Multi-jurisdiction compliance staffing:Export-oriented processors require personnel fluent in Vietnamese, Thai, and Indonesian regulatory filing requirements. Talent scarcity in this specialized function extends certification timelines.
- Cold chain integrity at pond-to-plate handoffs:Mekong Delta infrastructure gaps expose harvest-to-processing transit windows to temperature excursions. Capital deployment for insulated transport fleets competes with biosecurity retrofit spending.
- Genetic broodstock IP fragmentation:Proprietary strain development occurs across disconnected university and corporate research programs. Licensing complexity delays access to disease-resistant lines.
Report Scope
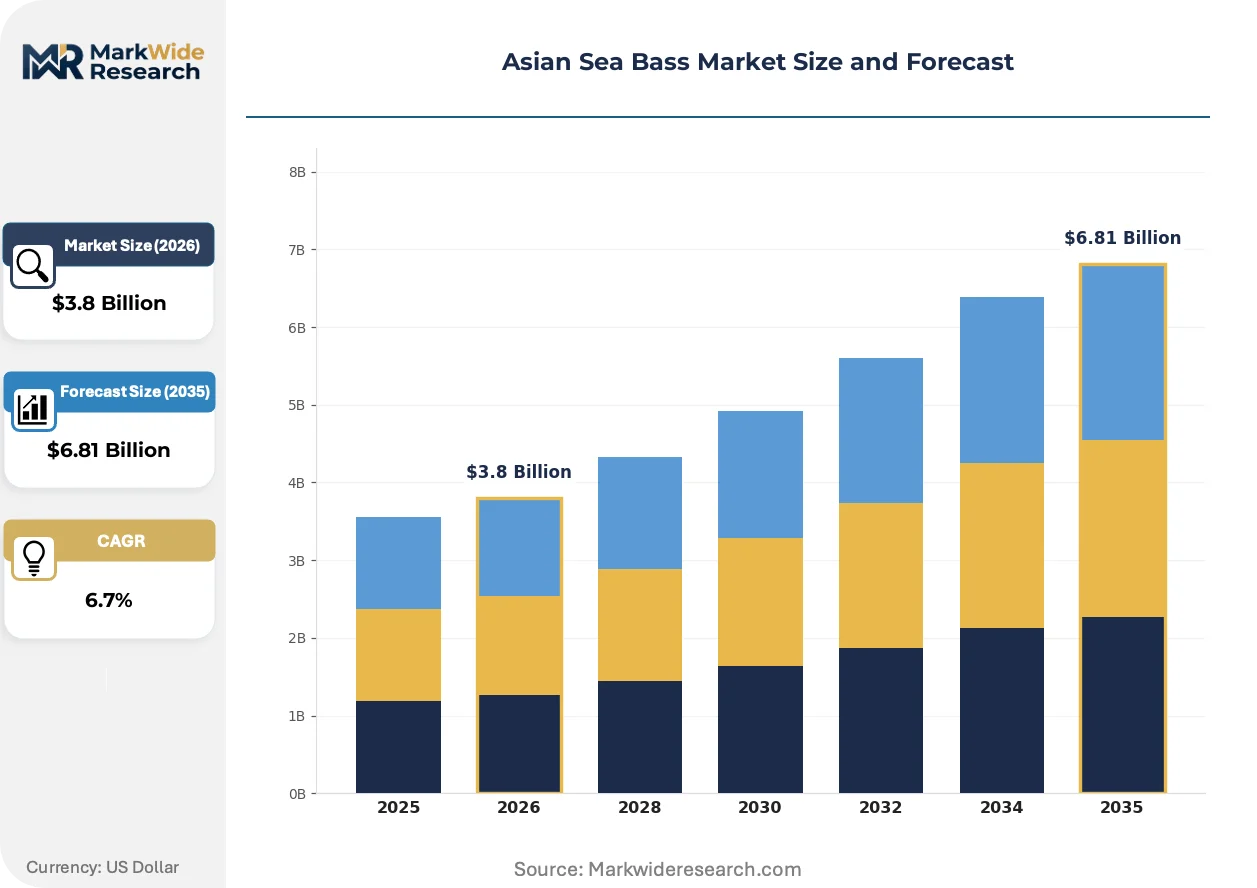
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asian Sea Bass Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Fish, Fresh Fillets, Frozen Fish, Processed Products Application: Food Service, Retail, Aquaculture, Exporting Distribution Channel: Direct Sales, Wholesale Markets, Supermarkets, Online Platforms End User: Restaurants, Households, Fish Markets, Industrial Consumers |
| Companies Covered | Marine Harvest, Cermaq Group, Thai Union Group, Grieg Seafood, Mowi, Charoen Pokphand Foods, Barramundi Group, Tassal Group, Australis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asian Sea Bass Market Strategic Shifts
Digital traceability infrastructure and closed-loop water treatment systems are compressing the distance between production origin and final buyer verification. These technologies are redrawing competitive boundaries between integrated operators and fragmented pond-based suppliers.
Automated feeding systems with integrated water quality sensors are integrating real-time biomass estimation into daily ration calculations. Intensive farms in Vietnam's An Giang and Dong Thap provinces deploy these platforms to reduce feed conversion ratios. The resulting cost structure compression is widening margin spreads between technology-adopted and conventional operations.
Thailand's Department of Fisheries has mandated electronic traceability documentation for all export-bound aquaculture products starting from hatchery origin. This regulatory requirement forces mid-scale processors to deploy cloud-based compliance platforms or exit EU-bound supply chains. Smallest operators are consolidating under larger exporters to access shared certification infrastructure.
Chef procurement patterns in Singapore and Hong Kong are rotating toward skin-on fillet specifications that signal processing freshness. Premium hotel and independent restaurant buyers now reject skinless portions regardless of price positioning. This specification shift is forcing processing plant reconfiguration investments across Mekong Delta clusters.
Asian Sea Bass Market Segmentation
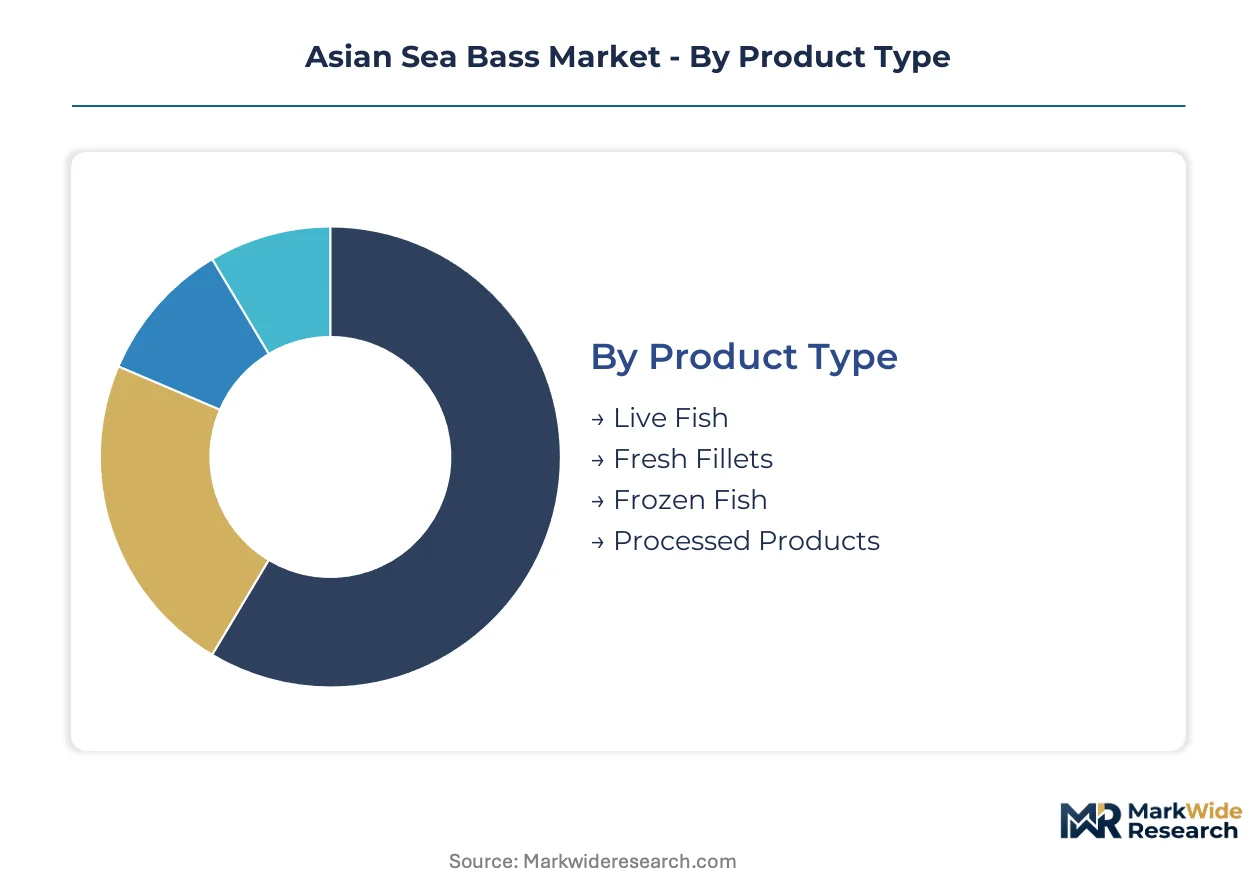
Product differentiation across freshness states and distribution channels determines margin capture in Asian sea bass supply chains. Each segment carries distinct cold chain requirements, regulatory exposure, and buyer concentration patterns that reshape producer investment priorities.
Product Type:
Freshness-state selection drives capital allocation between live-holding infrastructure and processing automation, with premium tiers commanding facility-specific upgrade cycles.
- Live Fish:Tank-to-table supply chains in Ho Chi Minh City and Bangkok restaurants require oxygenated transport systems and restaurant-side display installations. Chinese and Vietnamese food service buyers absorb the majority of live-harvest volume, where freshness spectacle supports menu pricing power unavailable to processed alternatives.
- Fresh Fillets:Skin-on portions with embedded traceability QR codes dominate Singapore and Hong Kong retail procurement. Chef preference for processing-fresh specifications is forcing Mekong Delta plants to reconfigure cutting lines and discard skinless production capacity.
- Frozen Fish:Extended distribution radius serves inland retail channels where cold storage infrastructure substitutes for proximity to coastal harvest zones.
- Processed Products:Value-added smoking and marination lines target export certification requirements in EU-bound supply chains.
Fresh fillets sit at the top of the volume ranking, with live fish climbing the fastest as restaurant display programs expand across Southeast Asian metropolitan cores.
Application:
End-use concentration shapes biosecurity compliance intensity, with export-facing channels absorbing the steepest certification cost burdens.
- Food Service:Live-tank installations in premium Vietnamese and Thai restaurants command freshness premiums that offset higher facility capex. Tank-to-table spectacle in Ho Chi Minh City and Bangkok properties differentiates against frozen-filament competitors.
- Retail:Traceability-bundled portion packs consolidate buyer relationships around integrated feed-to-fillet operators in Singapore and Hong Kong supermarket channels.
- Aquaculture:Broodstock and fingerling supply concentrates in Thailand's vertically controlled hatchery networks, limiting independent farm expansion velocity.
- Exporting:EU-bound shipments face intensified border inspection frequency that rewards pre-certified Vietnamese processors with displaced volume from delisted competitors.
Food service absorbs the dominant share of live-harvest volume, while retail channels gain share fastest through direct-to-consumer platform expansion.
Distribution Channel:
Channel selection determines margin retention versus intermediary extraction, with digital platforms compressing traditional wholesale layers.
- Direct Sales:Processor-to-restaurant contracts in Vietnam's Mekong Delta bypass wet-market intermediaries that historically controlled price discovery.
- Wholesale Markets:Traditional layered networks in Indonesian and Philippine supply chains extract margin through multiple handling stages before retail handoff.
- Supermarkets:Cold chain specifications in Singapore and Hong Kong retail require insulated transport fleets that compete with biosecurity retrofit spending for capital deployment.
- Online Platforms:E-commerce channels represent the steepest expansion trajectory, capturing margin previously extracted by wholesale intermediaries through disintermediated pond-to-consumer logistics.
Wholesale markets retain volume leadership in fragmented supply zones, while online platforms expand most quickly in metropolitan Vietnam and Singapore.
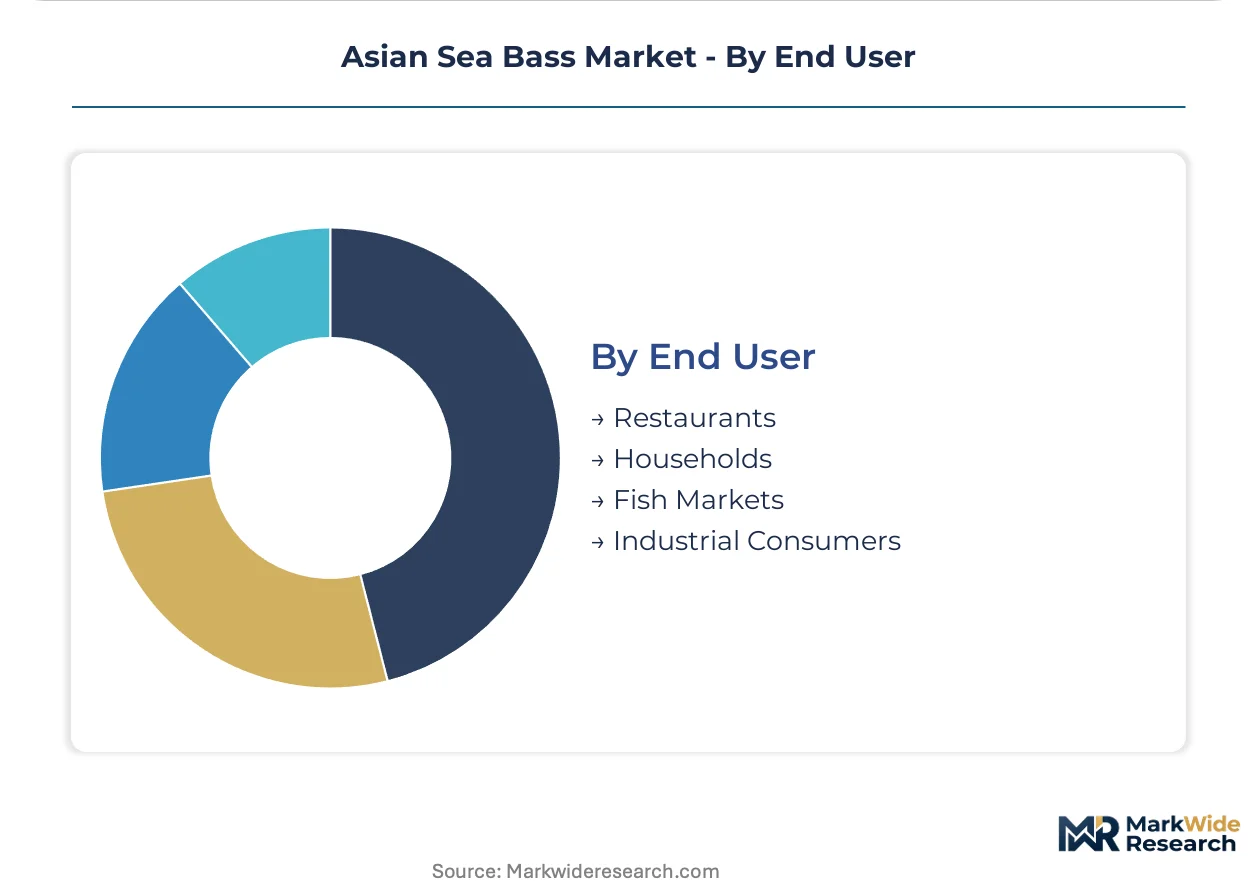
End User:
Buyer type dictates product-form specifications and freshness tolerance, with commercial kitchens absorbing higher per-unit prices for processing control.
- Restaurants:Premium hotel and independent buyers in Hong Kong and Singapore now reject skinless fillets regardless of price positioning, forcing plant reconfiguration investments.
- Households:Traceability-embedded retail packs in urban Vietnamese and Thai markets consolidate purchasing around branded fillet suppliers with provenance documentation.
- Fish Markets:Wet-market intermediaries in Indonesian and Philippine supply chains retain price discovery control in regions where cold chain gaps prevent direct-platform penetration.
- Industrial Consumers:Large-scale food manufacturers absorb frozen and processed volumes for further value-added transformation in export-oriented processing clusters.
Restaurants command the premium tier of live and fresh product pricing, with household direct purchasing gaining share fastest through platform-based disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian sea bass aquaculture originated in Thailand's brackish water pond systems during the 1970s before spreading to Vietnam's Mekong Delta and Indonesia's archipelagic coastlines. The industry now concentrates in four Southeast Asian production clusters where regulatory divergence and infrastructure investment patterns create distinct competitive terrains.
Vietnam
Live-tank restaurant programs in Ho Chi Minh City drive premium demand for oxygenated transport systems. The Ministry of Agriculture and Rural Development enforces tightened antibiotic residue monitoring protocols that force biosecurity retrofit spending across Mekong Delta processing clusters. An Giang and Dong Thap provinces host the deepest pond-to-plate cold chain infrastructure, where automated feeding platforms compress feed conversion ratios.
Thailand
Vertically controlled hatchery networks in Samut Sakhon and Chachoengsao provinces limit independent farm expansion velocity through genetic stock concentration. The Department of Fisheries mandates electronic traceability documentation for all export-bound aquaculture products starting from hatchery origin. Bangkok's food service sector absorbs dominant live-harvest volume through tank-to-table spectacle installations.
Indonesia
Wet-market intermediaries in Java and Sumatra retain price discovery control where cold chain gaps prevent direct-platform penetration. The National Agency for Drug and Food Control enforces distinct antibiotic residue limits that force parallel testing protocols for export-oriented processors. Batam and Bintan clusters face intensifying biosecurity compliance costs that restructure capital allocation toward retrofitting or exit.
Singapore
Urban-adjacent land-based recirculating aquaculture systems compete on biosecurity credentials unavailable to open-water cage operations. The Singapore Food Agency enforces strict import certification requirements that reward pre-certified Malaysian and Indonesian suppliers. Jurong and Lim Chu Kang host metropolitan production facilities that bypass coastal land scarcity through closed-loop water treatment systems.
Asian Sea Bass Market Competitive Environment
The competitive structure tilts toward integrated feed-to-fillet operators that control quality consistency across Singapore and Hong Kong retail channels. Three strategic archetypes dominate: vertically controlled hatchery networks that anchor genetic supply, land-based recirculating system specialists that compete on biosecurity credentials, and integrated multinationals that leverage backward integration into feed production. Dominant competitive moves include biosecurity infrastructure spending to capture displaced volume from delisted competitors, and direct-to-consumer platform expansion that bypasses wet-market intermediaries.
Among integrated multinationals, Mowi and Charoen Pokphand Foods occupy positions that exemplify feed-to-fillet control across premium retail channels. Mowi leverages integrated operations to sustain quality consistency in Singapore and Hong Kong supermarket procurement, while Charoen Pokphand Foods anchors Thailand's domestic supply through vertically controlled hatchery networks. Barramundi Group represents the land-based recirculating aquaculture archetype, competing on biosecurity credentials with traditional open-water farms in metropolitan Vietnam and Singapore.
| Leading Market Players |
|---|
| Marine Harvest |
| Cermaq Group |
| Thai Union Group |
| Grieg Seafood |
| Mowi |
| Charoen Pokphand Foods |
| Barramundi Group |
| Tassal Group |
| Australis |
| Others |
Value Chain & Pricing Dynamics
Skilled biosecurity technicians in Vietnam's Mekong Delta command wage premiums that compress margin spreads between antibiotic-compliant export tiers and domestic-market supply. Labor-cost differentials between certified processing clusters and conventional pond operations translate directly into three-tier pricing separation across Singapore and Hong Kong procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Asian sea bass transactions, with EU-certified fillets commanding spreads over domestic-market supply based on residue testing documentation and traceability bundling. Price differentiation rests on certification grade against Vietnam's tightened Ministry protocols and volume scale at harvest. Cost compression in standard-tier frozen fillets is intensifying because frozen pangasius substitutes extend distribution radius into inland channels. Industrial consumers and wet-market intermediaries exhibit highest price sensitivity, while premium hotel food service buyers reject skinless portions regardless of positioning.
Supply Chain Analysis
Single-source vulnerability sits with Thailand's vertically controlled hatchery networks in Samut Sakhon and Chachoengsao provinces, where genetic stock concentration limits farm expansion velocity independent of pond availability. Geographic supply concentration spans Vietnam, Thailand, and Indonesia, with Mekong Delta processing clusters drawing from An Giang and Dong Thap harvest zones. Raw material dependencies include specialized broodstock lines, formulated aquafeed, and oxygenated transport infrastructure. Tariff exposure runs through EU border inspection frequency escalation that rewards pre-certified Vietnamese processors. Distribution runs through layered wholesale networks in Indonesian and Philippine supply chains, with direct-to-consumer platforms gaining fastest share in metropolitan Vietnam and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where Thailand's Department of Fisheries electronic traceability mandate starting from hatchery origin forces mid-scale processors into cloud-based compliance platforms or exit.
For Market Incumbents: Deploy biosecurity infrastructure spending to capture displaced volume from delisted competitors facing EU inspection frequency escalation. Retrofit pond systems with automated feeding platforms and integrated water quality sensors to compress feed conversion ratios against technology-lagging operations. Charoen Pokphand Foods exemplifies hatchery-network control that anchors genetic supply against fingerling bottlenecks. For New Entrants and Emerging Players: Launch via direct-to-consumer online platforms that bypass wet-market intermediaries controlling price discovery in Indonesian and Philippine supply chains. Target metropolitan Vietnam and Singapore where cold chain gaps are narrowest and platform penetration faces lowest friction. White-space concentration sits with land-based recirculating aquaculture systems competing on biosecurity credentials unavailable to open-water cage operations. For Investors and Strategic Acquirers: Integrated feed-to-fillet operators are the most active acquirer in this space, consolidating backward integration into feed production and processing automation. Long-term viability favors assets with captive hatchery control and pre-certified EU export status. Watch for EU border inspection delisting announcements as volume displacement signals.| Strategic Initiative | Industry Significance |
|---|---|
| Biosecurity Infrastructure Retrofit | EU pre-certification captures volume from delisted Mekong Delta competitors. |
| Direct-to-Consumer Platform Launch | E-commerce disintermediation recaptures margin from layered wholesale networks. |
| Land-Based Recirculating System Deployment | Urban-adjacent production bypasses coastal land scarcity in Singapore. |
| Electronic Traceability Documentation | Thailand's Department of Fisheries mandate forces cloud platform adoption. |
| Omega-3 Content Certification | Nutritional labeling creates premium tiering for Hong Kong health-positioned retail. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hatchery network managers, Mekong Delta processing plant operators, Singapore supermarket category buyers, and Vietnam's Ministry of Agriculture compliance officers with secondary validation. Bottom-up triangulation drew from customs export records, Thailand's Department of Fisheries certification databases, and EU Rapid Alert System for Food and Feed notifications, while top-down cross-checks referenced aquaculture production statistics and cold chain infrastructure investment disclosures.
Segment-weighting approaches modeled volume and value across product type, application, distribution channel, and end user dimensions throughout the forecast period. CAGRs were derived from trajectory analysis of historical production volumes, regulatory enforcement intensity, and channel shift patterns. Industry-specific forecast inputs included antibiotic residue testing compliance rates and live-tank restaurant program expansion velocity across Ho Chi Minh City and Bangkok metropolitan cores.
Several conditions sit outside the modeled scope, including unforeseen disease outbreaks affecting broodstock lines, abrupt harmonization of antibiotic residue limits across Vietnam, Thailand, and Indonesia, and geopolitical disruptions to Mekong Delta cold chain infrastructure. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
North America Frozen Seafood Market
Seafood
Lobster Market
Seafood
Krill Meal Market
Seafood
Frozen Seafood Market
Seafood
Japan Frozen Seafood Market
Seafood
Sea Bream Market
Seafood
Striped Bass Market
Seafood
Global Shrimp Market
Seafood
Fish Protein Market
Seafood
Tinned Fish Market
Seafood
Sea Biscuits Market
Seafood
Global Seafood Market
Seafood
Mussels Market
Seafood
Oyster Market
Seafood
Cod Fish Market
Seafood
Europe Dried Scallop Market