
 Global Shrimp Market | 2026-2036
Global Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shrimp Market Outlook
Modular value-added configurations—breaded, pre-cooked, and seasoned shrimp—is restructuring buyer choice across retail and food service channels. Thai Union Group PCL leverages its integrated aquaculture-to-retail pipeline to sustain volume leadership in processed formats. Charoen Pokphand Foods PCL anchors Southeast Asian supply through captive hatchery networks. Clearwater Seafoods differentiates via Arctic wild-caught positioning in premium North American retail.
Shrimp are decapod crustaceans harvested from marine and aquaculture environments, typically processed at minus eighteen degrees Celsius for frozen distribution and graded by count per pound for commercial trade. Their primary commercial purpose centers on protein supply for human consumption across retail, restaurant, and industrial food manufacturing channels. Raw shrimp occupies the largest volume position, though breaded and pre-cooked segments capture disproportionate margin pools in developed markets. Restaurant supply channels show the fastest structural expansion as post-pandemic food service rebuilds inventory and menu breadth.
The EU's IUU Fishing Regulation and the US FDA Seafood HACCP framework shape import compliance costs, while Thailand's Department of Fisheries enforces domestic aquaculture certification that governs export eligibility. These layered requirements elevate traceability investment but also filter uncertified suppliers from premium channel access. Stakeholders must monitor evolving antibiotic residue protocols and cold-chain integrity standards as determinants of market access and buyer contract terms.
Market Dynamics
The EU's IUU Fishing Regulation is compressing import eligibility windows and forcing traceability infrastructure investments that filter uncertified suppliers from premium channel access. Food service operators simultaneously expand value-added shrimp menu configurations, pulling processing capacity toward breaded and pre-cooked formats.
Growth Catalysts
- EU IUU Fishing Regulation:Mandatory catch documentation schemes for imported seafood create compliance barriers that certified Vietnamese and Thai processors convert into contract premiums with EU retail chains.
- Food service rebuild:Post-pandemic restaurant inventory restocking and menu breadth expansion drive disproportionate demand for IQF and value-added shrimp formats across North American and European food service distributors.
- Recirculating Aquaculture Systems:Closed-loop RAS technology adoption in indoor shrimp farming is reducing disease pressure and enabling land-based production near major US and European consumption centers.
Market Restraints
- Feed cost volatility:Fishmeal and soy protein concentrate prices fluctuate with South American soybean harvests and Peruvian anchovy quotas, squeezing farm-gate margins for intensive aquaculture operations.
- Mekong Delta concentration risk:Processing and primary farming clusters in Vietnam's delta region face simultaneous climate vulnerability, salinity intrusion, and disease outbreak propagation that disrupts just-in-time supply to EU and US buyers.
- Antibiotic residue detection limits:FDA Seafood HACCP and EU RASFF alert systems enforce tightening chloramphenicol and nitrofuran thresholds that trigger automatic border rejections without appeal pathways.
Strategic Opportunities
- India's east coast expansion:Andhra Pradesh and Odisha shrimp farming zones remain underpenetrated in value-added processing, offering first-mover positioning for EU-compliant integrated operations.
- Eco-certification premiums:Aquaculture Stewardship Council and Best Aquaculture Practice labels command shelf price separation in German and Dutch retail, with compliance costs recoverable through contract duration.
- Direct-to-food service platforms:Digital procurement portals connecting Vietnamese processing clusters to US restaurant groups are disintermediating traditional importer-distributor layers and compressing landed cost structures.
Industry Challenges
- Traceability systems integration:Blockchain and ERP platform deployment across multi-tier supplier networks requires 18-24 month implementation timelines that delay EU market re-entry for reformatted operations.
- Cold-chain integrity maintenance:Minus eighteen degrees Celsius continuous temperature documentation from farm gate to retail shelf demands capital investment in monitoring hardware and backup power systems across Southeast Asian logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shrimp Market |
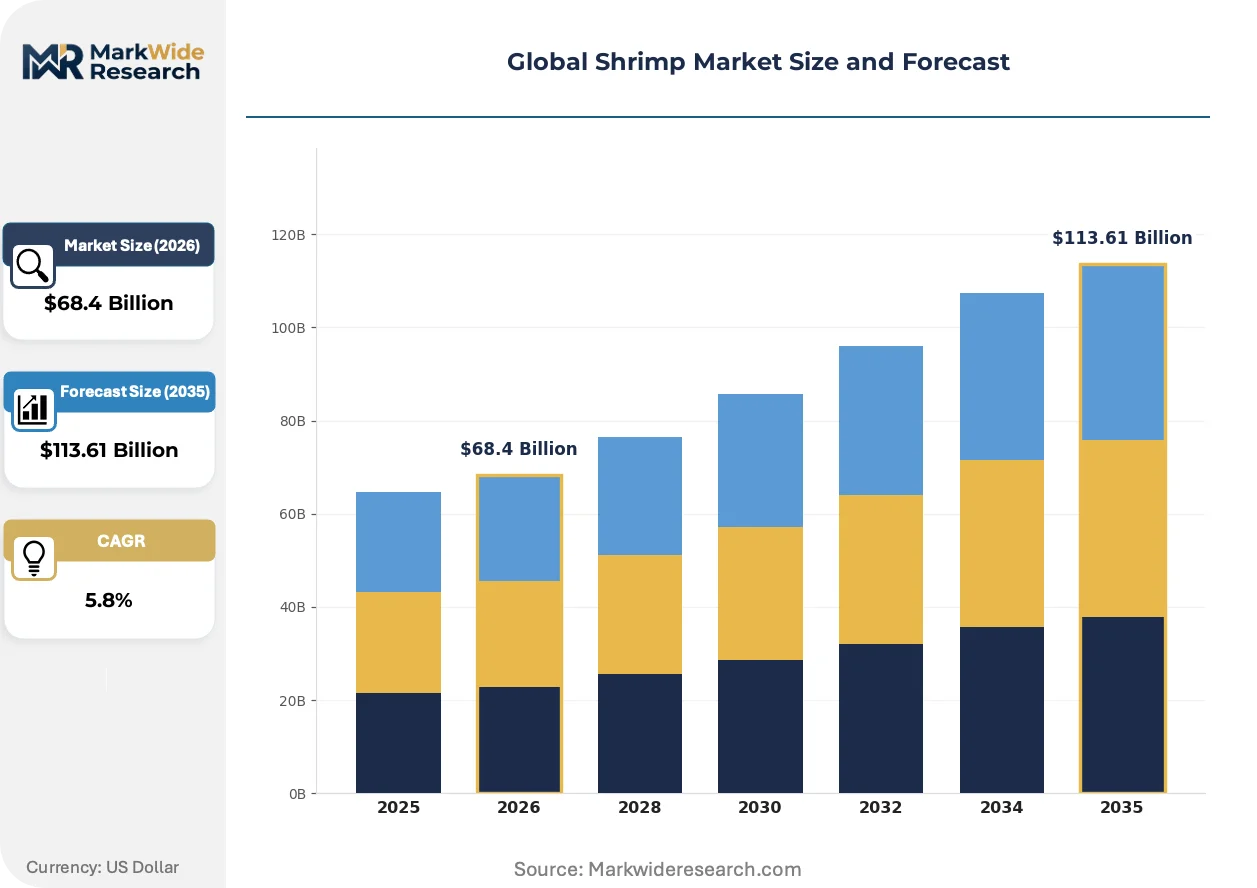
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Shrimp, Cooked Shrimp, Breaded Shrimp, Peeled Shrimp Distribution Channel: Supermarkets, Online Retail, Fish Markets, Restaurant Supply Size: Small, Medium, Large, Extra Large End User: Households, Restaurants, Food Service, Exporters |
| Companies Covered | Surapon Foods Public Company Limited, Mazzetta Company LLC, Thai Union Group PCL, Nordic Seafood A/S, Aqua Star, Clearwater Seafoods, Charoen Pokphand Foods PCL, Avanti Feeds Limited, High Liner Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shrimp Market Strategic Shifts
Automation and biotechnology are restructuring production economics while regulatory compliance technologies reshape competitive access. These intersecting forces favor capital-intensive operators with integrated quality control systems.
Gene editing for disease resistance is converging with selective breeding programs to shorten grow-out cycles and reduce mortality from early mortality syndrome and white spot syndrome virus. Major breeding operations in Thailand and Indonesia are deploying genomic selection tools that compress generation intervals. This biotechnology convergence is enabling farm density increases that were previously uneconomical due to disease risk.
The EU's Corporate Sustainability Reporting Directive expands due diligence obligations for seafood importers, requiring documented supplier audits and deforestation-free supply chain attestations. Large EU retail consortiums are now mandating third-party verified origin documentation as a contract precondition. Frozen shrimp consignments lacking digital traceability metadata face automatic downstream exclusion from central procurement tenders.
Restaurant groups are consolidating supplier relationships and unbundling specification-grade procurement from broadline distribution. US casual dining chains now contract directly with Ecuadorian and Indian processors for custom size-graded lots, bypassing traditional seafood distributors. This procurement consolidation concentrates volume with integrated processors capable of lot-level customization and is most visible in the US Southeast and Midwest regional chain expansions.
Global Shrimp Market Segmentation
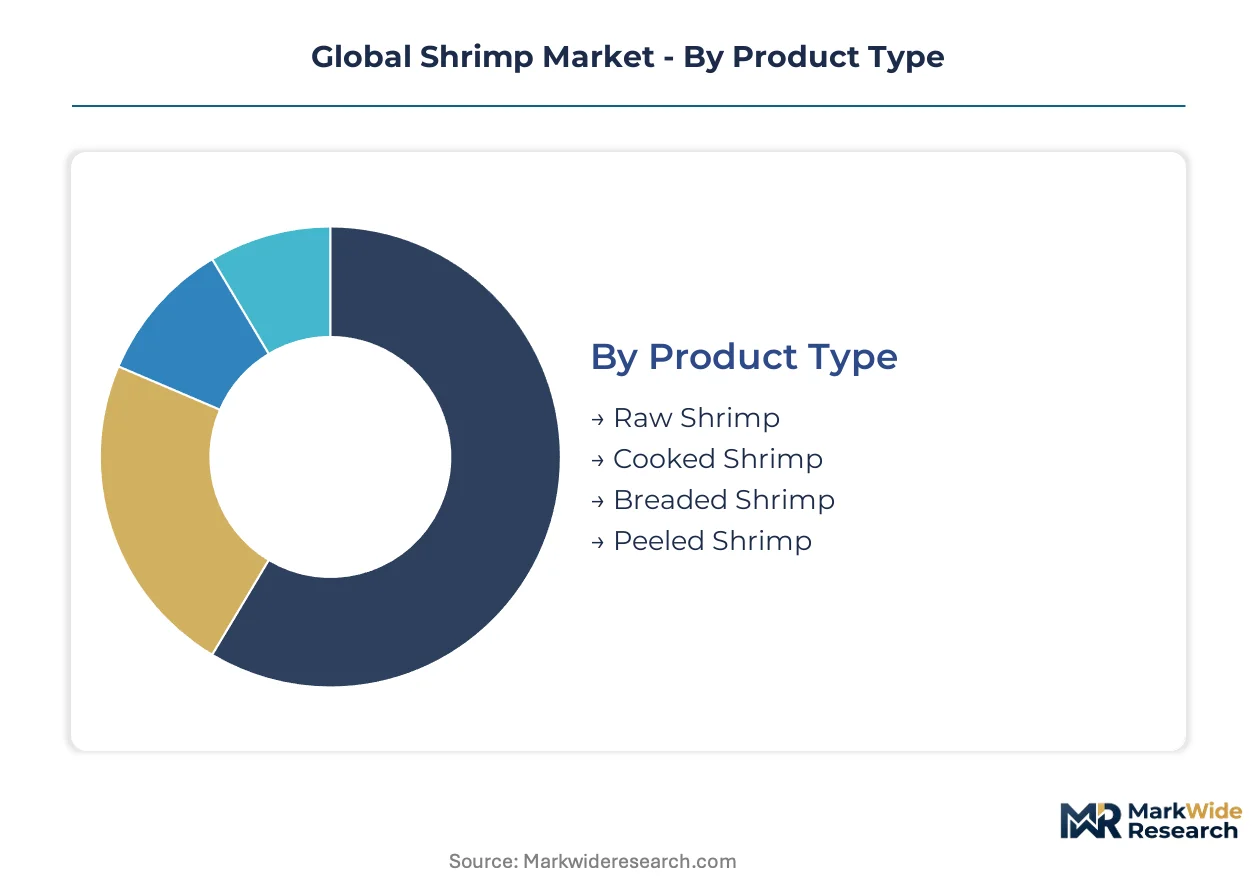
Shrimp market segmentation reflects divergent processing intensity and channel economics. Product format determines margin capture, while distribution channel shapes compliance burden and customer relationship depth.
Product Type:
Customization intensity spans from commodity raw material to fully configured ready-to-cook formats, with each step up the value ladder demanding specialized equipment and cold-chain discipline.
- Raw Shrimp:Unprocessed whole or head-on product frozen at minus eighteen degrees Celsius immediately post-harvest. Demand concentrates in Vietnamese and Thai processing clusters serving EU retail chains, constrained by EU IUU Fishing Regulation documentation requirements and antibiotic residue testing protocols.
- Cooked Shrimp:Pre-cooked product blast-chilled and individually quick frozen for food service rethermalization. US restaurant groups and European contract caterers drive procurement, prioritizing lot-level traceability and consistent tail-to-weight ratios for portion control.
- Breaded Shrimp:Value-added format with panko or tempura coating applied pre-freeze.
- Peeled Shrimp:Deveined and shell-removed product requiring labor-intensive processing.
Most installed capacity flows through Raw Shrimp. Expansion is steepest in Cooked Shrimp.
Distribution Channel:
Channel selection dictates working capital cycles, with direct food service contracts stretching payment terms against supermarket spot purchasing.
- Supermarkets:Centralized retail procurement with private-label specifications and shelf-life minimums. German and Dutch retail consortiums mandate Aquaculture Stewardship Council certification, filtering supplier pools to integrated Vietnamese and Ecuadorian processors with traceability infrastructure.
- Restaurant Supply:Direct processor-to-operator relationships bypassing traditional importer-distributor layers. US Southeast and Midwest casual dining chains contract for custom size-graded lots with specification-grade documentation.
- Online Retail:Direct-to-consumer fulfillment with frozen last-mile logistics.
- Fish Markets:Traditional wet-market channels with freshness-dependent pricing.
Volume concentrates in Supermarkets. Margin expansion is fastest in Restaurant Supply.
Size:
Count-per-pound grading creates tiered price bands that align with end-use portion economics and presentation requirements.
- Large:Twenty-one to twenty-five count per pound, the standard for premium restaurant entrees and retail tray packs. US food service distributors and Japanese import houses dominate procurement, with pricing indexed to uniform sizing and minimal broken pieces.
- Extra Large:Sixteen to twenty count per pound, commanding presentation premiums in white-tablecloth dining and high-end retail. Supply concentrates in Ecuadorian and Indian farming zones with extended grow-out cycles.
- Medium:Twenty-six to thirty count per pound for casual dining and ingredient applications.
- Small:Thirty-one to forty count per pound for processed foods and bait.
Harvest volume peaks in Medium grades. Price appreciation is strongest in Extra Large.
End User:
User type determines specification complexity, with exporters and food service operators imposing the most stringent documentation and customization requirements.
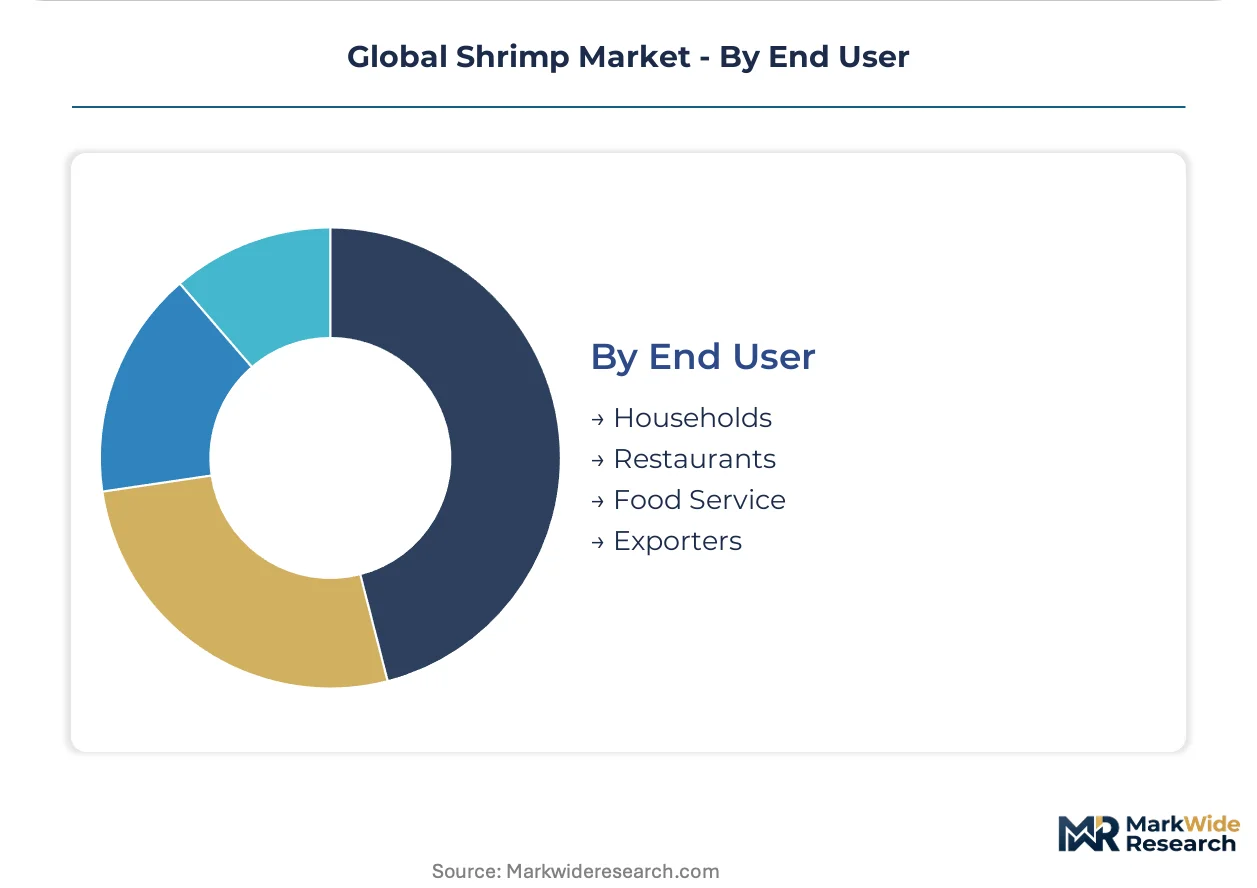
- Restaurants:Full-service and casual dining operators specifying size-graded lots with consistent cook yields and plate coverage. Post-pandemic menu breadth expansion is pulling inventory toward IQF and value-added formats with reliable supply continuity.
- Exporters:Re-export traders and regional distributors requiring origin documentation, health certificates, and EU-compliant traceability metadata. EU RASFF alert system vigilance shapes supplier selection and testing protocols.
- Households:Retail consumers purchasing tray packs and bulk frozen bags.
- Food Service:Institutional caterers and contract feeders with cost-driven procurement.
Contract volume concentrates with Exporters. Demand growth is most rapid in Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial shrimp aquaculture scaled from Southeast Asian coastal ponds in the 1980s into integrated supply chains serving EU and US retail. Today production concentrates in four countries commanding distinct regulatory and channel positions.
Vietnam
Mekong Delta processing clusters supply IQF raw shrimp to German and Dutch retail consortiums. The country's Department of Fisheries enforces aquaculture certification governing EU export eligibility. Cần Thơ and Bạc Liêu provinces host integrated operations investing in blockchain traceability to satisfy EU IUU Fishing Regulation documentation requirements.
Thailand
Bangkok-based processors dominate value-added breaded and pre-cooked formats for North American food service. Thai Union Group PCL anchors an integrated pipeline from captive hatcheries through retail distribution. Samut Sakhon and Surat Thani farming zones deploy genomic selection tools to compress grow-out cycles against early mortality syndrome pressure.
India
Andhra Pradesh and Odisha east coast zones remain underpenetrated in value-added processing despite expanding farm output. The Marine Products Export Development Authority coordinates EU-compliant certification for processors targeting German retail. Visakhapatnam and Bhimavaram clusters are attracting first-mover integrated operations seeking contract premiums.
United States
Domestic demand concentrates in Gulf Coast and Southeast regional restaurant chains specifying custom size-graded lots. FDA Seafood HACCP frameworks shape import compliance costs for Thai and Vietnamese suppliers. Texas and Florida distributors are consolidating procurement relationships directly with Ecuadorian processors, bypassing traditional importer layers.
Ecuador
Guayaquil and El Oro province farming zones specialize in extra-large count grades for premium US food service and Japanese import houses. The National Chamber of Aquaculture coordinates traceability standards aligned with EU RASFF alert system vigilance. Processing clusters are expanding cooked and breaded capacity to capture margin pools in post-pandemic restaurant rebuild.
Global Shrimp Market Competitive Environment
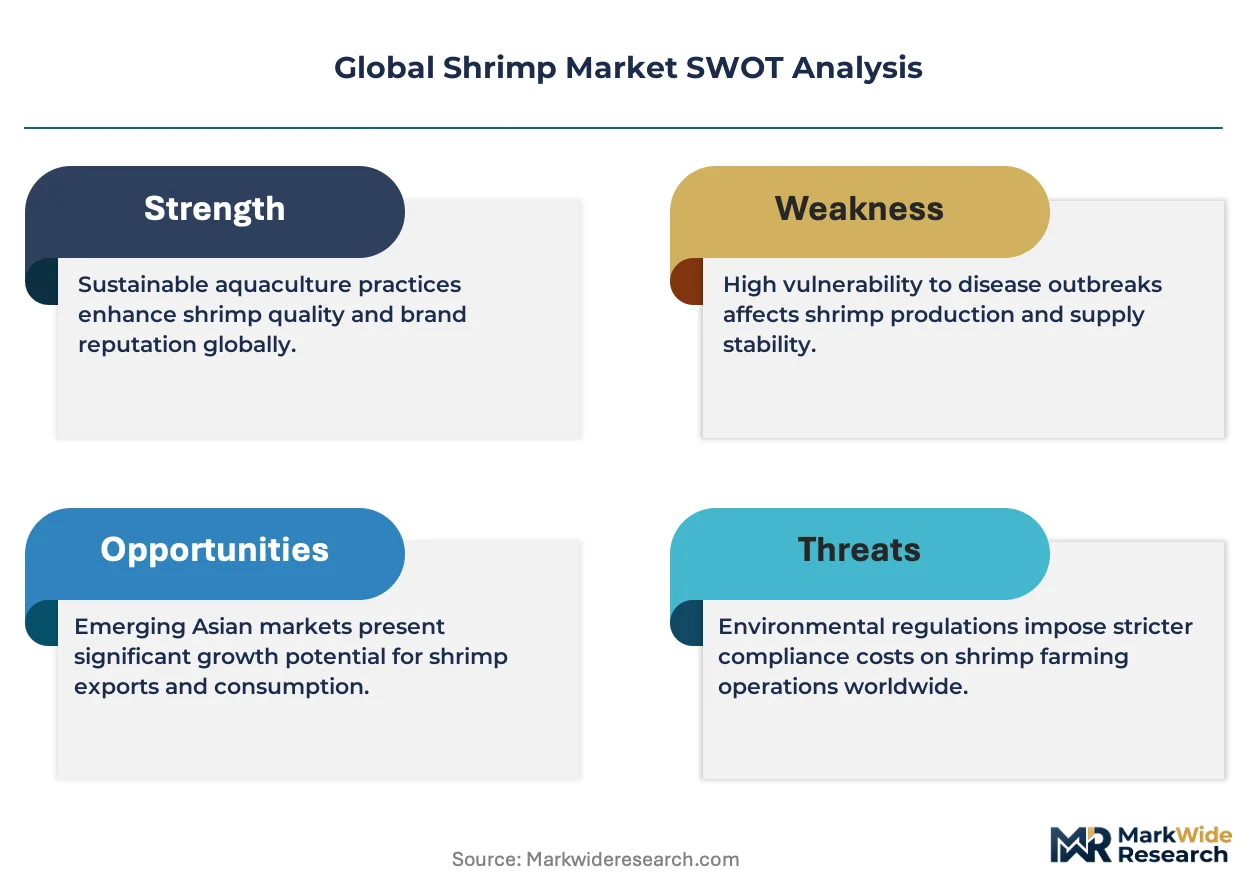
Premium-margin players sit above commodity-margin players across certification and traceability infrastructure. The vendor base stratifies between integrated aquaculture-to-retail operators, captive hatchery networks, and Arctic wild-caught specialists. Three archetypes dominate: vertically integrated Southeast Asian conglomerates with retail distribution control; North American and European processors with food service customization capabilities; and premium-positioned wild-caught operators with origin differentiation. Competitive moves concentrate on direct-to-restaurant procurement consolidation and RAS technology licensing for land-based production near major consumption centers.
Within the integrated conglomerate tier, Thai Union Group PCL and Charoen Pokphand Foods PCL exemplify Southeast Asian operators with captive supply chains spanning hatchery through retail shelf. Clearwater Seafoods occupies a position representing Arctic wild-caught specialists commanding premium positioning in North American retail through origin differentiation and cold-chain integrity documentation.
| Leading Market Players |
|---|
| Surapon Foods Public Company Limited |
| Mazzetta Company LLC |
| Thai Union Group PCL |
| Nordic Seafood A/S |
| Aqua Star |
| Clearwater Seafoods |
| Charoen Pokphand Foods PCL |
| Avanti Feeds Limited |
| High Liner Foods |
| Others |
Value Chain & Pricing Dynamics
EU retail consortiums in Germany and the Netherlands anchor procurement volume and impose contract-based long-term offtake structures with ASC-certified Vietnamese and Ecuadorian processors. These buyers leverage consolidated purchasing power to extract specification-grade compliance at fixed-price premiums, while Mekong Delta suppliers absorb feed cost volatility to maintain shelf placement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASC-certified IQF raw shrimp from commodity bulk grades and value-added breaded formats. Price differentiation hinges on certification grade and cold-chain documentation completeness, with EU-compliant traceability metadata commanding contract premiums. Pricing pressure stems from fishmeal and soy protein concentrate cost spikes in South American supply. Food service distributors show least price sensitivity for custom size-graded lots, while Asian wet-market traders drive spot-price volatility.
Supply Chain Analysis
EU IUU Fishing Regulation certification gating filters supplier pools to integrated Vietnamese, Thai, and Ecuadorian operators with blockchain traceability infrastructure. Raw material flows draw from Peruvian anchovy fisheries for fishmeal, Brazilian soybean harvests for protein concentrate, and domestic hatchery networks for post-larvae stock. Single-source vulnerability concentrates in Mekong Delta processing clusters facing salinity intrusion and disease outbreak propagation. Distribution runs through cold-chain logistics networks maintaining minus eighteen degrees Celsius from farm gate to retail shelf.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in shrimp processing rests on automation-driven cost compression in breaded and pre-cooked formats, alongside premium-tier capture via ASC certification in German and Dutch retail.
For Market Incumbents: Hedge against Mekong Delta concentration risk by diversifying processing capacity into India's Andhra Pradesh and Odisha zones with EU-compliant integrated operations. Reinforce cold-chain integrity documentation to preempt EU RASFF alert system exclusions. Defensive moves should prioritize captive hatchery network expansion and direct-to-food service platform development bypassing traditional importer-distributor layers.
For New Entrants and Emerging Players: Food service procurement portals represent the most penetrable channel for disintermediating landed cost structures. White-space targets include RAS technology licensing for land-based production near US consumption centers and value-added processing capacity in underpenetrated Indian east coast zones. Go-to-market positioning should emphasize lot-level customization capabilities for US Southeast and Midwest casual dining chains.
For Investors and Strategic Acquirers: Integrated aquaculture-to-retail conglomerates are the most active acquirer in this space, consolidating captive supply chains from hatchery through retail distribution. Long-term viability favors operations with genomic selection breeding programs and traceability infrastructure recoverable through contract duration premiums. Acquisition target archetypes include ASC-certified processors with EU retail shelf placement and RAS technology platforms. The signal to watch is FDA antibiotic residue threshold tightening triggering automatic border rejections.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | EU IUU Fishing Regulation compliance enables contract premiums with German retail consortiums. |
| RAS Technology Licensing | Land-based production near US consumption centers reduces disease pressure and logistics costs. |
| Direct-to-Food Service Platforms | Digital procurement portals compress landed costs for US restaurant group contracts. |
| Genomic Selection Breeding Programs | Thai and Indonesian operations compress grow-out cycles against early mortality syndrome. |
| ASC Certification Investment | Shelf price separation in Dutch retail recovers compliance costs through contract duration. |
Study Parameters
Multiple input streams — processor procurement directors, EU retail category buyers, aquaculture farm managers, and cold-chain logistics operators — were reconciled against customs trade data, FDA Seafood HACCP enforcement records, EU RASFF alert system databases, and ASC certification registries. Primary interviews with Vietnamese and Thai processing executives, German retail consortium procurement leads, and US food service distribution specialists were validated through secondary sources including Marine Products Export Development Authority filings and National Chamber of Aquaculture traceability standards. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Data-stream reconciliation across product type, distribution channel, size grade, and end-user segmentation generated volume and value trajectories over the projection horizon. CAGRs were derived from trend extrapolation anchored in historical trade flow analysis and regulatory compliance cost modeling. Industry-specific forecast inputs incorporated fishmeal price volatility indices, EU Corporate Sustainability Reporting Directive implementation timelines, and post-pandemic restaurant inventory restocking patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to antibiotic residue protocol shifts, climate vulnerability in Mekong Delta farming zones, and RAS technology cost curves. A model refresh is warranted upon material change in EU IUU Fishing Regulation enforcement intensity or FDA Seafood HACCP threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Sea Bream Market
Seafood
United States Plant-Based Seafood Market
Seafood
Surimi by-Product Market
Seafood
Mussels Market
Seafood
Crustacean Market
Seafood
Wild Pollock Market
Seafood
Groundfish Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
GCC Seafood Market
Seafood
Japan Frozen Seafood Market
Seafood
Milkfish Market
Seafood
North America Salmon Market
Seafood
United States Seafood Market
Seafood
Salmon Market
Seafood
Cod Fish Market
Seafood
Tuna Fish Market