
 Krill Meal Market | 2026-2036
Krill Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Krill Meal Market Outlook
Precision-targeted enzymatic hydrolysis is rewriting protein recovery yields from Antarctic krill biomass, enabling higher amino acid density in finished meal products. Aker BioMarine leverages proprietary Eco-Harvesting technology to sustain its Antarctic supply chain dominance. Rimfrost anchors its competitive position through Norwegian vertical integration from vessel to processing plant. TripleNine Group competes via Danish North Atlantic sourcing networks that bypass Antarctic quota pressures entirely.
Krill meal is a dried, defatted marine protein product derived from Euphausia superba, typically containing 50-65% crude protein and 8-12% residual lipids including omega-3 phospholipids, manufactured through onboard catch processing followed by land-based drying and solvent extraction. Its primary commercial purpose centers on high-performance aquaculture diets where palatability enhancement and growth promotion justify premium inclusion rates over fishmeal alternatives. The powder segment leads volume throughput due to superior blending characteristics in extruded salmon and shrimp feeds, while the nutraceuticals end-user channel captures the fastest value growth as human-grade phospholipid extraction creates dual-revenue streams from single harvests. Bulk container packaging dominates B2B aquaculture procurement, though sachet formats are gaining traction in specialty pet food channels where portion control commands retail premiums.
The Commission for the Conservation of Antarctic Marine Living Resources enforces ecosystem-based catch limits that directly constrain raw material access for Southern Ocean harvesters, while the Norwegian Food Safety Authority and South Korea's Ministry of Oceans and Fisheries impose residue testing protocols that shape export eligibility for processed meal. These overlapping regulatory frameworks elevate compliance costs for new entrants and consolidate advantage among established vertically integrated operators with dedicated quality laboratories. Stakeholders must monitor quota negotiation outcomes and alternative protein substitution thresholds in salmonid diet formulations to anticipate demand inflection points before they compress margin structures.
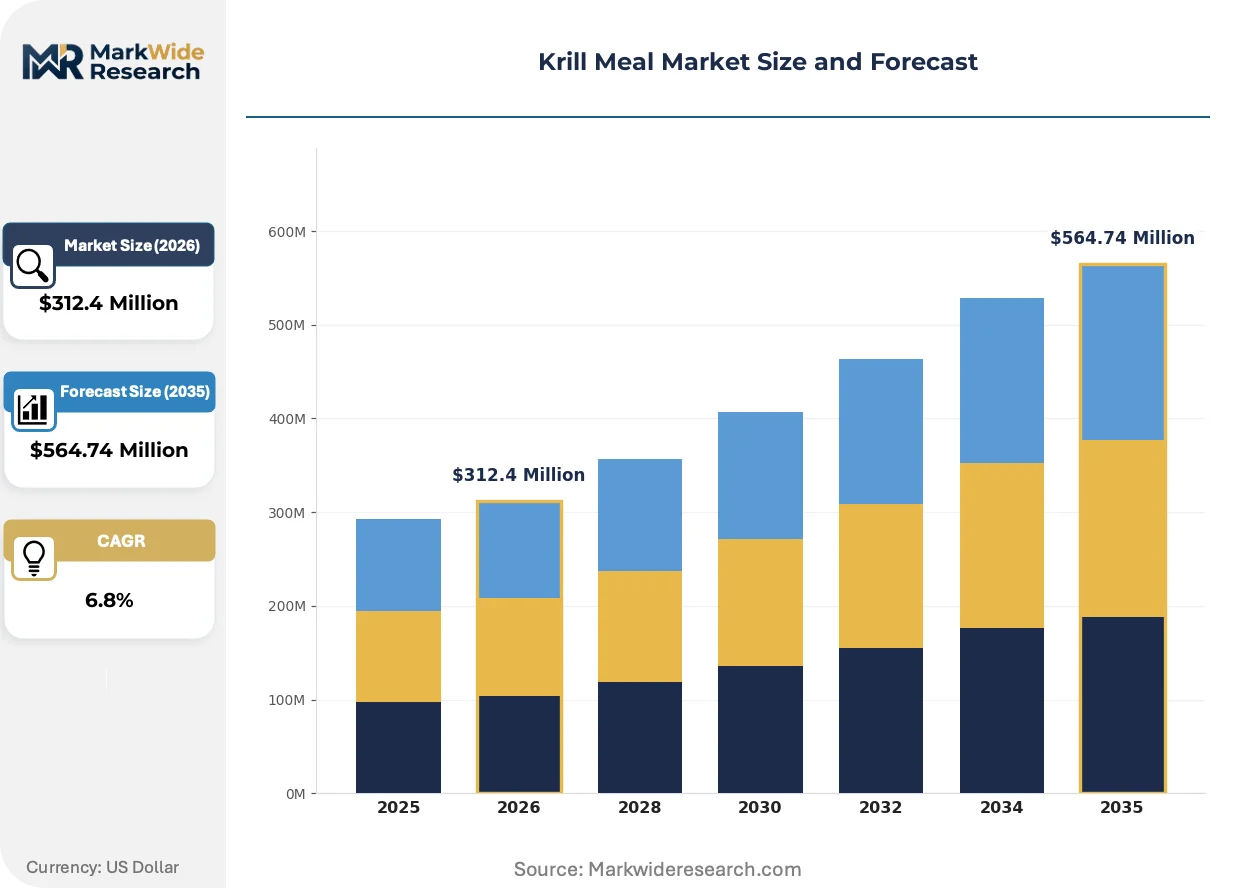
Market Dynamics
Antarctic krill biomass quotas enforced by the Commission for the Conservation of Antarctic Marine Living Resources are compressing raw material flows and forcing procurement networks toward Norwegian and South Korean processing infrastructure.
Growth Catalysts
- CCAMLR ecosystem-based management:Norwegian and South Korean processors with dedicated quality laboratories gain export eligibility advantages under residue testing protocols imposed by the Norwegian Food Safety Authority and South Korea's Ministry of Oceans and Fisheries.
- Enzymatic hydrolysis advancement:Precision-targeted protein recovery methods are deepening amino acid density in finished meal products for high-performance aquaculture diets.
- Salmonid diet formulation evolution:Marine ingredient substitution thresholds in aquafeed are redirecting demand toward krill-derived proteins as sustainability scrutiny tightens on conventional fishmeal.
Market Restraints
- Antarctic quota compression:CCAMLR catch limits directly constrain Southern Ocean harvester access and elevate raw material competition among processors.
- Input cost volatility:Fuel and vessel maintenance expenses for Antarctic expedition fleets fluctuate with polar logistics windows.
- Plant protein substitution:Soy and pea protein concentrates are displacing marine meals in lower-specification aquafeed formulations.
Strategic Opportunities
- Human-grade phospholipid extraction:Dual-revenue stream creation from single harvests through nutraceuticals channel development.
- Specialty pet food sachet formats:Portion-controlled retail packaging commands premium pricing in companion animal nutrition.
- North Atlantic sourcing bypass:Norwegian and Danish North Atlantic networks circumvent Antarctic quota pressures entirely.
Industry Challenges
- Polar logistics specialization:Crew training for Antarctic ice-class vessel operations requires extended certification timelines.
- Onboard processing integration:Catch-to-meal workflow optimization demands capital-intensive equipment retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Krill Meal Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Oil, Supplements End User: Aquaculture, Animal Feed, Pet Food, Nutraceuticals Packaging Type: Bags, Bulk Containers, Tubs, Sachets Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Shandong Luhua Group Co. Ltd., TripleNine Group, Orkla Group, Rimfrost, KD Pharma Group, Daesang Corporation, Aker BioMarine, Neptune Krill, BioMar Group A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Krill Meal Market Strategic Shifts
Processing technology advancement and regulatory geography fragmentation are redrawing competitive boundaries in krill meal supply chains. Value capture is shifting toward vertically integrated operators with captive laboratory infrastructure.
Sensor-integrated catch monitoring systems are digitizing biomass assessment precision for Antarctic fleet operators. Norwegian processors deploying these platforms achieve real-time quota compliance verification. The technology is digitizing documentation workflows for CCAMLR reporting requirements and compressing audit preparation cycles.
EU Green Deal sustainability disclosure mandates are tightening traceability requirements for marine ingredients entering European aquafeed supply chains. Norwegian and South Korean exporters must now maintain chain-of-custody documentation from vessel through processing plant. Salmon feed manufacturers in Norway and Scotland are responding by consolidating supplier relationships toward integrated operators with certified quality laboratories.
Direct processor-to-farm contracting is displacing traditional commodity trading structures in salmon aquaculture procurement. Large Norwegian and Chilean salmon producers are negotiating multi-year supply agreements with krill meal processors. This pattern is most visible in Norway's fjord farming regions where feed cost predictability outweighs spot market flexibility.
Krill Meal Market Segmentation
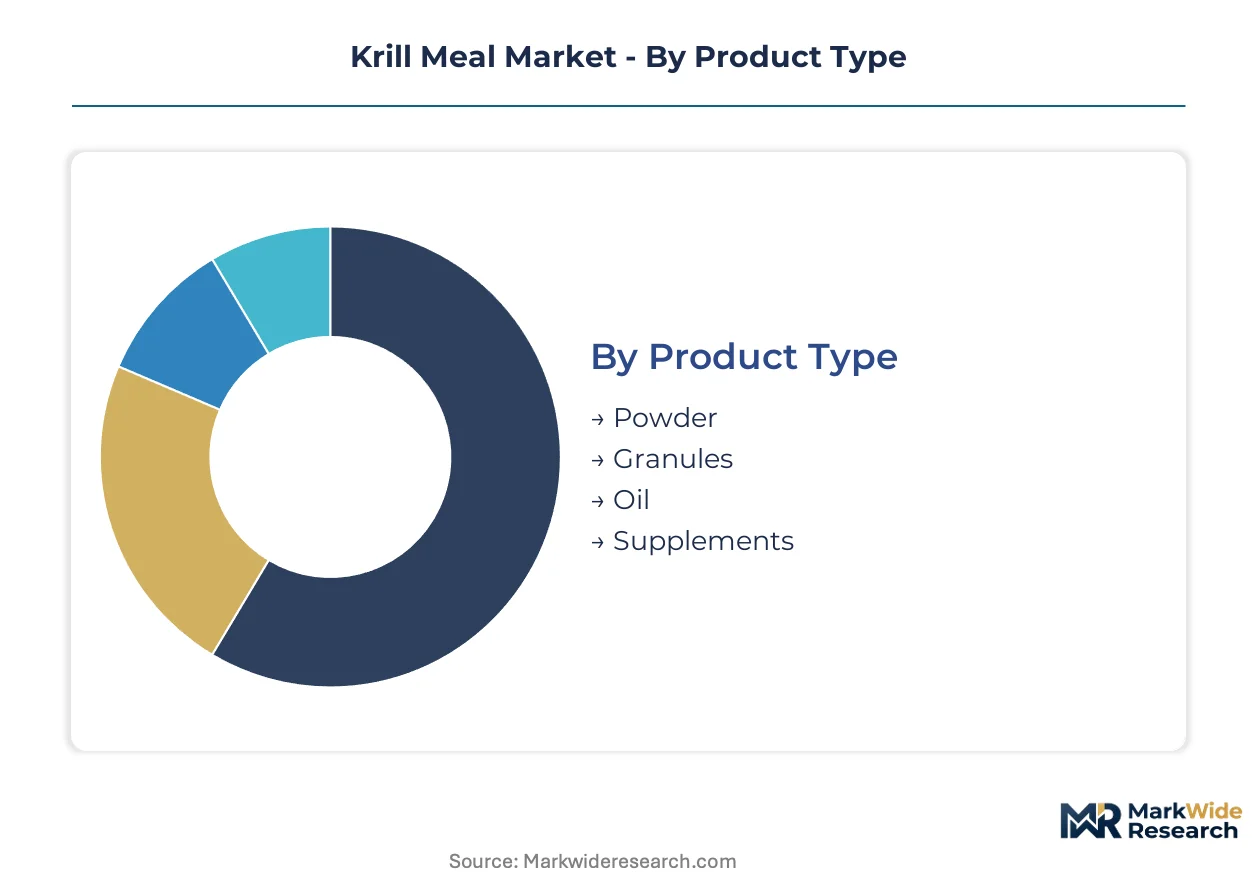
Krill meal segmentation reveals how processing form, customer application, and logistics configuration each create distinct margin profiles and procurement cycles. Understanding these dimensional splits exposes where volume concentrates versus where value capture accelerates.
Product Type:
Cycle times vary sharply across physical forms, with powder turning over fastest due to continuous aquafeed demand while oil extraction requires extended processing windows.
- Powder:Dried defatted meal containing 50-65% crude protein and 8-12% residual lipids, engineered for homogeneous dispersion in extruded feeds. Norwegian salmon feed manufacturers in Bergen and Ålesund consume the bulk of powder throughput, driven by precision diet formulation requirements for Atlantic salmon grow-out operations. Powder anchors the volume base while oil gains share at the steepest rate.
- Granules:Agglomerated particles with controlled dissolution rates for slow-release feeding regimes in recirculating aquaculture systems. Chilean salmon producers in Los Lagos favor granules for their reduced leaching characteristics in high-density tank culture. Granule procurement cycles extend 15-20% longer than powder due to custom sizing requirements.
- Oil:Omega-3 phospholipid concentrate extracted through solvent separation, commanding nutraceutical-grade premiums.
- Supplements:Encapsulated or tablet-form krill derivatives for human consumption channels.
Powder dominates tonnage throughput while oil extraction delivers the steepest margin expansion trajectory.
End User:
Cost tier stratification separates commodity-scale animal nutrition from premium-positioned human health applications.
- Aquaculture:High-performance salmonid and shrimp diets where palatability enhancement justifies inclusion rates above conventional fishmeal. Norwegian, Chilean, and Scottish farmed salmon operations absorb the majority of aquaculture-directed supply, constrained by CCAMLR quota availability and seasonal harvest windows. Aquaculture anchors the volume base while nutraceuticals gains share at the steepest rate.
- Pet Food:Premium companion animal formulations emphasizing omega-3 coat conditioning and palatability.
- Animal Feed:Broader livestock applications including poultry and swine where krill meal serves as a marine protein fortifier.
- Nutraceuticals:Human-grade phospholipid and astaxanthin extraction for dietary supplement and functional food integration.
Aquaculture consumes the majority of raw material flow while nutraceuticals commands the highest per-kilogram realization.
Packaging Type:
Customer type dictates format selection, with industrial buyers favoring bulk efficiency and retail channels requiring unitized presentation.
- Bulk Containers:Flexible intermediate bulk containers and tanker shipments for aquafeed mill direct delivery. Norwegian and Danish compound feed manufacturers in central Jutland and Trøndelag source exclusively through bulk to minimize handling costs and preserve lipid stability. Bulk anchors the volume base while sachets gains share at the steepest rate.
- Bags:Multi-wall paper or woven polypropylene sacks for mid-scale aquaculture operations.
- Tubs:Rigid plastic containers for specialty pet food and premium aquaculture applications.
- Sachets:Single-serve foil packets for companion animal retail and nutraceutical sampling programs.
Bulk configurations dominate B2B procurement while sachet formats penetrate fastest in direct-to-consumer channels.
Distribution Channel:
Supply concentration clusters around distributor networks for industrial volumes, with digital channels capturing emerging specialty demand.
- Distributors:Specialized marine ingredient traders and feed additive wholesalers managing inventory across Norwegian, Chilean, and Scottish salmon farming regions. Distributor relationships consolidate procurement for mid-sized aquaculture operations lacking direct processor contracts. Distributors anchors the volume base while online retail gains share at the steepest rate.
- Specialty Stores:Premium pet nutrition boutiques and aquaculture supply depots serving hobbyist and small-scale producers.
- Supermarkets:Mass retail placement for pet food and limited human supplement SKUs.
- Online Retail:Direct-to-consumer platforms for nutraceutical and specialty pet food segments.
Distributor networks maintain procurement dominance while online retail expands fastest in human-grade and companion animal categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salmon feed manufacturers in Norway, Chile, and Scotland absorb the majority of krill meal procurement, with Norwegian processors commanding supply chain influence through vertical integration from vessel to processing plant.
Norway
Atlantic salmon grow-out operations in Bergen and Ålesund drive powder-form demand for precision diet formulations. The Norwegian Food Safety Authority enforces residue testing protocols that shape export eligibility for processed meal. Trøndelag's compound feed manufacturers source exclusively through bulk containers to minimize handling costs.
Chile
Los Lagos salmon producers favor granule formats for reduced leaching in high-density tank culture systems. The country's national fisheries regulator maintains catch documentation requirements for marine ingredient imports. Puerto Montt anchors southern processing infrastructure where custom sizing extends procurement cycles.
South Korea
The Ministry of Oceans and Fisheries imposes residue testing standards that redirect Antarctic raw material flows toward domestic processing hubs. Busan-Ulsan region concentrates krill meal refining capacity with dedicated quality laboratories. Daesang Corporation exemplifies the integrated processor archetype operating within this regulatory framework.
United States
Specialty pet food manufacturers in the Pacific Northwest command premium pricing for portion-controlled sachet formats. The FDA oversees import safety verification for marine-derived feed additives. Seattle-Tacoma logistics clusters facilitate direct processor-to-farm contracting for aquaculture operations.
Denmark
North Atlantic sourcing networks bypass Antarctic quota pressures entirely for TripleNine Group and BioMar Group A/S operations. The Danish Veterinary and Food Administration enforces traceability requirements for marine ingredients entering European supply chains. Central Jutland compound feed manufacturers consolidate procurement through distributor relationships.
Krill Meal Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Antarctic quota holders with ice-class vessel fleets occupy the upstream extraction tier. Norwegian and South Korean processors with captive laboratory infrastructure dominate the midstream refining tier. Danish North Atlantic operators and Chinese ingredient suppliers populate the alternative sourcing tier. Capacity expansion and geographic licensing represent the dominant competitive moves as quota compression intensifies raw material competition.
Among Norwegian-integrated operators, Aker BioMarine and Rimfrost occupy positions exemplifying the upstream-to-midstream archetype. TripleNine Group represents the North Atlantic bypass strategy that circumvents Southern Ocean regulatory constraints. Shandong Luhua Group Co. Ltd. anchors the Asia-Pacific ingredient supply tier.
| Leading Market Players |
|---|
| Shandong Luhua Group Co. Ltd. |
| TripleNine Group |
| Orkla Group |
| Rimfrost |
| KD Pharma Group |
| Daesang Corporation |
| Aker BioMarine |
| Neptune Krill |
| BioMar Group A/S |
| Others |
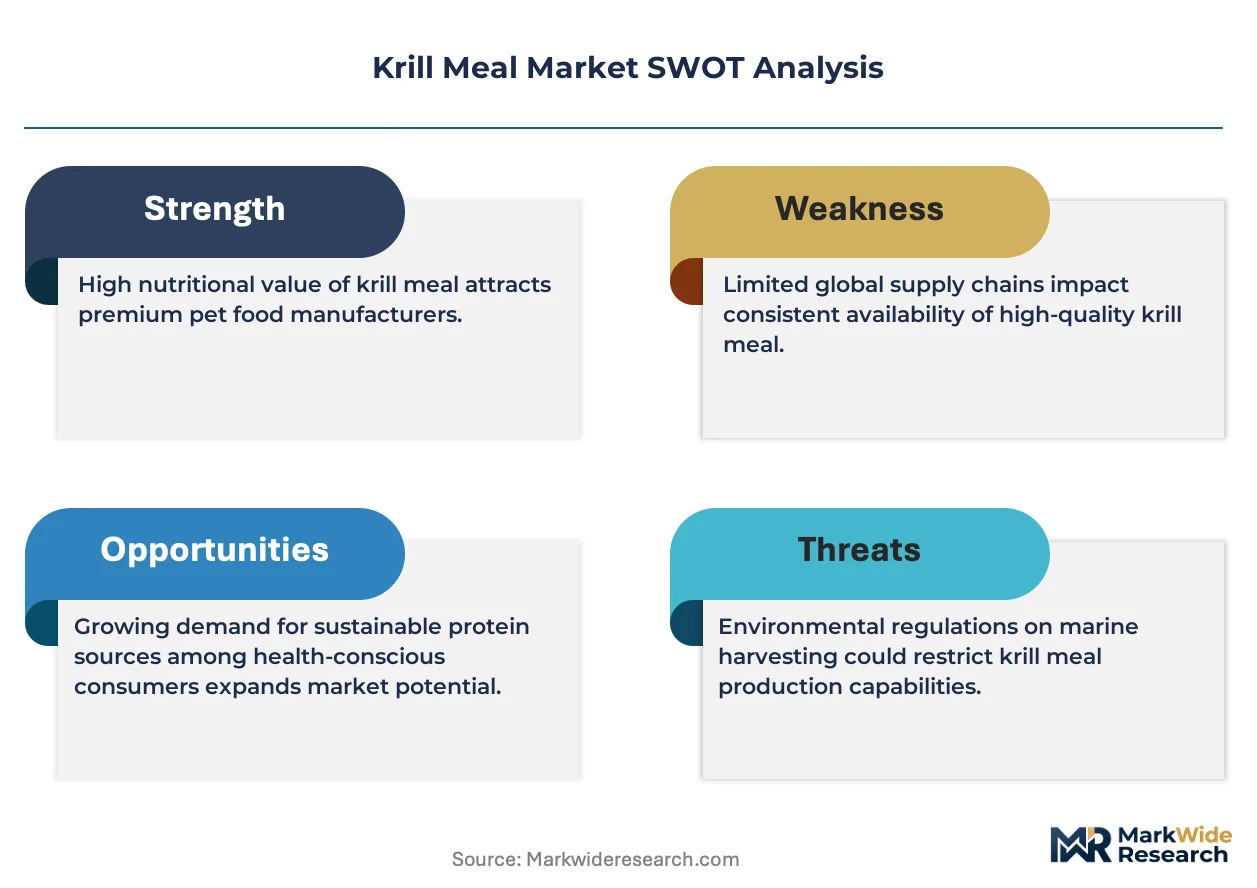
Value Chain & Pricing Dynamics
Antarctic quota compression under CCAMLR rules funnels raw material scarcity toward Norwegian and South Korean processing hubs, concentrating margin capture with operators holding dedicated quality laboratories and long-term salmon producer contracts. Powder-form commodity transactions compete against oil-extraction premiums, splitting value pools between volume throughput and nutraceutical-grade realization.
Pricing Analysis
Cost-plus contracts indexed to Antarctic catch volumes and fuel logistics dominate B2B aquafeed procurement, with Norwegian salmon feed manufacturers locking multi-year agreements to insulate against quota volatility. Price differentiation hinges on phospholipid concentration grades and CCAMLR chain-of-custody certification tiers, while powder segments face margin compression from soy and pea protein substitution in lower-specification diets. Premium oil extraction commands the widest spreads due to nutraceutical channel access. Mid-scale aquaculture operations in Chile and Scotland exhibit highest price sensitivity, whereas integrated Norwegian salmon producers prioritize supply security over spot-market flexibility.
Supply Chain Analysis
Contract-manufacturing concentration rests with Aker BioMarine's Eco-Harvesting fleet integration and Rimfrost's Norwegian vertical processing network, alongside Daesang Corporation's Busan-Ulsan refining complex. Antarctic krill biomass, North Atlantic alternative sourcing, and solvent extraction chemicals constitute the core input dependencies. Single-source vulnerability concentrates around CCAMLR quota allocations and polar logistics windows. Distribution runs through specialized marine ingredient distributors serving Norwegian, Chilean, and Scottish salmon farming regions, with direct processor-to-farm contracting displacing traditional commodity trading structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soy and pea protein concentrates threaten aquafeed inclusion rates, forcing krill meal incumbents to defend premium positioning through phospholipid differentiation and supply security guarantees.
For Market Incumbents: Pre-empt substitution pressure by deepening captive laboratory infrastructure for residue testing compliance under Norwegian Food Safety Authority and South Korea Ministry of Oceans and Fisheries protocols. Secure Antarctic quota holdings through ice-class vessel fleet investment or North Atlantic sourcing bypass strategies. Prioritize direct contracting with Norwegian and Chilean salmon producers to lock volume commitments before plant protein displacement accelerates in lower-tier diets. For New Entrants and Emerging Players: Pursue specialty pet food sachet formats where portion-controlled retail packaging commands premium pricing and Antarctic quota constraints pose less procurement risk. Target nutraceutical phospholipid extraction as the most penetrable value tier, leveraging human-grade certification pathways that bypass commodity aquafeed competition. Establish go-to-market presence through online retail channels for direct-to-consumer supplement distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Norwegian processors holding Antarctic quota licenses but lacking nutraceutical extraction capabilities. Five-to-ten year viability hinges on dual-revenue stream development from single harvests. Monitor CCAMLR quota negotiation outcomes and salmonid diet formulation substitution thresholds as inflection indicators for demand compression or premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ice-Class Vessel Fleet | CCAMLR quota access secures raw material supply against Antarctic biomass constraints. |
| Human-Grade Phospholipid Extraction Scale-Up | Nutraceutical channel development captures premium realization from omega-3 concentrate production. |
| Direct Processor-to-Farm Contracting | Multi-year agreements with Norwegian salmon producers displace spot-market commodity trading structures. |
| North Atlantic Sourcing Network Expansion | Norwegian and Danish operations bypass Southern Ocean regulatory constraints entirely. |
| EU Green Deal Traceability Certification | Chain-of-custody documentation meets tightening sustainability disclosure mandates for European aquafeed. |
Study Parameters
Desk research of CCAMLR catch documentation, Norwegian Food Safety Authority residue testing protocols, and EU Green Deal sustainability mandates preceded structured interviews with Antarctic fleet operations managers, salmon feed formulation scientists, marine ingredient procurement directors, and nutraceutical extraction specialists. Secondary validation drew from customs trade data, aquafeed mill production records, and pharmaceutical phospholipid import filings. Bottom-up volume modeling across powder, granule, oil, and supplement forms triangulated against top-down market sizing through processor capacity assessments.
Assumptions held fixed include CCAMLR ecosystem-based management continuity and Norwegian-South Korean processing hub dominance, while Antarctic quota negotiation outcomes and salmonid diet substitution thresholds were varied across scenarios. Segmentation dimensions encompassed product form, end-user application, packaging configuration, and distribution channel, with regional regulatory clusters modeled separately. CAGRs derived from volume trajectory analysis against baseline procurement patterns, incorporating enzymatic hydrolysis yield improvements and polar logistics cost fluctuations as industry-specific inputs.
Sensitivities concentrate around CCAMLR quota compression severity and plant protein substitution acceleration in aquafeed formulations. Forecasts reflect documented assumptions regarding Antarctic biomass availability and nutraceutical channel penetration. Quarterly review of CCAMLR catch limit announcements and salmon producer diet formulation disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Surimi Market
Seafood
Shellfish Market
Seafood
GCC Seafood Market
Seafood
Fish Fermentation Market
Seafood
Japan Lobster Market
Seafood
Surimi by-Product Market
Seafood
Frozen Seafood Market
Seafood
Processed Seafood Market
Seafood
Canned Fishery Product Market
Seafood
Mackerel Market
Seafood
Europe Lobster Market
Seafood
Mussel Oil Market
Seafood
Milkfish Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Caviar Market
Seafood
Fried Dace with Salted Black Beans Market