
 Mussels Market | 2026-2036
Mussels Market Size, Share, and Industry Trends Forecast 2026-2036
Mussels Market Foresight
Foodservice procurement is recalibrating how mussels move through supply chains, with restaurants and institutional kitchens demanding more live and minimally processed formats. Sanford Limited leverages its South Pacific aquaculture footprint to serve Asian foodservice channels. Barbé Group anchors European distribution through its Belgian processing and cold-chain infrastructure. Camanchaca competes in the premium live-export segment with Chilean-raised Blue Mussels.
Mussels comprise bivalve mollusks of the family Mytilidae, typically harvested at shell lengths of 6-10 centimeters after 12-24 months of rope or seabed cultivation, valued for protein content exceeding 15 grams per 100 grams and omega-3 fatty acid profiles. Their primary commercial purpose spans direct human consumption, bait, and emerging marine ingredient applications. Blue Mussels dominate volume across North Atlantic supply basins due to faster growth cycles and established hatchery protocols. Frozen packaging captures margin pools through extended shelf life and reduced spoilage risk in distant export markets. Vacuum packs sustain premium positioning in European retail channels where freshness signaling commands price premiums.
EU food safety frameworks including EFSA hazard assessments and national veterinary controls determine harvest area classifications, depuration requirements, and maximum biotoxin thresholds that directly shape market access. The US FDA enforces Hazard Analysis Critical Control Point protocols for imported molluscan shellfish, creating compliance cost differentials across origin countries. Stakeholders must monitor evolving maximum residue limits for veterinary medicines and algal biotoxins, as regulatory tightening in major import jurisdictions could redirect trade flows and reshape supplier qualification requirements.
Market Dynamics
Foodservice procurement patterns are restructuring mussel supply chains as coastal restaurants and institutional buyers prioritize live, minimally processed formats over frozen alternatives, compressing traditional processing margins and rewiring cold-chain logistics toward shorter distribution loops.
Growth Catalysts
- EU food safety harmonization:EFSA hazard assessments and national veterinary controls standardize harvest zone classifications across member states, reducing cross-border friction for Spanish and Dutch suppliers accessing German and French retail channels.
- Blue Mussel cultivation protocols:Rope-based aquaculture systems in the North Atlantic basin shorten grow-out cycles to 12-18 months, enabling faster inventory turnover and year-round supply consistency for foodservice contracts.
- Per capita shellfish consumption in Spain:Galician rias supply premium Mediterranean mussels that command price premiums in Madrid and Barcelona restaurant markets, creating pull-through demand for continental European distributors.
Market Restraints
- Algal biotoxin volatility:PSP and DSP toxin outbreaks in North Atlantic harvest zones trigger unpredictable closure periods, forcing processors to maintain expensive multi-origin sourcing networks to ensure supply continuity.
- Depuration infrastructure concentration:EU-mandated purification facilities cluster in Belgium, the Netherlands, and northern France, creating logistical chokepoints for Irish and Scottish producers seeking continental market access.
- Frozen mussel substitution:New Zealand Greenshell mussels and Asian green mussels compete on price in distant export markets, pressuring live-product margins in Asia-Pacific foodservice channels.
Strategic Opportunities
- Marine ingredient applications:Hydrolyzed mussel protein and omega-3 concentrates target nutraceutical and pet food formulations, diversifying revenue beyond traditional whole-shell consumption.
- Direct-to-restaurant distribution:Bypassing centralized auction systems through farm-to-table partnerships with coastal restaurant groups captures margin currently absorbed by wholesale intermediaries.
- EU Green Deal aquaculture incentives:Carbon-neutral certification programs and sustainable seafood labeling schemes create premium positioning for rope-cultivated Blue Mussels in northern European retail.
Industry Challenges
- Depuration cycle standardization:Varying national interpretations of EU minimum purification periods create compliance complexity for multi-market exporters, with some veterinary services demanding 48-hour holds versus the 42-hour baseline.
- Live-transport mortality management:Temperature-controlled logistics for restaurant delivery requires specialized refrigerated vehicles and real-time monitoring systems that strain working capital for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mussels Market |
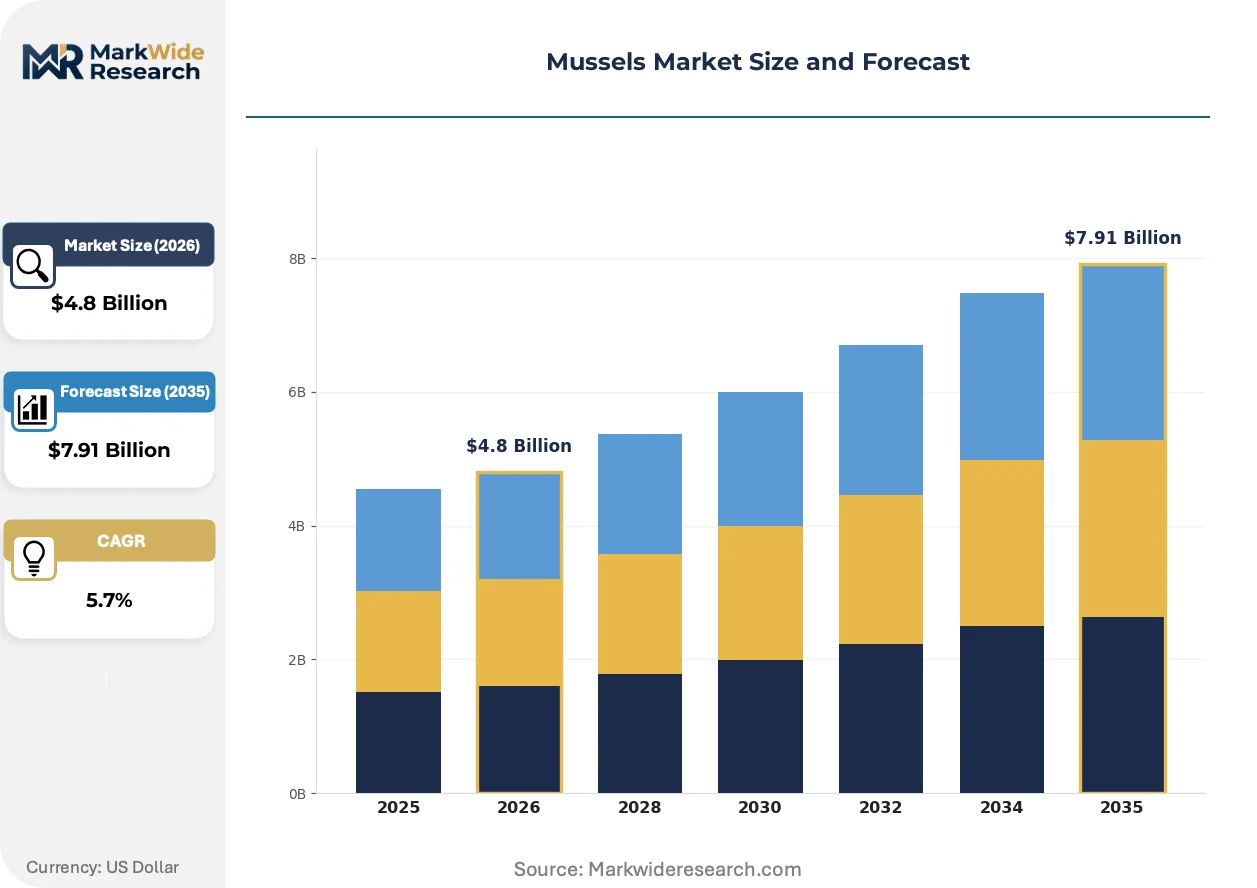
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blue Mussels, Green Mussels, Mediterranean Mussels, Others End User: Restaurants, Seafood Retailers, Foodservice, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Vacuum Packs, Cans, Fresh, Frozen |
| Companies Covered | Barbé Group, Whakatohea Mussel Limited, Sanford Limited, Talley's Group, Westcountry Mussels of Fowey Limited, Camanchaca, Viking Aquaculture, Kush Shellfish, SUDMARIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mussels Market Shifts & Advancements
Remote sensing and predictive modeling are transforming how harvest zones are monitored, while packaging innovations and procurement platform digitization compress transaction friction between producers and end-users.
Automated underwater monitoring systems combining sonar imaging with AI-driven biomass estimation are decentralizing harvest planning away from centralized fleet managers toward individual farm operators. Spanish and Irish rope-cultivation sites deploy these sensors to optimize seeding density and predation response. The technology is decentralizing decision-making authority across historically fragmented producer cooperatives, enabling faster market responsiveness without consolidated ownership structures.
REACH chemical registration requirements and emerging EU microplastic contamination standards are tightening input material specifications for aquaculture gear. Netting, ropes, and flotation devices face heightened scrutiny for polymer degradation products. Processing equipment suppliers in Belgium and the Netherlands are reformulating coating compounds to preempt regulatory non-compliance, with premium certification becoming a procurement prerequisite for northern European retail contracts.
Restaurant groups are consolidating shellfish purchasing through specialized seafood procurement platforms that aggregate demand across multi-location operators. These digital marketplaces displace traditional wholesale auction participation for mid-tier foodservice accounts. The shift is most pronounced in Spanish and Portuguese coastal cities where restaurant density supports platform economics and live-product traceability commands menu price premiums.
Mussels Market Segmentation
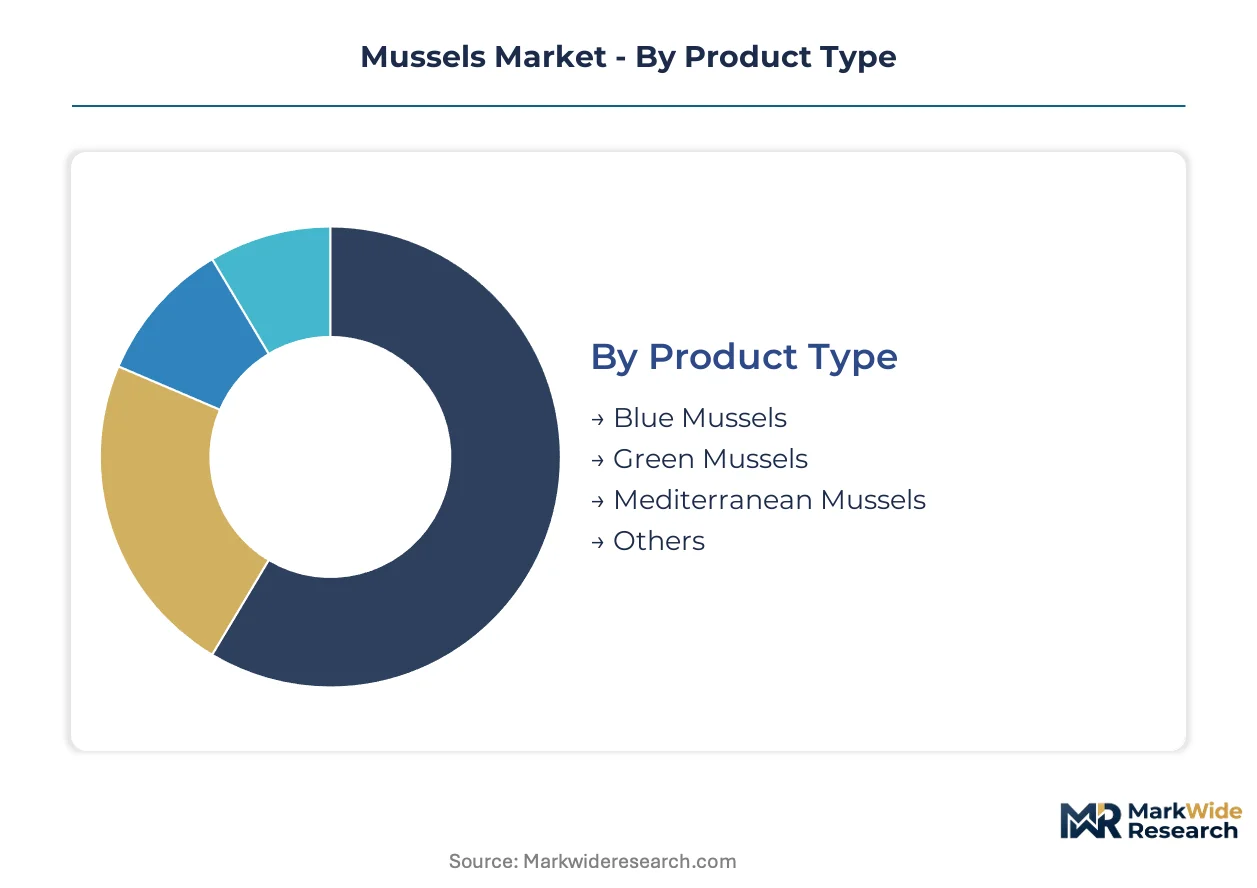
Mussel procurement patterns diverge sharply across product formats and buyer categories, with live-product channels commanding premium positioning while frozen alternatives compete on price in distant markets. Understanding these segment boundaries reveals where margin pools concentrate and how supply chain investments should prioritize.
Product Type:
Upgrade cycles in mussel aquaculture favor faster-growing strains with established hatchery protocols, driving replanting decisions toward varieties with shorter time-to-harvest and proven depuration compliance.
- Blue Mussels:These North Atlantic natives reach commercial size in 12-18 months under rope-cultivation systems, with protein content exceeding 15 grams per 100 grams. Spanish foodservice buyers in Madrid and Barcelona prioritize Blue Mussels for their consistent supply and familiar flavor profile, though algal biotoxin closures in Irish and Scottish waters periodically disrupt availability.
- Green Mussels:Asian green mussel varieties and New Zealand Greenshell strains compete aggressively on price in Asia-Pacific export channels. Their longer grow-out cycles and temperature sensitivity limit European penetration, but cost advantages sustain volume in frozen and processed applications.
- Mediterranean Mussels:Galician rias production commands premium positioning in continental retail through protected designation recognition.
- Others:Niche varieties including horse mussels and local bivalve species serve specialized bait and regional consumption markets.
Blue Mussels sits at the top of the volume ranking, with Mediterranean Mussels climbing the fastest.
End User:
Customer procurement sophistication varies dramatically, with institutional buyers demanding live-product traceability while household purchasers prioritize convenience and price visibility.
- Restaurants:Coastal restaurant groups in Spain and Portugal specify live-product delivery with 48-hour harvest-to-kitchen documentation, absorbing premium pricing for freshness signaling that supports menu premiums. EFSA-compliant depuration certificates have become non-negotiable for high-end establishments.
- Foodservice:Institutional kitchens and catering operations balance cost control with volume reliability, increasingly consolidating purchases through digital procurement platforms that aggregate demand across multi-location operators.
- Seafood Retailers:Belgian and Dutch cold-chain specialists dominate continental distribution, with vacuum-pack formats capturing margin in urban centers.
- Households:Direct-to-consumer channels remain underdeveloped outside Galician production zones, though online platforms are emerging.
Restaurants generate the highest per-kilogram margins, with foodservice expanding most quickly through platform consolidation.
Distribution Channel:
Channel selection directly determines working capital intensity and regulatory compliance burden, with direct sales minimizing intermediaries but concentrating logistics risk.
- Direct Sales:Farm-to-table partnerships with coastal restaurant groups bypass wholesale auction systems, capturing margin currently absorbed by Belgian and Dutch intermediaries while requiring specialized refrigerated transport and real-time mortality monitoring.
- Supermarkets:Northern European retail chains demand REACH-compliant packaging materials and carbon-neutral certification under EU Green Deal labeling schemes, with vacuum-pack formats sustaining premium shelf positioning.
- Specialty Stores:Independent fishmongers and gourmet retailers in French and Italian cities maintain live-tank infrastructure for discerning consumers.
- Online:Digital marketplaces are displacing traditional wholesale participation for mid-tier foodservice accounts, particularly in Portuguese coastal cities where restaurant density supports platform economics.
Supermarkets dominate volume throughput, with online channels gaining share fastest in urban foodservice aggregation.
Packaging Type:
Packaging technology investments align with target market distance and freshness signaling requirements, with format selection determining export feasibility.
- Frozen:Blast-freezing at harvest preserves shelf life for 12-18 months, enabling New Zealand and Chilean producers to serve distant Asian markets where live-transport mortality would erode margins. Frozen formats absorb price competition from Asian green mussel substitutes.
- Vacuum Packs:Modified atmosphere packaging extends chilled shelf life to 10-14 days, supporting premium positioning in German and French retail where freshness signaling commands price premiums and EU labeling requirements demand traceability documentation.
- Fresh:Live-product logistics concentrate in coastal corridors with depuration infrastructure clustering in Belgium, the Netherlands, and northern France.
- Cans:Thermal processing targets mass-market shelf-stable applications with lower per-unit margins but reduced cold-chain dependency.
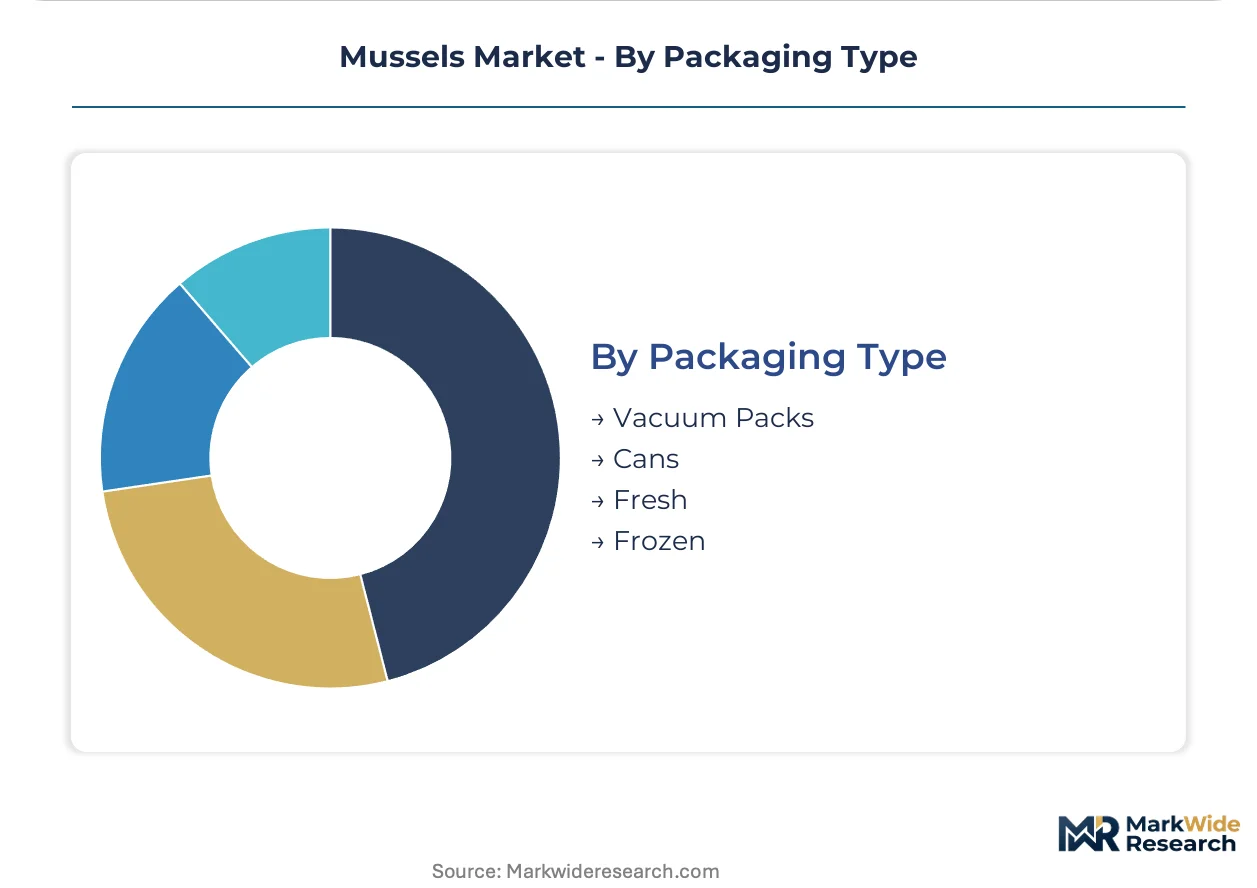
Frozen packaging leads volume in export markets, with vacuum packs expanding most quickly in premium European retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as harvest zone classifications and depuration infrastructure costs create compliance gaps between jurisdictions. Producers migrate toward regions with streamlined veterinary controls and established cold-chain logistics, while EFSA harmonization reduces friction for cross-border suppliers.
Spain
Galician rias anchor Mediterranean mussel production with protected designation recognition commanding premium positioning in Madrid and Barcelona restaurant markets. EFSA hazard assessments standardize harvest classifications across autonomous communities, reducing veterinary inspection fragmentation. Vigo and A Coruña processing clusters concentrate depuration capacity and live-export logistics for continental European buyers.
Netherlands
Yerseke and Zeeland province dominate Blue Mussel cultivation through established rope-based aquaculture systems serving German and Belgian retail channels. National veterinary services enforce EU-mandated purification protocols that exceed baseline requirements, creating qualification barriers for non-domestic suppliers. Rotterdam cold-chain infrastructure enables rapid distribution to northern European supermarkets demanding vacuum-pack formats.
Chile
Los Lagos Region production targets premium live-export segments in Asia-Pacific foodservice channels where Blue Mussel growth cycles compete with New Zealand supply. The country's national fisheries service applies HACCP-aligned protocols for molluscan shellfish export certification. Puerto Montt processing facilities concentrate blast-freezing capacity for distant markets where transport mortality would erode live-product margins.
New Zealand
Coromandel and Marlborough Sounds anchor Greenshell mussel production competing aggressively on price in frozen and processed Asian export channels. Ministry for Primary Industries biotoxin monitoring programs determine harvest area openings with predictive modeling reducing closure unpredictability. Havelock and Nelson processing clusters specialize in half-shell and value-added formats for Japanese and Korean retail.
Ireland
County Cork and County Galway rope-cultivation sites supply live-product channels to French and Belgian buyers despite depuration infrastructure concentration creating logistical chokepoints. Sea-Fisheries Protection Authority enforcement of EU shellfish hygiene regulations determines market access eligibility. Bantry Bay and Killary Harbour production zones leverage Atlantic water quality for premium positioning in continental specialty stores.
Mussels Market Competitive Landscape
Strategic partnerships dominate the current landscape as processing specialists and aquaculture operators combine capabilities to secure foodservice contracts. The vendor base concentrates around three tiers: integrated producers controlling cultivation through distribution, specialized processors leveraging regional cold-chain infrastructure, and export-focused cultivators serving distant markets through frozen formats. Two archetypes define competitive positioning: scale-driven operators optimizing volume throughput in standardized product lines, and premium specialists capturing margin through live-product traceability and protected designation sourcing. Geographic expansion and portfolio diversification represent the dominant competitive moves, with producers extending cultivation licenses into new water bodies while adding value-added formats to reduce commodity exposure.
Within the integrated-producer tier, Sanford Limited and Camanchaca exemplify scale-driven positioning through South Pacific and South American aquaculture footprints respectively. Among European processing specialists, Barbé Group occupies a position anchored in Belgian cold-chain infrastructure and continental distribution networks. Talley's Group represents the export-focused archetype with New Zealand-based cultivation serving Asian frozen and processed segments. These three companies illustrate how geographic origin and structural integration determine competitive positioning without requiring specific operational claims about individual facilities or customer relationships.
| Leading Market Players |
|---|
| Barbé Group |
| Whakatohea Mussel Limited |
| Sanford Limited |
| Talley's Group |
| Westcountry Mussels of Fowey Limited |
| Camanchaca |
| Viking Aquaculture |
| Kush Shellfish |
| SUDMARIS |
| Others |
Supply & Pricing Matrix
Foodservice procurement preferences for live-product delivery with 48-hour harvest-to-kitchen documentation force supply chains to absorb premium logistics costs, compressing processor margins while elevating price premiums for verified traceability in Madrid and Barcelona restaurant markets.
Pricing Analysis
Distributor margin layers in Belgian and Dutch cold-chain infrastructure sustain three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EFSA-compliant depuration certification and live-transport mortality guarantees, with premium tiers capturing margin from coastal restaurant groups. Cost compression in frozen formats intensifies because New Zealand Greenshell mussels compete aggressively on price in Asia-Pacific channels. Institutional foodservice buyers exhibit highest price sensitivity, while high-end restaurants in Spain absorb premiums for freshness signaling.
Supply Chain Analysis
Workforce availability constraints in Galician processing clusters and Zeeland rope-cultivation sites limit seasonal scaling capacity. Supply concentrates in Spain, the Netherlands, and New Zealand, with raw material dependencies on hatchery seed stock, specialized depuration equipment, and REACH-compliant polymer gear. Single-source vulnerability runs through Belgian depuration infrastructure concentration for Irish and Scottish producers. Distribution runs through Rotterdam cold-chain hubs for northern European supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU-mandated depuration infrastructure costs and Chilean HACCP-aligned export certification pathways, with compliance cost differentials creating margin capture opportunities for multi-origin sourcing networks.
For Market Incumbents: Anchor market position through backward integration into hatchery seed production and captive depuration capacity in Vigo or Yerseke clusters. New Zealand frozen-format competitors threaten live-product margins in Asia-Pacific channels; defend through EFSA certification investment and direct-to-restaurant partnerships that bypass Belgian intermediaries. For New Entrants and Emerging Players: Seafood procurement platforms serving Portuguese coastal restaurant groups represent the most penetrable channel wedge. Target underdeveloped direct-to-consumer online channels outside Galician production zones, with farm-to-table subscription models leveraging real-time mortality monitoring as the go-to-market differentiator. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale rope-cultivation operators holding Atlantic water quality licenses in County Cork or County Galway. Long-term viability over a multi-year horizon rests on EU Green Deal carbon-neutral certification positioning. Acquisition targets should demonstrate live-export logistics capability and protected designation access. Watch algal biotoxin predictive modeling accuracy as the inflection indicator for harvest zone stability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hatchery Operations | Captive seed supply reduces dependency on external nurseries and accelerates grow-out cycle control. |
| Carbon-Neutral Certification Program | EU Green Deal labeling schemes unlock premium positioning in German and Dutch supermarket channels. |
| Direct-to-Restaurant Distribution Partnership | Farm-to-table agreements with Madrid restaurant groups capture margin from Belgian wholesale intermediaries. |
| Predictive Biotoxin Monitoring Investment | AI-driven harvest zone forecasting reduces closure unpredictability and secures foodservice contract reliability. |
| Marine Ingredient Diversification | Hydrolyzed protein and omega-3 concentrate production hedges revenue exposure to whole-shell commodity cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aquaculture farm operators, seafood procurement platform executives, EFSA regulatory affairs specialists, and cold-chain logistics managers with secondary validation. Customs trade data, EU veterinary service harvest zone classifications, FAO aquaculture production statistics, and SEC filings from publicly traded seafood processors anchored the dataset. Bottom-up farm-level production estimates and top-down trade flow analysis provided triangulation.
Segment-weighting approaches modeled product type, end-user category, distribution channel, and packaging format dimensions across the analysis window. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated algal biotoxin closure frequency patterns and EU microplastic contamination standard evolution timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA regulatory tightening and climate-driven harvest zone reclassification. Projections reflect documented assumptions about depuration infrastructure expansion rates and foodservice platform penetration curves. Material deviation in biotoxin predictive modeling accuracy or EU Green Deal subsidy allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
North America Seafood Market
Seafood
Canned Seafood Market
Seafood
European Frozen Seafood Market
Seafood
South America Canned Seafood Market
Seafood
Europe Seafood Market
Seafood
Surimi Market
Seafood
Fin Fish Market
Seafood
Salmon Market
Seafood
Fish Hydrolysate Market
Seafood
Europe Salmon Market
Seafood
Smoked Whiting Market
Seafood
Milkfish Market
Seafood
Europe Shrimp Market
Seafood
Molluscs Market
Seafood
China Crustaceans Market
Seafood
Fish Oil Market