
 Home Security Camera Market | 2026-2036
Home Security Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Home Security Camera Market Intelligence
Manufacturing capacity in Asia, particularly within China's electronics hubs, is consolidating around firms with advanced sensor and wireless module integration capabilities. Arlo leverages its strong brand presence in the premium wireless camera segment. Ring, a subsidiary of Amazon, dominates the doorbell camera category through its deep integration with the Alexa ecosystem. Eufy Security competes on data privacy by emphasizing local storage solutions over mandatory cloud subscriptions.
A home security camera is a video surveillance device designed for residential monitoring, typically featuring IP-based connectivity for remote viewing. These devices often incorporate CMOS image sensors, wide-angle lenses, and infrared LEDs for night vision capabilities. Wireless cameras and doorbell cameras represent the fastest-growing product types, driven by ease of installation for homeowners. Within technology, the shift towards 4K resolution cameras is notable in the premium residential segment, while IP cameras have become the standard.
Data privacy regulations, including the EU's GDPR and various state-level laws in the United States, impose strict requirements on how manufacturers handle and store video data. Concurrently, cybersecurity standards from bodies like the FCC in the US and equivalent agencies in other nations are influencing device hardware and software security protocols to prevent unauthorized access. Navigating the complex patchwork of regional data sovereignty and security certification requirements remains a critical strategic challenge for vendors.
Market Dynamics
The central tension shaping the home security camera market is the conflict between consumer demand for advanced AI-powered analytics and escalating regulatory and personal concerns over data privacy and cybersecurity, forcing a strategic re-evaluation of cloud-centric architectures.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence for sophisticated object detection, facial recognition, and behavior analysis enhances the value proposition, moving cameras from simple recorders to proactive security tools for homeowners.
- Smart Home Ecosystems:Proliferation of smart home platforms in markets like the United States and Germany drives demand for cameras that seamlessly integrate with voice assistants and other connected devices, creating a unified home automation experience.
- Wireless Infrastructure Expansion:The continued rollout of 5G and advanced Wi-Fi standards enables more reliable, high-bandwidth connectivity, supporting the adoption of higher-resolution wireless cameras without compromising performance.
Market Restraints
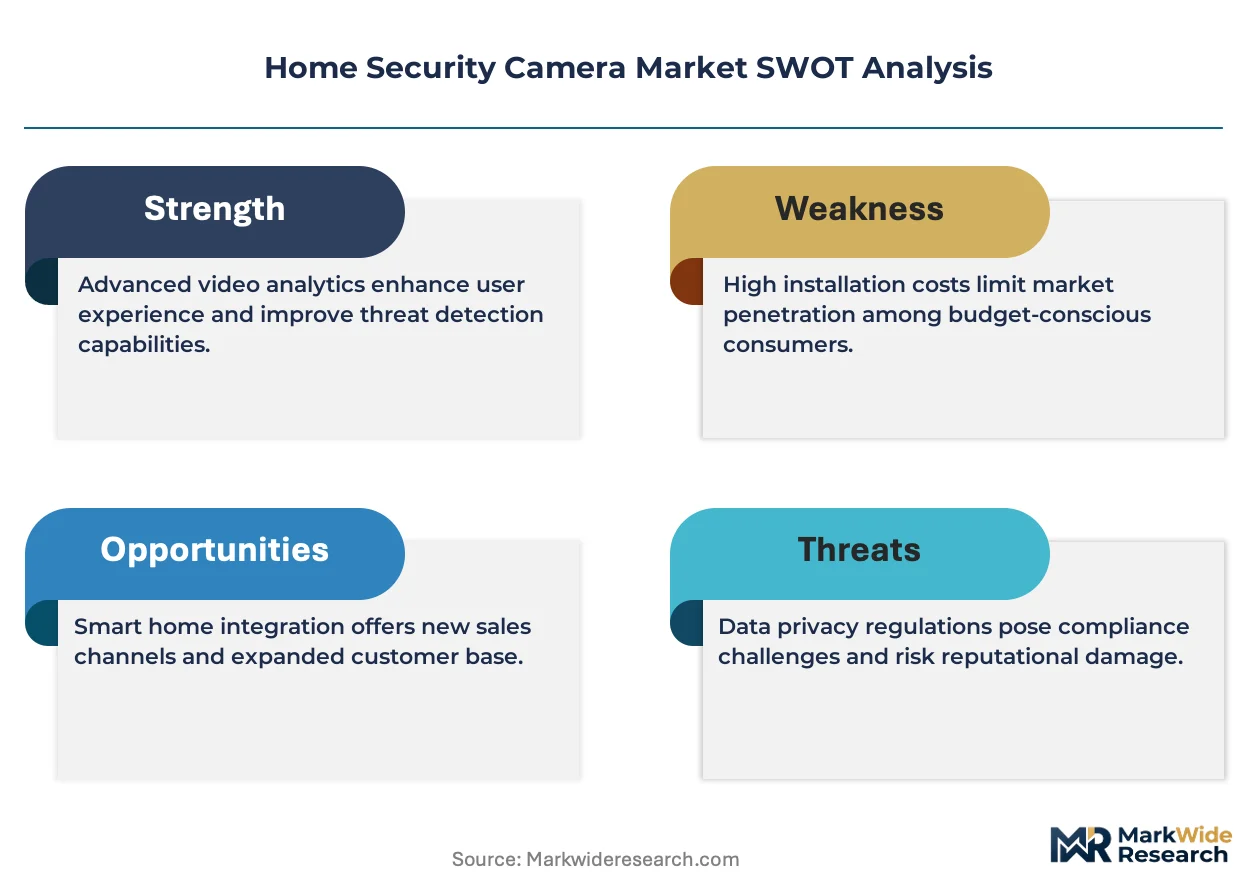
- Data Privacy Regulation:Strict regulations like the EU's GDPR impose significant compliance burdens on manufacturers regarding video data storage, processing, and user consent, limiting certain features and increasing operational costs.
- Cybersecurity Vulnerabilities:High-profile security breaches have heightened consumer fears about unauthorized access to camera feeds, creating a barrier to adoption and pressuring vendors to meet rigorous security standards from bodies like the FCC.
- Subscription Model Fatigue:Consumer resistance to mandatory monthly cloud storage subscriptions for full feature access acts as a restraint, particularly in price-sensitive segments where local storage alternatives are preferred.
Strategic Opportunities
- Emerging Market Penetration:Rapid urbanization and a growing middle class in countries like India present a significant opportunity for market expansion as smart home technology adoption begins to accelerate.
- Health and Wellness Monitoring:Repurposing camera technology for in-home, non-intrusive monitoring of the elderly or individuals with health conditions opens a new B2C and B2B2C application vertical in assisted living.
- Edge Computing Integration:Developing cameras with powerful on-device processors for local AI analysis presents an opportunity to address privacy concerns directly, creating a key differentiator from cloud-reliant competitors.
Industry Challenges
- Regulatory Fragmentation:Vendors face the operational challenge of designing and managing products that comply with a complex and often conflicting patchwork of regional data sovereignty and security certification requirements across the globe.
- Interoperability Standards:Ensuring seamless and secure communication between cameras and devices from different manufacturers within a smart home ecosystem remains a significant technical hurdle, despite efforts like the Matter protocol.
- Supply Chain Concentration:A heavy reliance on a few specialized suppliers in China for critical components like image sensors and wireless modules creates geopolitical risk and potential for supply chain disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Security Camera Market |
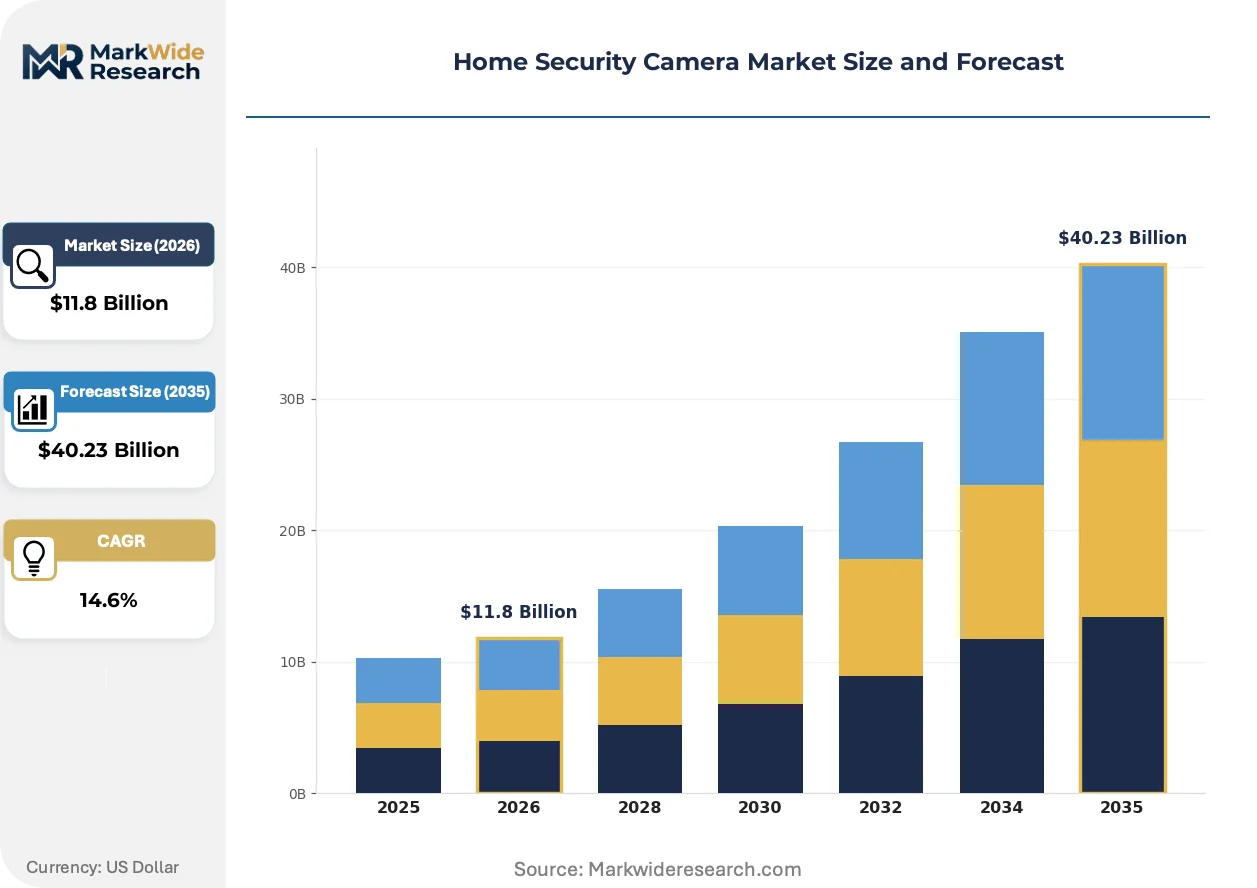
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, Doorbell Cameras, Wireless Cameras, Wired Cameras Technology: IP Cameras, Analog Cameras, Pan-Tilt-Zoom Cameras, 4K Resolution Cameras, Thermal Cameras Application: Residential Properties, Small Office Security, Retail Premises, Warehouses, Educational Facilities End User: Homeowners, Property Managers, Security Agencies, Business Owners, Facility Managers |
| Companies Covered | Ring, TP-Link, Reolink, Alibi Security, Arlo, Eufy Security, Axis Communications, SimpliSafe, Lorex (by Dahua), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Security Camera Market Strategic Shifts & Innovations
The market is pivoting towards on-device intelligence and privacy-centric designs. This shift responds directly to consumer and regulatory pressures, forcing a re-architecture of how video data is processed, stored, and secured away from purely cloud-based models.
Edge AI, which embeds neural processing units directly into the camera hardware, performs real-time analytics such as person detection and facial recognition locally. Consumers in the premium residential segment are adopting this for faster alerts and greater privacy assurance. On-device processing is overtaking cloud-dependent analytics for critical, low-latency security functions, which reduces data transmission vulnerabilities and subscription costs.
The European Union's proposed AI Act introduces a risk-based framework for artificial intelligence systems. This legislation will mandate stringent compliance and transparency for cameras using AI in ways that could be deemed high-risk surveillance. Consequently, vendors targeting the EU market are proactively designing systems with features like user-controlled data processing and explainable AI to align with future regulatory obligations.
A clear consumer preference for non-recurring revenue models is altering go-to-market strategies. Buyers are increasingly choosing devices that feature robust local storage via high-capacity SD cards or dedicated home base stations, thereby disrupting the previously dominant mandatory cloud subscription model. This demand-side shift is particularly visible in North American and European markets where data privacy is a primary purchasing driver.
Home Security Camera Market Segmentation
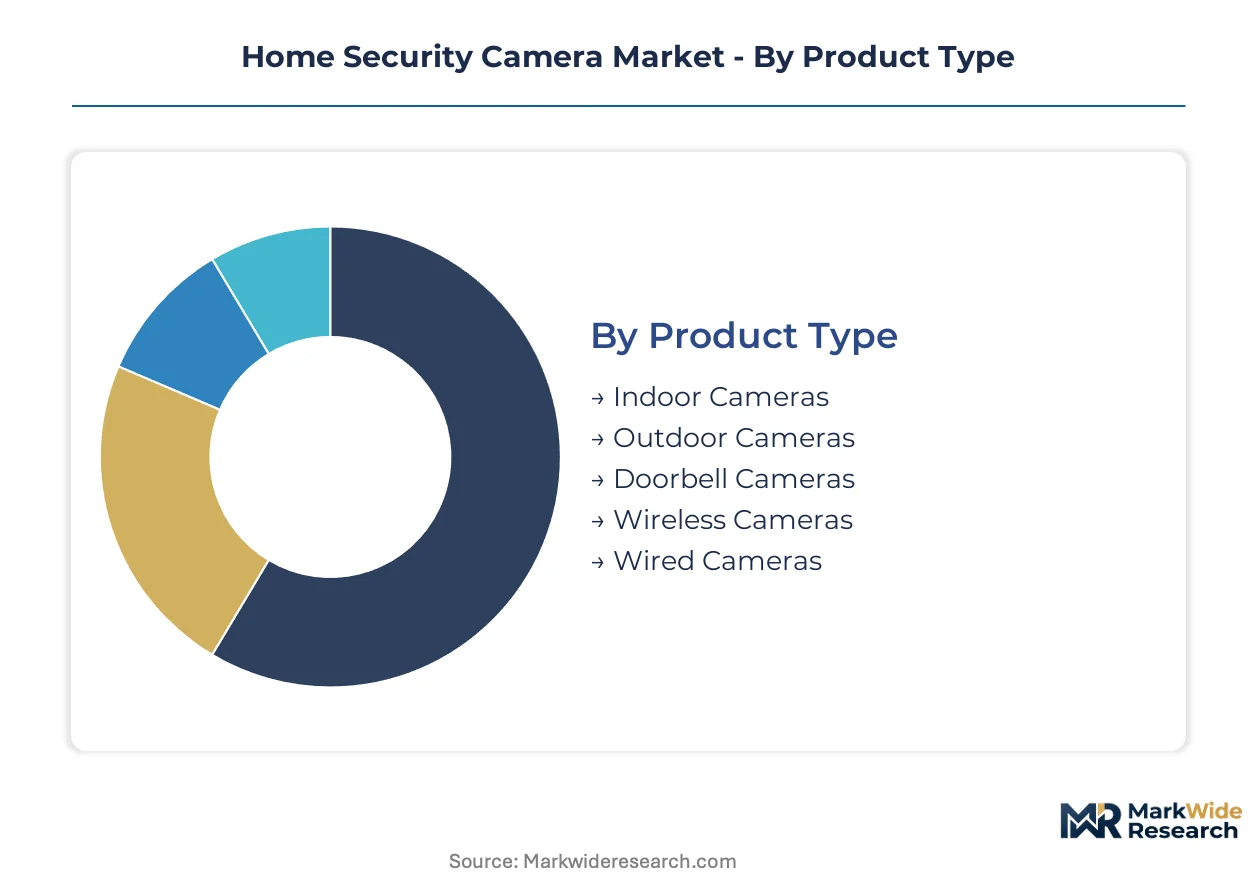
Segmentation of the home security camera market illuminates the varied consumer needs and technological preferences driving product development. Understanding these distinct segments helps manufacturers tailor solutions for specific residential monitoring requirements. This approach informs strategic decisions on feature sets and distribution channels.
Product Type:
Product types differentiate by their installation complexity and integration into broader home systems, ranging from standalone units to deeply embedded solutions.
- Doorbell Cameras:These devices combine a camera, microphone, and speaker into a single unit, often with motion detection and two-way audio. Demand concentrates in urban residential areas, driven by convenience and package delivery monitoring, integrating with smart home ecosystems like Alexa.
- Wireless Cameras:Operating without physical data cables, these cameras transmit video over Wi-Fi or proprietary wireless protocols, powered by batteries or low-voltage wiring. Homeowners in the United States and Germany prioritize these for ease of installation and flexible placement, avoiding complex wiring.
- Indoor Cameras:Designed for internal monitoring, these cameras often feature discreet designs and basic motion detection for living spaces.
- Outdoor Cameras:Built to withstand environmental elements, outdoor cameras offer robust housing and enhanced night vision for perimeter surveillance.
- Wired Cameras:These cameras rely on physical cables for power and data transmission, providing reliable, continuous surveillance for fixed installations.
Indoor Cameras lead volumes today; Doorbell Cameras are gaining share fastest.
Technology:
Technological distinctions define camera performance and feature sets, from basic monitoring to advanced analytical capabilities.
- IP Cameras:These digital cameras transmit video data over an internet protocol network, enabling remote access and often integrating advanced analytics. Residential users in North America and Europe adopt IP cameras for their superior resolution and seamless integration with smart home platforms.
- 4K Resolution Cameras:Offering ultra-high-definition video with four times the pixels of 1080p, these cameras provide exceptional image clarity and detail. The premium residential segment in markets like the United States increasingly seeks 4K cameras for enhanced forensic detail and larger coverage areas.
- Analog Cameras:These traditional cameras transmit video signals over coaxial cables, offering a cost-effective solution for basic surveillance needs.
- Pan-Tilt-Zoom Cameras:PTZ cameras allow remote control of their lens direction and zoom, providing dynamic coverage of wider areas from a single vantage point.
- Thermal Cameras:Detecting heat signatures rather than visible light, thermal cameras provide effective surveillance in complete darkness or obscured conditions.
IP Cameras remain the standard, while 4K Resolution Cameras are expanding most quickly in the premium segment.
Application:
Applications for home security cameras vary significantly based on the scale of deployment and specific security objectives of the monitored environment.
- Residential Properties:This segment focuses on individual homes and apartments, addressing personal safety, property protection, and remote monitoring needs. Homeowners globally represent the largest application segment, driven by personal security concerns and smart home integration trends.
- Small Office Security:Cameras deployed in small businesses for monitoring entrances, inventory, and employee activity, often requiring remote access and analytics. Business owners in urban centers increasingly adopt these systems for loss prevention and after-hours surveillance, often bundling with other IT services.
- Retail Premises:Surveillance solutions for retail stores focus on preventing theft, monitoring customer traffic, and ensuring employee safety within commercial spaces.
- Warehouses:Cameras in warehouses manage inventory, monitor logistics, and enhance security over large areas, often integrating with access control systems.
- Educational Facilities:Security cameras in schools and universities enhance campus safety, monitor public areas, and provide evidence in incident investigations.
Residential Properties command the largest share, with Small Office Security experiencing the steepest expansion trajectory.
End User:
End users are categorized by their primary motivation for camera deployment, ranging from personal safety to large-scale facility management.
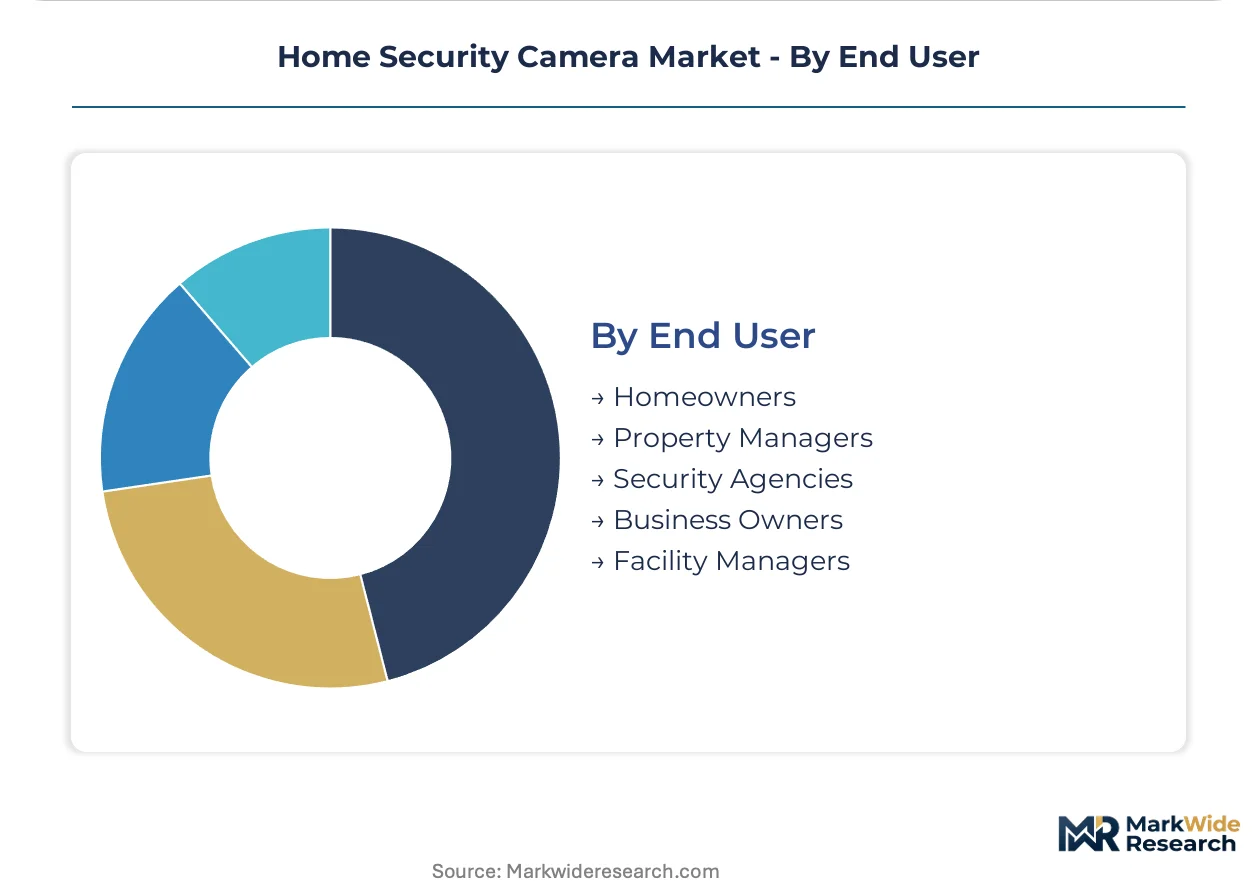
- Homeowners:Individuals purchasing cameras for their private residences, prioritizing ease of use, privacy features, and integration with personal smart devices. This user group in the United States and Germany drives the bulk of market demand, focusing on family safety and property monitoring.
- Property Managers:Professionals overseeing multiple residential or commercial units, requiring scalable, centralized monitoring solutions for common areas and tenant security. Urban property management firms increasingly invest in these systems for liability reduction and enhanced communal area surveillance.
- Security Agencies:These entities utilize advanced camera systems for professional surveillance, remote monitoring, and rapid response capabilities for clients.
- Business Owners:Entrepreneurs deploy cameras to protect assets, monitor employee activity, and ensure customer safety within their commercial establishments.
- Facility Managers:Responsible for large-scale infrastructure, facility managers implement comprehensive camera networks for perimeter control and operational oversight.
Homeowners remain the dominant end-user group, while Property Managers are showing strong momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States demonstrates robust consumer adoption of smart home devices, while Germany exhibits a strong preference for privacy-centric solutions. These distinct market dynamics shape regional product development and regulatory adherence. Regulatory frameworks influence market growth across various geographies.
United States
The United States drives significant demand for home security cameras, particularly for integration into broader smart home ecosystems. FCC regulations influence device hardware and software security protocols to prevent unauthorized access. Silicon Valley continues to foster innovation in AI-powered analytics and smart home device interoperability.
Germany
Germany's market shows strong demand for home security cameras with emphasis on data privacy and local storage options. The EU's GDPR imposes stringent requirements on how manufacturers handle and store video data. Munich and Berlin are centers for smart home technology development, focusing on secure and compliant solutions.
China
China's manufacturing capacity for home security cameras consolidates around firms with advanced sensor and wireless module integration capabilities. GB standards for electronics ensure product quality and safety for domestic and international markets. Shenzhen's extensive electronics hubs serve as global production centers for camera components and finished goods.
India
India presents a significant opportunity for market expansion, driven by rapid urbanization and a growing middle class adopting smart home technology. BIS standards apply to electronic products, ensuring adherence to national quality and safety benchmarks. Bangalore's burgeoning tech sector sees rising interest in smart home security solutions and local manufacturing initiatives.
Japan
Japan's premium residential segment increasingly seeks 4K resolution cameras for enhanced forensic detail and larger coverage areas. JIS standards govern product quality and reliability across consumer electronics, including home security devices. Tokyo's advanced consumer electronics market drives adoption of high-tech surveillance solutions and sophisticated smart home integration.
Home Security Camera Market Key Industry Players
Chinese producers anchor one tier of the home security camera market, specializing in component manufacturing and high-volume production. European and North American specialists hold positions in premium segments, focusing on brand and software integration. The market structure exhibits both consolidation in core technology and fragmentation in consumer-facing brands. Companies pursue strategic partnerships for ecosystem expansion and invest in advanced AI analytics.
Within the premium wireless camera segment, Arlo exemplifies a brand known for its robust features and design, catering to consumers seeking high-end surveillance solutions. Ring, a subsidiary of Amazon, anchors the doorbell camera category through its deep integration with the Alexa ecosystem, dominating a specific product type. Eufy Security occupies a position emphasizing data privacy by offering local storage solutions, directly addressing consumer and regulatory concerns around cloud dependence. These companies represent distinct strategic approaches to market penetration and consumer trust.
| Leading Market Players |
|---|
| Ring |
| TP-Link |
| Reolink |
| Alibi Security |
| Arlo |
| Eufy Security |
| Axis Communications |
| SimpliSafe |
| Lorex (by Dahua) |
| Others |
Cost & Logistics Intelligence
Edge AI integration, a significant technological shift, simultaneously increases hardware costs for on-device processing and reduces long-term operational expenses by mitigating cloud subscription dependencies. This transition reshapes the cost structure for manufacturers while concentrating advanced module supply among specialized firms.
Pricing Analysis
Capacity additions in China's electronics hubs are reshaping price floors for core camera components, influencing the final product cost. Pricing stratifies across premium, standard, and economy tiers, driven by brand premium for established players like Arlo and the inclusion of local storage features by competitors such as Eufy Security. Consumer resistance to mandatory cloud subscriptions exerts downward pricing pressure, particularly in price-sensitive segments. The premium residential segment, however, exhibits lower price sensitivity for advanced features like 4K resolution and Edge AI capabilities.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers in China for critical components such as CMOS image sensors and wireless modules. The supply chain draws heavily from electronics hubs like Shenzhen, creating a high geographic concentration. Geopolitical risk represents a significant structural risk due to this reliance on a few key regions. Distribution runs through a hybrid model, combining direct-to-consumer online sales with strategic partnerships for smart home ecosystem integration, exemplified by Ring's deep links with Amazon's Alexa platform.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the European Union's proposed AI Act driving demand for privacy-by-design solutions and local processing capabilities.
For Market Incumbents:Hedge against evolving data privacy regulations by investing heavily in Edge AI development and secure local storage solutions. This proactive R&D in on-device processing can mitigate the threat of increasing compliance burdens from regulations like GDPR. Incumbents should also reinforce channel control within established smart home ecosystems, leveraging existing brand presence and customer trust to maintain market share against new entrants focusing on privacy. Prioritizing robust cybersecurity certifications, such as those from the FCC, protects against high-profile security breaches.
For New Entrants and Emerging Players:Direct-to-consumer online channels offer a penetrable segment by emphasizing data privacy and non-recurring revenue models. Target emerging markets like India, where rapid urbanization and a growing middle class present significant underpenetration for smart home technology. Focus on specific application verticals, such as health and wellness monitoring for the elderly, to create a distinct go-to-market angle. Offering cameras with powerful on-device processors and robust local storage can differentiate new players from cloud-reliant competitors, addressing consumer subscription model fatigue.
For Investors and Strategic Acquirers:Valuations sit cheapest among firms specializing in local storage solutions or those with proprietary Edge AI intellectual property, offering strong long-term viability within a market driven by privacy concerns. Acquisition targets should include companies with established niches in specific product types, like doorbell cameras, or strong regional compliance certifications. The signal to watch is the widespread adoption of interoperability standards like Matter, which could unlock new market segments and consolidate ecosystem players.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Edge AI Development | Enhances privacy and reduces cloud dependency, aligning with regulatory shifts and consumer preference. |
| Expand Local Storage Offerings | Addresses consumer fatigue with subscriptions and strengthens data privacy claims, differentiating product lines. |
| Secure Strategic Ecosystem Partnerships | Broadens market reach and deepens integration with smart home platforms, crucial for market penetration. |
| Obtain Global Security Certifications | Builds consumer trust and ensures compliance with diverse regional cybersecurity standards like FCC and GB. |
| Penetrate Emerging Urban Markets | Captures new demand in rapidly urbanizing regions adopting smart home technology, like India. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the market dynamics. Primary research involved discussions with product managers, smart home integrators, cybersecurity experts, and regulatory compliance officers across various regions. This primary intelligence was cross-referenced with secondary data from FCC filings, EU GDPR compliance reports, patent databases, and smart home adoption surveys for robust validation, employing both bottom-up and top-down triangulation.
The segment-weighting approach informed the analytical framework, modeling market behavior across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and key regional markets like the United States and Germany. Compound annual growth rates were derived from historical growth trends, projected technological adoption rates, and anticipated shifts in regulatory frameworks. Smart home device penetration rates and evolving data privacy regulations served as critical industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for Edge AI or 5G infrastructure deployment would alter the outlook. Forecasts reflect assumptions concerning geopolitical stability affecting supply chains and the consistent evolution of data privacy regulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Security and Surveillance Storage Market