
 Asia-Pacific Video Surveillance Storage Market | 2026-2036
Asia-Pacific Video Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Video Surveillance Storage Market Insights
Public-sector buyers are unwinding the historical dominance of private retail deployments across the Asia-Pacific Video Surveillance Storage Market. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its integrated camera-to-storage ecosystem to anchor large-scale municipal contracts in China. Seagate Technology LLC specializes in surveillance-optimized hard disk drives with workload ratings exceeding standard enterprise drives. Dahua Technology Co., Ltd. competes through edge-storage appliances that reduce backhaul bandwidth requirements for distributed installations.
Video surveillance storage encompasses disk arrays, solid-state media, network-attached enclosures, and cloud repositories engineered for sequential write-intensive workloads with retention periods spanning weeks to years. These systems employ vibration-resistant mechanics, enhanced error correction, and firmware tuned for 24/7 multi-stream ingestion from hundreds of concurrent camera channels. Hard Disk Drives sustain the bulk of installed petabytes due to cost-per-terabyte economics, though Solid State Drives are capturing share in edge analytics nodes requiring millisecond retrieval. Cloud Storage leads growth trajectory as hybrid deployment models gain traction among banking and government end users seeking elastic capacity without capital-heavy infrastructure builds.
China's MIIT enforces data-localization rules that restrict cross-border video archive transfers, while India's BIS certification mandates thermal and electromagnetic resilience standards for storage hardware deployed in outdoor enclosures. TRAI guidelines on telecommunications infrastructure indirectly shape bandwidth pricing that affects cloud-versus-on-premise deployment economics. Stakeholders must monitor evolving encryption requirements from national cybersecurity regulators as facial recognition integration deepens across transportation and banking verticals.
Market Dynamics
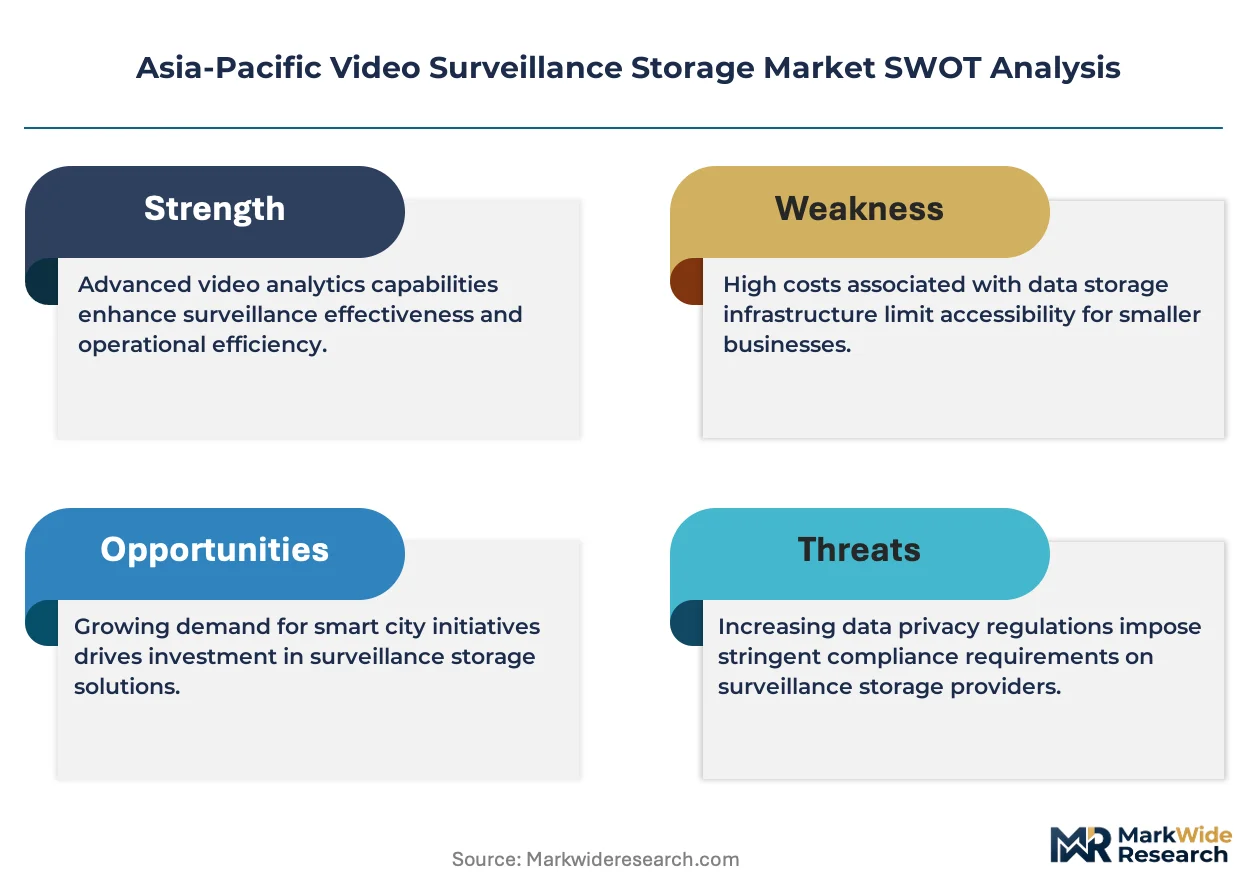
Data-localization mandates across Asia-Pacific jurisdictions are fragmenting storage procurement into sovereignty-compliant silos, forcing vendors to engineer region-specific firmware and certification stacks rather than shipping universal hardware platforms.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian municipalities are accelerating centralized video retention system procurement for urban safety networks. These projects specify multi-petabyte scalability with decade-long retention horizons.
- India's extended retention regulations:State government mandates for prolonged urban surveillance footage archiving are compressing replacement cycles for legacy storage arrays. Municipal police departments now specify minimum seven-year retention windows.
- MIIT cybersecurity compliance:China's critical infrastructure standards compel storage hardware vendors to certify data sovereignty and encryption modules. This creates captive demand for domestically certified supply chains.
Market Restraints
- HDD supply concentration:Rotating media manufacturing concentrates in Thailand and Malaysia, exposing procurement timelines to regional flooding and component shortages. Single-source dependencies extend lead times during supply shocks.
- Cross-border data friction:India's BIS thermal and electromagnetic resilience certification adds six to nine months to hardware qualification. Foreign vendors face redundant testing for outdoor enclosure deployments.
- Edge analytics substitution:On-camera solid-state storage with embedded inference engines reduces backhaul bandwidth requirements. This displaces centralized array capacity in distributed retail and warehouse installations.
Strategic Opportunities
- Vietnam and Indonesia smart city buildouts:Secondary Southeast Asian markets remain underpenetrated for municipal-scale storage procurement. These jurisdictions lack established vendor relationships, creating entry paths for certified competitors.
- Hybrid cloud orchestration:Banking and government end users seek elastic burst capacity for forensic retrieval without capital-heavy infrastructure builds. Managed service providers can capture recurring revenue through subscription retention models.
- Facial recognition integration mandates:Transportation and banking verticals are embedding biometric analytics into retention workflows. Storage systems must now support frame-level metadata indexing alongside raw video streams.
Industry Challenges
- Legacy analog migration complexity:Government and enterprise buyers operate hybrid environments with decades-old coaxial infrastructure. Storage vendors must engineer backward-compatible ingestion gateways without compromising throughput.
- Forensic chain-of-custody certification:Judicial admissibility requirements demand tamper-evident logging and write-once-read-many media. Vendors face extended validation cycles with national cybersecurity regulators.
- Specialized firmware talent scarcity:Sequential write optimization and vibration-resistant error correction require niche engineering expertise. Competition for storage controller architects intensifies against enterprise IT and automotive sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Video Surveillance Storage Market |
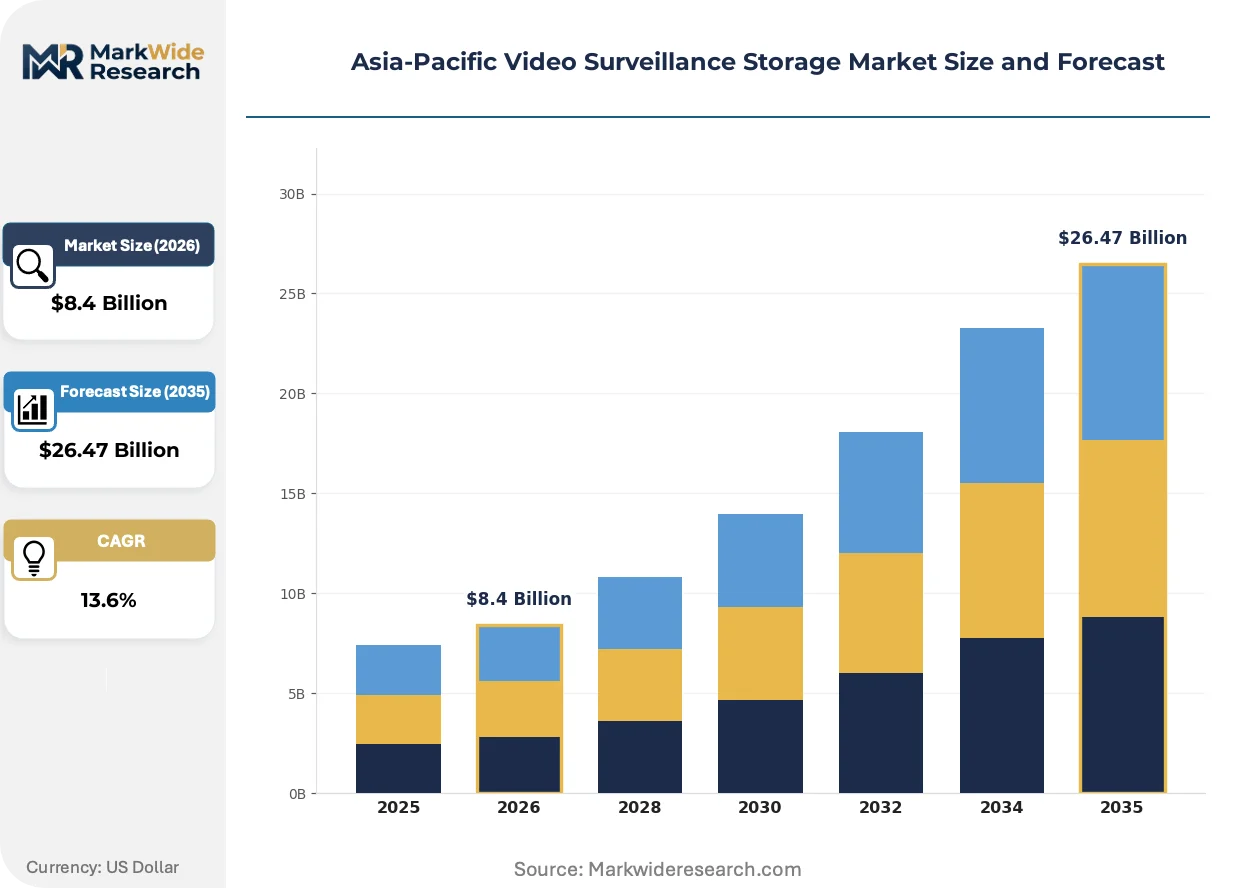
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Hard Disk Drives, Solid State Drives, Network Attached Storage, Cloud Storage Deployment Model: On-Premise, Hybrid, Cloud-Based, Edge End User: Retail, Transportation, Banking, Government Technological Feature: Motion Detection, Remote Access, Analytics Integration, Video Compression |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Dell Technologies Inc., Seagate Technology LLC, Huawei Technologies Co., Ltd., Western Digital Corporation, Honeywell International Inc., NetApp, Zhejiang Uniview Technologies Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Video Surveillance Storage Market Trends and Innovations
Storage architecture is bifurcating between centralized cloud-scale repositories and distributed edge appliances, with middleware layers emerging to unify retention policies across hybrid deployments.
Software-defined storage is decomposing proprietary hardware lock-in across municipal and enterprise deployments. Transit authorities in Singapore and Sydney are adopting vendor-agnostic storage virtualization to pool capacity across multi-generational disk arrays. This technology is compressing switching costs and enabling incremental procurement from competing suppliers without forklift upgrades.
China's MIIT data-localization enforcement restricts cross-border video archive transfers and mandates domestic encryption certification. Storage vendors must maintain separate firmware branches for China-bound hardware, fragmenting engineering resources and extending release cycles. Banking and critical infrastructure operators in Shanghai and Shenzhen now specify MIIT-compliant modules as non-negotiable procurement criteria.
Long-term retention contracts are displacing capital purchase models among provincial police departments and casino operators. Managed service providers in Australia and South Korea now bundle storage hardware, maintenance, and cloud burst capacity into single-vendor agreements. This shift concentrates buyer relationships with integrators possessing sovereign data center footprints and cybersecurity clearances.
Asia-Pacific Video Surveillance Storage Market Segmentation
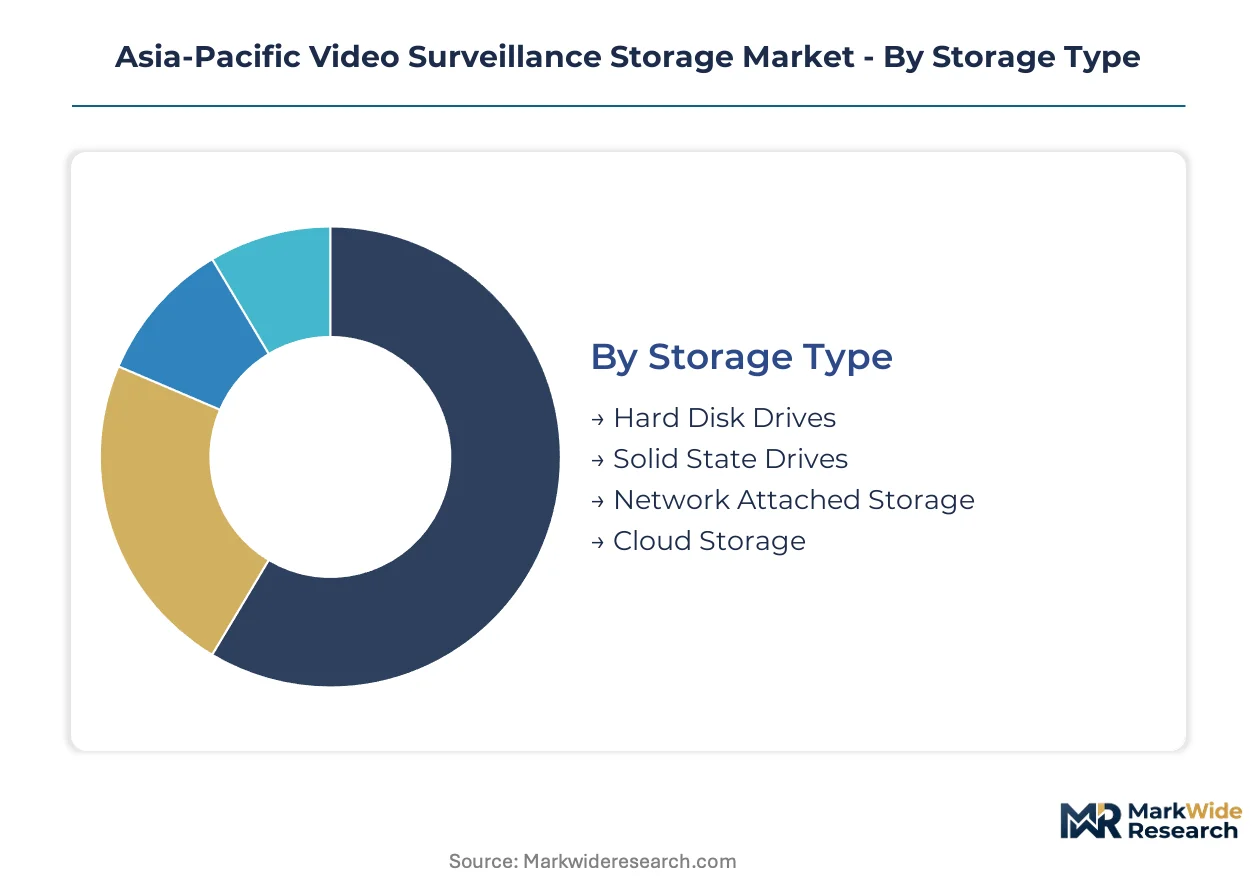
Video surveillance storage procurement diverges sharply across infrastructure layers, with retention economics and data sovereignty mandates dictating hardware-versus-cloud allocation. Municipal buyers in China and India weight total cost of ownership differently than Southeast Asian retail chains optimizing for bandwidth constraints.
Storage Type:
Channel mix varies by petabyte scale: systems integrators push disk arrays for municipal contracts, while value-added resellers dominate edge SSD deployments for retail franchises.
- Hard Disk Drives:Rotating media with vibration-resistant mechanics and firmware tuned for 24/7 sequential write ingestion from hundreds of concurrent camera channels. China's provincial police departments and India's state governments specify multi-petabyte HDD arrays for seven-year retention mandates, though Thailand-Malaysia manufacturing concentration exposes procurement to flood-related supply shocks.
- Solid State Drives:Flash-based storage delivering millisecond retrieval for edge analytics nodes requiring real-time inference. Singapore transit authorities and Australian casino operators deploy SSDs at camera-adjacent aggregation points where thermal resilience and rapid forensic search outweigh cost premiums.
- Network Attached Storage:IP-connected enclosures serving mid-tier enterprise deployments with centralized management.
- Cloud Storage:Elastic repositories accessed via subscription models, gaining traction among South Korean banking consortia seeking burst capacity without capital builds.
Hard Disk Drives dominate installed base. Cloud Storage is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise builds from operational-expense cloud subscriptions favored by budget-constrained municipal buyers.
- On-Premise:Dedicated hardware arrays within buyer-controlled facilities requiring full lifecycle ownership. China's MIIT data-localization rules compel critical infrastructure operators in Shanghai and Shenzhen to maintain sovereign physical storage, disqualifying cross-border cloud alternatives.
- Hybrid:Orchestrated architectures pooling on-premise capacity with cloud burst for forensic retrieval. Australian state police departments and South Korean casino operators adopt this model to balance compliance with elastic demand spikes.
- Cloud-Based:Fully outsourced retention with managed service providers bearing infrastructure burden.
- Edge:Distributed appliances reducing backhaul bandwidth through localized processing. Vietnam and Indonesia smart city buildouts favor edge nodes where telecommunications infrastructure remains underdeveloped.
On-Premise retains the largest revenue share. Hybrid deployments are climbing the fastest as sovereignty and elasticity requirements converge.
End User:
Application-specific retention periods and judicial admissibility standards fragment procurement specifications across verticals.
- Government:Municipal and national security agencies mandating decade-long retention with chain-of-custody certification. India's state government directives for extended urban surveillance footage archiving compress replacement cycles for legacy arrays.
- Banking:Financial institutions integrating facial recognition into retention workflows with frame-level metadata indexing. China's banking regulators in Beijing and Shenzhen specify MIIT-compliant encryption modules as non-negotiable criteria.
- Transportation:Transit authorities requiring vibration-resistant storage for mobile and fixed infrastructure.
- Retail:Franchise operators optimizing for loss prevention with shorter retention horizons and edge-analytics substitution.
Government commands the highest petabyte volumes. Banking represents the steepest expansion trajectory as biometric integration deepens.
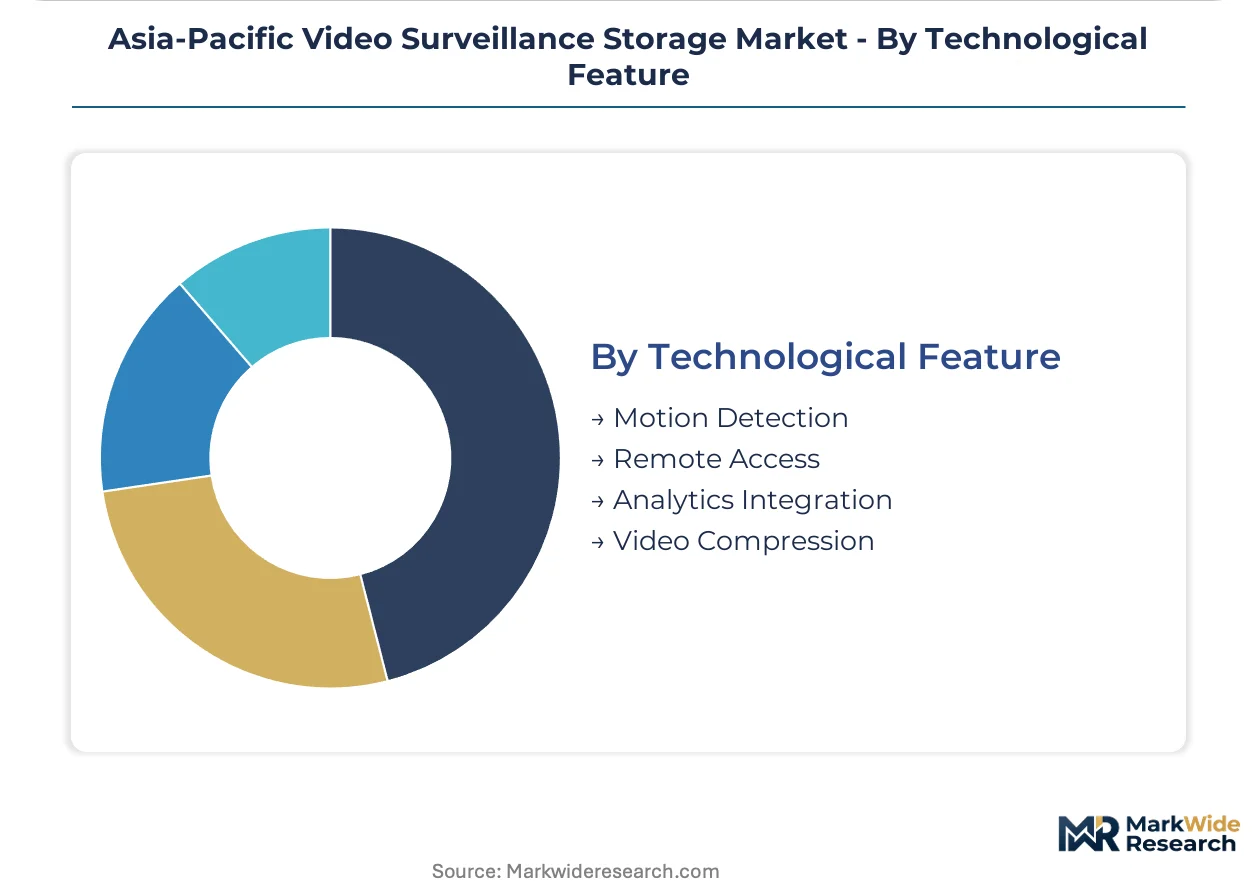
Technological Feature:
Maturity gradients separate baseline compression from advanced analytics integration, with pricing stratifying across certification-grade and standard-tier implementations.
- Analytics Integration:Embedded inference engines enabling real-time object recognition and behavioral analysis. Singapore's Land Transport Authority and Sydney's transit networks deploy storage systems supporting simultaneous video ingestion and AI workload processing.
- Video Compression:Algorithmic reduction of storage footprint through H.265 and proprietary codecs. Municipal buyers across Southeast Asia specify compression ratios that extend retention without array expansion.
- Motion Detection:Event-triggered recording reducing write volume and extending media lifespan.
- Remote Access:Secure portal architectures for distributed forensic review.
Video Compression saturates baseline deployments. Analytics Integration is gaining share fastest as transportation and banking verticals mandate biometric capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Guangzhou-Shenzhen-Hong Kong Express Rail Link underwrites China's surveillance storage dominance. Singapore's Tuas Mega Port anchors Southeast Asian demand for maritime security systems. Australia's East Coast Rail Link shapes procurement for transportation infrastructure monitoring.
China
Provincial police departments in Guangdong and Jiangsu drive multi-petabyte HDD array procurement for smart city networks. MIIT cybersecurity standards compel domestic encryption certification for all critical infrastructure storage hardware. Shanghai's Pudong district exemplifies sovereign data center construction where banking and transit operators mandate MIIT-compliant modules.
India
State government mandates for seven-year urban surveillance footage retention compress replacement cycles for legacy storage arrays. BIS thermal and electromagnetic resilience certification adds six to nine months to foreign vendor hardware qualification. Maharashtra's Mumbai-Pune corridor concentrates municipal procurement for centralized video retention systems.
Australia
State police departments adopt hybrid deployment models balancing on-premise capacity with cloud burst for forensic retrieval spikes. TRAI-equivalent telecommunications regulations shape bandwidth pricing affecting cloud-versus-on-premise economics. Sydney's transit authority deploys vendor-agnostic storage virtualization across multi-generational disk arrays.
South Korea
Casino operators and banking consortia seek elastic burst capacity through subscription retention models with managed service providers. National cybersecurity regulators enforce evolving encryption requirements as facial recognition integration deepens. Seoul's metropolitan police specify decade-long retention horizons with chain-of-custody certification for judicial admissibility.
Singapore
Transit authorities deploy storage systems supporting simultaneous video ingestion and AI workload processing for real-time behavioral analysis. Land Transport Authority procurement specifications mandate frame-level metadata indexing alongside raw video streams. The Tuas port cluster drives demand for vibration-resistant storage in maritime security applications.
Asia-Pacific Video Surveillance Storage Market Competitive Landscape
Concentration sits with integrated camera-to-storage ecosystem providers and surveillance-optimized component specialists. The vendor base spans vertically integrated security conglomerates, dedicated storage hardware fabricators, and managed service operators with sovereign data center footprints. Three archetypes dominate: municipal-scale system integrators, edge-storage appliance specialists, and hybrid cloud orchestration providers. Competitive moves center on MIIT compliance certification for China-bound hardware and strategic partnerships for hybrid deployment middleware.
Within the integrated ecosystem tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify vendors anchoring large-scale municipal contracts through camera-to-storage vertical integration. Seagate Technology LLC occupies a position among surveillance-optimized component specialists, representing fabricators focused on workload-rated rotating media rather than full system integration. These three companies illustrate the bifurcation between end-to-end platform providers and dedicated storage hardware suppliers competing for procurement specification slots across Asia-Pacific smart city deployments.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Dell Technologies Inc. |
| Seagate Technology LLC |
| Huawei Technologies Co., Ltd. |
| Western Digital Corporation |
| Honeywell International Inc. |
| NetApp |
| Zhejiang Uniview Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day component lead times for surveillance-optimized HDD controllers concentrate pricing power with Thailand-Malaysia fabricators, while municipal buyers in China and India face step-function cost escalations when qualifying secondary suppliers through BIS and MIIT certification channels.
Pricing Analysis
Volume-discount tiering separates MIIT-certified premium modules from standard enterprise-grade arrays and economy-tier refurbished enclosures. Price differentiation hinges on encryption certification depth and sovereign data center proximity, with Chinese critical infrastructure operators absorbing 15-25% premiums for domestic compliance. Cost compression in standard-tier HDD arrays is intensifying because Southeast Asian municipal budgets favor lowest-qualified-bid procurement. Retail franchise operators across Vietnam and Indonesia exhibit highest price sensitivity, whereas Australian state police departments prioritize chain-of-custody certification over unit economics.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore trade lane elevates inbound logistics costs for NAND flash controllers and precision spindle motors bound for regional assembly plants. Manufacturing concentrates in Thailand, Malaysia, and coastal China, with rotating media fabrication drawing from rare earth magnet feedstock and aluminum substrate supply pools. Single-source vulnerability pervades vibration-resistant actuator arm production, where Japanese precision component houses anchor tier-one supply. Distribution runs through systems integrators for municipal contracts and value-added resellers for edge SSD deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against edge-analytics substitution as on-camera solid-state storage with embedded inference engines displaces centralized array capacity in distributed installations.
For Market Incumbents: Compound firmware certification advantages by maintaining parallel MIIT and BIS validation tracks that exhaust new entrant qualification timelines. Anchor municipal relationships through captive supply of sovereign data center construction services alongside storage hardware. Prioritize acquisition of edge-analytics appliance specialists before inference engines commoditize camera-adjacent retention nodes.
For New Entrants and Emerging Players: Differentiate on hybrid cloud orchestration middleware that unifies retention policies across legacy on-premise arrays and burst-capacity cloud repositories. Target underpenetrated provincial police departments in Indonesia and Vietnam where established vendor relationships remain unformed. Lead with subscription-based managed retention models that shift capital expenditure burdens to operational budgets.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive surveillance storage divisions lacking standalone scale. Frame long-term viability around 5-10 year data sovereignty enforcement trajectories across Asia-Pacific jurisdictions. Monitor BIS certification queue lengths as an inflection indicator for foreign vendor market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Fast-Track | Accelerates hardware qualification for Shanghai and Shenzhen critical infrastructure procurement windows. |
| Hybrid Cloud Orchestration Platform | Enables Australian state police to burst forensic retrieval capacity without sovereign data center expansion. |
| Edge-Analytics Appliance Acquisition | Captures inference-engine capabilities before on-camera storage displaces centralized array demand. |
| Subscription Retention Model Rollout | Aligns South Korean banking consortia procurement with operational-expense budget cycles. |
| Vibration-Resistant Firmware R&D Partnership | Addresses Singapore Tuas port maritime security specifications for mobile storage deployments. |
Research Methodology
A spread of perspectives from municipal procurement officers, storage hardware engineering leads, systems integration specialists, and sovereign data center operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, MIIT certification registries, BIS technical standards filings, and hyperscaler capex disclosures. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation against national smart city budget allocations anchored volume estimates.
Segmentation dimensions modeled span storage type, deployment architecture, end-user vertical, and technological feature integration depth across the projection horizon. CAGRs derived from fitted growth curves applied to petabyte-scale procurement trajectories, with cross-validation against historical replacement cycles for legacy analog-to-digital migration waves. Industry-specific forecast inputs incorporated TRAI bandwidth pricing elasticity and provincial retention mandate enforcement timelines.
Material uncertainties — supply shock disruptions to Thailand-Malaysia HDD manufacturing, abrupt encryption standard revisions from national cybersecurity regulators, and edge-analytics substitution velocity — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
North America Smart Home Security Cameras Market