

Autonomous UAM Exterior Sensor Integration Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous UAM Exterior Sensor Integration Kits Market Insights
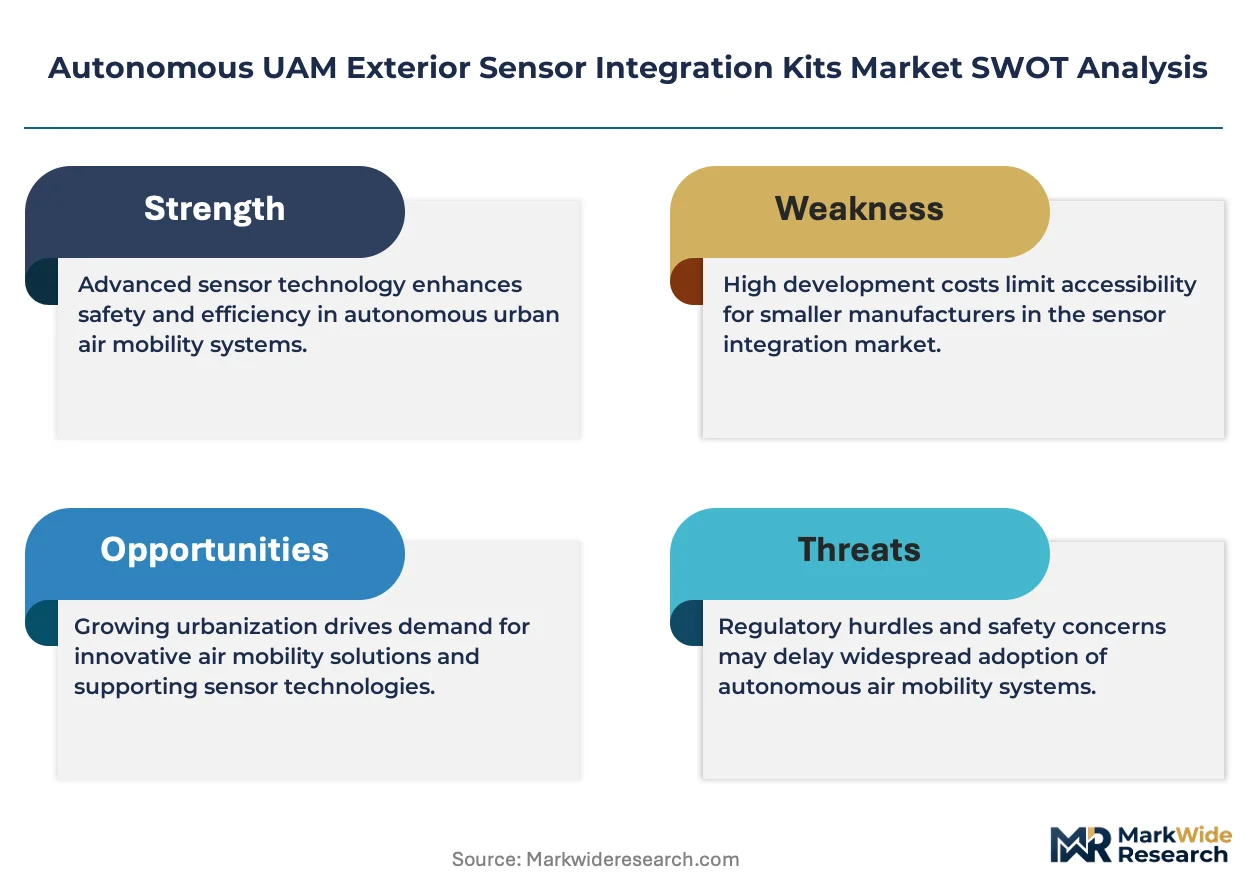
The gap between aviation-grade redundancy and cost-optimized commercial tiers is recalibrating procurement patterns across the UAM sensor stack. Honeywell Aerospace leverages its Part 23 certification heritage to anchor premium positioning for lidar-radar fusion arrays. uAvionix competes on miniaturized transponder-integrated sensor nodes purpose-built for Part 107 operations. Garmin differentiates through dual-use avionics architectures that span certified and experimental aircraft categories.
Autonomous UAM exterior sensor integration kits comprise multi-modal perception assemblies—typically encompassing solid-state lidar with centimeter-range resolution, millimeter-wave radar arrays, and thermal-visual camera clusters—engineered for real-time obstacle detection in GPS-degraded urban canyons. These systems enable beyond-visual-line-of-sight navigation for electric vertical take-off and landing platforms operating in dense metropolitan airspace. Lidar modules command the dominant share of kit value owing to their indispensable role in precision landing and terrain mapping, while frequency modulated continuous wave radar systems represent the fastest-expanding technology segment as manufacturers pursue all-weather operational envelopes. Fleet operators constitute the most concentrated end-user pool, driving volume through standardized retrofit programs across emerging eVTOL fleets.
The FAA's detect-and-avoid performance standards under 14 CFR Part 89, alongside EASA's SC-VTOL certification framework, are mandating redundant sensor architectures that elevate kit complexity and validation costs. China's CAAC unmanned aviation regulations and GB standards for low-altitude flight management are similarly reshaping product specifications for manufacturers targeting the Shenzhen-Guangzhou corridor. Stakeholders must weigh certification jurisdiction against production scale when selecting sensor modality combinations and integration partners.
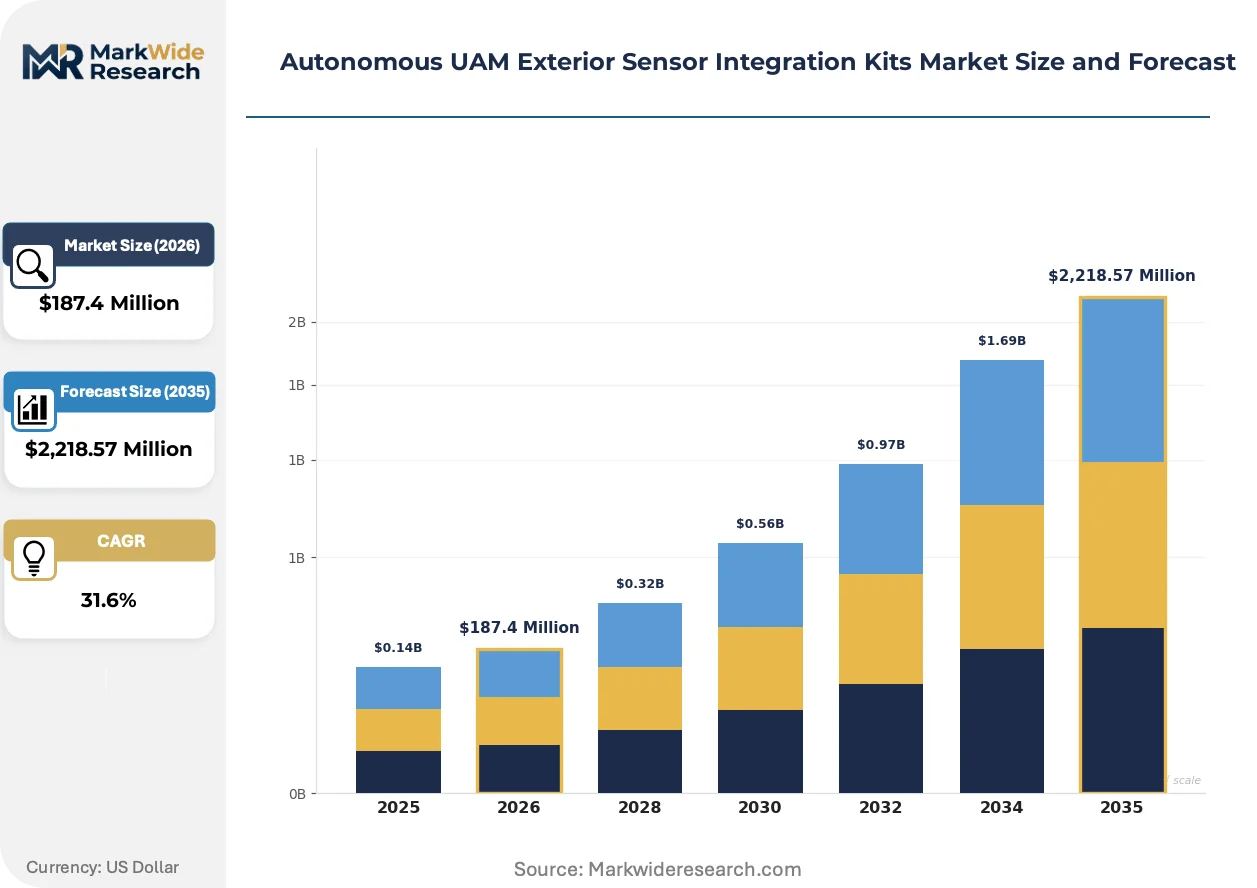
Market Dynamics
The FAA's tightening detect-and-avoid certification thresholds under 14 CFR Part 89 are forcing sensor kit architectures toward redundant multi-modal configurations, compressing supplier margins while elevating validation costs for eVTOL platform integrators.
Growth Catalysts
- FAA Part 89 Mandates:Performance standards for beyond-visual-line-of-sight operations require certified detect-and-avoid capabilities, creating baseline demand for lidar-radar fusion arrays across commercial eVTOL fleets.
- Solid-State Lidar Maturation:Semiconductor advances in flash and MEMS beam-steering architectures reduce unit costs while maintaining centimeter-range precision for urban canyon navigation.
- Shenzhen Manufacturing Clusters:China's concentrated drone and sensor component ecosystem enables rapid prototyping and volume scaling for export-oriented kit assemblers targeting global UAM programs.
Market Restraints
- Indium Phosphide Wafer Supply:Solid-state lidar's reliance on 1550nm wavelength sources ties kit pricing to constrained III-V semiconductor foundry capacity concentrated in Taiwan and the United States.
- EASA SC-VTOL Validation Burden:The European framework's mean-time-between-failure requirements for sensor redundancy add 18-24 months to certification timelines, freezing procurement decisions.
- Visual Line-of-Sight Piloting:Regulatory exemptions for traditional helicopter and light aircraft operations in uncontrolled airspace delay the economic imperative for full autonomy in certain metropolitan corridors.
Strategic Opportunities
- India UAM Corridors:The country's PLI scheme for drone components and proposed low-altitude flight management regulations position Bengaluru and Hyderabad as emerging demand centers for cost-optimized sensor kits.
- Frequency Modulated Continuous Wave Radar:FMCW architectures enable simultaneous velocity and range detection in precipitation, opening all-weather revenue streams for kit suppliers serving medical transport and logistics operators.
- Performance-Based Navigation Integration:FAA NextGen and EUROCONTROL trajectory management initiatives create pathways for sensor-derived positioning to supplement GNSS in urban terminal areas.
Industry Challenges
- Systems Safety Engineering Talent:The intersection of aviation software assurance (DO-178C) and machine learning perception validation requires hybrid skill sets scarce in both aerospace and autonomous vehicle labor pools.
- Sensor-to-Avionics Integration:eVTOL airframe designers face thermal management and electromagnetic interference constraints when packaging multi-spectral arrays within compact nacelle geometries.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous UAM Exterior Sensor Integration Kits Market Trends and Innovations
Sensor fusion architectures are converging on common data bus standards while thermal-visual imaging modules compress form factors for aerodynamic integration. These developments compress the gap between experimental and certifiable system configurations.
Frequency modulated continuous wave lidar is rewriting the economics of all-weather perception for electric aircraft. Archer Aviation and Joby Aviation have both specified FMCW units for their production eVTOL platforms. The technology is compressing the traditional trade-off between solid-state reliability and mechanical scanning range.
China's GB standards for low-altitude flight management are mandating broadcast remote identification and network-based detect-and-avoid for unmanned systems above 25 kilograms. CAAC's framework is compressing the timeline for airworthiness certification of integrated sensor kits. Manufacturers targeting the Shenzhen-Guangzhou corridor must embed BeiDou augmentation and domestic encryption protocols.
Fleet operators are consolidating procurement through long-term sensor-as-a-service agreements rather than capital purchases. Beta Technologies and Wisk Aero have both moved to subscription models covering hardware refresh and algorithm updates. This shift is most visible in California's aerospace corridors where venture-backed eVTOL developers prioritize operational expenditure predictability over asset ownership.
Autonomous UAM Exterior Sensor Integration Kits Market Segmentation
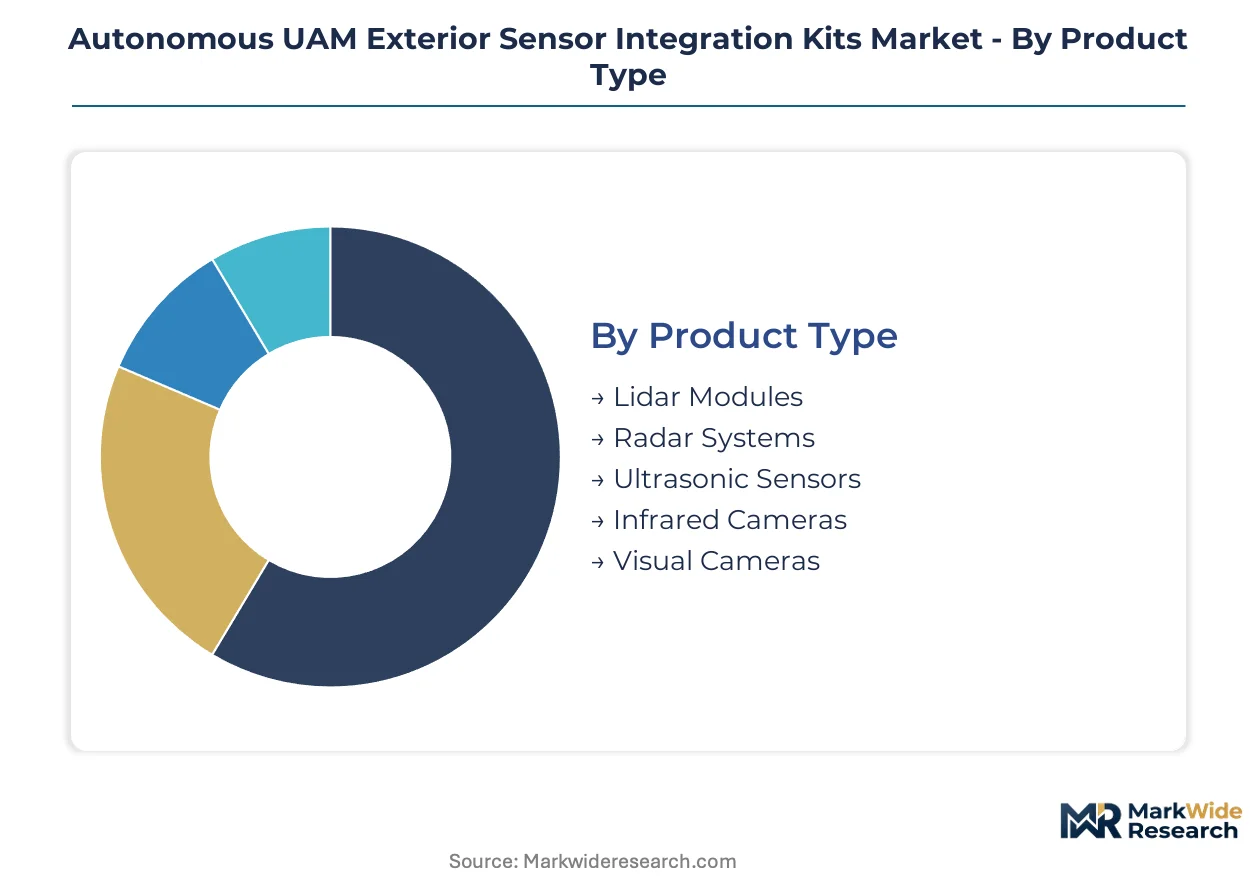
Sensor kit procurement patterns diverge sharply across application contexts and certification tiers. Fleet operators prioritize standardized retrofit bundles for volume scaling, while OEM manufacturers demand bespoke architectures aligned with specific airframe designs.
Product Type:
Upgrade cycles vary by component durability and technology obsolescence rates, with solid-state modules extending replacement intervals versus mechanical alternatives.
- Lidar Modules:Solid-state flash and MEMS beam-steering architectures deliver centimeter-range precision for precision landing and terrain mapping. California's aerospace corridors concentrate demand from eVTOL developers pursuing FAA Part 89 certification for beyond-visual-line-of-sight operations.
- Radar Systems:Millimeter-wave arrays enable all-weather obstacle detection through precipitation and degraded visibility. Shenzhen's manufacturing clusters drive volume production for export-oriented kit assemblers targeting global UAM programs.
- Ultrasonic Sensors:Short-range proximity detection for hover stability and ground collision avoidance in terminal maneuvering.
- Infrared Cameras:Thermal signature detection for nighttime operations and heat-source identification in cluttered airspace.
- Visual Cameras:Stereo vision arrays supporting optical flow navigation and visual-inertial odometry in GPS-denied environments.
Lidar modules sit at the top of the volume ranking, with radar systems climbing the fastest as manufacturers pursue all-weather operational envelopes.
Technology:
Cost tiers separate aviation-grade certified implementations from experimental-grade alternatives, with validation burden driving price multiples between adjacent tiers.
- Time-of-Flight:Direct time-of-measurement lidar dominates commercial deployments for its deterministic latency characteristics. Fleet operators in California standardize on ToF architectures for retrofit program compatibility.
- Frequency Modulated Continuous Wave:Simultaneous velocity and range extraction enables Doppler-aware tracking in dynamic urban airspace. Archer Aviation and Joby Aviation have specified FMCW units for production eVTOL platforms.
- Pulse Doppler:Conventional radar modality for long-range target acquisition and weather penetration.
- Structured Light:Active illumination patterns for high-resolution depth mapping at close range.
- Thermal Imaging:Uncooled microbolometer arrays for passive infrared scene analysis.
Time-of-Flight commands the largest installed base, while Frequency Modulated Continuous Wave gains share fastest through its velocity-measurement advantages.
Application:
Customer type dictates performance requirements and certification rigor, with passenger-carrying platforms facing stricter redundancy mandates than unmanned cargo alternatives.
- Urban Air Mobility:Passenger eVTOL operations demand triple-redundant sensor configurations meeting EASA SC-VTOL mean-time-between-failure thresholds. European validation timelines of 18-24 months freeze procurement decisions for this segment.
- Cargo Delivery:Unmanned logistics platforms operate under Part 107 exemptions with reduced redundancy requirements. India's PLI scheme for drone components positions Bengaluru and Hyderabad as emerging demand centers.
- Emergency Response:Medical transport operators prioritize all-weather availability and rapid deployment protocols.
- Aerial Surveillance:Persistent observation missions favor extended-range detection and low-power consumption profiles.
- Infrastructure Inspection:Close-proximity flight near power lines and towers requires millimeter-precision positioning.
Urban Air Mobility leads absolute kit value, with Cargo Delivery expanding most quickly through regulatory exemptions enabling faster fleet deployment.
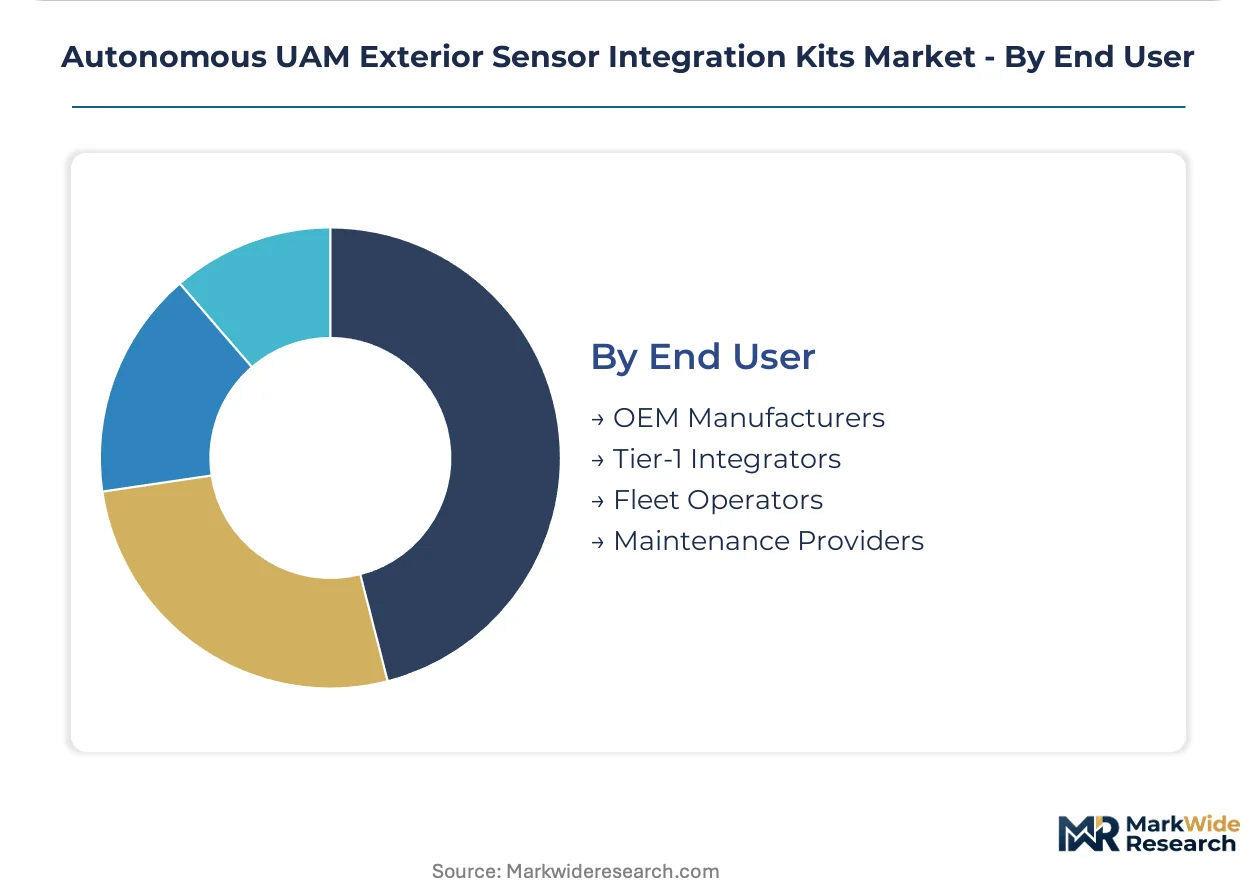
End User:
Supply concentration among Tier-1 integrators shapes procurement access for downstream participants, with captive relationships limiting vendor switching.
- OEM Manufacturers:Airframe designers specify custom sensor geometries for aerodynamic integration and thermal management. Beta Technologies and Wisk Aero have adopted sensor-as-a-service subscription models covering hardware refresh cycles.
- Tier-1 Integrators:Consolidated procurement platforms aggregate demand across multiple OEM programs for volume pricing leverage.
- Fleet Operators:Standardized retrofit programs drive repeat purchases for emerging eVTOL fleets seeking operational expenditure predictability.
- Maintenance Providers:Aftermarket replacement demand concentrates on lidar module failures and calibration drift correction.
Fleet operators dominate unit volume, with OEM manufacturers representing the steepest expansion trajectory through production ramp commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systems safety engineering talent concentrates in California's aerospace corridors and Shenzhen's manufacturing clusters, anchoring production capacity for lidar-radar fusion arrays and miniaturized transponder nodes.
United States
FAA Part 89 detect-and-avoid mandates drive procurement of redundant multi-modal sensor configurations for beyond-visual-line-of-sight eVTOL operations. The FAA's tightening performance standards compress supplier margins while elevating validation costs for platform integrators. California's aerospace corridors host Beta Technologies and Wisk Aero, both transitioning to sensor-as-a-service subscription models covering hardware refresh cycles.
China
CAAC unmanned aviation regulations and GB standards for low-altitude flight management mandate broadcast remote identification for systems above 25 kilograms. Manufacturers targeting the Shenzhen-Guangzhou corridor must embed BeiDou augmentation and domestic encryption protocols. Shenzhen's concentrated drone and sensor component ecosystem enables rapid prototyping and volume scaling for export-oriented kit assemblers.
Germany
EASA SC-VTOL certification framework mean-time-between-failure requirements for sensor redundancy add 18-24 months to validation timelines. The European regulator's stringent thresholds freeze procurement decisions for passenger-carrying platforms. Bavaria's precision engineering base supports Tier-1 integrators aggregating demand across multiple OEM programs for volume pricing leverage.
India
The PLI scheme for drone components and proposed low-altitude flight management regulations position Bengaluru and Hyderabad as emerging demand centers. Cost-optimized sensor kits serve cargo delivery platforms operating under reduced redundancy requirements. Fleet operators in these corridors prioritize standardized retrofit bundles for operational expenditure predictability over capital purchases.
France
EASA alignment drives certification rigor for triple-redundant sensor configurations in urban air mobility applications. Thales and Safran anchor domestic avionics expertise supporting FMCW radar integration for all-weather operational envelopes. The Paris-Saclay cluster concentrates systems integration talent for machine learning perception validation.
Autonomous UAM Exterior Sensor Integration Kits Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sensor stack, with semiconductor foundries and III-V wafer fabricators controlling upstream chokepoints for 1550nm wavelength sources. The vendor base stratifies between aviation-grade certified integrators and experimental-grade assemblers serving Part 107 exemptions. Three archetypes dominate: legacy aerospace conglomerates leveraging Part 23 heritage, miniaturization specialists targeting reduced regulatory tiers, and dual-use avionics architects spanning certified and experimental categories. Capacity expansion in Taiwan and United States foundries, alongside strategic partnerships for BeiDou-compliant encryption modules, represent the dominant competitive moves.
Within the legacy aerospace tier, Honeywell Aerospace and Collins Aerospace exemplify certification-anchored positioning for premium lidar-radar fusion arrays. Garmin occupies a position bridging certified and experimental aircraft categories through dual-use avionics architectures. uAvionix represents the miniaturization specialist archetype, with its name signaling focus on unmanned aviation transponder-integrated nodes purpose-built for reduced regulatory tiers.
| Leading Market Players |
|---|
| Honeywell Aerospace |
| Garmin |
| Teledyne FLIR |
| uAvionix |
| L3Harris Technologies |
| Collins Aerospace |
| Thales |
| Safran |
| Leonardo |
| Others |
Pricing and Supply Chain Analysis
Captive integration into III-V semiconductor foundries anchors supply positions and pricing power for solid-state lidar manufacturers targeting FAA Part 89 certification tiers. Taiwan's concentrated InP wafer capacity and Shenzhen's sensor assembly clusters create divergent cost structures across aviation-grade and commercial-tier kit suppliers.
Pricing Analysis
The bundled-vs-unbundled service split separates sensor-as-a-service subscription models from capital purchase arrangements. Three-tier pricing structure across premium, standard, and economy levels tracks certification rigor, with EASA SC-VTOL validation adding substantial premiums over Part 107-exempt tiers. Cost compression in commercial-grade segments is intensifying because Shenzhen manufacturers scale MEMS beam-steering volumes. Fleet operators exhibit highest price sensitivity, while OEM manufacturers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Workforce availability in Taiwan's semiconductor foundries and Shenzhen's electronics manufacturing zones shapes upstream capacity for 1550nm wavelength sources and compact radar arrays. The supply chain draws from Taiwan's InP wafer fabrication, China's MEMS foundries, and California's precision optics clusters. Indium phosphide substrate constraints and single-source vulnerability for aviation-grade lidar emitters create chokepoint exposure. Distribution runs through Tier-1 avionics integrators aggregating OEM demand for volume pricing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Autonomous UAM Exterior Sensor Integration Kits Market functions as a stable compounder, with regulatory certification mandates for beyond-visual-line-of-sight operations generating durable replacement demand across eVTOL fleet ramp cycles.
For Market Incumbents: Anticipate margin compression from Shenzhen-based cost-optimized entrants by deepening backward integration into MEMS foundry partnerships and accelerating FAA Part 89 validation pipelines. Lock long-term sensor-as-a-service agreements with California-based fleet operators to secure recurring revenue streams before subscription models commoditize. For New Entrants and Emerging Players: Enter via India's cargo delivery corridor, where PLI scheme incentives and reduced redundancy requirements for Part 107 platforms create the most penetrable demand pool. Target Bengaluru and Hyderabad fleet operators with standardized retrofit bundles priced for operational expenditure predictability rather than capital sale premiums. For Investors and Strategic Acquirers: Roll-up economics work for miniaturization specialists because EASA SC-VTOL validation timelines freeze procurement decisions and strand mid-tier vendors without certification heritage. Monitor FAA detect-and-avoid rulemaking velocity as the inflection signal—accelerated Part 89 enforcement compresses the window for uncertified market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Platform Launch | Subscription revenue models align with fleet operator preference for operational expenditure predictability in California corridors. |
| FAA Part 89 Certification Fast-Track | Accelerated validation pipelines capture procurement decisions frozen by EASA SC-VTOL timeline uncertainty. |
| Backward Integration into MEMS Foundries | Captive beam-steering chip supply insulates margins from Taiwan III-V wafer pricing volatility. |
| India PLI Scheme Manufacturing Localization | Bengaluru assembly footprints reduce landed costs for cargo delivery platforms under reduced redundancy tiers. |
| FMCW Radar Technology Licensing | All-weather velocity detection capabilities differentiate kit suppliers targeting medical transport operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with eVTOL platform engineers, FAA certification consultants, fleet procurement directors, and solid-state lidar R&D leads with secondary validation against FAA docket filings, EASA SC-VTOL guidance documents, CAAC unmanned aviation regulations, and customs trade data for sensor component flows. Bottom-up kit shipment estimates and top-down fleet deployment projections were triangulated to anchor volume assumptions.
Comparable historical periods spanning detect-and-avoid regulatory development in manned aviation informed the projection horizon's baseline assumptions. The analytical framework modeled segmentation across sensor modality, certification tier, end-use application, and geographic regulatory cluster. CAGRs were derived from fitted adoption curves incorporating fleet operator procurement timelines and OEM production ramp commitments. Forecast inputs included eVTOL airframe certification velocity and solid-state lidar cost reduction trajectories.
Inputs from regulatory dockets and supplier production disclosures were available through the study window; gaps in emerging fleet operator deployment schedules introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions regarding FAA Part 89 enforcement timing and EASA SC-VTOL validation throughput. Material deviation in CAAC low-altitude flight management rulemaking or InP wafer supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.