
 France Auto Loan Market | 2026-2036
France Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
France Auto Loan Market Insights
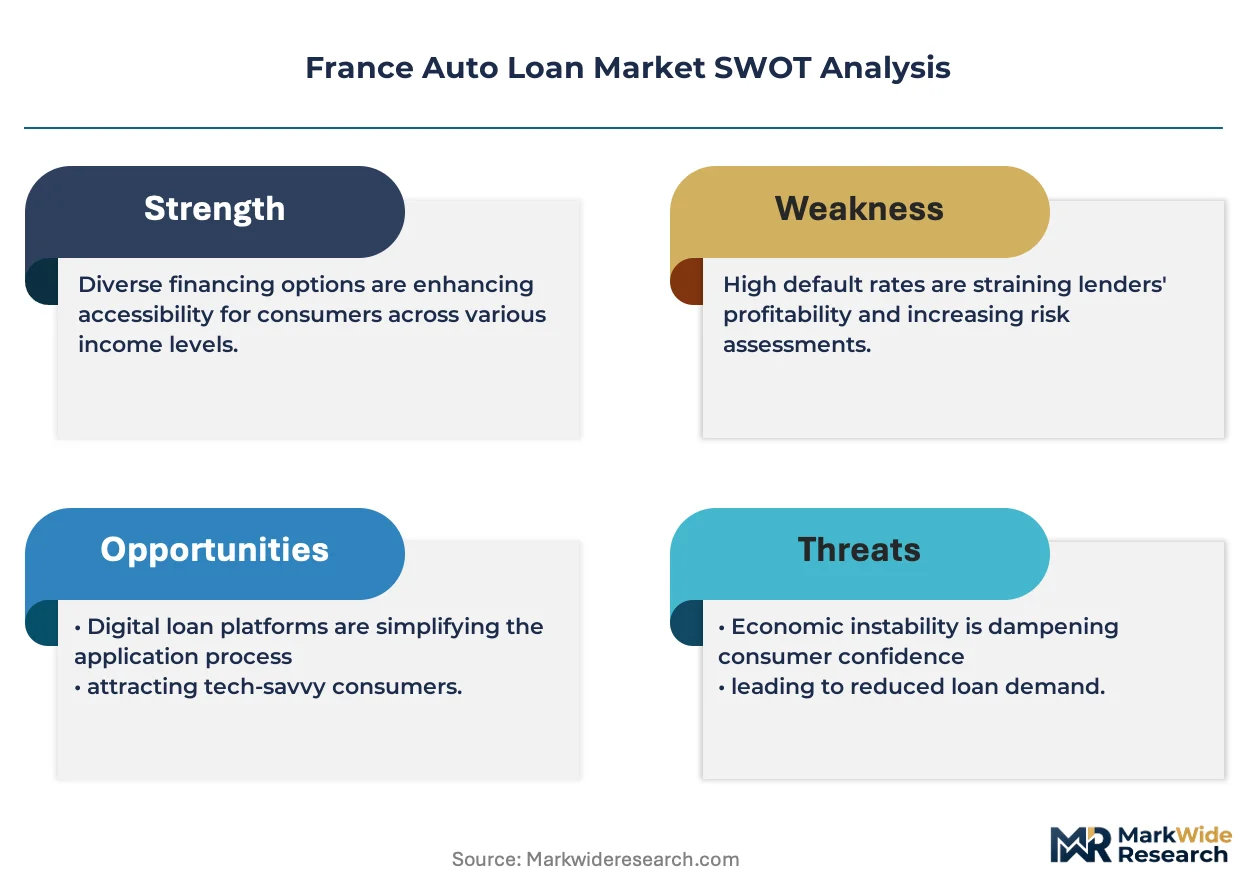
The EU Green Deal is recalibrating how French lenders underwrite automotive credit, tightening capital requirements for fossil-fuel exposure while rewarding green asset pools. BNP Paribas Personal Finance anchors its market position through captive partnerships with Renault and Stellantis distribution networks. Societe Generale differentiates via digital origination platforms that compress decision timelines for used-vehicle applicants. Credit Agricole leverages its cooperative branch density in rural France to sustain dominant penetration among small-business fleet borrowers.
France auto loans represent secured consumer credit instruments collateralized by vehicle titles, typically structured with fixed amortization schedules and loan-to-value ratios calibrated against depreciation curves. These instruments finance acquisition of passenger and commercial vehicles while transferring residual-value risk to borrowers or captive finance arms. New vehicle loans command the deepest margin pools due to manufacturer subvention programs and bundled insurance products, though electric vehicle financing represents the fastest-expanding segment as battery-electric model ranges broaden. Used vehicle loans occupy a mature, rate-sensitive tier where Cofidis and Franfinance compete on promotional rate positioning. Short-term and medium-term products dominate origination volumes, reflecting French regulatory caps on total cost of credit and borrower preference for rapid principal reduction.
France's national banking regulator, the Autorité de Contrôle Prudentiel et de Résolution, enforces strict debt-service-to-income thresholds that constrain maximum loan tenors, while European Central Bank climate stress-test protocols are reshaping green-asset classification for auto loan portfolios. The bonus écologique and malus écologique frameworks administered by the French Ministry of Economy directly alter effective vehicle pricing and therefore optimal loan structuring. Stakeholders must monitor how forthcoming EU digital euro pilots and open-finance mandates reshape payment-intermediation economics for automotive credit disbursement.
Market Dynamics
The bonus écologique subsidy framework is restructuring French auto loan origination patterns, redirecting credit flows toward battery-electric vehicles while compressing margins on internal-combustion financing. This policy-driven demand rotation is forcing lenders to recalibrate risk models and collateral valuation methodologies.
Growth Catalysts
- bonus écologique:The French Ministry of Economy's subsidy program reduces effective vehicle purchase prices, expanding addressable borrower pools for electric vehicle financing.
- Île-de-France commuter demand:Parisian fleet operators and individual borrowers in the capital region drive structured credit uptake for new vehicle acquisition.
- EU Green Deal capital requirements:Preferential treatment of green asset pools incentivizes French lenders to expand electric vehicle loan portfolios.
Market Restraints
- ACPR debt-service-to-income thresholds:The national banking regulator's strict caps constrain maximum loan tenors, limiting product flexibility for higher-value electric vehicles.
- Residual value uncertainty:Rapid battery technology evolution and policy shifts create collateral valuation risk for long-dated auto loans.
- Used vehicle rate sensitivity:Mature secondary-market financing faces margin compression as promotional rate competition intensifies among non-bank lenders.
Strategic Opportunities
- Rural cooperative branch networks:Credit Agricole's density in non-metropolitan France offers underexploited penetration for small-business fleet financing.
- Digital origination platforms:Compressed decision timelines for used-vehicle applicants create differentiation potential against traditional bank processes.
- EU digital euro pilots:Forthcoming payment-intermediation pilots may reshape disbursement economics for automotive credit.
Industry Challenges
- Climate stress-test compliance:European Central Bank protocols demand portfolio reclassification, requiring data infrastructure upgrades for green-asset tracking.
- malus écologique integration:Penalty frameworks complicate loan structuring for higher-emission vehicles, demanding real-time policy monitoring capabilities.
- Open-finance mandate adaptation:Regulatory data-sharing requirements force reconciliation between legacy core banking systems and API-driven architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Auto Loan Market |
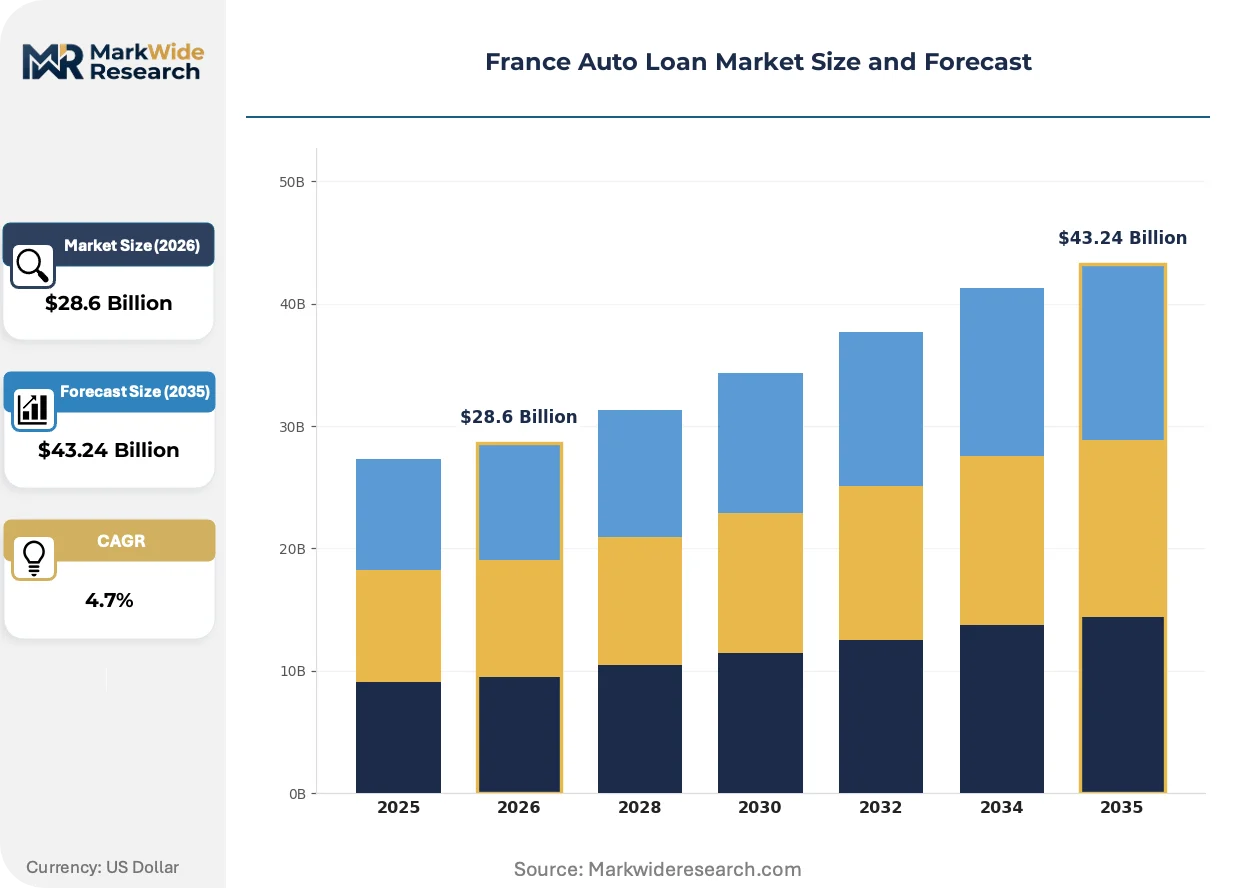
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Vehicles, Used Vehicles, Electric Vehicles, SUVs Customer Type: Individual Consumers, Small Businesses, Corporates, Fleet Operators Loan Term: Short-term, Medium-term, Long-term, Flexible-term Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Rate |
| Companies Covered | Banque Populaire, Banque Postale, Credit Agricole, Sofinco, Credit Mutuel, Societe Generale, Cofidis, Franfinance, BNP Paribas Personal Finance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Auto Loan Market Trends and Innovations
Digital underwriting architectures are compressing origination timelines while embedded finance partnerships reshape distribution economics. These shifts are redrawing competitive boundaries between captive finance arms, traditional banks, and fintech intermediaries.
Artificial intelligence-driven credit scoring is converging with real-time vehicle telematics data. Fleet operators in commercial segments are adopting these integrated risk assessment tools fastest. This convergence is enabling dynamic loan pricing that adjusts to actual driver behavior and vehicle utilization patterns.
The EU Green Deal's climate stress-test protocols are mandating granular carbon-footprint disclosure for auto loan portfolios. French lenders must now segment exposure by vehicle powertrain type and emissions class. Battery-electric and plug-in hybrid financing lines face the most stringent reporting requirements.
Borrower preferences are rotating toward rapid principal reduction structures. Individual consumers in metropolitan areas favor shorter tenors that align with anticipated technology refresh cycles. This behavioral shift is most pronounced among Parisian applicants financing premium electric vehicles.
France Auto Loan Market Segmentation
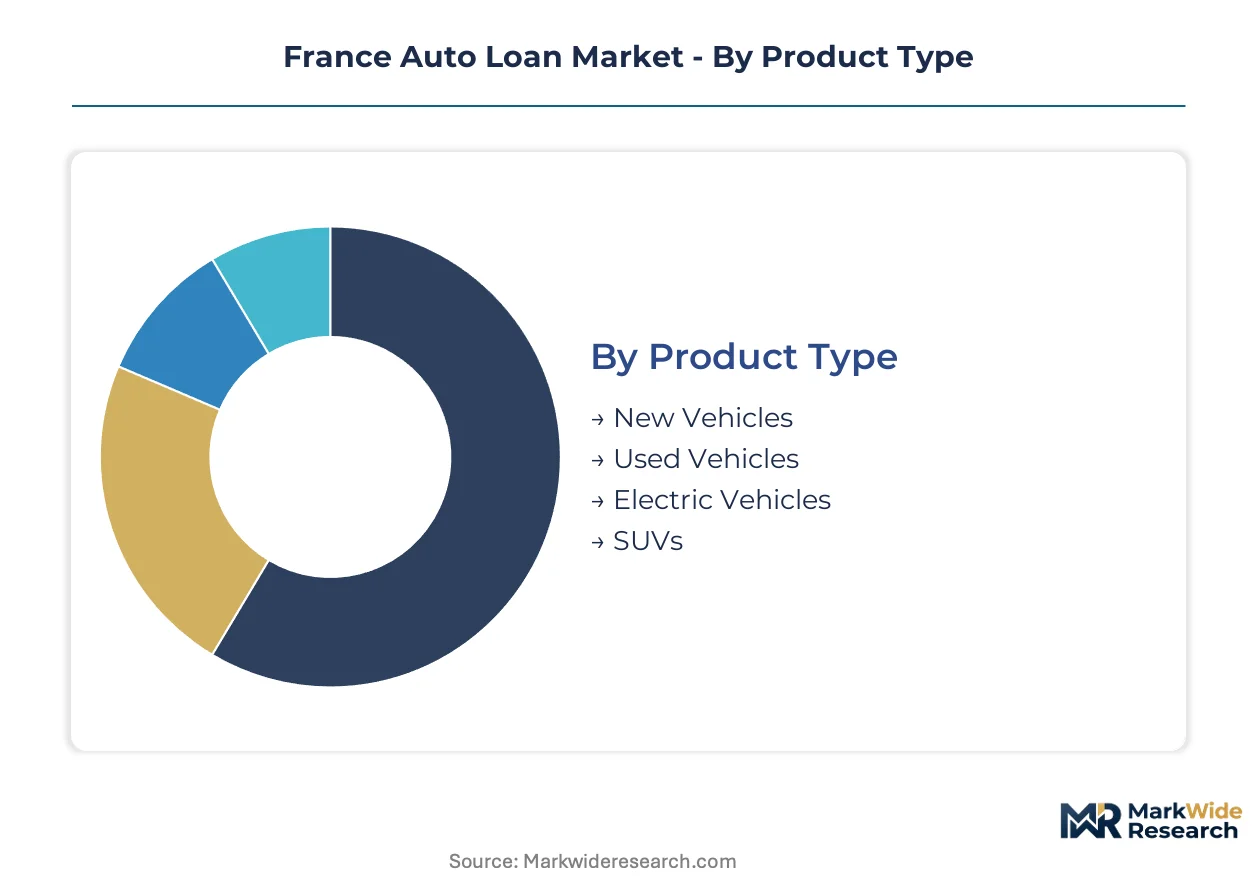
France auto loan segmentation reveals how capital deployment, regulatory pressure, and borrower behavior intersect across product structures. Lenders must align origination strategies with distinct risk-return profiles and policy-driven demand shifts.
Product Type:
New vehicle financing demands the highest upfront capital commitment due to manufacturer subvention programs and bundled insurance requirements.
- New Vehicles:These loans carry fixed amortization schedules against manufacturer-backed residual values. BNP Paribas Personal Finance and Societe Generale concentrate origination volume in the Île-de-France corridor where Parisian commuters prioritize structured credit for premium acquisitions.
- Electric Vehicles:Battery-electric financing lines require recalibrated collateral valuation methodologies given rapid technology evolution. The bonus écologique subsidy administered by the French Ministry of Economy directly compresses effective purchase prices, expanding addressable borrower pools in metropolitan clusters.
- Used Vehicles:Mature secondary-market segment where Cofidis and Franfinance compete on promotional rate positioning.
- SUVs:Higher loan-to-value ratios reflect steeper depreciation curves and malus écologique penalty exposure.
Most installed capacity flows through New Vehicles. Expansion is steepest in Electric Vehicles.
Customer Type:
Corporate and fleet operators generate the largest average ticket sizes, though individual consumers drive aggregate origination volume.
- Individual Consumers:Fixed-rate products dominate this segment as borrowers seek payment certainty against household budget constraints. Parisian applicants in the Île-de-France region favor shorter tenors aligning with anticipated technology refresh cycles.
- Fleet Operators:Commercial borrowers adopt AI-driven credit scoring integrated with real-time vehicle telematics fastest. Credit Agricole leverages cooperative branch density in rural France to sustain penetration among small-business fleet borrowers requiring multi-vehicle financing structures.
- Small Businesses:Underexploited penetration opportunity in non-metropolitan regions where branch network density determines competitive position.
- Corporates:Centralized procurement decisions favor captive finance partnerships with established manufacturer distribution networks.
Individual Consumers anchor origination volume. Fleet Operators are climbing the fastest.
Loan Term:
Regulatory caps on total cost of credit favor shorter-duration products with rapid principal reduction characteristics.
- Short-term:Tenors under 36 months align with French regulatory preference for rapid principal amortization. These structures minimize interest cost exposure for rate-sensitive borrowers in used-vehicle segments.
- Medium-term:37-60 month products balance affordability with residual value risk transfer. This band captures the majority of new vehicle financing in the Île-de-France market where monthly payment sensitivity shapes selection.
- Long-term:Extended tenors face ACPR debt-service-to-income threshold constraints that limit product flexibility for higher-value electric vehicles.
- Flexible-term:Emerging structures allowing payment holidays or balloon arrangements remain niche given regulatory complexity.
Medium-term structures dominate origination flow. Flexible-term products are gaining share fastest.
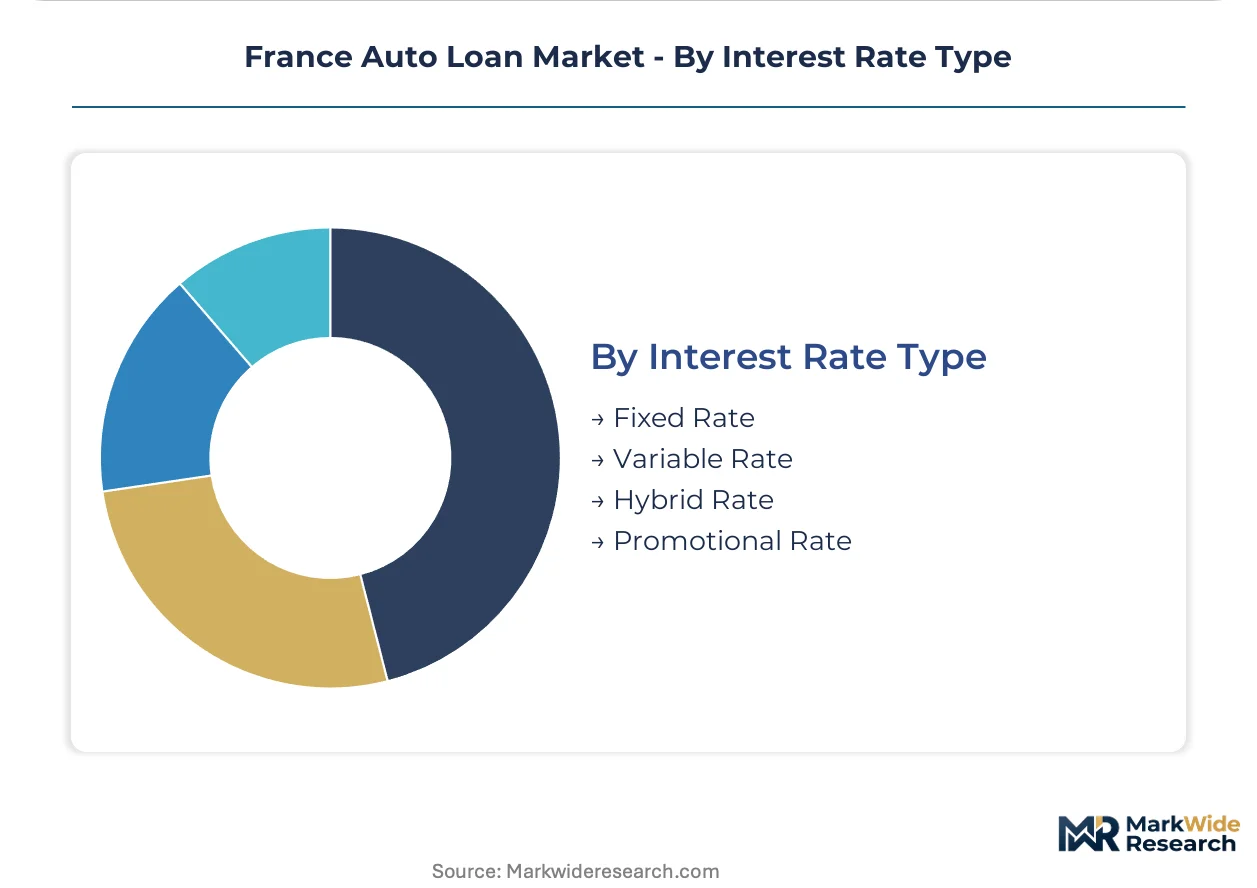
Interest Rate Type:
Fixed-rate products require the most substantial hedging infrastructure given duration exposure in a rising-rate environment.
- Fixed Rate:Predominant structure providing payment certainty across the loan lifecycle. These instruments collateralized by vehicle titles transfer residual-value risk fully to borrowers or captive finance arms.
- Variable Rate:Tied to ECB reference rates, these products concentrate among commercial borrowers with sophisticated treasury functions capable of managing interest rate exposure.
- Hybrid Rate:Blended structures combining initial fixed periods with subsequent variable adjustments appeal to borrowers seeking short-term payment stability.
- Promotional Rate:Manufacturer-subsidized offerings deployed strategically to move inventory, particularly in battery-electric model ranges.
Fixed Rate instruments command the deepest margin pools. Promotional Rate deployment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parisian financial talent and Île-de-France banking infrastructure anchor France's auto loan origination capacity. Regional credit demand concentrates around commuter corridors and industrial clusters where fleet operators and individual borrowers drive structured financing uptake.
Île-de-France
Parisian commuters and corporate fleet operators generate the densest auto loan origination volume in France. The Autorité de Contrôle Prudentiel et de Résolution enforces debt-service-to-income thresholds that shape product structures across the region. La Défense and central Paris banking headquarters host BNP Paribas Personal Finance and Societe Generale operations that dominate metropolitan credit distribution.
Auvergne-Rhône-Alpes
Lyon-based manufacturing supply chains and Saint-Étienne automotive clusters sustain fleet financing demand from commercial borrowers. The bonus écologique subsidy program administered by the French Ministry of Economy redirects individual consumer preferences toward battery-electric vehicle financing. Grenoble's technology corridor influences telematics-integrated credit scoring adoption among regional lenders.
Provence-Alpes-Côte d'Azur
Marseille port logistics and Nice tourism fleets drive commercial vehicle financing structures with shorter tenor preferences. ACPR regulatory caps on total cost of credit limit extended loan arrangements for premium vehicle acquisitions. Toulon naval base proximity sustains specialized fleet financing for defense contractor vehicle pools.
Hauts-de-France
Lille metropolitan cross-border commuters and Calais logistics corridors generate distinct credit demand patterns blending French and Belgian regulatory exposure. Credit Agricole leverages cooperative branch density to penetrate small-business fleet borrowers in rural Picardy. The region's industrial heritage sustains used-vehicle financing volume through rate-sensitive secondary market activity.
Nouvelle-Aquitaine
Bordeaux wine industry logistics and Biarritz tourism operators shape seasonal fleet financing structures with flexible payment characteristics. The malus écologique penalty framework complicates loan structuring for higher-emission commercial vehicles prevalent in agricultural supply chains. Limoges ceramic industry clusters sustain steady mid-market corporate fleet renewal cycles.
France Auto Loan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's auto loan market, creating a tiered competitive structure. Universal banking groups with captive finance arms dominate new vehicle origination through manufacturer distribution partnerships. Digital-native consumer finance platforms and cooperative banking networks occupy distinct competitive positions based on geographic density and rate positioning. Strategic rivalry centers on embedded finance partnerships and API-driven origination speed rather than balance sheet scale alone.
Among established banking groups, BNP Paribas Personal Finance, Societe Generale, and Credit Agricole exemplify divergent competitive archetypes. BNP Paribas Personal Finance occupies a position anchored to captive manufacturer partnerships. Societe Generale represents the digital origination platform strategy. Credit Agricole exemplifies cooperative network density advantages in non-metropolitan penetration. These three structures illustrate how regulatory compliance, technology infrastructure, and branch economics segment competitive positioning across the French market.
| Leading Market Players |
|---|
| Banque Populaire |
| Banque Postale |
| Credit Agricole |
| Sofinco |
| Credit Mutuel |
| Societe Generale |
| Cofidis |
| Franfinance |
| BNP Paribas Personal Finance |
| Others |
Pricing and Supply Chain Analysis
ECB policy rate trajectories cascade through French auto loan pricing tiers, compressing net interest margins on fixed-rate products while manufacturer subvention programs absorb residual-value risk for electric vehicle financing. Borrower payment sensitivity in the Île-de-France corridor shapes product bundling economics as lenders compete on total cost of credit rather than headline rates alone.
Pricing Analysis
Bundled manufacturer subvention programs versus unbundled rate-transparent structures define the pricing architecture. Three-tier pricing separates captive-subsidized offerings from bank-direct products and fintech promotional rates. Price differentiation hinges on insurance bundling density and residual-value guarantee attachment. Cost compression in used-vehicle segments is intensifying because Cofidis and Franfinance deploy zero-percent campaigns. Individual consumers in metropolitan clusters exhibit highest price sensitivity; fleet operators prioritize total cost of ownership over rate points.
Supply Chain Analysis
Vehicle titling infrastructure rests on centralized state registries interfacing with lender collateral management systems. Funding liquidity draws from ECB refinancing operations, retail deposit bases at cooperative networks, and securitization conduits in Luxembourg and Ireland. Single-source vulnerability concentrates in credit scoring data providers serving multiple French lenders simultaneously. Distribution runs through manufacturer dealer networks, direct digital platforms, and embedded finance partnerships at point of sale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France auto loan market functions as a regulatory compounder where bonus écologique subsidy recalibration drives demand rotation toward battery-electric financing structures.
For Market Incumbents: Extend captive finance partnerships into telematics-integrated risk pricing before fintech intermediaries capture fleet operator relationships. Defend margin position by embedding insurance products at origination rather than competing on rate alone. Credit Agricole's cooperative density in rural France offers a template for geographic moat construction against digital-native entrants. For New Entrants and Emerging Players: Enter via small-business fleet financing in non-metropolitan regions where branch network coverage remains sparse. The Hauts-de-France and Nouvelle-Aquitaine corridors present underexploited penetration opportunity among agricultural logistics operators. A digital-first origination platform with compressed decision timelines creates differentiation against Societe Generale's established infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized auto loan servicers possessing ECB climate stress-test compliance infrastructure. Long-term viability favors platforms with granular powertrain-level portfolio segmentation capabilities. Watch bonus écologique budget allocation announcements as inflection indicators for electric vehicle financing volume trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Integrated Risk Pricing | AI-driven credit scoring converges with real-time vehicle data to enable dynamic loan pricing. |
| Green Asset Pool Securitization | EU Green Deal preferential capital treatment rewards battery-electric loan portfolio structuring. |
| Embedded Finance Partnership Expansion | Point-of-sale integration with Renault and Stellantis distribution networks captures origination flow. |
| Digital Euro Pilot Participation | Forthcoming ECB payment-intermediation pilots reshape automotive credit disbursement economics. |
| Rural Cooperative Network Extension | Credit Agricole branch density in non-metropolitan France sustains small-business fleet penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from auto loan product managers at BNP Paribas Personal Finance and Societe Generale, fleet procurement officers in Lyon manufacturing clusters, and ACPR supervisory staff. Secondary validation drew from ECB statistical releases, Banque de France consumer credit aggregates, and vehicle registration data from the French Ministry of Economy. Bottom-up origination volume estimates triangulated against top-down banking sector credit flow statements.
Comparable-period anchoring linked projection assumptions to historical bonus écologique utilization rates and ACPR debt-service-to-income threshold enforcement patterns. Segmentation modeling spanned vehicle powertrain architecture, customer type, loan tenor band, and regional credit demand cluster. CAGRs derived from fitted trend extrapolation adjusted for policy-driven demand inflection points. Battery-electric model range expansion and malus écologique penalty thresholds served as key forecast inputs.
The model holds under stable subsidy framework conditions; deviation in bonus écologique budget exhaustion timing or ACPR threshold tightening would shift origination volume projections. A small set of named triggers warrants ongoing watch: ECB climate stress-test protocol amendments, EU digital euro pilot scope expansion, and open-finance mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Factoring Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
Home Equity Lending Market