
 Asia-Pacific Sugar Free Mints Market | 2026-2036
Asia-Pacific Sugar Free Mints Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sugar Free Mints Market Insights
Market Dynamics
Aftermarket wellness positioning is tilting from medicinal breath fresheners toward daily lifestyle confectionery. Nestlé S.A. leverages its nutrition science heritage to anchor premium sugar-free formulations across Japanese and Australian pharmacy channels. Perfetti Van Melle Group B.V. dominates value-tier pouch formats through deep convenience store penetration in Indonesia and Vietnam. Lotte Group competes on flavor innovation, extending its herbal and fruit mint portfolios to capture younger demographics seeking variety beyond traditional peppermint.
Product Segmentation
Asia-Pacific sugar free mints are compressed or molded confectionery products containing non-nutritive sweeteners such as sorbitol, xylitol, or stevia, manufactured through direct compression or depositing processes to achieve controlled dissolution rates for sustained breath freshening. Hard mints sustain the largest volume base due to shelf stability and low unit cost, while breath strips represent the fastest-growing format as consumers prioritize portability and discrete consumption in professional settings. Pouch packaging captures growing share in online retail and convenience channels, whereas tins retain dominance in gift-oriented and premium supermarket placements across South Korea and Japan.
Regulatory Environment
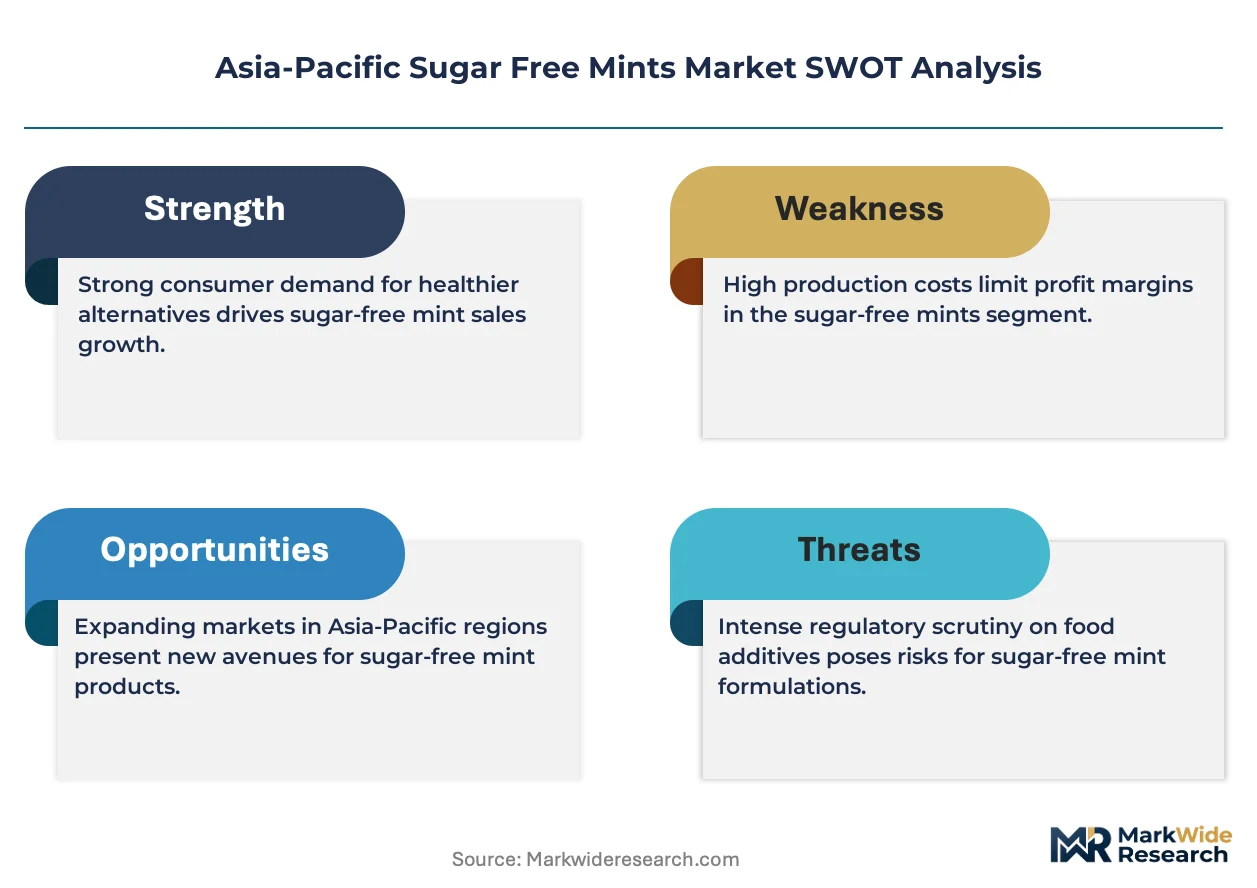
FSSAI in India mandates explicit sugar content disclosures and restricts nutrient claims, compelling manufacturers to reformulate with approved polyols and substantiate dental health benefits. Japan's Consumer Affairs Agency enforces strict functional food labeling under Foods with Function Claims, while Australia's FSANZ governs sweetener maximum limits and permitted health statements. Stakeholders must monitor evolving front-of-pack regulations across Southeast Asian markets, where Thailand and Vietnam are developing comparable labeling frameworks that will reshape permissible marketing claims and reformulation timelines.
Market Dynamics
India's FSSAI front-of-pack labeling rules are forcing rapid reformulation across the Asia-Pacific sugar free mints landscape, compressing product development cycles while elevating polyol-based formulations.
Growth Catalysts
- Urban Professional Consumption:Young corporate workers in Chinese tier-one cities are adopting on-the-go oral care as daily ritual, expanding convenience store velocity for discrete breath-freshening formats.
- FSSAI Disclosure Mandates:India's explicit sugar content labeling rules are accelerating manufacturer migration toward xylitol and stevia formulations to retain shelf positioning.
- Pharmacy Channel Expansion:Wellness-positioned sugar-free mints are capturing incremental space in Japanese and Australian pharmacy chains, anchoring premium placement adjacent to oral care.
Market Restraints
- Sorbitol Supply Concentration:Bulk polyol sourcing clusters among limited Southeast Asian chemical processors, exposing margin pressure during feedstock volatility.
- Functional Claim Friction:Japan's Consumer Affairs Agency Foods with Function Claims framework imposes substantiation burdens that delay regional product launches by 8-14 months.
- Hard Candy Substitution:Traditional medicated throat drops retain price advantage in rural Vietnamese and Indonesian distribution, constraining value-tier mint penetration.
Strategic Opportunities
- Vietnam Convenience Modernization:Underpenetrated rural convenience infrastructure offers first-mover positioning as 7-Eleven and local chains expand beyond Ho Chi Minh City and Hanoi.
- Breath Strip Format White Space:Film-based delivery systems remain nascent outside Japan and South Korea, presenting portfolio extension potential for portability-focused segments.
- Thailand Labeling Alignment:Emerging front-of-pack frameworks mirror Indian and Vietnamese precedents, creating regulatory harmonization benefits for preemptive reformulators.
Industry Challenges
- Polyol Formulation Expertise Gap:Scarcity of food technologists skilled in controlled-dissolution compression is throttling N throughput for regional manufacturers.
- Multi-Regulatory Compliance Burden:Simultaneous navigation of FSSAI, FSANZ, and Japan's functional food regimes fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sugar Free Mints Market |
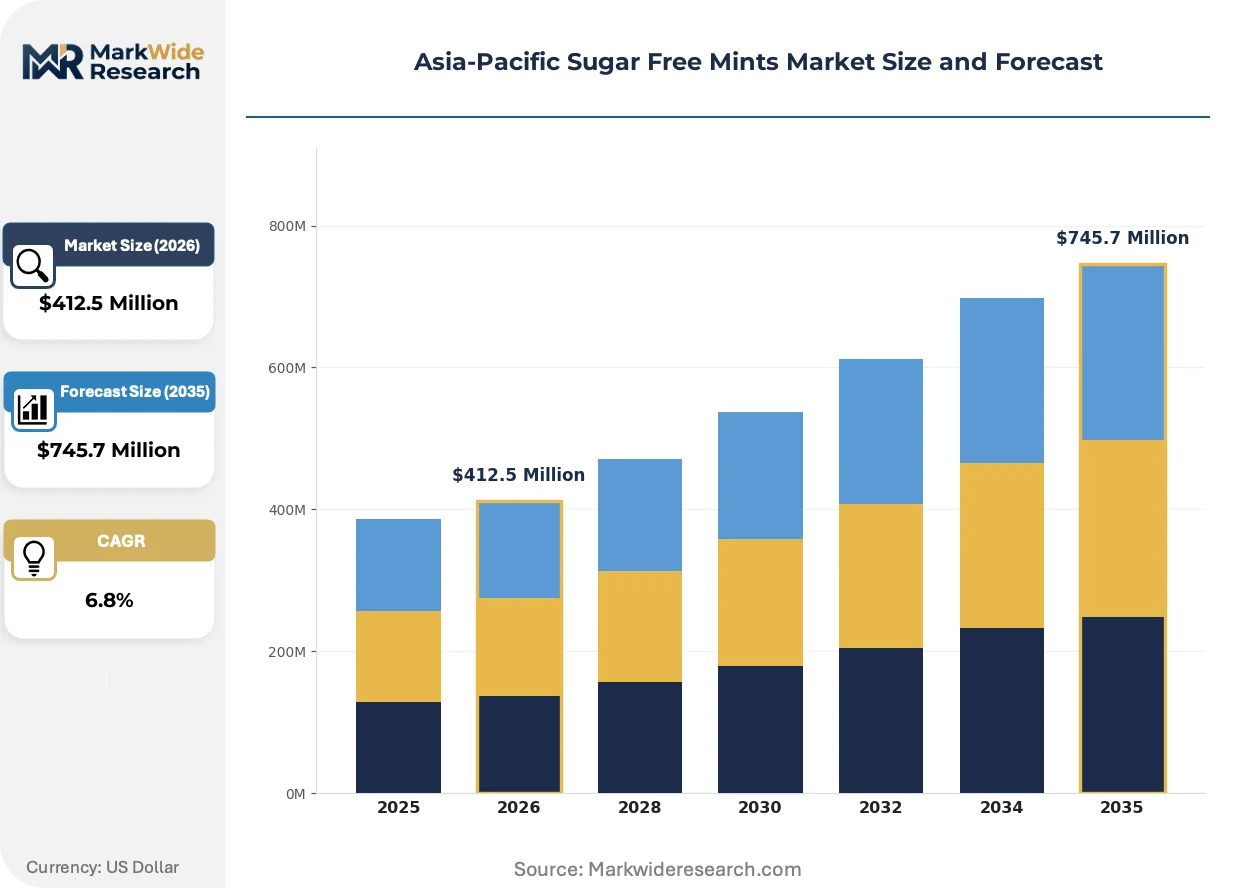
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Mints, Soft Mints, Chewing Mints, Breath Strips Flavor: Mint, Fruit, Herbal, Spicy Packaging Type: Bottles, Pouches, Tins, Dispensers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Ferrero International S.A., Nestlé S.A., The Wrigley Company, Mondelēz International, Lotte Group, Perfetti Van Melle Group B.V., The Hershey Company, Albanese Candy, Atkinson Candy Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sugar Free Mints Market Trends and Innovations
Asia-Pacific sugar free mints are experiencing format fragmentation as portability demands reshape conventional hard candy dominance, with dissolution engineering and packaging miniaturization now central to competitive differentiation.
Controlled-release compression technology is collapsing the functional boundary between confectionery and oral care. Direct compression systems modulating xylitol dissolution rates enable sustained breath freshening across 15-20 minute windows. Young professionals in Shanghai and Seoul are adopting these formats for meeting-room discretion. The technology is collapsing traditional segmentation between daily mints and medicated breath products.
FSSAI's front-of-pack sugar disclosure rules are reshaping permissible marketing architecture. Explicit gram declarations on primary packaging are eliminating implied health positioning for legacy formulations. Indian manufacturers are responding with accelerated stevia and erythritol transitions ahead of enforcement deadlines. Tier-one city consumers are demonstrating measurable preference for labeled sugar-free alternatives.
Procurement patterns among Asian convenience retailers are compressing supplier qualification cycles. Category managers at Lawson and FamilyMart are reducing new SKU evaluation from 90 to 45 days, favoring established polyol suppliers with regional manufacturing footprints. Breath strips and micro-pouch formats are gaining disproportionate shelf allocation versus traditional tins. This velocity shift is most pronounced in Tokyo, Singapore, and Sydney metropolitan networks.
Asia-Pacific Sugar Free Mints Market Segmentation
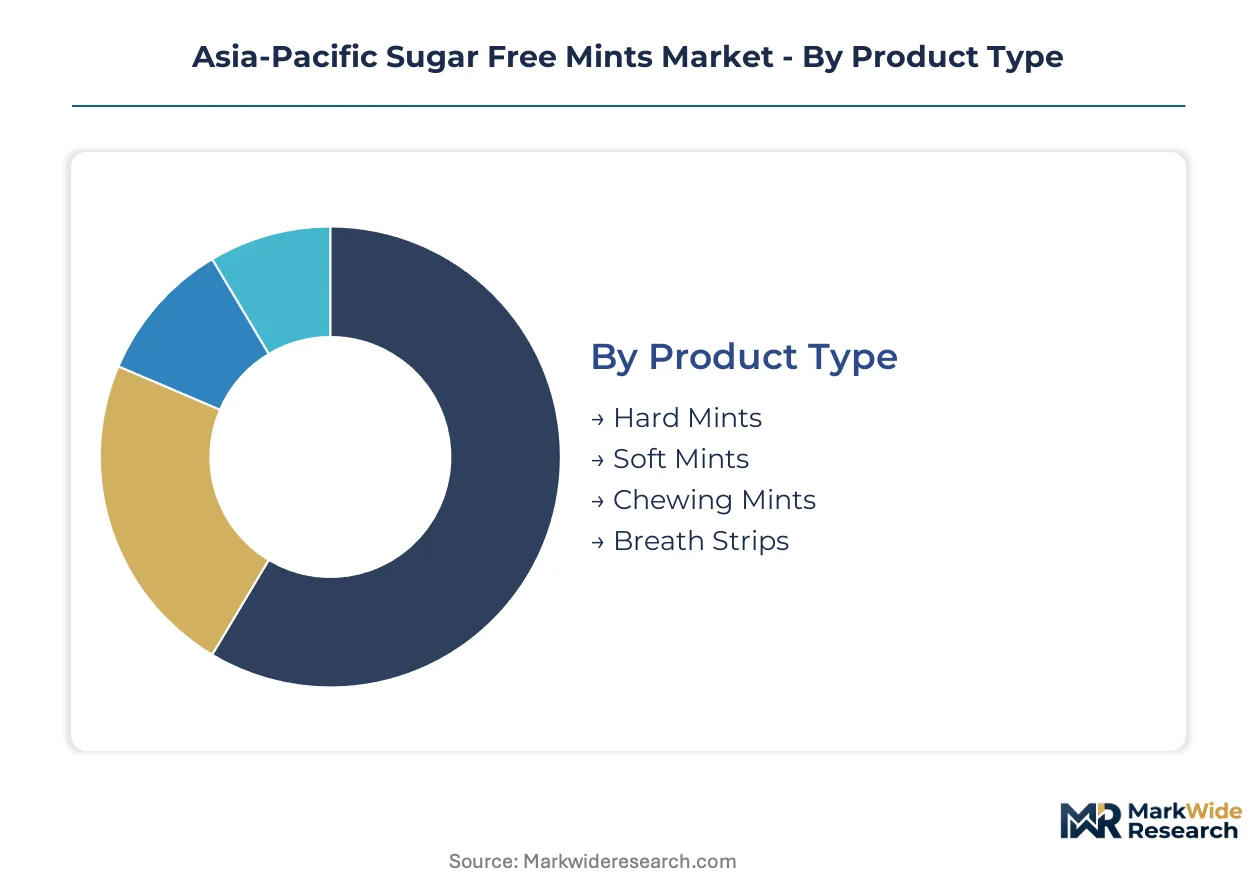
Asia-Pacific sugar free mints segmentation reveals how format engineering and channel dynamics fragment purchasing behavior across urban professional demographics. Distinct product architectures align with specific consumption moments, from desk-drawer discretion to transit portability.
Product Type:
Format engineering determines dissolution kinetics and shelf stability, with compression technology separating daily-use confectionery from functional oral care hybrids.
- Hard Mints:Direct-compressed tablets using sorbitol or xylitol matrices achieve 15-20 minute controlled release. Chinese tier-one city convenience stores move these formats fastest for meeting-room consumption.
- Breath Strips:Film-based delivery systems dissolve in 30-60 seconds for maximum discretion. Japanese and South Korean pharmacy channels are expanding shelf space for these portable formats among young corporate workers.
- Soft Mints:Chewable centers with compressed shells balance texture and breath-freshening duration.
- Chewing Mints:Extended-mastication formats emphasize flavor longevity over rapid dissolution.
Hard mints hold installed capacity. Breath strips are rotating up the share rankings.
Flavor:
Taste architecture segments consumers by usage occasion intensity and regional palate preferences, with herbal formulations gaining traction alongside traditional peppermint dominance.
- Mint:Peppermint and spearmint oil formulations deliver immediate cooling sensation through menthol activation. Australian pharmacy channels anchor premium positioning for therapeutic-grade mint oils.
- Herbal:Green tea, ginseng, and traditional medicine extracts target wellness-positioned consumers in Japan and South Korea seeking functional differentiation.
- Fruit:Citrus and berry profiles capture younger demographics seeking variety rotation.
- Spicy:Ginger and cinnamon variants appeal to Southeast Asian markets with heat-forward culinary traditions.
Mint maintains formulation dominance. Herbal is climbing the fastest as functional claims harden.
Packaging Type:
Container engineering shapes retail velocity and consumption occasion, with miniaturization and resealability now primary purchase drivers.
- Pouches:Flexible film with zip-lock closures enables pocket portability and portion control. Indonesian and Vietnamese convenience chains are allocating disproportionate shelf space to these formats.
- Tins:Metal containers signal premium positioning and gift suitability. South Korean and Japanese supermarket premium aisles retain tin dominance for ceremonial giving occasions.
- Bottles:Rigid plastic with flip-top lids targets desk and automotive storage.
- Dispensers:Mechanized single-unit delivery systems emphasize hygiene and controlled consumption.
Tins hold installed capacity. Pouches are rotating up the share rankings.
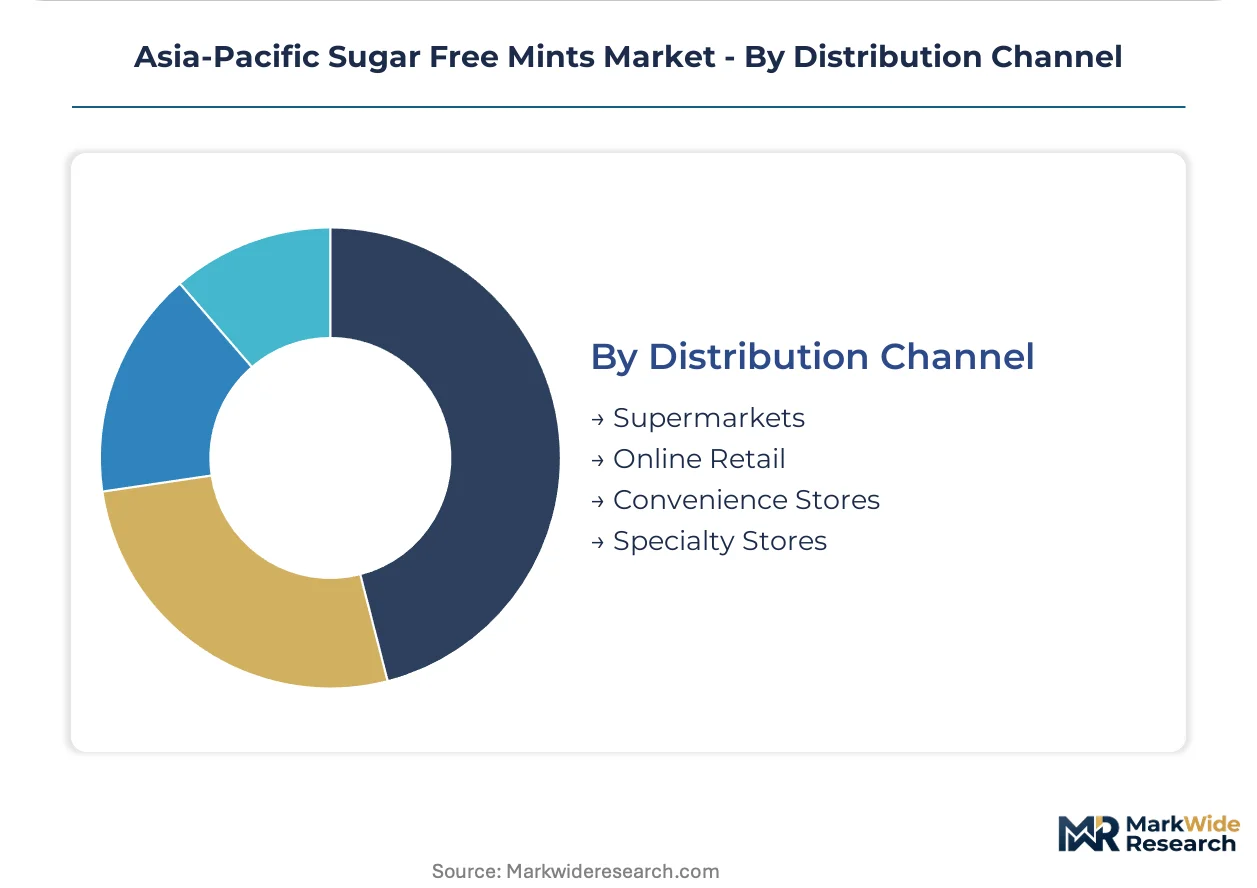
Distribution Channel:
Channel selection determines pricing architecture and consumer touchpoint frequency, with convenience density mapping directly to urban professional population concentration.
- Convenience Stores:Lawson, FamilyMart, and 7-Eleven networks in Tokyo, Shanghai, and Singapore compress purchase cycles to impulse frequency. Shelf placement adjacent to checkout drives unplanned trial.
- Online Retail:E-commerce platforms enable bulk purchasing and subscription mechanics for pantry stocking. India's tier-one cities demonstrate strongest digital adoption for sugar-free mint replenishment.
- Supermarkets:Hypermarket chains anchor family-pack economics and promotional bundling.
- Specialty Stores:Pharmacy and wellness retailers emphasize therapeutic positioning and premium pricing.
Supermarkets hold installed capacity. Convenience stores are climbing the fastest as urban density intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific sugar free mints landscape. Vietnamese and Indonesian consumers gravitate toward value-tier pouch formats, while Japanese and Australian buyers absorb premium positioning in pharmacy channels.
China
Young corporate workers in Shanghai, Beijing, and Shenzhen treat discrete breath freshening as daily ritual. SAMR's evolving food labeling standards are compressing reformulation timelines for imported and domestic brands alike. Tier-one city convenience stores now allocate prime checkout placement to polyol-based compressed mints.
Japan
Functional food positioning commands sustained pharmacy channel expansion. The Consumer Affairs Agency enforces strict substantiation under Foods with Function Claims, delaying launches by 8-14 months. Tokyo and Osaka metropolitan networks favor film-based breath strips for meeting-room discretion.
India
FSSAI front-of-pack sugar disclosure mandates are accelerating manufacturer migration toward stevia and erythritol formulations. Mumbai and Delhi-NCR consumers demonstrate measurable preference for labeled sugar-free alternatives. Enforcement deadlines are compressing product development cycles across domestic and multinational portfolios.
South Korea
Herbal and green tea flavor innovation captures wellness-positioned younger demographics. Premium tin packaging retains dominance in Seoul supermarket gift aisles for ceremonial giving occasions. Lotte Group and local competitors extend portfolios beyond traditional peppermint to secure rotation.
Australia
FSANZ governs sweetener maximum limits and permitted health statements with precision. Pharmacy chains in Sydney and Melbourne anchor premium placement adjacent to oral care categories. Therapeutic-grade mint oil formulations sustain price architecture above standard confectionery tiers.
Asia-Pacific Sugar Free Mints Market Competitive Landscape
Capability concentration sits with nutrition science and flavor innovation specialists; scale advantage sits with global confectionery conglomerates with deep convenience store penetration. The market structures around three tiers: multinational nutrition heritage players, Asia-Pacific regional specialists with herbal portfolio depth, and value-tier pouch format dominators. Dominant competitive moves include accelerated polyol reformulation to meet FSSAI deadlines and format diversification into breath strips and micro-pouches.
Within the nutrition science tier, Nestlé S.A. leverages its heritage to anchor premium formulations across Japanese and Australian pharmacy channels. Among Asia-Pacific regional specialists, Lotte Group competes on flavor innovation extending herbal and fruit mint portfolios. At the value-tier end, Perfetti Van Melle Group B.V. dominates pouch formats through deep convenience store penetration in Indonesia and Vietnam.
| Leading Market Players |
|---|
| Ferrero International S.A. |
| Nestlé S.A. |
| The Wrigley Company |
| Mondelēz International |
| Lotte Group |
| Perfetti Van Melle Group B.V. |
| The Hershey Company |
| Albanese Candy |
| Atkinson Candy Co. |
| Others |
Pricing and Supply Chain Analysis
Singapore-Jakarta maritime freight corridors are compressing logistics costs for polyol feedstock movements, amplifying margin pressure on regional manufacturers while enabling sharper price differentiation between pharmacy-channel premiums and convenience-store value tiers across Southeast Asian markets.
Pricing Analysis
After-sales service bundling through pharmacy-channel oral care adjacencies drives lifetime value capture for premium sugar-free mint portfolios. Three-tier pricing structure across premium, standard, and economy levels separates therapeutic-grade xylitol formulations from sorbitol-based value pouches and unbranded private-label alternatives. Cost compression in economy tiers is intensifying because Indonesian and Vietnamese retailers are consolidating supplier bases toward regional polyol manufacturers with captive logistics networks. Rural Indonesian distributors exhibit highest price sensitivity, while Japanese pharmacy buyers absorb premium positioning for functional breath-freshening claims.
Supply Chain Analysis
Tariff exposure between China and Australia dominates sourcing calculus for stevia and erythritol sweetener inputs. Bulk polyol production clusters in Thailand, Malaysia, and Indonesia, with formulation expertise concentrated in Japanese and South Korean technical centers. Raw material dependencies center on corn-derived sorbitol, birch-sourced xylitol, and stevia leaf extracts from cultivation networks. Single-source vulnerability persists for pharmaceutical-grade xylitol refining. Distribution runs through convenience store procurement hubs in Tokyo, Singapore, and Sydney metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific sugar free mints market is cycling through a reformulation-driven recovery as FSSAI enforcement deadlines compress product development timelines and accelerate manufacturer migration toward compliant polyol portfolios.
For Market Incumbents: Harden formulation IP around controlled-dissolution compression technology to defend against regional contract manufacturers entering with reverse-engineered alternatives. Anchor pharmacy-channel positioning through certification investment in Japan's Foods with Function Claims framework, while consolidating convenience store shelf space via exclusive pouch-format supply agreements with Lawson and FamilyMart networks. For New Entrants and Emerging Players: Vietnam's rural convenience infrastructure outside Ho Chi Minh City and Hanoi offers first-mover positioning as 7-Eleven and local chains expand distribution footprints. Breath strip formats remain nascent outside Japan and South Korea, presenting portfolio extension potential for portability-focused professional segments. Target pharmacy-channel oral care adjacencies as the most penetrable premium entry vector. For Investors and Strategic Acquirers: Regional polyol suppliers with backward integration into Southeast Asian chemical processing assets represent the most defensible acquisition archetype for long-term viability across the 5-10 year projection horizon. Watch FSSAI enforcement rigor and subsequent Indian market share shifts toward labeled sugar-free alternatives as the primary inflection signal for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Polyol Reformulation Acceleration | FSSAI compliance deadlines in India are forcing stevia and erythritol transitions ahead of enforcement. |
| Breath Strip Format Expansion | Film-based delivery systems capture pharmacy-channel shelf space in Tokyo and Seoul metropolitan networks. |
| Convenience Store Supply Agreements | Exclusive pouch-format partnerships with Lawson and FamilyMart compress competitor access to prime checkout placement. |
| Pharmacy Channel Premium Positioning | Functional claims adjacent to oral care categories in Australian and Japanese chains sustain price architecture. |
| Regional Manufacturing Footprint Consolidation | Thai and Malaysian polyol production hubs reduce freight exposure and tariff vulnerability for ASEAN distribution. |
Research Methodology
A standing panel of brand managers, category buyers at convenience retailers, supply planners, and food technology R&D directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FSSAI regulatory filings, Nielsen retail audit data, customs records, and company SEC disclosures. Bottom-up channel velocity estimates and top-down category sizing triangulated to produce segmentation-level outputs.
Scenario-bracketing framed analytical approach across the projection horizon, with CAGRs derived from trend extrapolation against historical elasticity patterns. Segmentation dimensions modeled include product format, flavor architecture, packaging type, and distribution channel intensity. Forecast inputs incorporated polyol feedstock price trajectories and convenience store penetration rates by metropolitan density tier.
Macroeconomic conditions sit as an overlay; deviation in consumer disposable income indices or freight cost volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and channel expansion schedules. Material shifts in FSSAI interpretation rigor or ASEAN labeling harmonization pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Crunchy Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
US Dark Chocolate Market
Confectionery
Brazil Chocolate Market
Confectionery
Gummy Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Low Calorie Nutella Market
Confectionery
North America Compound Chocolate Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Salted Caramel Products Market
Confectionery
South Africa Confectionery Market
Confectionery
Xylitol Lollipops Market
Confectionery
Buttercream Frosting Market
Confectionery
Gummy Candy Market