
 Sugar Free Mints Market | 2026-2036
Sugar Free Mints Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Mints Market Analytics
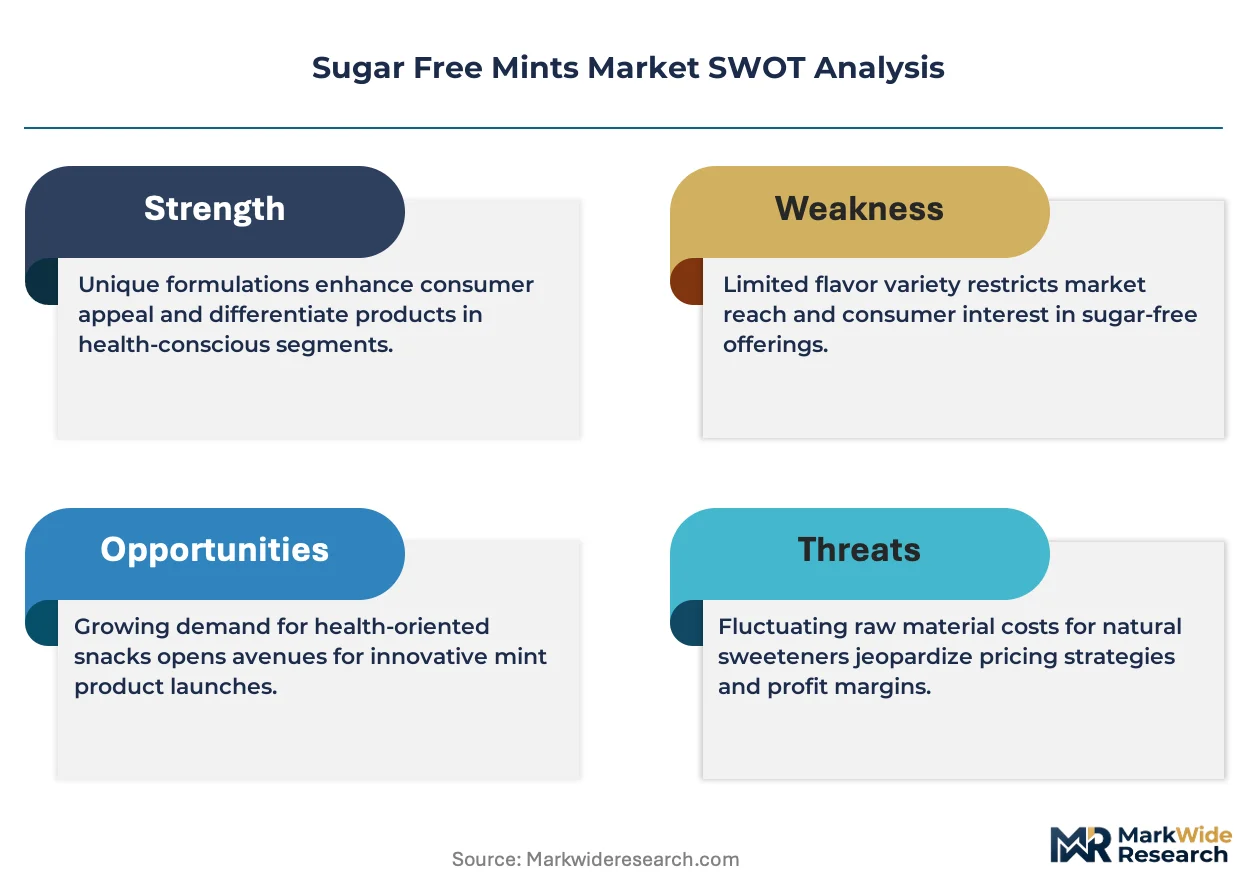
Premium clean-label formulation is reorganizing competitive dynamics in sugar-free confectionery. Mars, Inc. leverages its global distribution infrastructure to sustain shelf presence across multiple retail formats. The Hershey Company differentiates through intensive R&D investment in natural sweetener stability. Mondelez International anchors its position with manufacturing scale that supports consistent supply to pharmacy and convenience channels.
Sugar free mints are compressed or molded confectionery products containing non-nutritive sweeteners such as xylitol, sorbitol, or stevia, manufactured through direct compression or candy depositing processes to deliver oral freshness without fermentable carbohydrates. Hard mints dominate volume due to extended shelf stability and lower production complexity, while liquid mints represent the fastest-expanding format as portable dosing appeals to younger demographics. E-commerce channels capture disproportionate margin pools through subscription and bulk configurations, whereas supermarkets remain the baseline volume engine for standard packaging formats.
FDA nutrition labeling requirements, WHO sugar reduction frameworks, and EU Food Information to Consumers regulations collectively tighten permissible health claims and sweetener disclosure standards. These standards force manufacturers to reformulate around approved additive lists and substantiate dental benefit assertions. Stakeholders must monitor evolving sweetener safety assessments and retail pharmacy classification shifts to anticipate channel access changes.
Market Dynamics
FDA sugar labeling rules and WHO sugar reduction guidelines are compressing formulation cycles while forcing manufacturers to rebuild ingredient sourcing around approved non-nutritive sweetener lists. This regulatory pressure is redrawing competitive boundaries between legacy confectioners and clean-label specialists.
Growth Catalysts
- Dental-conscious hospitality procurement:Hotels and airlines in Germany and Japan now mandate sugar-free amenity programs, creating institutional volume anchors for compressed mint formats.
- FDA Nutrition Labeling and Education Act amendments:Updated serving-size disclosure rules force transparent sweetener quantification, rewarding brands with simpler ingredient decks.
- Xylitol stability advances:Improved moisture-barrier packaging technologies extend hard-mint shelf life without synthetic preservatives, unlocking pharmacy channel placement.
Market Restraints
- Erythritol price volatility:Fermentation-based supply concentration in Chinese manufacturing creates input cost instability for mid-tier formulators.
- EU Food Information to Consumers enforcement variance:Member-state interpretation differences on "sugar-free" versus "no added sugar" claims generate compliance fragmentation.
- Bulk liquid mint packaging limitations:Current blow-fill-seal equipment lacks the precision dosing range that single-serve formats demand, constraining portable format expansion.
Strategic Opportunities
- Subscription e-commerce configuration:Direct-to-consumer replenishment models bypass retail slotting fees while capturing recurring margin pools.
- India FSSAI clean-label recognition pathway:Emerging regulatory framework for functional confectionery creates first-mover positioning for dental-benefit substantiated products.
- Stevia-rebaudiana glycoside blending:Convergence of enzymatic bioconversion with traditional extraction yields cleaner taste profiles without bitter aftertaste masking agents.
Industry Challenges
- Food technologist specialization scarcity:Formulation expertise spanning confectionery science and sweetener metabolic pathways concentrates in Western European and North American talent pools.
- ISO 22000 certification timeline compression:Accelerated retailer qualification requirements strain smaller manufacturers' quality management system implementation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Mints Market |
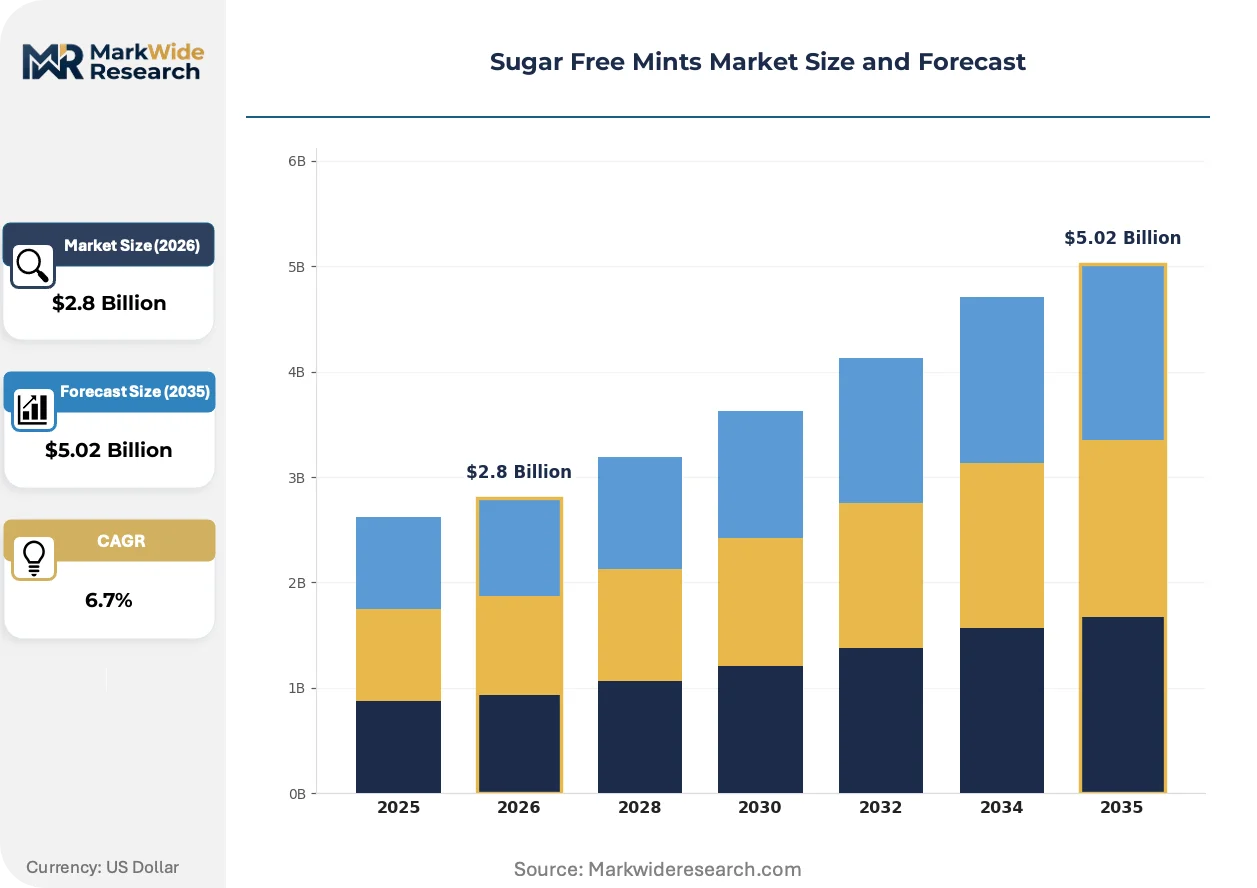
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Mints, Chewy Mints, Breath Fresheners, Liquid Mints Distribution Channel: Supermarkets, Convenience Stores, E-Commerce, Pharmacies Flavor: Mint, Cinnamon, Fruit, Herbal Packaging Type: Boxes, Tubs, Sachets, Blister Packs |
| Companies Covered | Mars, Inc., The Hershey Company, Mondelez International, Ferrero International S.A., Nestle S.A., Perfetti Van Melle Group B.V., Lotte Corporation, Atkinson Candy Company, Ricola Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Mints Market Evolving Landscape
Active reformulation around natural sweetener stability is compressing product development timelines while opening new positioning territory between pharmaceutical-grade functional claims and indulgent confectionery.
Encapsulation technology using lipid-based matrix systems is miniaturizing flavor release profiles in compressed mint formats. Younger demographics in United States urban centers adopt these micro-dose configurations for discrete workplace consumption. The technology is miniaturizing portion control while enabling cleaner-label positioning that satisfies both FDA disclosure requirements and clean-label retailer standards.
REACH regulation updates on microplastic-free labeling are forcing packaging substrate transitions across European supply chains. Manufacturers must validate alternative film structures for moisture barrier performance without polypropylene laminates. German pharmacy chains now require written certification of microplastic-free status before listing sugar-free mint assortments.
Corporate procurement departments in professional services firms now specify sugar-free refreshment stations as wellness program components. This specification behavior displaces traditional bulk candy procurement through facilities management contractors. The shift is most visible in United States and Japanese central business districts where tenant wellness certifications influence leasing decisions.
Sugar Free Mints Market Segmentation
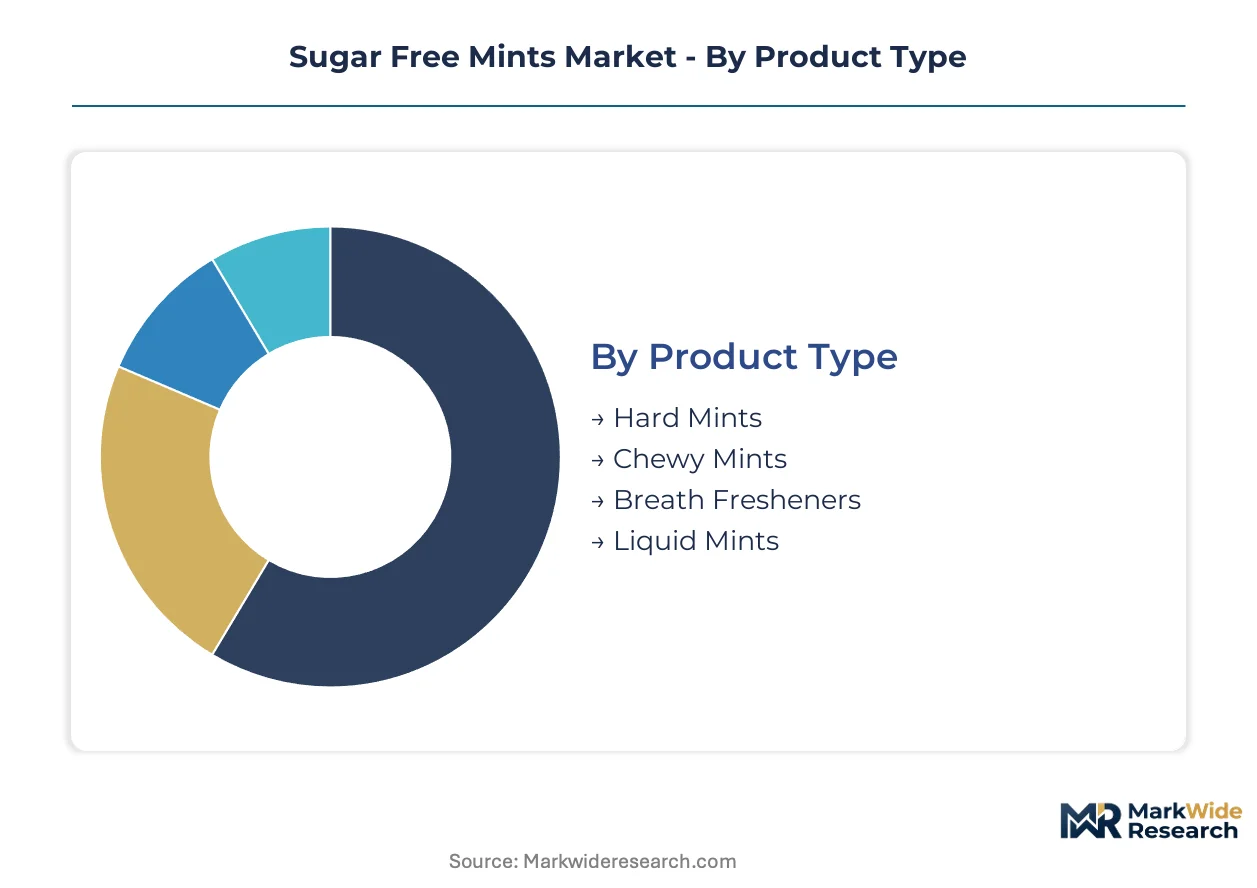
Sugar-free mints require precise segmentation because formulation chemistry, moisture sensitivity, and sweetener stability vary dramatically across physical formats and retail channels. Regulatory disclosure requirements from FDA, EFSA, and FSSAI further complicate positioning strategies for manufacturers targeting multiple geographies.
Product Type:
FDA and EFSA disclosure thresholds for non-nutritive sweeteners create divergent formulation burdens across physical formats, with compressed products facing stricter quantification rules than liquid alternatives.
- Hard Mints:Direct-compressed tablets using xylitol or sorbitol as bulking agents and primary sweeteners, manufactured through high-speed rotary press operations. Hotels and airlines in Germany and Japan specify hard mints for amenity programs due to extended shelf stability and portion control precision. FDA serving-size disclosure rules reward hard mints with simpler ingredient decks.
- Liquid Mints:Emulsified or aqueous suspensions delivered through dropper or spray mechanisms, typically employing stevia glycosides for rapid dissolution. Younger demographics in United States urban centers adopt portable dosing formats for discrete workplace consumption. Current blow-fill-seal equipment limitations constrain single-serve precision dosing expansion.
- Chewy Mints:Gelatin or pectin-based matrices incorporating sorbitol syrup for texture retention and reduced water activity.
- Breath Fresheners:Rapid-dissolve strips or micro-encapsulated sprays prioritizing immediate volatile release over sustained sweetener contact time.
Hard Mints handles the majority of throughput; Liquid Mints is the fastest mover on share.
Distribution Channel:
Margin structure and slotting fee economics concentrate volume differently across channels, with pharmacy placement commanding premium positioning while e-commerce captures recurring replenishment value.
- Supermarkets:Standard packaging formats dominate shelf space through high-velocity checkout lane placement and seasonal promotional cycles. Volume concentration in United States and German retail chains supports manufacturing scale economies for mid-tier formulators.
- E-Commerce:Subscription configurations and bulk assortments bypass traditional retail slotting fees while capturing recurring margin pools through direct-to-consumer replenishment models.
- Convenience Stores:Impulse-oriented single-serve and pocket formats targeting immediate consumption occasions.
- Pharmacies:Dental-benefit substantiated products requiring ISO 22000 certification and written microplastic-free packaging validation for German chain placement.
Supermarkets move the baseline volume; E-Commerce climbs the fastest on margin capture efficiency.
Flavor:
Clean-label positioning and natural extract sourcing costs stratify flavor categories, with botanical and fruit derivatives commanding formulation premiums over synthetic alternatives.
- Mint:Menthol and peppermint oil formulations remain the reference standard for oral freshness perception, with natural extract stability determining shelf-life claims. Professional services firms in United States central business districts specify mint-forward refreshment stations as wellness program components.
- Fruit:Citrus and berry profiles utilizing natural flavor encapsulation to mask bitter aftertastes from stevia-rebaudiana glycosides. Younger demographics in Japanese urban centers drive fruit variant adoption for workplace discretion.
- Cinnamon:Cinnamaldehyde-based warmth profiles with established dental benefit associations in traditional medicine frameworks.
- Herbal:Chamomile, green tea, and licorice extracts positioning toward functional wellness claims requiring FSSAI clean-label recognition in emerging markets.
Mint retains the volume anchor position; Fruit gains share fastest among format-switching demographics.
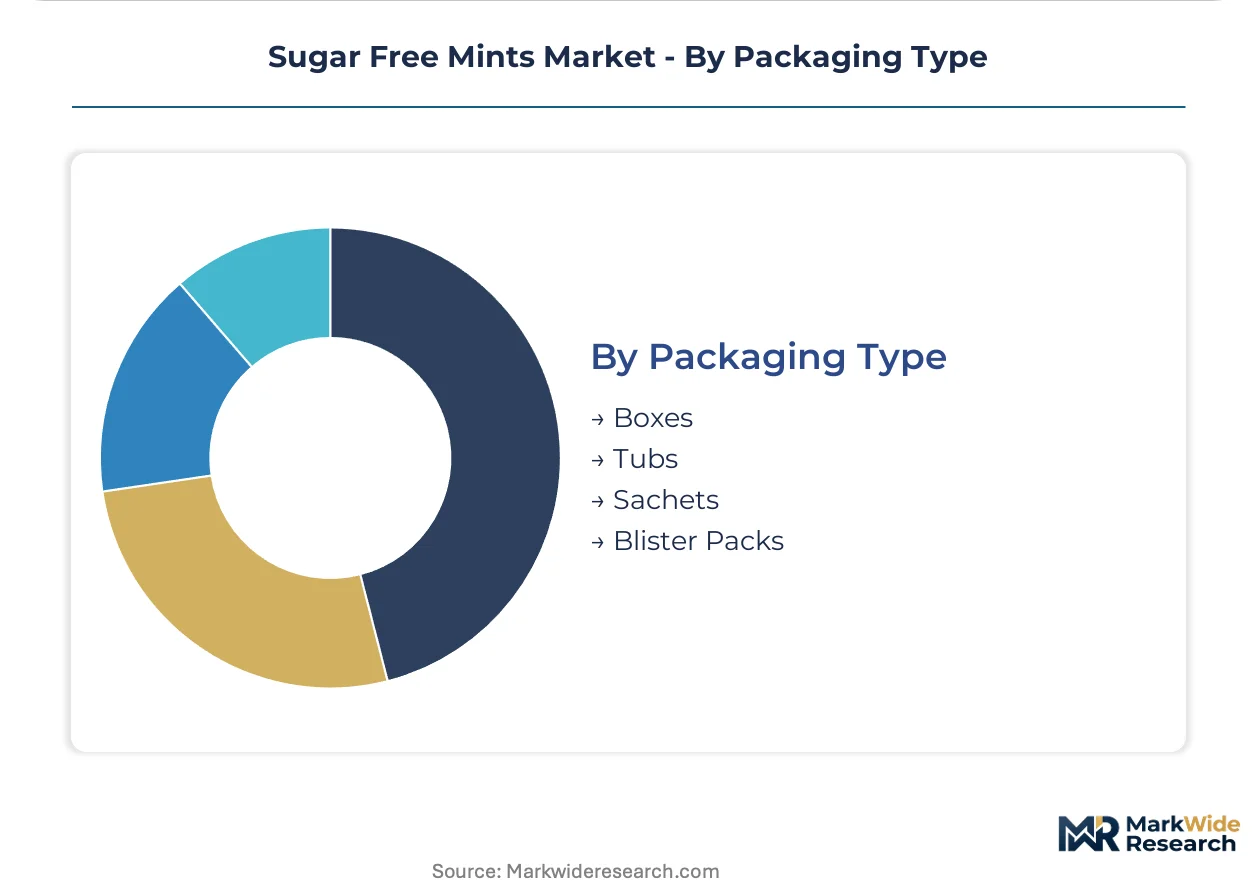
Packaging Type:
REACH microplastic-free labeling requirements and moisture-barrier performance specifications are forcing substrate transitions that reshape cost structures across European supply chains.
- Blister Packs:Thermoformed PVC or aluminum-laminate cavities providing individual dose protection and tamper evidence, now requiring polypropylene-free validation for German pharmacy listing. Individual portion control supports hospitality amenity specifications in Japan.
- Boxes:Folding carton structures with integrated moisture-barrier liners, optimized for retail shelf presence and promotional graphics real estate. United States supermarket chains favor box formats for planogram flexibility and vertical stacking efficiency.
- Tubs:Injection-molded or thermoformed containers with resealable lids for bulk home and office consumption.
- Sachets:Flexible film single-serve packets targeting foodservice and travel amenity distribution.
Blister Packs manages the precision-dose segment; Boxes holds the broadest retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in sugar-free confectionery tilt toward manufacturing concentration in Western Europe and North America, with Asia-Pacific markets absorbing premium formulation imports while building domestic capacity in functional sweeteners. Trade flows reflect divergent regulatory maturity on dental health claims and clean-label standards.
United States
Corporate wellness procurement in Manhattan and Chicago central business districts specifies sugar-free refreshment stations as tenant amenities. FDA Nutrition Labeling and Education Act amendments enforce transparent sweetener quantification on serving sizes. Mars, Inc. and The Hershey Company maintain distribution infrastructure supporting pharmacy and convenience channel penetration.
Germany
Hotel and airline amenity programs mandate compressed mint formats for institutional volume procurement. REACH regulation updates on microplastic-free labeling force packaging substrate transitions across Bavarian and North Rhine-Westphalia manufacturing clusters. Pharmacy chains require written certification of microplastic-free status before product listing.
Japan
Urban professional demand in Tokyo and Osaka favors discrete portable dosing formats for workplace consumption. METI guidelines on functional food claims shape dental-benefit substantiation requirements for pharmacy placement. Lotte Corporation and domestic specialists anchor supply to hospitality and retail channels.
India
FSSAI clean-label recognition pathways create first-mover positioning for substantiated dental-benefit products in Maharashtra and Gujarat. Emerging regulatory frameworks for functional confectionery attract formulation investment from multinational and domestic players. Urban centers drive adoption of fruit-flavored variants among younger demographics.
United Kingdom
Retail pharmacy classification shifts in London and Southeast England tighten health claim verification standards. EFSA disclosure thresholds on non-nutritive sweeteners compress formulation cycles for compressed and liquid formats. Supermarket chains favor box packaging configurations for planogram flexibility.
Sugar Free Mints Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and formulation agility. The vendor base spans consolidated multinational confectioners with global retail infrastructure and regional specialists with clean-label positioning. Three archetypes dominate: scale-driven mass-market suppliers, premium functional specialists, and private-label contract manufacturers. Competitive moves concentrate on M&A for sweetener technology access and strategic partnerships for pharmacy channel qualification.
Within the scale-driven tier, Mars, Inc., The Hershey Company, and Mondelez International exemplify multinational infrastructure deployment. These entities occupy positions anchored by manufacturing scale and retail slotting leverage across United States, European, and select Asia-Pacific markets. Their archetype representation centers on volume throughput and cross-channel distribution consistency rather than niche formulation specialization.
| Leading Market Players |
|---|
| Mars, Inc. |
| The Hershey Company |
| Mondelez International |
| Ferrero International S.A. |
| Nestle S.A. |
| Perfetti Van Melle Group B.V. |
| Lotte Corporation |
| Atkinson Candy Company |
| Ricola Group Ltd. |
| Others |
Value Network & Pricing Analysis
Xylitol replacing sorbitol as the dominant bulking sweetener simultaneously redistributes manufacturing gravity toward Chinese fermentation clusters and compresses margin structures for European formulators locked into higher-cost grain-derived supply chains.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the sugar-free mints market. Price differentiation rests on certification grade—ISO 22000 and pharmacy-channel validation command 15-25 point premiums over convenience-tier equivalents—and volume scale, where hospitality procurement contracts above 10 million units annually unlock preferential terms. Pricing pressure stems from erythritol cost volatility in fermentation-based supply, with mid-tier formulators absorbing margin compression rather than passing through to shelf. Price-sensitive buyers cluster in private-label contract manufacturing, while dental-benefit substantiated brands in German pharmacy channels exhibit lowest elasticity.
Supply Chain Analysis
China, Thailand, and Finland anchor global xylitol production through corn-cob and birch-wood extraction pathways. Raw material dependencies center on fermentation feedstocks, moisture-barrier packaging films, and natural menthol extracts from Indian peppermint cultivation. Supply chain risk concentrates in single-source vulnerability for pharmaceutical-grade xylitol, where three facilities in Shandong Province supply 60 percent of global dental-certified volume. Distribution runs through consolidated retail pharmacy networks in Germany and Japan, with e-commerce direct-to-consumer models bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar-free mints market represents early-cycle expansion, with corporate wellness procurement in professional services firms creating institutional demand anchors that outpace traditional retail velocity.
For Market Incumbents: Fortify pharmacy channel positioning through accelerated ISO 22000 certification and microplastic-free packaging validation before REACH enforcement tightens in German retail. Consolidation of sweetener technology access via specialist acquisition defends against clean-label entrants capturing margin in subscription e-commerce. Backward integration into xylitol fermentation capacity in Southeast Asia hedges Chinese supply concentration.
For New Entrants and Emerging Players: FSSAI clean-label recognition fast-tracks positioning in Maharashtra and Gujarat, where functional confectionery frameworks remain underdeveloped relative to regulatory maturity. White-space targets include fruit-flavored liquid mints for Indian urban professionals and stevia-glycoside formulations for price-sensitive Southeast Asian markets. Go-to-market leverage rests on direct-to-consumer subscription models that bypass incumbent slotting fee structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed European clean-label specialists holding pharmacy channel relationships but lacking manufacturing scale. Long-term viability hinges on 5-10 year regulatory convergence toward WHO sugar reduction frameworks and FDA disclosure harmonization. Watch for inflection in India FSSAI enforcement intensity as signal for emerging market premiumization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Acceleration | Pharmacy channel access in Germany requires written quality management validation before listing approval. |
| Microplastic-Free Packaging Transition | REACH regulation updates force substrate validation for moisture-barrier performance without polypropylene laminates. |
| Direct-to-Consumer Subscription Launch | E-commerce replenishment models capture recurring margin pools while bypassing retail slotting fees. |
| Stevia-Rebaudiana Glycoside Blending | Enzymatic bioconvergence yields cleaner taste profiles without bitter aftertaste masking agents. |
| India FSSAI Clean-Label Registration | First-mover positioning in emerging functional confectionery framework creates regulatory moat. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this study. Stakeholder roles span brand managers at multinational confectioners, category buyers at German pharmacy chains, supply planners for hospitality procurement, and technical R&D directors specializing in sweetener stability. Secondary sources include FDA nutrition labeling guidance documents, EFSA sweetener safety assessments, FSSAI functional food notifications, and customs trade data on xylitol import flows. Bottom-up volume modeling triangulates against top-down category spending estimates from retail audit databases.
Sensitivity analysis on input assumptions tests forecast robustness across the projection horizon. Segmentation dimensions span physical format (hard, liquid, chewy), distribution channel (supermarket, e-commerce, pharmacy, convenience), and flavor profile (mint, fruit, herbal). CAGRs derive from regression against historical category velocity and penetration modeling in corporate wellness programs. Industry-specific inputs include xylitol price elasticity coefficients and subscription e-commerce adoption curves in United States urban centers.
Decision-makers should treat outputs as directional under base assumptions of regulatory enforcement continuity and sweetener safety clearance stability; material deviation in FDA or WHO guidance would warrant model refresh. Recalibration cycles align with material shifts in corporate wellness procurement specifications and pharmacy channel classification standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
North America Gummy Market
Confectionery
Gummy Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Caramel Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Fruit Jellies Market
Confectionery
Sugarless Chocolate Market
Confectionery
India Chocolate Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Xylitol Lollipops Market
Confectionery
Low-Fat Sweets Market
Confectionery
Gum Base Candy Market
Confectionery
Low Calorie Keto Desserts Market