
 Saudi Arabia Drinking Water Market | 2026-2036
Saudi Arabia Drinking Water Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Drinking Water Market Analytics
HoReCa buyers is bifurcating from residential bulk purchasers as Saudi hospitality capacity expands under Vision 2030 diversification targets. Hana Water leverages its Jeddah production base to anchor supply contracts with coastal resort developments. Nestlé Water competes through premium mineral positioning in urban retail, while Almarai extends its dairy-era cold-chain infrastructure into chilled bottled water distribution.
Drinking water in Saudi Arabia comprises desalinated, treated, or naturally sourced water meeting potable standards for direct human consumption, typically characterized by total dissolved solids below 500 mg per liter and compliance with SASO bottled water specifications. The product serves residential hydration, commercial food service, and industrial process needs across a kingdom where renewable freshwater scarcity necessitates advanced treatment infrastructure. Purified water leads volume through reverse osmosis desalination dominance, while mineral water commands margin premiums in retail and hospitality channels. Plastic bottles sustain packaging share through cost efficiency, though hospitality procurement is shifting toward glass and premium formats for experiential positioning.
SFDA enforces bottled water labeling and contaminant thresholds, while SASO governs product standards and packaging material compliance; MOHAP coordinates municipal distribution quality for non-bulk segments. These frameworks elevate capital requirements for new entrants and reward incumbent certification depth. Stakeholders must monitor desalination energy cost trajectories and hospitality contract renewal cycles as decisive variables for capacity planning and margin defense.
Market Dynamics
Desalination energy intensity and hospitality procurement fragmentation are restructuring Saudi Arabia drinking water economics, as Vision 2030 resort construction pulls supply contracts toward coastal production clusters while SFDA certification timelines compress operational flexibility.
Growth Catalysts
- Vision 2030 hospitality buildout:Resort and hotel construction along the Red Sea coast is generating bulk water procurement contracts that favor suppliers with adjacent desalination capacity.
- SFDA labeling harmonization:Unified contaminant thresholds and packaging disclosure rules are reducing cross-border compliance friction for treated water imports from GCC neighbors.
- Reverse osmosis membrane advancement:Energy recovery device integration at Jubail and Yanbu desalination complexes is lowering unit production costs for high-purity output.
Market Restraints
- Desalination feedstock concentration:Over 70% of Saudi municipal supply originates from Ras Al-Khair and Jubail megaplants, creating geographic vulnerability to single-point infrastructure disruption.
- SFDA certification lag:New entrant approval timelines for bottled water labeling compliance extend 14-18 months, freezing market access for uncertified imports.
- Petrochemical input cost volatility:PET resin prices track Saudi Aramco feedstock pricing, compressing bottle manufacturing margins during crude price spikes.
Strategic Opportunities
- Neom hospitality pre-positioning:The northwest giga-project's zero-carbon water specifications favor suppliers with renewable-powered desalination and premium packaging capabilities.
- Glass format hospitality penetration:Coastal resorts are substituting plastic with returnable glass for experiential dining, opening margin premiums for cold-chain distributors.
- SASO packaging material incentives:Post-consumer recycled content mandates for bottled water containers are rewarding early movers with recycled PET processing infrastructure.
Industry Challenges
- Desalination chemical handling certification:Plant operators face acute shortages of technicians credentialed for antiscalant and chlorine dioxide management under MOHAP safety protocols.
- Multi-regulator coordination friction:SFDA bottled water standards, SASO packaging rules, and MOHAP municipal quality mandates create overlapping inspection schedules that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Drinking Water Market |
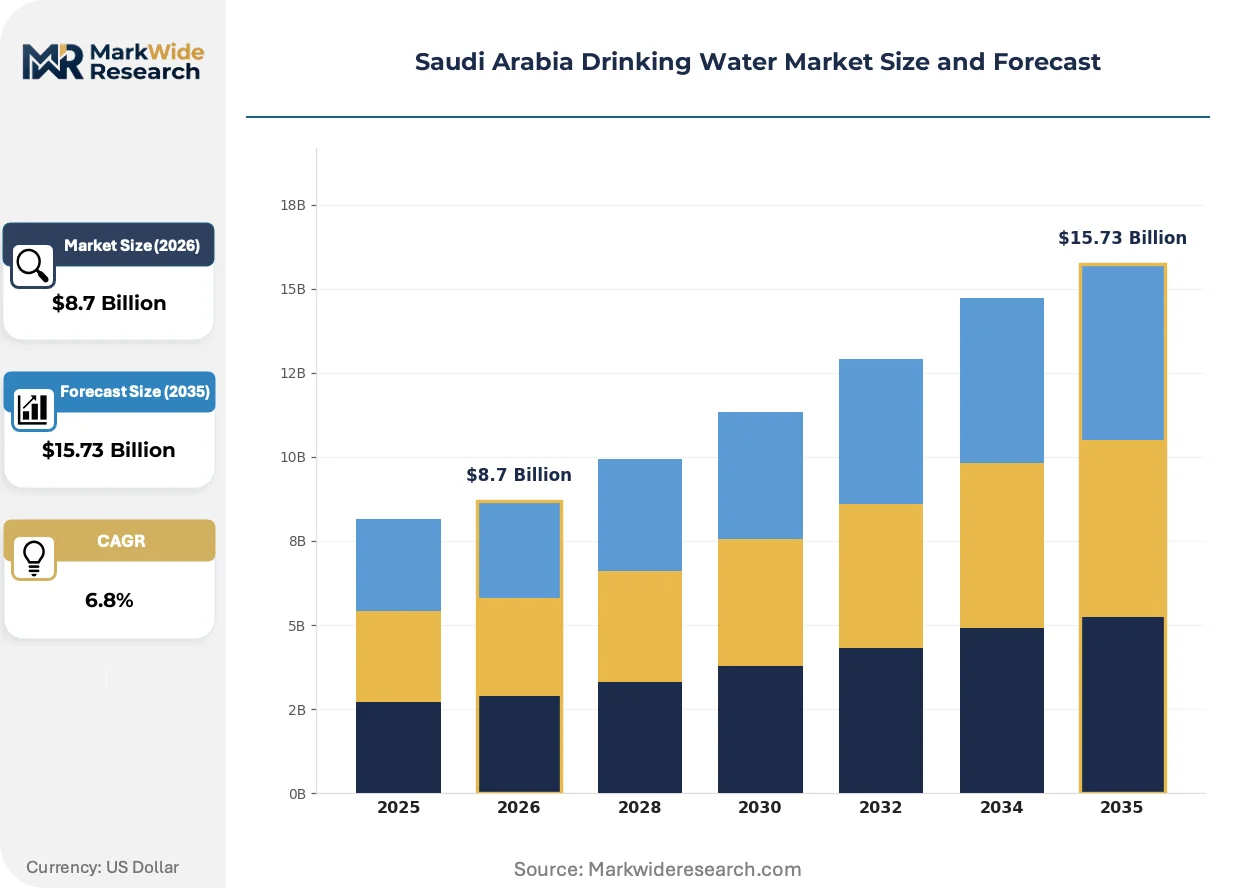
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottled Water, Purified Water, Mineral Water, Spring Water Distribution Channel: Retail Outlets, E-commerce, Direct Sales, HoReCa End User: Residential, Commercial, Industrial, Hospitality Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches |
| Companies Covered | Hana Water, Health Water Bottling Co, Aloyoun Water Factory Inc, Almarai, Nestlé Waters, Agthia Group, PepsiCo, Bin Zomah Group Trading & Manufacturing, Al Qassim Health Water, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Drinking Water Market Evolving Landscape
Container format diversification and certification-driven supply chain reconfiguration are compressing traditional procurement patterns in Saudi Arabia drinking water, as hospitality buyers decouple from residential distribution economics.
Membrane-based remineralization is decomposing the historical split between purified and mineral water categories. Hospitality procurement teams in Jeddah and Riyadh are adopting single-pass RO systems with calcite post-treatment to generate customized mineral profiles for premium positioning. This technology is decomposing the traditional two-supplier model where hotels sourced purified bulk and imported mineral brands separately.
SFDA's 2024 updated bottled water labeling regulation mandates real-time QR-code traceability for production batch and desalination source disclosure. The framework forces reformulation of legacy packaging designs and accelerates digital printing adoption among label converters. Small-format urban retail faces the steepest compliance cost absorption, driving consolidation among regional distributors lacking in-house regulatory affairs capacity.
HoReCa buyers are consolidating supplier relationships around full-service hydration contracts that bundle equipment, filtration maintenance, and consumable replenishment. Hotels along the Red Sea coast are displacing traditional wholesale purchasing with multi-year service agreements tied to guest satisfaction metrics. This pattern concentrates procurement authority among three Jeddah-based distributors with integrated technical service capabilities.
Saudi Arabia Drinking Water Market Segmentation
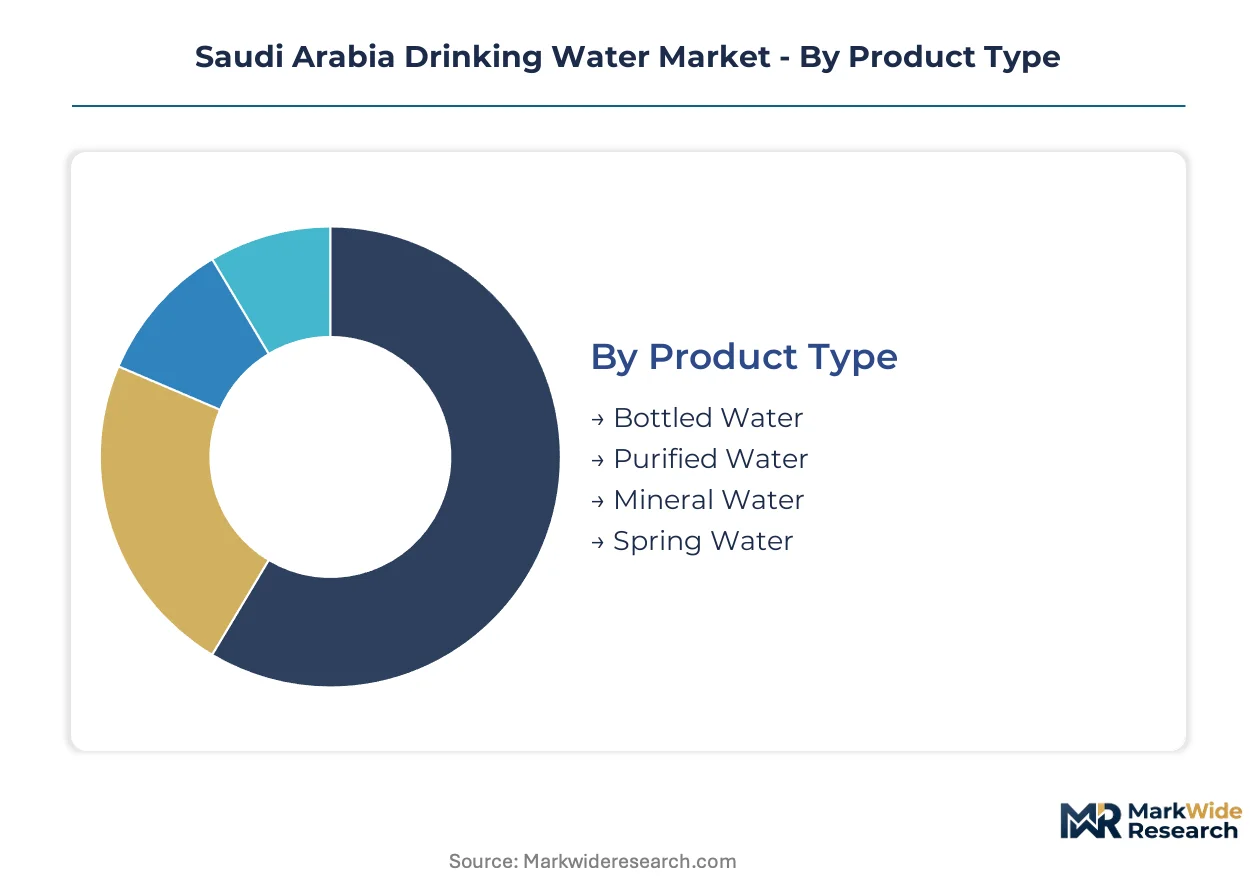
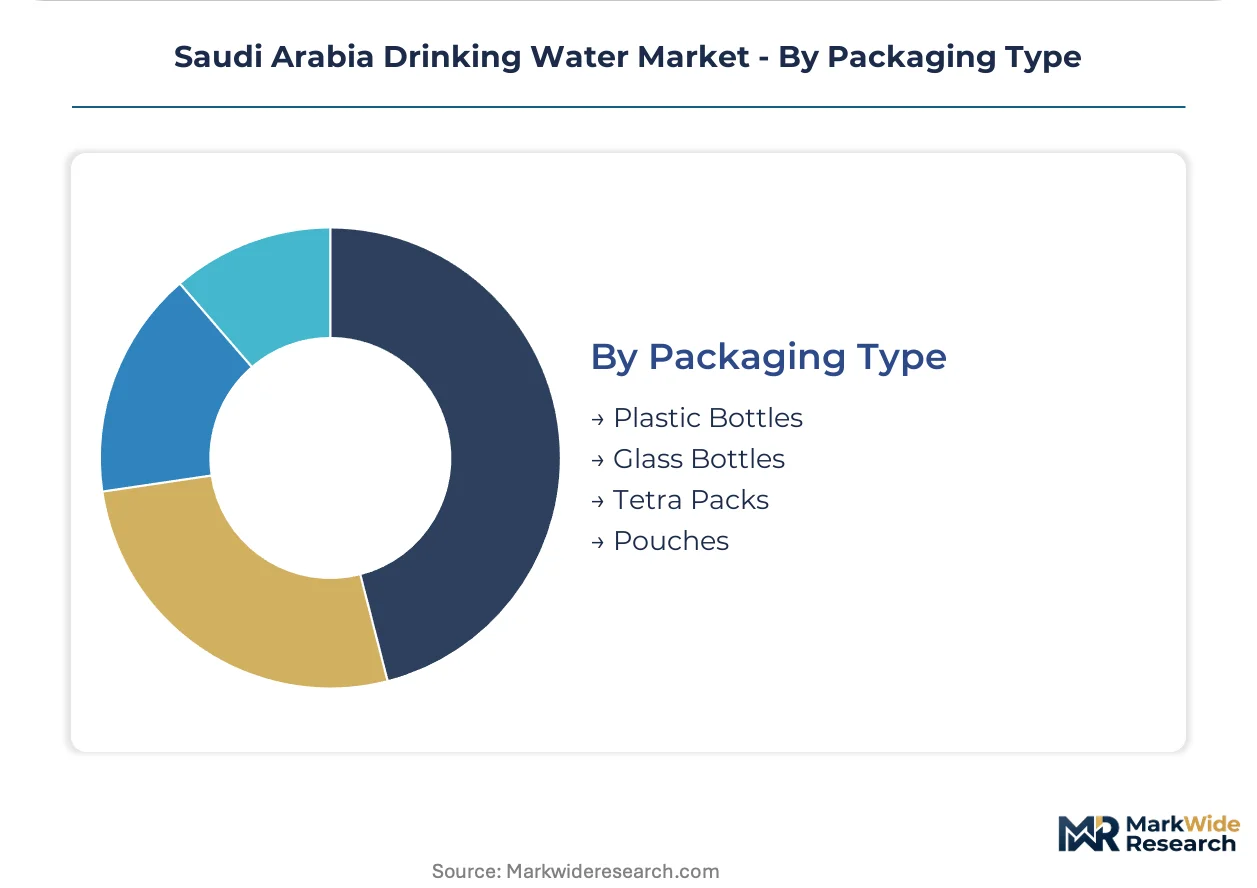
Saudi Arabia drinking water segmentation reflects regulatory boundaries enforced by SFDA and SASO, with certification requirements varying sharply across product categories and packaging formats. Understanding these divisions reveals where capital requirements concentrate and where operational flexibility survives.
Product Type:
SFDA contaminant thresholds and mineral content disclosure rules create divergent compliance burdens across water categories, with purified and mineral segments facing the strictest batch testing protocols.
- Bottled Water:Encompasses all packaged drinking water meeting SASO potable standards, typically sourced from desalination plants or treated municipal supply. Riyadh and Jeddah retail corridors absorb the bulk of volume as residential pantry stocking persists despite hospitality channel expansion.
- Purified Water:Reverse osmosis-treated water with total dissolved solids below 50 mg per liter, produced at Jubail and Yanbu megaplants. Industrial process demand in Eastern Province chemical complexes anchors offtake, while membrane advancement continues compressing unit energy costs.
- Mineral Water:Naturally sourced or artificially remineralized water with defined ionic profiles, commanding shelf price premiums in urban retail. SFDA mandates precise label disclosure of calcium, magnesium, and sodium content, extending new entrant approval timelines.
- Spring Water:Groundwater extracted from protected aquifers with minimal treatment, limited by Saudi Arabia's scarce renewable freshwater reserves. Niche positioning in premium hospitality gift channels sustains minimal volume.
Purified water handles the majority of throughput; mineral water is expanding most quickly on share as hospitality buyers premiumize hydration offerings.
Distribution Channel:
Channel economics split between high-frequency retail replenishment and contract-driven institutional procurement, with logistics infrastructure determining viable service radii from desalination clusters.
- Retail Outlets:Supermarkets, convenience stores, and petrol station kiosks sustaining grab-and-go residential demand across Riyadh, Jeddah, and Dammam metropolitan zones. Cold-chain requirements for chilled SKUs favor distributors with captive fleet capacity.
- E-commerce:Platform-mediated bulk ordering gaining traction among residential subscribers seeking scheduled replenishment. Last-mile delivery economics from Jeddah fulfillment centers constrain penetration beyond urban cores.
- Direct Sales:B2B bulk delivery to offices, factories, and construction sites, typically via 19-liter dispenser-compatible containers. Contract renewal cycles align with Ramadan and Hajj seasonal demand spikes.
- HoReCa:Hotels, restaurants, and catering operations procuring through multi-year service agreements bundling equipment and consumables. Red Sea coastal resort construction under Vision 2030 is pulling procurement authority toward Jeddah-based distributors with technical service capabilities.
Retail outlets handle the majority of throughput; HoReCa is climbing the fastest as hospitality capacity expands.
End User:
User segments separate by volume scale and quality specification intensity, with industrial and hospitality buyers imposing the most stringent supply continuity requirements.
- Residential:Individual and family consumption spanning pantry stocking, daily hydration, and meal preparation. Riyadh corridor density supports direct-to-home delivery subscription models.
- Commercial:Office buildings, retail premises, and service establishments with intermediate volume needs and moderate specification stringency. Central business district concentration in Jeddah and Khobar drives route density optimization.
- Industrial:Process water for food manufacturing, pharmaceutical production, and electronics fabrication requiring ultra-pure specifications. Jubail industrial city proximity to desalination infrastructure minimizes transport cost and quality degradation risk.
- Hospitality:Hotels, resorts, and event venues demanding premium presentation formats and consistent guest experience delivery. Neom giga-project specifications favor suppliers with renewable-powered desalination and glass packaging capabilities.
Residential handles the majority of throughput; hospitality is gaining share fastest under Vision 2030 construction timelines.
Packaging Type:
Material selection reflects tension between cost efficiency and experiential positioning, with SASO recycled content mandates accelerating format transition planning.
- Plastic Bottles:PET containers dominating volume through manufacturing cost efficiency and logistics durability. Post-consumer recycled content thresholds are forcing capital deployment into rPET processing infrastructure.
- Glass Bottles:Returnable and single-use formats commanding hospitality channel adoption for premium dining presentation. Weight and fragility limit viable distribution radius from coastal production bases.
- Tetra Packs:Aseptic cartons penetrating institutional catering and airline service applications where shelf stability and stackability outweigh unit cost premiums.
- Pouches:Flexible film formats for single-serve and bulk dispenser applications, constrained by consumer familiarity barriers and recycling infrastructure gaps.
Plastic bottles handle the majority of throughput; glass bottles are expanding most quickly on share as coastal resorts displace disposable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports desalinated drinking water to Bahrain and Kuwait through submarine pipeline corridors, while domestic consumption concentrates in four distinct economic zones shaped by infrastructure density and Vision 2030 construction timelines.
Riyadh
Central Province administrative and commercial capital absorbs the largest residential volume through direct-to-home delivery subscriptions. SFDA labeling mandates force distributors to maintain dedicated regulatory affairs teams in the metropolitan core. King Abdullah Financial District and Diriyah Gate developments are pulling hospitality procurement toward premium mineral formats.
Eastern Province
Jubail and Ras Al-Khair desalination megaplants anchor industrial process water demand from petrochemical complexes. MOHAP municipal quality protocols govern distribution to Dammam and Khobar residential corridors. The industrial city concentration creates captive offtake agreements with membrane-based purified water suppliers.
Western Region
Jeddah production clusters serve coastal resort developments along the Red Sea coast under Vision 2030 hospitality buildout schedules. Hana Water leverages its Jeddah base for bulk supply contracts with hotel operators. The port infrastructure enables import logistics for premium glass packaging materials.
NEOM Northwest
The giga-project's zero-carbon water specifications favor suppliers with renewable-powered desalination capabilities. NEOM procurement teams are pre-qualifying vendors through technical service bundling requirements. The Tabuk logistics corridor is absorbing cold-chain infrastructure investment for premium format distribution.
Saudi Arabia Drinking Water Market Competitive Landscape
Player mix skews toward vertically integrated dairy and beverage conglomerates with captive cold-chain infrastructure. Market structure concentrates around three Jeddah-based distributors controlling hospitality procurement through multi-year service agreements. Strategic archetypes include desalination-anchored regional producers, multinational premium mineral brands, and dairy-era logistics repurposers. Dominant competitive moves involve hospitality contract pre-positioning ahead of resort construction milestones and SASO recycled content compliance through rPET processing partnerships.
Among Saudi-based producers, Hana Water and Almarai occupy positions reflecting divergent heritage strategies. Hana Water exemplifies the coastal production cluster archetype with Jeddah-anchored supply contracts. Almarai represents dairy-era infrastructure repurposing into chilled bottled water distribution. Nestlé Waters sits within the multinational premium mineral positioning tier, competing through brand equity in urban retail corridors rather than hospitality bulk procurement.
| Leading Market Players |
|---|
| Hana Water |
| Health Water Bottling Co |
| Aloyoun Water Factory Inc |
| Almarai |
| Nestlé Waters |
| Agthia Group |
| PepsiCo |
| Bin Zomah Group Trading & Manufacturing |
| Al Qassim Health Water |
| Others |
Value Network & Pricing Analysis
Megaplant scale economies at Ras Al-Khair and Jubail desalination complexes compress unit production costs below regional competitors, anchoring price floors for bulk municipal supply while concentrating procurement leverage among three Jeddah-based distributors serving hospitality contracts.
Pricing Analysis
Membrane-generation pricing gaps separate legacy thermal desalination output from advanced reverse osmosis production and emerging renewable-powered installations. Three-tier pricing structure across premium glass-bottled hospitality formats, standard PET retail SKUs, and bulk dispenser contracts reflects certification grade and cold-chain service bundling. Cost compression in economy-tier purified water intensifies as Jubail capacity expansions feed oversupply into Riyadh corridors. HoReCa buyers show lowest price sensitivity due to guest-experience positioning requirements, while residential subscribers in Eastern Province demonstrate highest elasticity to delivery fee adjustments.
Supply Chain Analysis
Strategic stockpiling of PET resin and antiscalant chemicals dominates inventory strategy over just-in-time approaches, given Saudi Aramco feedstock price volatility and SFDA certification lag risks. Supply concentrates in Saudi Arabia for desalination output, with secondary inputs drawn from China for membrane modules and Germany for precision dosing equipment. Raw material dependencies center on petrochemical feedstocks, calcite remineralization media, and returnable glass logistics infrastructure. Single-source vulnerability pervades membrane supply chains. Distribution runs through captive cold-chain fleets controlled by vertically integrated dairy-era repurposers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi drinking water procurement is consolidating around platform-style service bundling, where hydration contracts integrate equipment maintenance, filtration servicing, and consumable replenishment into single-vendor relationships.
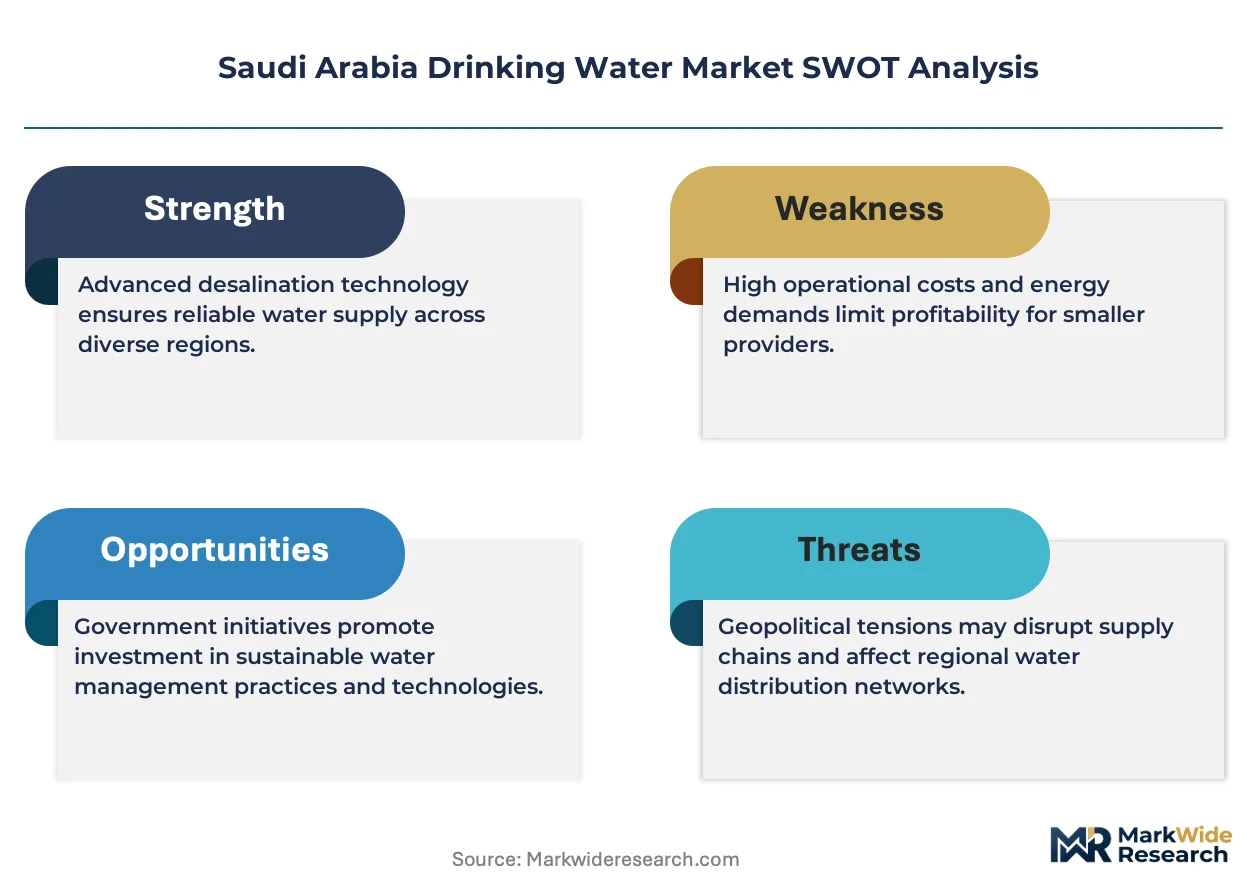
For Market Incumbents: Consolidate hospitality procurement authority through multi-year technical service agreements ahead of Red Sea resort construction milestones. Lock in rPET processing partnerships to meet SASO recycled content mandates before compliance deadlines tighten. SFDA labeling harmonization threatens margin compression for legacy packaging designs lacking QR-code traceability infrastructure. For New Entrants and Emerging Players: Differentiate on renewable-powered desalination credentials to capture Neom giga-project pre-qualification status. Target glass-format hospitality penetration along the Tabuk logistics corridor where cold-chain infrastructure investment lags coastal clusters. Pursue membrane-based remineralization technology licensing as the fastest route to premium mineral positioning without aquifer access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Jeddah-based distributors with integrated technical service capabilities and multi-year HoReCa contract backlogs. Long-term viability favors acquisition targets combining coastal production proximity with hospitality service bundling expertise. Watch for desalination energy cost trajectories crossing thresholds that render thermal plant retrofits economically unviable.| Strategic Initiative | Industry Significance |
|---|---|
| Hospitality Contract Pre-Positioning | Secures multi-year offtake ahead of Vision 2030 resort construction milestones. |
| rPET Processing Infrastructure Deployment | Positions suppliers for SASO post-consumer recycled content mandate compliance. |
| Membrane-Based Remineralization Licensing | Enables premium mineral positioning without scarce renewable aquifer access. |
| Renewable-Powered Desalination Certification | Qualifies vendors for Neom zero-carbon water procurement specifications. |
| Integrated Technical Service Bundling | Consolidates procurement authority against fragmented wholesale competitors. |
Research Methodology
Cross-validation between primary field interviews and regulatory filing analysis anchors the qualitative findings in documented compliance patterns. Conversations with desalination plant operators, HoReCa procurement directors, SFDA regulatory affairs specialists, and cold-chain logistics managers combined with SASO standards documentation, MOHAP quality protocols, customs trade records, and hospitality development permit databases. Bottom-up volume triangulation against top-down macroeconomic absorption models validated segment-level projections.
Sensitivity analysis around energy cost trajectories and hospitality construction timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user vertical alongside desalination technology generation tier. CAGRs derived from historical absorption pattern extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated membrane efficiency advancement curves and recycled content mandate phase-in schedules.
The analysis sits within stated boundaries; outcomes outside sustained Vision 2030 construction pacing and stable petrochemical feedstock pricing would require recalibration. Forecasts reflect assumptions regarding SFDA certification timeline stability and hospitality procurement consolidation trends. Revision becomes warranted when desalination energy cost volatility crosses thresholds that disrupt incumbent cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Oat Based Beverages Market
Beverages
CBD-Infused Beverages Market
Beverages
Wellness Water Market
Beverages
Nitro-Infused Beverages Market
Beverages
Europe Coconut Water Market
Beverages
Sparkling Bottled Water Market
Beverages
China Soy Beverages Market
Beverages
Foaming Creamer Market
Beverages
Soy Drinks Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Beverage Dispenser Market
Beverages
Recovery Drinks Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
North America Energy Drink Market
Beverages
Europe Sugar Free Energy Drinks Market