
 Asia-Pacific Solar E-Bike Market | 2026-2036
Asia-Pacific Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solar E-Bike Market Analytics
Subscription-based battery-swapping infrastructure is hardening as the core revenue layer in the Asia-Pacific solar e-bike ecosystem. Yadea Group Holdings Ltd leverages its charging network density to lock in recurring revenue streams across Chinese cities. Aima Technology Group Co. Ltd anchors its competitive stance through backward integration into lithium-ion pack assembly. Giant Manufacturing Co. Ltd specializes in high-efficiency photovoltaic panel integration for its premium hybrid models.
An Asia-Pacific solar e-bike combines photovoltaic surface integration with electric pedal-assist propulsion, typically incorporating monocrystalline silicon cells rated between 50-100 watts mounted on frame surfaces or cargo enclosures to trickle-charge battery systems during daylight exposure. The primary commercial purpose centers on reducing grid dependency for urban and semi-urban mobility while extending effective range per charge cycle. Lithium-ion battery configurations dominate unit economics due to superior energy density and cycle life, though nickel-metal hydride retains niche positioning in cost-sensitive Indian municipal fleets. Hybrid product architecture captures the widest addressable base by offering dual-mode reliability during monsoon seasons or extended cloud cover. Delivery services represent the most structurally attractive end-user segment, characterized by predictable route patterns, high daily utilization rates, and fleet-scale procurement contracts that amortize solar premium pricing.
India's BIS certification mandates for electric two-wheeler safety and China's GB standards for photovoltaic equipment create dual compliance thresholds for cross-border manufacturers. Japan's METI feed-in tariff derivatives and Australia's Clean Energy Regulator incentives shape demand-side economics for solar-assisted transport adoption. Stakeholders must monitor regulatory divergence between national battery recycling obligations and emerging cross-border carbon accounting frameworks for renewable-powered mobility assets.
Market Dynamics
Subscription-based battery-swapping infrastructure is hardening as the core revenue layer across the Asia-Pacific solar e-bike ecosystem, locking fleet operators into recurring payment structures that amortize hardware costs while creating captive demand for charging network services.
Growth Catalysts
- India's PLI scheme for advanced chemistry cell batteries:The production-linked incentive framework is reshoring lithium-ion pack assembly capacity, compressing import dependency for Vietnamese and Thai assemblers.
- Last-mile delivery fleet electrification:Predictable route patterns and high daily utilization rates among Southeast Asian logistics operators justify solar premium pricing through fuel cost arbitrage.
- Monocrystalline silicon cell efficiency gains:50-100 watt photovoltaic surfaces now deliver meaningful range extension during daylight exposure, reducing grid dependency for urban corridors.
Market Restraints
- Polysilicon price volatility:Raw material cost swings for photovoltaic-grade silicon strain margin predictability for frame-integrated solar panel manufacturers.
- Dual compliance thresholds:India's BIS certification mandates for electric two-wheeler safety and China's GB standards for photovoltaic equipment create cross-border regulatory friction for regional assemblers.
- Monsoon season reliability gaps:Extended cloud cover in Vietnam's urban corridor and Philippine archipelago markets degrades solar trickle-charge consistency, forcing hybrid backup dependency.
Strategic Opportunities
- Indonesia's underpenetrated urban corridor:Jakarta-Bandung-Surabaya freight networks lack dedicated solar e-bike fleet operators, presenting first-mover whitespace for battery-swapping infrastructure deployment.
- Japan's METI feed-in tariff derivatives:Renewable energy credit frameworks for solar-assisted transport create demand-side subsidy pools that improve unit economics for premium hybrid models.
- Photovoltaic-battery management system convergence:Integrated charge optimization algorithms that balance solar input, grid charging, and discharge cycles enable predictive maintenance revenue streams.
Industry Challenges
- Photovoltaic integration engineering talent scarcity:Frame-mounted cell durability design and weatherproofing expertise concentrates among a narrow supplier base in China's Jiangsu and Zhejiang provinces.
- Cross-border carbon accounting complexity:Emerging frameworks for renewable-powered mobility asset verification lack harmonization between Australia's Clean Energy Regulator methodologies and ASEAN national standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solar E-Bike Market |
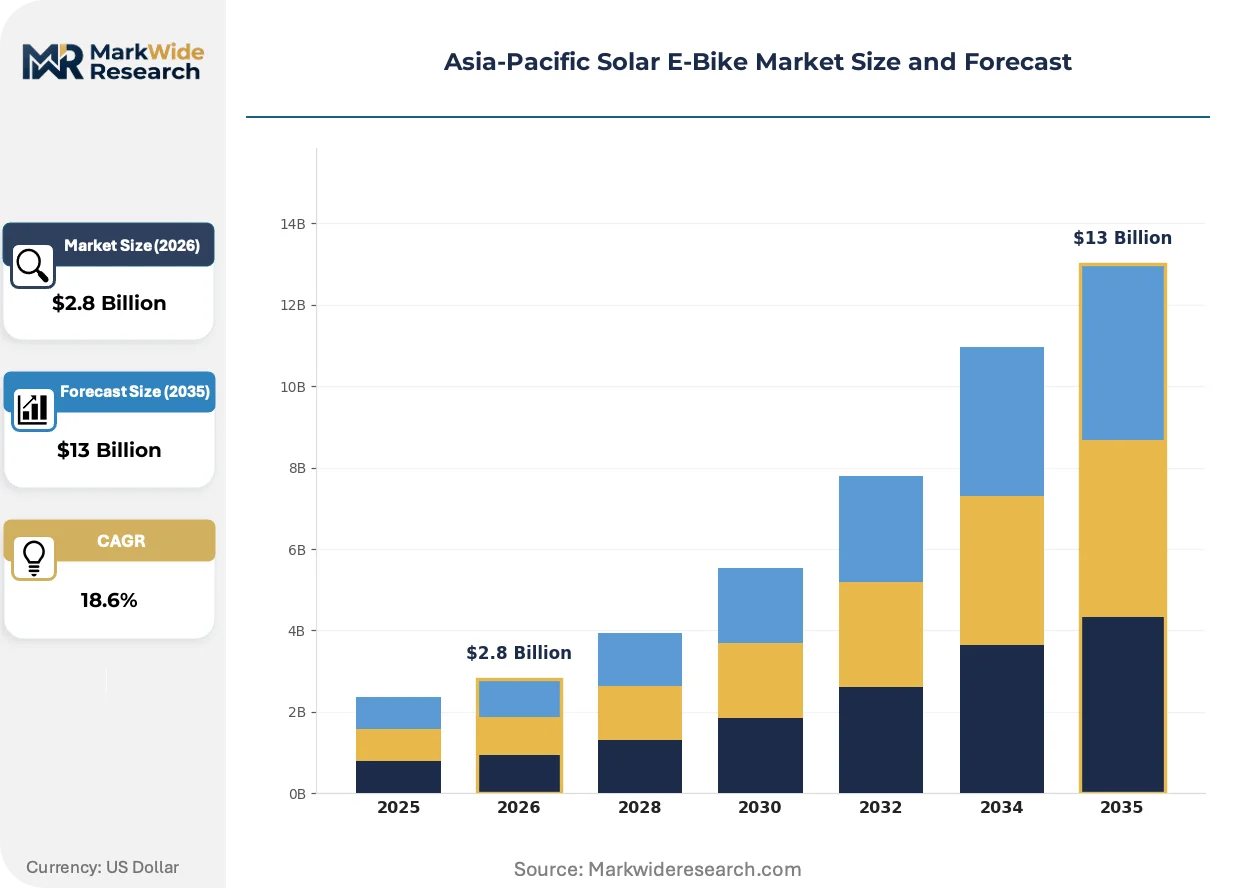
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar-Powered, Hybrid, Standard Electric, Folding End User: Urban Commuters, Recreational Riders, Delivery Services, Tourists Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Others Charging Method: Solar Panel, Plug-In, Regenerative Braking, Wireless |
| Companies Covered | Yadea Group Holdings Ltd, Aima Technology Group Co. Ltd, Giant Manufacturing Co. Ltd, Merida Industry Co. Ltd, Yamaha Motor Company, Jiangsu Xinri E-Vehicle Co. Ltd, CSE EV Group Co. Ltd, Shenzhen TAILG Technology Group Co. Ltd, Fuji-Ta Bicycle Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solar E-Bike Market Evolving Landscape
Photovoltaic surface integration is advancing from auxiliary range extension toward primary propulsion energy contribution, reshaping competitive positioning around charging network density and solar conversion efficiency rather than battery capacity alone.
Perovskite-silicon tandem cell architectures are overtaking conventional monocrystalline panels for frame-integrated applications. These dual-junction configurations harvest broader spectrum sunlight, extending effective charging hours during partial cloud cover. Vietnamese last-mile operators are piloting cargo-enclosure installations that leverage the technology's lighter weight-to-output ratio. The structural consequence is overtaking incumbent suppliers who lack thin-film deposition partnerships.
China's GB standards for photovoltaic equipment are tightening efficiency certification thresholds for imported solar modules, creating technical barriers for non-domestic panel suppliers. The MIIT framework now mandates traceable supply chain documentation for rare earth elements in permanent magnet motors paired with solar charging systems. Premium hybrid manufacturers serving cross-border markets are responding by localizing final assembly within mainland China to secure GB compliance.
Fleet-scale procurement contracts are displacing individual consumer purchases as the dominant transaction structure across the Asia-Pacific solar e-bike market. Delivery services and municipal logistics operators now negotiate multi-year leasing arrangements that bundle hardware, battery-swapping access, and maintenance into per-kilometer pricing. This concentration is most visible in Vietnam's Ho Chi Minh City-Da Nang urban corridor, where regional food delivery platforms have consolidated vendor relationships around three network operators.
Asia-Pacific Solar E-Bike Market Segmentation
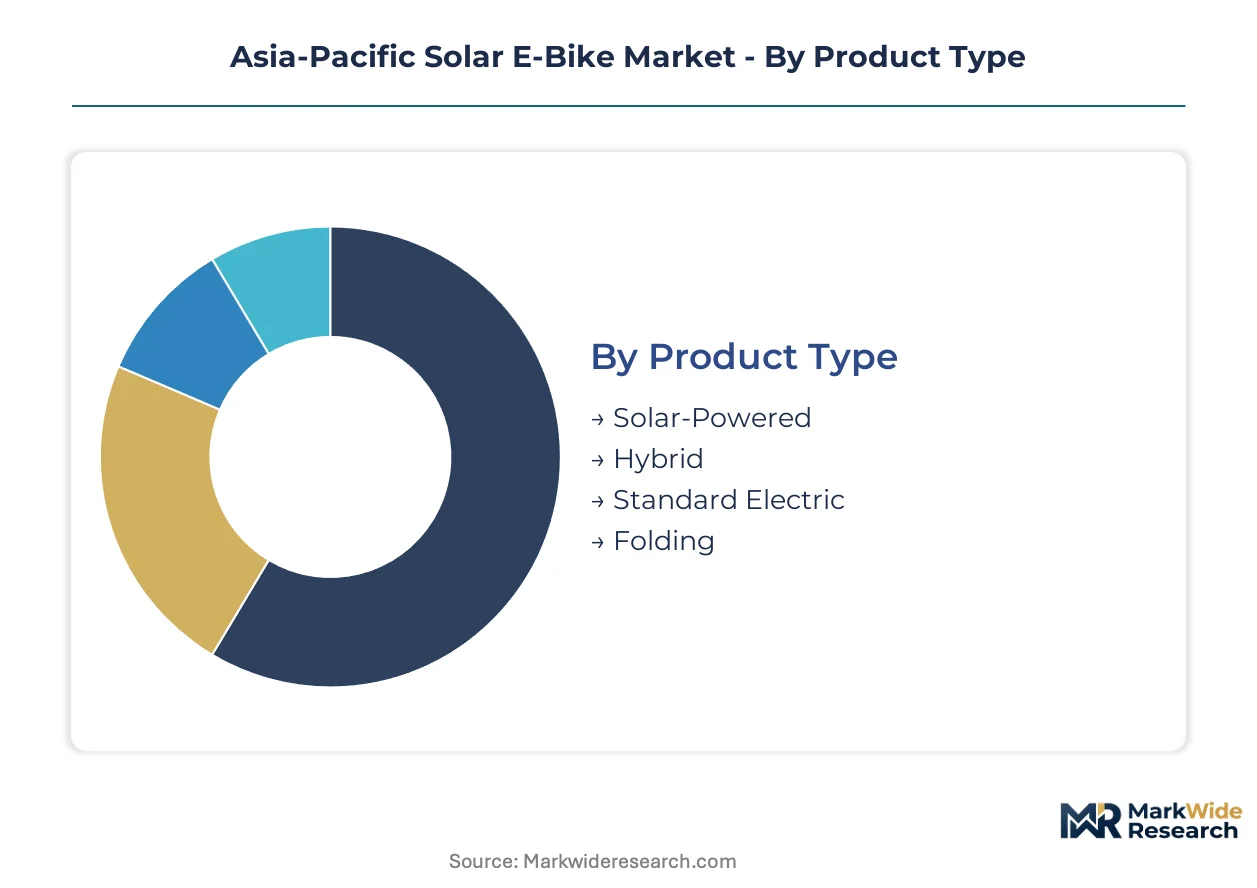
Segmentation in the Asia-Pacific solar e-bike market reveals how photovoltaic integration depth, battery chemistry trade-offs, and charging infrastructure availability reshape procurement patterns across fleet operators and individual buyers. Understanding these axes exposes where margin concentrates and where technology transitions disrupt incumbent positioning.
Product Type:
Photovoltaic surface area and propulsion architecture differentiate competitive positioning across Vietnamese fleet tenders and Indian municipal contracts.
- Hybrid:Dual-mode systems pair 50-100 watt monocrystalline panels with grid-chargeable battery packs, ensuring operational continuity during monsoon cloud cover in Ho Chi Minh City-Da Nang corridor operations. Delivery services anchor procurement volume here, accepting 15-20% unit cost premiums for route reliability.
- Solar-Powered:Frame-integrated photovoltaic panels rated 80-120 watts deliver primary propulsion energy for last-mile logistics with predictable daylight exposure patterns. Deployment concentrates in Indonesia's underpenetrated Jakarta-Bandung freight networks where grid infrastructure remains sparse.
- Standard Electric:Conventional plug-dependent architectures without photovoltaic augmentation serve cost-sensitive Indian municipal fleets and recreational segments where capital constraints override range extension priorities.
- Folding:Collapsible frame designs accommodate multi-modal urban transit integration across Japan's dense metropolitan corridors, with solar charging capabilities limited to auxiliary battery maintenance rather than primary propulsion contribution.
Mature deployment sits with Hybrid configurations. Newer deployment is concentrated in Solar-Powered systems as perovskite-silicon tandem efficiency gains extend effective charging hours.
End User:
Utilization intensity and route predictability determine whether solar premium pricing amortizes through operational savings.
- Delivery Services:Fleet-scale operators negotiate multi-year leasing with embedded battery-swapping access, converting per-kilometer economics into captive revenue for charging network providers. Vietnam's food delivery platforms consolidated vendor relationships around three network operators in this segment.
- Urban Commuters:Individual purchasers across Chinese cities prioritize subscription-based battery-swapping infrastructure density over solar conversion efficiency, treating photovoltaic range extension as secondary to charging convenience.
- Recreational Riders:Weekend usage patterns with lower daily mileage dilute solar payback calculations, pushing demand toward standard electric architectures in price-sensitive Indian markets.
- Tourists:Short-term rental operators in Thailand and Philippine beach destinations deploy folding solar e-bikes for island-hopping itineraries where grid access proves intermittent.
Delivery Services command the steepest expansion trajectory as fleet electrification mandates harden across Southeast Asian logistics networks. Urban Commuters retain the largest installed base volume.
Battery Type:
Energy density and cycle life specifications trade off against import dependency and local assembly incentives.
- Lithium-Ion:Advanced chemistry cell configurations dominate unit economics through superior energy density and 800-1200 cycle lifespans. India's PLI scheme is reshoring pack assembly capacity, compressing Vietnamese and Thai import dependency.
- Nickel-Metal Hydride:Lower energy density but improved temperature tolerance suits Indian municipal fleet tenders where procurement committees prioritize capital cost minimization over total cost of ownership.
- Lead Acid:Legacy chemistry retains niche positioning in rural Indonesian markets with minimal cold-chain logistics requirements and abundant recycling infrastructure.
- Others:Solid-state and sodium-ion prototypes circulate through Japanese METI-funded pilot programs, though commercial scale remains constrained by GB standards compliance timelines.
Lithium-Ion anchors current procurement volume. Nickel-Metal Hydride is gaining share fastest in cost-sensitive public sector tenders.
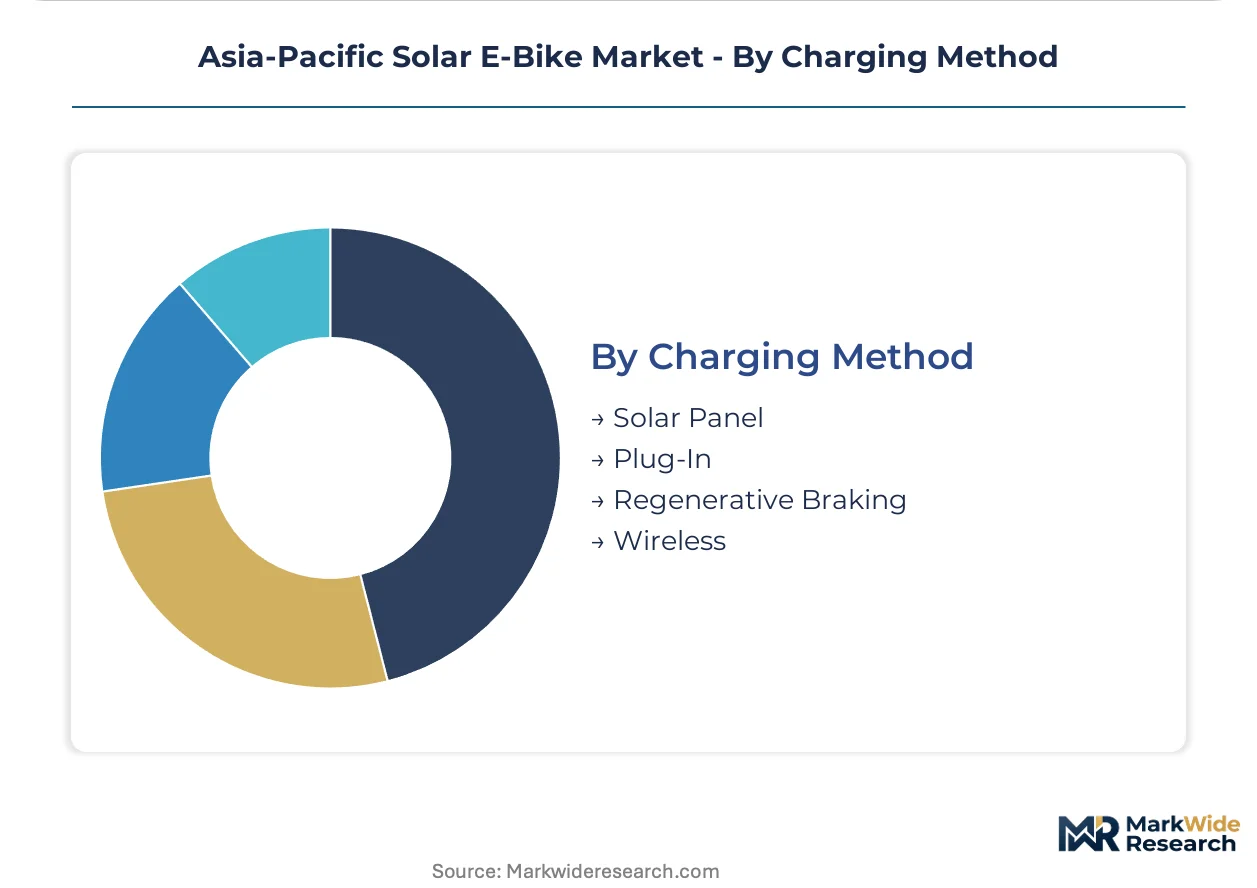
Charging Method:
Infrastructure access patterns and capital deployment preferences segment operator choices between asset-heavy and asset-light models.
- Solar Panel:Frame-mounted or cargo-enclosure photovoltaic surfaces enable off-grid operation for Indonesian archipelago logistics and Philippine rural delivery networks. Perovskite-silicon tandem architectures are overtaking conventional monocrystalline for these applications.
- Plug-In:Conventional grid charging dominates Chinese urban markets where MIIT-mandated charging infrastructure density supports overnight residential and workplace top-up patterns.
- Regenerative Braking:Kinetic energy recovery systems supplement battery range in hilly Vietnamese terrain and Japanese mountainous corridors, though contribution remains marginal to total energy balance.
- Wireless:Inductive charging pads pilot in premium Japanese hybrid models and Singaporean smart city demonstrations, with standardization gaps limiting cross-manufacturer interoperability.
Plug-In infrastructure supports mature deployment density. Solar Panel integration represents the fastest-climbing configuration as monocrystalline efficiency gains and battery-swapping network expansion converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates photovoltaic panel and lithium-ion pack production capacity while Vietnam and India absorb the bulk of fleet procurement volume. This production-consumption divide shapes cross-border supply chain configuration and regulatory compliance strategy across the region.
China
Jiangsu and Zhejiang provinces host the dominant concentration of frame-integrated solar panel engineering talent and monocrystalline cell manufacturing infrastructure. MIIT's GB standards for photovoltaic equipment tighten efficiency certification thresholds for imported modules, forcing regional assemblers to localize final assembly within mainland China. The Yangtze River Delta cluster around Suzhou and Ningbo anchors captive supply relationships for permanent magnet motors paired with solar charging systems.
Vietnam
Food delivery platforms and last-mile logistics operators drive fleet-scale procurement concentrated in the Ho Chi Minh City-Da Nang urban corridor. Predictable route patterns and high daily utilization rates amortize solar premium pricing through fuel cost arbitrage against gasoline-powered two-wheelers. Three network operators have consolidated vendor relationships here, locking fleet operators into subscription-based battery-swapping infrastructure.
India
Municipal fleet tenders and cost-sensitive delivery operators anchor demand, with procurement committees prioritizing capital cost minimization in nickel-metal hydride configurations. The PLI scheme for advanced chemistry cell batteries is reshoring lithium-ion pack assembly capacity, compressing import dependency for Vietnamese and Thai assemblers. Maharashtra and Gujarat industrial corridors are emerging as battery pack integration hubs.
Indonesia
Jakarta-Bandung-Surabaya freight networks present first-mover whitespace for solar e-bike fleet operators where grid infrastructure remains sparse. Frame-mounted photovoltaic surfaces enable off-grid operation across the archipelago, with perovskite-silicon tandem architectures piloting in cargo-enclosure installations. Local recycling infrastructure for lead-acid batteries retains niche positioning in rural markets with minimal cold-chain logistics requirements.
Japan
METI feed-in tariff derivatives create demand-side subsidy pools that improve unit economics for premium hybrid models in dense metropolitan corridors. Kanto and Kansai regions pilot solid-state and sodium-ion prototypes through government-funded programs, though commercial scale remains constrained by GB standards compliance timelines. Folding solar e-bike configurations accommodate multi-modal urban transit integration across Tokyo and Osaka.
Asia-Pacific Solar E-Bike Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific solar e-bike ecosystem. Integrated manufacturers with captive photovoltaic panel and battery pack assembly capacity face pressure from regional assemblers sourcing modular components. Three strategic archetypes dominate: charging network operators monetizing subscription infrastructure, backward-integrated battery specialists controlling lithium-ion chemistry, and premium hybrid manufacturers differentiating through photovoltaic conversion efficiency. Competitive moves concentrate on geographic expansion into underpenetrated Indonesian corridors and technology licensing partnerships for perovskite-silicon tandem cell integration.
Among Chinese fabricators, Yadea Group Holdings Ltd and Aima Technology Group Co. Ltd exemplify divergent strategic postures within the integrated manufacturer archetype. Taiwan-based Giant Manufacturing Co. Ltd occupies a position in the premium hybrid tier, while Japanese-listed Yamaha Motor Company represents the diversified motor vehicle conglomerate archetype with cross-segment technology transfer capabilities. These three entities anchor competitive dynamics around charging network density, backward integration depth, and photovoltaic efficiency certification respectively.
| Leading Market Players |
|---|
| Yadea Group Holdings Ltd |
| Aima Technology Group Co. Ltd |
| Giant Manufacturing Co. Ltd |
| Merida Industry Co. Ltd |
| Yamaha Motor Company |
| Jiangsu Xinri E-Vehicle Co. Ltd |
| CSE EV Group Co. Ltd |
| Shenzhen TAILG Technology Group Co. Ltd |
| Fuji-Ta Bicycle Co. Ltd |
| Others |
Value Network & Pricing Analysis
Polysilicon spot price volatility cascades through frame-integrated solar panel manufacturing into three-tier pricing structure across premium, standard, and economy levels, compressing margin buffers for Vietnamese assemblers while amplifying cost-down pressure on Indian municipal fleet tenders.
Pricing Analysis
Cost-down pressure on hybrid configurations accelerates because monocrystalline silicon cell efficiency gains commoditize mid-tier photovoltaic integration. Pricing stratifies across premium, standard, and economy tiers based on GB standards certification level and battery-swapping network bundling. Fleet-scale procurement contracts command steepest discounts through multi-year offtake commitments. Delivery services exhibit lowest price sensitivity; recreational riders in India face highest capital constraint pressure.
Supply Chain Analysis
Container freight rates from Jiangsu and Zhejiang provinces to Ho Chi Minh City-Da Nang corridor feed directly into landed cost calculations for Vietnamese fleet operators. Manufacturing gravity centers on China for monocrystalline cells, India for PLI-reshoring lithium-ion pack assembly, and Vietnam for final frame integration. Raw material flows draw from polysilicon smelters, rare earth magnet processors, and advanced chemistry cell electrolyte suppliers. Single-source vulnerability concentrates in frame-mounted cell weatherproofing expertise. Distribution runs through battery-swapping network operators capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite-silicon tandem architectures are displacing conventional monocrystalline panels as the dominant photovoltaic integration pathway, rendering legacy frame-assembly partnerships obsolete.
For Market Incumbents: Acquire thin-film deposition capability and perovskite-silicon tandem cell partnerships to neutralize technology substitution risk from Chinese Jiangsu-Zhejiang suppliers. Lock in multi-year lithium-ion offtake contracts before India's PLI scheme saturates regional pack assembly capacity. Battery-swapping network density serves as the critical defensive moat against modular assemblers. For New Entrants and Emerging Players: METI feed-in tariff derivatives in Japan open a window for premium hybrid model entry with solid-state battery pilot positioning. Indonesia's Jakarta-Bandung-Surabaya freight networks present first-mover whitespace for solar-powered cargo-enclosure deployments where grid infrastructure remains sparse. Anchor go-to-market strategy through direct fleet operator leasing rather than retail channel buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor battery-swapping infrastructure operators with captive demand from Vietnamese food delivery platforms. Long-term viability hinges on 5-10 year renewable energy credit framework durability across Japan and Australia. Monitor polysilicon price stabilization as inflection signal for photovoltaic panel manufacturer margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Integration | Extends effective charging hours for Vietnamese fleet operators during monsoon cloud cover periods. |
| Battery-Swapping Network Expansion | Locks recurring revenue streams from Indonesian logistics operators in grid-sparse archipelago corridors. |
| PLI-Aligned Lithium-Ion Assembly | Compresses import dependency for Thai and Vietnamese assemblers sourcing from Maharashtra-Gujarat hubs. |
| GB Standards Localization | Secures MIIT compliance for cross-border manufacturers serving Chinese urban commuter segments. |
| Cargo-Enclosure Photovoltaic Pilot | Validates lighter weight-to-output ratio for Indonesian last-mile freight network deployment. |
Research Methodology
Multi-period observation of photovoltaic cell efficiency benchmarks and battery-swapping network deployment rates anchored the trend analysis, supplemented by interviews with fleet procurement managers at Vietnamese food delivery platforms, lithium-ion pack assembly engineers at Indian PLI beneficiaries, photovoltaic equipment certification specialists at MIIT-accredited labs, and logistics operators across Indonesia's Jakarta-Bandung corridor. Secondary validation drew from MIIT GB standards filings, India's BIS certification registries, METI renewable energy credit disclosures, customs trade data for monocrystalline silicon cell imports, and ASEAN automotive production databases. Bottom-up unit shipment tallies triangulated against top-down addressable market sizing.
Input-output matrices mapped photovoltaic surface area specifications against battery chemistry configurations and charging infrastructure availability across the projection horizon. Segmentation dimensions modeled included product architecture, end-user utilization intensity, battery type energy density tiers, and charging method infrastructure dependency. CAGRs derived from slope analysis of historical procurement volume trajectories and elasticity estimates for solar premium pricing acceptance. Forecast inputs incorporated monsoon season reliability coefficients and feed-in tariff derivative policy durability assumptions.
The model assumes a particular technology adoption path for perovskite-silicon tandem cell integration; alternative pathways for solid-state battery commercialization would alter the outlook for premium hybrid manufacturer positioning. Forecasts reflect documented assumptions regarding PLI scheme continuation timelines and GB standards enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
US Electric Bus Battery Pack Market
Electric Vehicles
Hybrid EV Conversion Kit Market