
 Hybrid Electric Vehicle Battery Market | 2026-2036
Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Electric Vehicle Battery Market Insights
Performance metrics and cost structures between premium lithium-ion packs and commodity nickel-metal hydride systems is decoupling as cell chemistry divergence widens. LG Energy Solution leverages its cylindrical cell expertise to anchor supply contracts with premium passenger car programs. Contemporary Amperex Technology Co. Limited dominates prismatic lithium iron phosphate production for cost-sensitive commercial truck applications. Samsung SDI competes through solid-state R&D pipelines targeting next-generation energy density thresholds.
A hybrid electric vehicle battery stores electrical energy through electrochemical processes, typically employing lithium-ion cells with nominal voltages between 200-400V or nickel-metal hydride modules with 1.2V cylindrical cells, to supplement internal combustion engines during acceleration and recapture kinetic energy through regenerative braking. The battery's primary purpose is to enable fuel consumption reduction while maintaining driving range flexibility absent in full battery electric vehicles. Lithium-ion chemistry leads installed capacity across passenger car applications where energy density requirements prioritize mass reduction. Nickel-metal hydride retains structural share in commercial trucks and public transport where cycle life durability and thermal stability outweigh gravimetric performance. Solid-state technology occupies emerging prototype stages with OEM validation programs targeting enhanced safety margins and extended operating temperature windows.
The EPA tailpipe standards and China's MIIT dual carbon goals compress development timelines while the EU Green Deal's F-Gas Regulation shapes thermal management system specifications for European-bound platforms. Japan's METI battery supply chain initiatives and South Korea's K Battery strategy direct national subsidy flows toward domestic cell manufacturing scale. Stakeholders must monitor regulatory calibration between emissions mandates and raw material sourcing constraints as chemistry selection decisions lock in decade-long capital commitments.
Market Dynamics
Cell chemistry divergence between lithium-ion and nickel-metal hydride architectures is fragmenting supplier tiers as OEMs lock in decade-long platform commitments based on divergent energy density and cycle life requirements. This structural split is compressing R&D timelines while amplifying capital intensity for parallel chemistry pipelines.
Growth Catalysts
- EPA tailpipe emissions standards:Tightened corporate average fuel economy mandates force accelerated hybrid powertrain deployment across light-duty truck portfolios.
- Fleet operator TCO modeling:Total cost of ownership calculations favor electrified powertrains in commercial logistics applications with high daily mileage.
- Prismatic lithium iron phosphate cells:Cost-sensitive commercial truck segments adopt these modules for thermal stability under sustained duty cycles.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress cell manufacturer margins and destabilize long-term contract pricing.
- Japanese supplier concentration:Dense supplier networks in Toyota and Honda corridors create single-source vulnerability for nickel-metal hydride pack assembly.
- Gravimetric performance ceiling:Nickel-metal hydride chemistry hits fundamental energy density limits that disqualify it from premium passenger car applications.
Strategic Opportunities
- India commercial vehicle electrification:PLI scheme subsidies for domestic cell manufacturing create first-mover advantages for hybrid bus and truck platforms.
- Solid-state battery convergence:Next-generation energy density thresholds from solid-state R&D pipelines unlock extended-range hybrid architectures.
- EU Green Deal F-Gas Regulation:Thermal management system specifications for European-bound platforms favor advanced cooling-integrated pack designs.
Industry Challenges
- Electrochemical engineering talent scarcity:Shortage of specialists in solid-state electrolyte formulation slows prototype-to-production timelines.
- Dual chemistry certification complexity:Parallel validation of lithium-ion and nickel-metal hydride packs under UN 38.3 and UL 2580 standards extends development cycles.
- Legacy thermal management integration:Retrofitting advanced battery cooling into existing vehicle architectures requires substantial redesign of HVAC and power electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Electric Vehicle Battery Market |
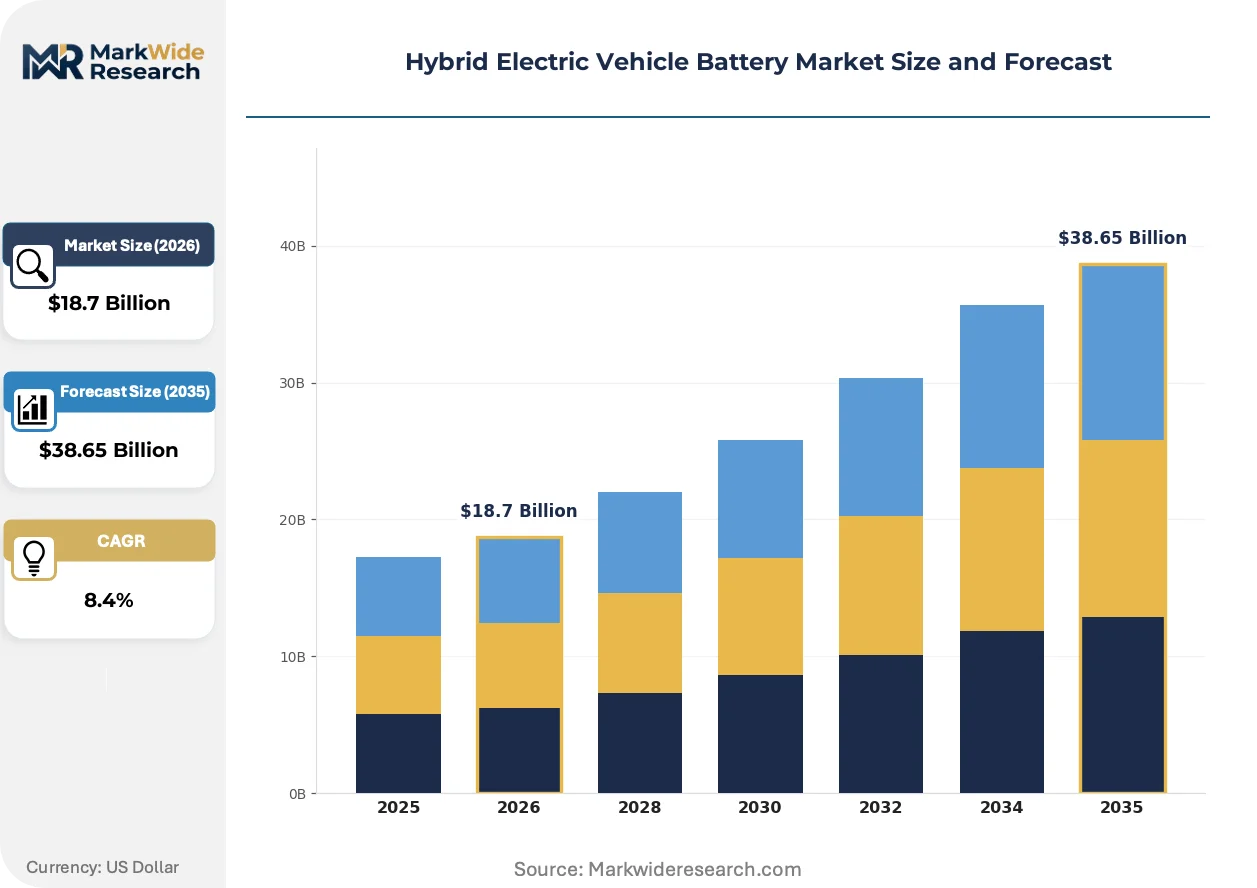
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Application: Passenger Cars, Commercial Trucks, Public Transport, Motorcycles End User: OEMs, Fleet Operators, Private Consumers, Aftermarket Providers Technology: Regenerative Braking, Energy Management, Thermal Management, Charging Solutions |
| Companies Covered | LG Energy Solution, Contemporary Amperex Technology Co. Limited, BYD Company Limited, Panasonic Corporation, Samsung SDI, SK Innovation, GS Yuasa Corporation, AESC, Primearth EV Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Electric Vehicle Battery Market Trends and Innovations
Active materials and cell formats are diverging faster than pack architectures can standardize, forcing suppliers to place parallel bets on cylindrical, prismatic, and pouch formats while regulatory timelines compress.
Solid-state electrolyte technology is converging with conventional lithium-ion manufacturing lines as OEM validation programs accelerate. Automotive engineering teams at premium passenger car divisions are pilot-testing solid-state prototypes for enhanced safety margins. This convergence is compressing the timeline for next-generation energy density thresholds previously considered decade-away milestones.
China's MIIT dual carbon goals are mandating carbon intensity disclosures across battery supply chains. Domestic cell manufacturers must now certify cradle-to-gate emissions for export qualification. European-bound hybrid platforms face the steepest compliance burden as the EU Green Deal's embodied carbon rules phase in.
Fleet procurement teams are consolidating supplier relationships around vertically integrated cell-to-pack providers. Commercial truck operators in North America now demand decade-long service agreements bundling hardware, thermal management, and residual value guarantees. This consolidation is most visible in California's drayage and last-mile logistics corridors where CARB mandates accelerate fleet turnover.
Hybrid Electric Vehicle Battery Market Segmentation
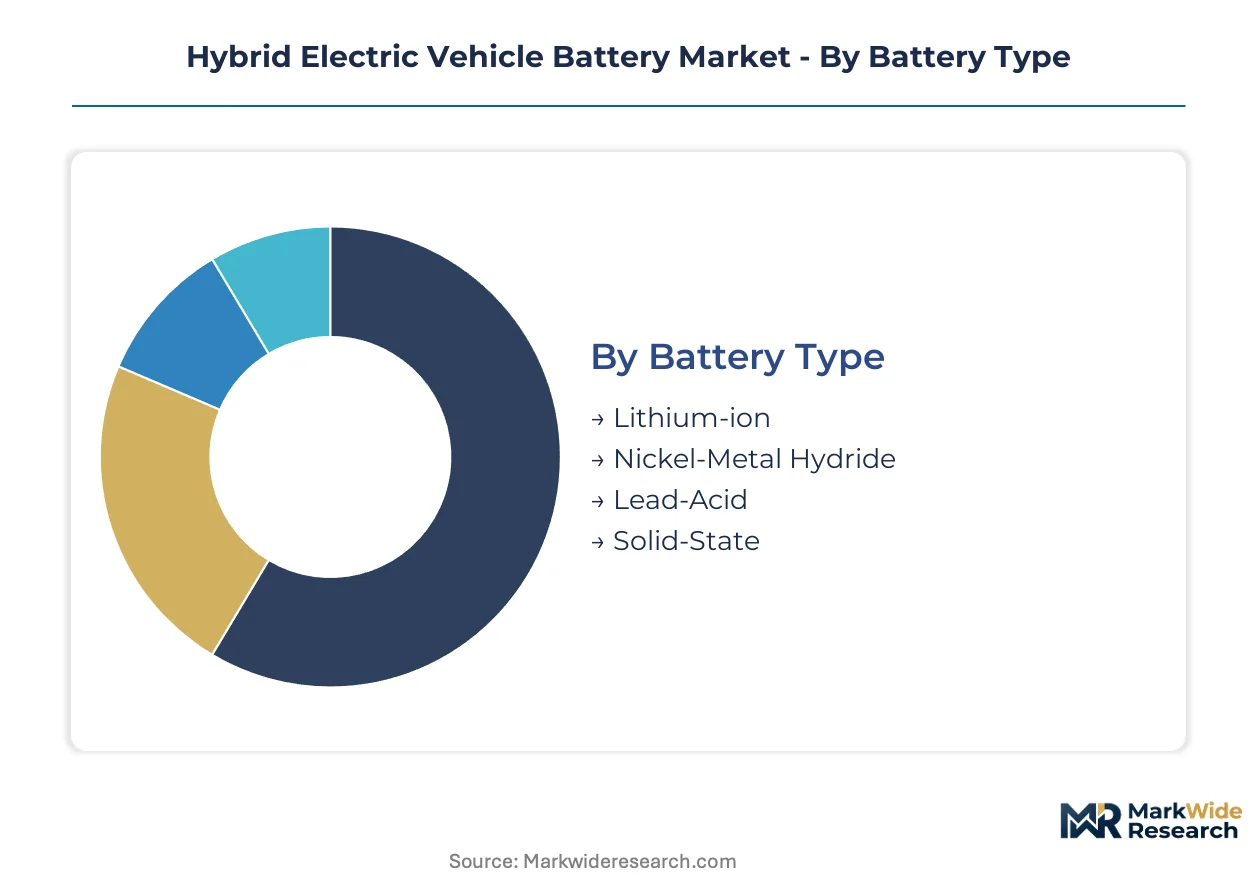
Segmentation in the hybrid electric vehicle battery market reveals how capital allocation, chemistry selection, and end-use requirements fragment procurement patterns. OEM platform commitments spanning decade-long cycles lock suppliers into divergent technology trajectories with limited switching flexibility.
Battery Type:
Capital intensity varies sharply across chemistries, with solid-state and advanced lithium-ion formats demanding multibillion-dollar fabrication facilities while nickel-metal hydride leverages depreciated legacy infrastructure.
- Lithium-ion:Prismatic and cylindrical cells utilizing nickel-cobalt-manganese or lithium iron phosphate cathodes dominate passenger car installations where gravimetric energy density above 250 Wh/kg reduces pack mass. CATL and LG Energy Solution anchor supply contracts with premium OEM programs in Germany and South Korea as energy density thresholds harden competitive requirements.
- Nickel-Metal Hydride:Cylindrical 1.2V modules with rare-earth lanthanum-based cathodes retain structural positions in commercial trucks and public transport where cycle life exceeding 2,000 deep discharges outweighs mass penalties. Toyota's supplier corridors in Aichi Prefecture concentrate pack assembly capacity for hybrid bus platforms serving Japanese municipal operators.
- Lead-Acid:Absorbent glass mat variants provide 12V auxiliary power for engine start-stop systems and low-voltage electrical architectures in cost-sensitive vehicle segments.
- Solid-State:Sulfide and oxide electrolyte prototypes undergoing OEM validation target enhanced safety margins and extended temperature windows for next-generation hybrid architectures.
Lithium-ion absorbs the bulk of installed capacity; solid-state is expanding most quickly through accelerated OEM validation timelines.
Application:
Volume concentration follows duty cycle intensity, with high-mileage commercial segments amortizing pack costs faster than intermittent-use passenger applications.
- Passenger Cars:Compact to full-size sedans and SUVs utilize 200-400V packs enabling 2-5 km pure electric range for urban stop-start operation. European premium OEMs in Stuttgart and Munich specify liquid-cooled lithium-ion architectures meeting EU Green Deal thermal efficiency mandates.
- Commercial Trucks:Class 4-8 delivery and drayage vehicles deploy 300-600V systems with sustained discharge capability for highway gradeability. California fleet operators under CARB mandates consolidate procurement around decade-long service agreements bundling hardware and thermal management.
- Public Transport:Transit buses and commuter coaches prioritize cycle life durability over energy density, favoring nickel-metal hydride for predictable route duty cycles.
- Motorcycles:Two-wheeler hybrid systems utilize compact 48V architectures for emerging urban mobility platforms in Indian and Southeast Asian markets.
Commercial trucks absorb the bulk of installed capacity; passenger cars are climbing the fastest as OEMs electrify light-duty portfolios under tightening EPA standards.
End User:
Procurement sophistication diverges between vertically integrated OEMs with captive cell supply and fragmented aftermarket channels managing residual value risk.
- OEMs:Toyota, Honda, and Hyundai maintain in-house pack assembly with direct cell supply agreements spanning 5-10 year horizons. Japanese METI supply chain initiatives subsidize domestic manufacturing scale for national champion producers.
- Fleet Operators:Logistics companies and municipal transit authorities negotiate performance-based contracts with guaranteed residual value and end-of-life recycling provisions. North American drayage operators in Long Beach and Newark corridors consolidate supplier relationships around vertically integrated providers.
- Private Consumers:Retail replacement demand concentrates in aging hybrid vehicle populations requiring dealer-serviced pack exchanges.
- Aftermarket Providers:Independent remanufacturers source second-life cells from warranty returns for cost-sensitive replacement applications.
OEMs absorb the bulk of installed capacity; fleet operators are gaining share fastest as TCO modeling favors electrified powertrains in high-utilization segments.
Technology:
System integration complexity concentrates value capture in thermal management and energy control software rather than cell commodity supply.
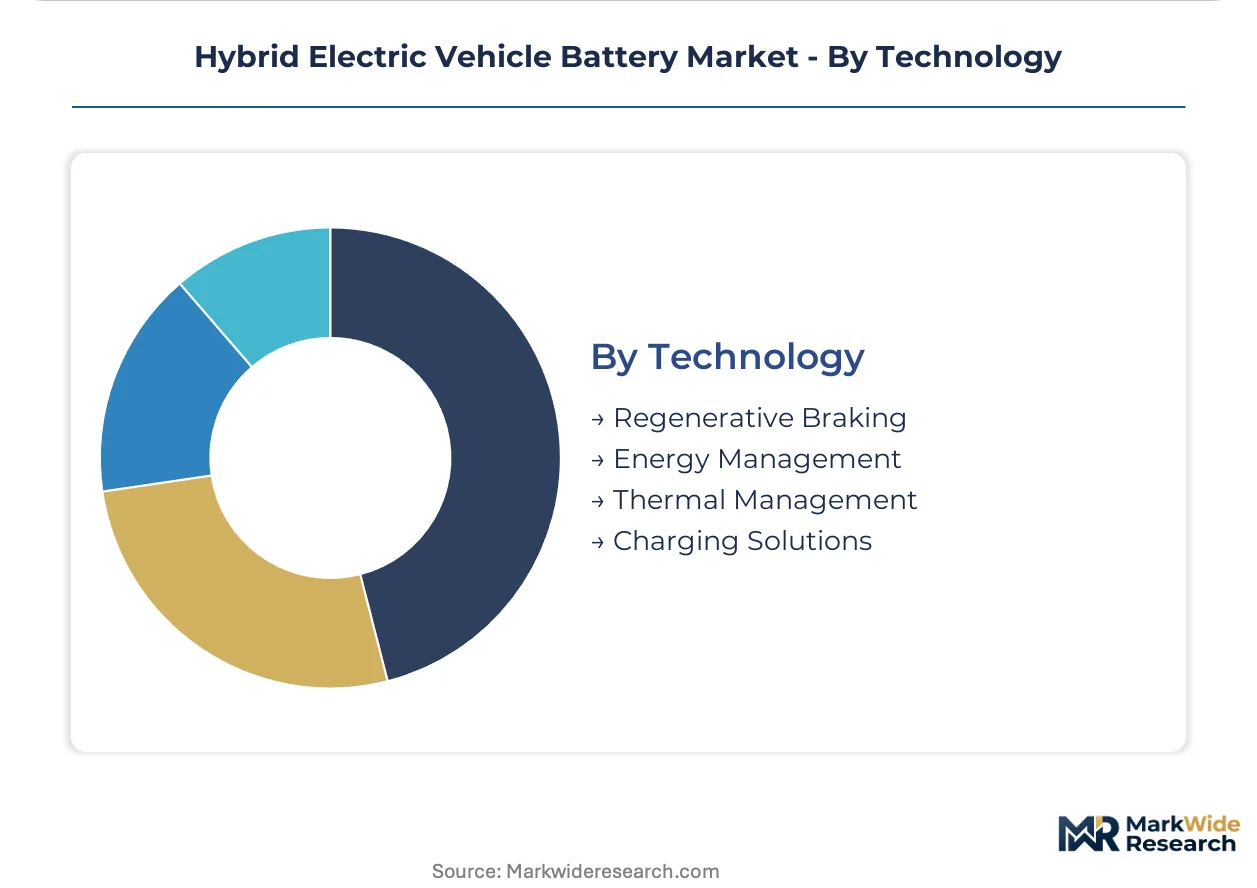
- Regenerative Braking:Kinetic energy recovery systems utilizing permanent magnet synchronous motors and bidirectional inverters capture 10-30% of braking energy for battery replenishment.
- Energy Management:Predictive control algorithms optimizing engine-battery power split across drive cycles differentiate OEM hybrid system efficiency.
- Thermal Management:Liquid cooling circuits and refrigerant-based battery chillers maintain cell temperatures within 15-35°C operating windows under sustained loads. EU F-Gas Regulation specifications constrain refrigerant selection for European-bound platforms.
- Charging Solutions:Onboard AC chargers and conductive charging interfaces support plug-in hybrid variants with extended electric range capability.
Thermal management absorbs the bulk of installed capacity; energy management is expanding most quickly as software-defined efficiency gains harden competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aichi Prefecture's Toyota supplier corridor concentrates nickel-metal hydride pack assembly for hybrid bus platforms serving Japanese municipal transit authorities.
United States
California fleet operators under CARB mandates consolidate procurement around decade-long service agreements bundling hardware and thermal management for drayage and last-mile logistics. The EPA's tightened corporate average fuel economy standards accelerate hybrid powertrain deployment across light-duty truck portfolios. Long Beach and Newark corridors anchor North American demand concentration for commercial vehicle electrification.
China
Domestic cell manufacturers face MIIT mandates requiring cradle-to-gate carbon intensity disclosures for export qualification under dual carbon goals. Prismatic lithium iron phosphate production scales for cost-sensitive commercial truck applications with sustained duty cycle requirements. Yangtze River Delta industrial clusters house the majority of CATL's manufacturing footprint for hybrid battery supply.
Germany
Premium OEMs in Stuttgart and Munich specify liquid-cooled lithium-ion architectures meeting EU Green Deal thermal efficiency mandates for European-bound hybrid platforms. The F-Gas Regulation constrains refrigerant selection for battery thermal management systems. Bavarian engineering centers pilot solid-state prototypes for next-generation energy density thresholds.
Japan
METI battery supply chain initiatives direct national subsidy flows toward domestic cell manufacturing scale for national champion producers. Toyota and Honda maintain dense supplier networks for nickel-metal hydride and lithium-ion pack assembly in Aichi and Saitama prefectures. Kanto region industrial corridors concentrate hybrid component production for domestic and export markets.
South Korea
The K Battery strategy channels government support toward domestic cell manufacturing scale for cylindrical and prismatic formats. Seoul-based producers leverage cylindrical cell expertise to anchor supply contracts with premium passenger car programs. Gyeonggi Province fabrication facilities serve as primary export hubs for hybrid battery modules.
Hybrid Electric Vehicle Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry specialization and thermal management integration depth. The supplier base fragments along parallel lithium-ion and nickel-metal hydride chemistry pipelines with limited cross-over capability. Three archetypes dominate: vertically integrated cell-to-pack providers, chemistry-specialist fabricators, and thermal management system integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs lock in decade-long platform commitments.
Within the cell-to-pack tier, LG Energy Solution and Contemporary Amperex Technology Co. Limited exemplify divergent format specialization strategies, with the former representing cylindrical expertise and the latter anchoring prismatic production scale. Samsung SDI occupies a position within the solid-state R&D pipeline archetype, reflecting next-generation chemistry positioning. These three entities collectively illustrate how geographic origin and corporate structure map to divergent technology bets across the hybrid battery value chain.
| Leading Market Players |
|---|
| LG Energy Solution |
| Contemporary Amperex Technology Co. Limited |
| BYD Company Limited |
| Panasonic Corporation |
| Samsung SDI |
| SK Innovation |
| GS Yuasa Corporation |
| AESC |
| Primearth EV Energy |
| Others |
Pricing and Supply Chain Analysis
Electrochemical engineering talent concentration in South Korea's Gyeonggi Province and Japan's Kanto region widens pricing-tier spreads between premium solid-state R&D pipelines and commodity nickel-metal hydride pack assembly, as labor-cost differentials compound chemistry-specific capital intensity.
Pricing Analysis
Cycle-life guarantees tied to fleet uptime metrics anchor value-based pricing for commercial truck applications. Three-tier pricing structure across premium liquid-cooled lithium-ion, standard air-cooled prismatic, and economy nickel-metal hydride modules differentiates on thermal management sophistication and UN 38.3 certification tier. Cost compression in the economy tier is intensifying because depreciated Japanese manufacturing infrastructure amortizes fixed costs across legacy hybrid platforms. Fleet operators with high daily mileage exhibit lowest price sensitivity; aftermarket remanufacturers serving aging vehicle populations exhibit highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from Toyota, Honda, and Hyundai captive pack assembly operations. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material processing drawing from Indonesian nickel and Chilean lithium carbonate feedstocks. Single-source vulnerability permeates Toyota's Aichi Prefecture supplier corridor for nickel-metal hydride cylindrical cells. Distribution runs through long-term offtake agreements bundling hardware, thermal management, and residual value guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase as solid-state electrolyte architectures displace conventional lithium-ion liquid electrolyte systems in OEM validation pipelines.
For Market Incumbents: Anticipate solid-state chemistry convergence by securing sulfide electrolyte formulation partnerships ahead of prototype-to-production timelines. Lock in decade-long platform commitments with North American fleet operators under CARB mandates to defend against emerging Chinese prismatic cell exporters. Prioritize thermal management software integration as the primary margin preservation lever.
For New Entrants and Emerging Players: Fleet operator procurement teams represent the most penetrable channel partner type for hybrid battery newcomers lacking OEM heritage. Target California drayage and last-mile logistics corridors where CARB compliance deadlines consolidate supplier relationships around vertically integrated providers. Lead with performance-based service agreements bundling hardware uptime guarantees and end-of-life recycling provisions.
For Investors and Strategic Acquirers: Re-rating potential sits with solid-state R&D specialists given accelerated OEM validation timelines compressing next-generation energy density thresholds. Long-term viability favors entities with captive cathode active material processing and thermal management software stacks. Monitor EPA tailpipe standard calibration announcements as the critical inflection signal for hybrid powertrain deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Partnership | OEM validation programs with BMW and Toyota accelerate sulfide electrolyte commercialization timelines. |
| Backward Integration into Cathode Materials | Indonesian nickel processing joint ventures reduce exposure to London Metal Exchange price volatility. |
| Thermal Management Software Acquisition | Predictive control algorithm specialists differentiate energy management efficiency in Stuttgart premium platforms. |
| Fleet Service Agreement Expansion | Decade-long California drayage contracts bundle hardware, cooling, and residual value guarantees. |
| Prismatic Cell Capacity Buildout | Yangtze River Delta fabrication facilities serve cost-sensitive commercial truck applications under MIIT mandates. |
Research Methodology
Independent corroboration across OEM platform engineering directors, fleet procurement managers, and cell manufacturer R&D leads underwrites the qualitative findings. Secondary validation draws from EPA regulatory filings, MIIT dual carbon disclosure databases, EU Green Deal technical specifications, and vehicle production registration data. Bottom-up cell shipment tallies triangulate against top-down OEM powertrain deployment forecasts across the analysis window.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across battery type, application, and end-user segmentation. The analytical framework models vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions throughout the forecast period. CAGRs derive from logistic diffusion curves fitted to OEM platform commitment announcements and fleet operator procurement timelines, with lithium carbonate spot price trajectories and EPA regulatory stringency indices as key exogenous inputs.
Caveats apply where lithium carbonate price volatility, EPA standard calibration shifts, or solid-state prototype delays could materially shift the outlook. Forecasts reflect assumptions regarding OEM platform commitment durability and fleet operator TCO model stability. Periodic stress-testing of base assumptions against MIIT policy announcements and EU F-Gas Regulation amendments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market