
 Italy Automotive Adaptive Lighting System Market | 2026-2036
Italy Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Adaptive Lighting System Market Foresight
Electric vehicle fleet operators is collapsing as the fastest-growing buyer archetype for adaptive lighting systems in Italy, while traditional mass-market passenger vehicle procurement softens. HELLA KGaA Hueck & Co leverages its matrix lighting engineering base in Lippstadt to supply Italian premium OEM programs. Valeo Group sustains competitive pressure through its integrated sensor-lighting platforms developed for European adaptive driving beam mandates. Magneti Marelli SpA anchors domestic supply chain control through its historic lighting manufacturing presence across Emilia-Romagna.
Automotive adaptive lighting systems comprise electronically controlled headlamp and taillamp assemblies that modulate beam patterns, intensity, and direction in response to vehicle speed, steering angle, ambient conditions, and detected traffic participants, typically operating across 12V or 48V vehicle electrical architectures with controller area network integration. LED technology segments now dominate Italian OEM fitment due to thermal efficiency and pixel-level controllability enabling compliance with stringent glare-limitation protocols. Matrix lighting technology leads technology segmentation by installed value, while laser lighting segments represent the fastest-growing structural category as Italian luxury vehicle platforms adopt extended-range high-beam functionality. OEM installation channels capture the preponderance of value flow, though aftermarket retrofit solutions for aging premium fleets are expanding in Milan and Rome metropolitan service networks.
Italy's automotive lighting market operates under EU General Safety Regulation requirements enforced by the Ministry of Infrastructure and Transport, with CE marking and ECE R48/R123 type approvals governing photometric performance and adaptive function certification. The EU AI Act and forthcoming Euro 7 emission frameworks are indirectly shaping lighting system design by accelerating sensor fusion demands that adaptive headlamps must support. Stakeholders must monitor how Italy's national type-approval authority interprets evolving United Nations Economic Commission for Europe amendments governing adaptive driving beam activation thresholds and pedestrian detection responsiveness.
Market Dynamics
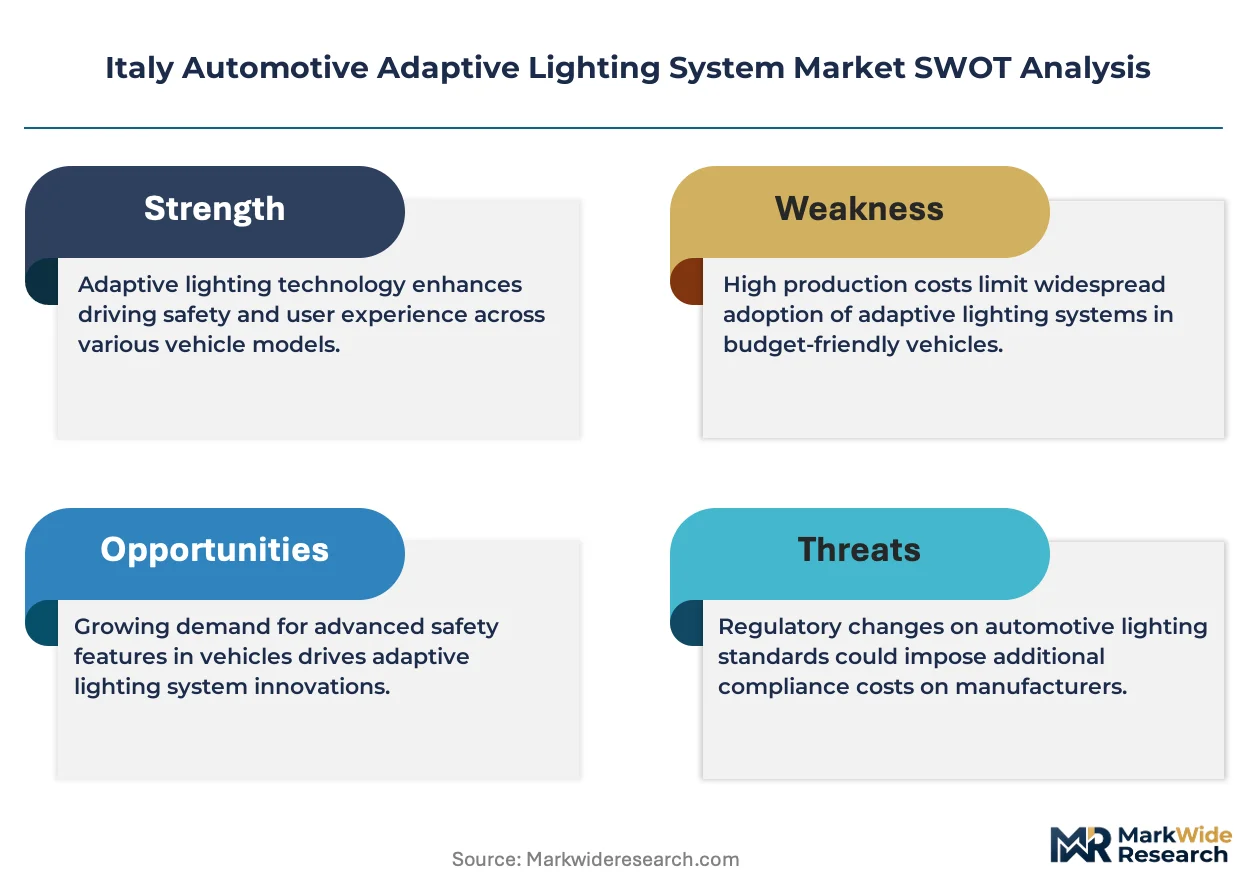
Matrix LED pixel density requirements under EU General Safety Regulation are compressing development cycles for Italian tier-1 suppliers, forcing simultaneous hardware miniaturization and software validation acceleration.
Growth Catalysts
- EU General Safety Regulation:Mandates for adaptive driving beam compatibility are pulling forward replacement demand across premium vehicle platforms assembled in Turin and Milan.
- Electric vehicle fleet operators:Commercial electrification programs in northern Italy are specifying adaptive lighting as standard fitment for nighttime logistics safety.
- Laser lighting modules:Extended-range high-beam functionality is penetrating luxury segments, creating upstream demand for thermal management components from Emilia-Romagna suppliers.
Market Restraints
- Controller semiconductor concentration:Dependency on East Asian foundry output for LED driver ICs exposes Italian assemblers to allocation volatility.
- Photometric testing infrastructure:Limited ECE R48 certification capacity at national type-approval bodies extends program validation timelines.
- Halogen aftermarket substitution:Low-cost retrofit kits for aging vehicle pools divert maintenance spending from OEM-specified adaptive systems.
Strategic Opportunities
- Sensor-lighting convergence:Integration of lidar-transparent headlamp covers with adaptive beam controllers opens ADAS-tier supplier partnerships.
- Central-southern service networks:Rome and Naples metropolitan aftermarket channels remain underdeveloped for premium retrofit solutions.
- Euro 7 pre-compliance positioning:Early alignment with forthcoming emission-linked safety mandates secures platform engineering slots for 2028+ vehicle generations.
Industry Challenges
- Embedded software validation:Functional safety certification to ISO 26262 ASIL-B requires scarce automotive firmware engineering talent in Lombardy.
- Legacy 12V architecture integration:Hybrid electrical systems complicate controller area network timing for adaptive function synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Adaptive Lighting System Market |
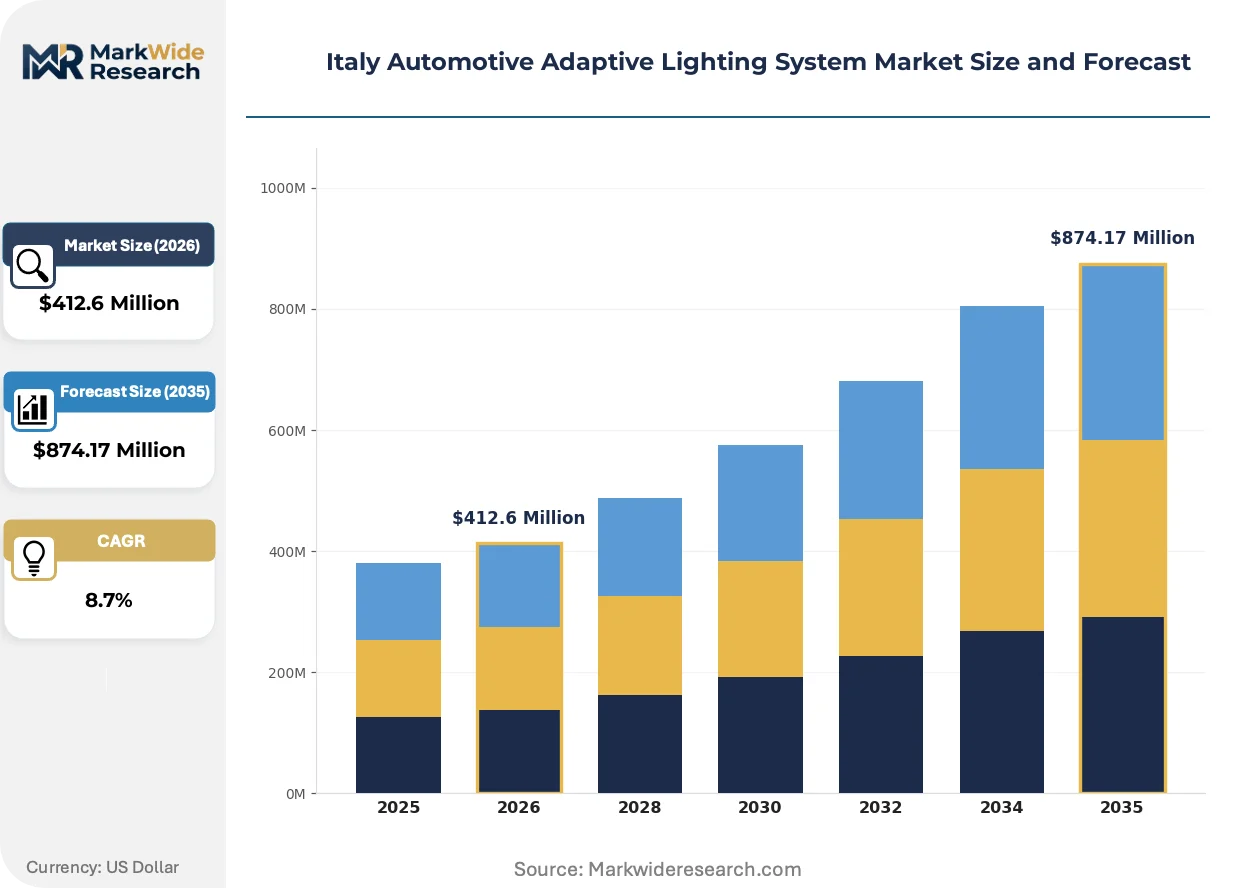
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, LED, Xenon, OLED Technology: Matrix Lighting, Laser Lighting, Dynamic Bending, Light Spot Control End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Installation: Aftermarket, OEM, Integrated Systems, Retrofit Solutions |
| Companies Covered | HELLA KGaA Hueck & Co, Valeo Group, Magneti Marelli SpA, Koito Manufacturing Co Ltd, Osram, Stanley Electric Co Ltd, Hyundai Mobis, Koninklijke Philips N.V., Texas Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Adaptive Lighting System Market Shifts & Advancements
Digital light processing is dissolving the boundary between illumination and communication functions, with headlamp assemblies assuming active roles in pedestrian warning and vehicle-to-infrastructure signaling.
Micro-LED matrix arrays are fragmenting the dominance of conventional LED chip-on-board architectures. Italian premium OEMs are specifying 25,000+ pixel densities for glare-free adaptive driving beam execution. Tier-1 engineering centers in Bologna are compressing optical module footprints by 40% while maintaining ECE R123 compliance margins.
EU AI Act classification rules for safety-critical automotive systems are forcing lighting suppliers to document algorithmic decision pathways for beam pattern selection. Italian type-approval authorities are interpreting these requirements through ECE amendment frameworks, extending homologation timelines for machine-learning-enabled adaptive functions. Northern European OEMs are accelerating compliance investments ahead of Italian enforcement schedules.
Commercial fleet procurement is consolidating specification authority at the holding-company level, displacing individual operator discretion. Long-term leasing structures in Milan logistics corridors are bundling adaptive lighting into total-cost-of-ownership calculations. Tier-1 suppliers are reconfiguring sales organizations to address centralized technical committees rather than regional dealer networks.
Italy Automotive Adaptive Lighting System Market Segmentation
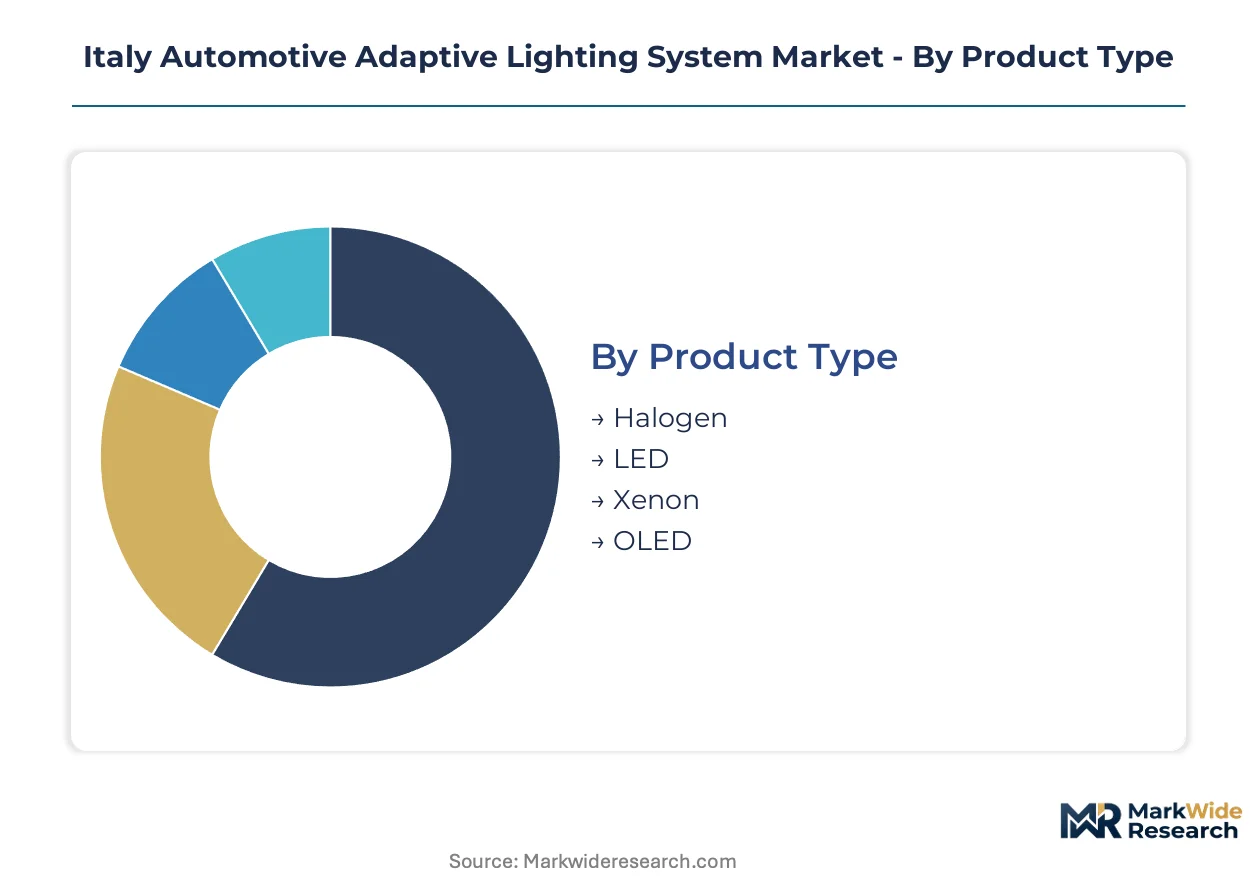
Segmentation in the Italy Automotive Adaptive Lighting System Market reveals how procurement authority concentrates across electrical architectures, technology readiness tiers, and fleet ownership structures. Manufacturers must align module specifications with distinct validation requirements and margin profiles that vary sharply between OEM assembly contracts and aftermarket retrofit channels.
Product Type:
Margin pools in this category concentrate where thermal management complexity intersects with pixel-level controllability, rewarding suppliers who master semiconductor-thermal integration.
- LED:These assemblies deploy chip-on-board architectures with 12V or 48V electrical integration, enabling pixel-level beam modulation for ECE R123 compliance. Northern Italian OEM engineering centers in Turin and Milan specify LED modules as baseline fitment for premium platforms, driven by EU General Safety Regulation mandates for adaptive driving beam compatibility.
- Halogen:Legacy tungsten-halogen reflector assemblies persist in cost-sensitive fleet retrofit channels and aging vehicle pools. Demand concentrates in central-southern Italy aftermarket service networks where maintenance spending prioritizes functional replacement over adaptive functionality upgrades.
- Xenon:High-intensity discharge systems with arc-tube ignition and mechanical beam leveling retain niche presence in older premium vehicle segments.
- OLED:Organic electroluminescent panels enable surface-emitting taillamp designs with segmented animation capability for vehicle-to-pedestrian communication.
The dominant share belongs to LED, while OLED is closing the gap fastest as Italian luxury platforms adopt signature lighting differentiation.
Technology:
Volume concentration tracks directly with EU regulatory enforcement timelines, pulling forward procurement of architectures that satisfy adaptive driving beam mandates.
- Matrix Lighting:Micro-LED pixel arrays with 25,000+ individually addressable elements execute glare-free high-beam operation through real-time masking of detected traffic participants. Bologna-based tier-1 engineering centers are compressing optical module footprints by 40% while maintaining ECE R123 homologation margins, responding to Emilia-Romagna OEM platform requirements.
- Laser Lighting:Coherent diode-pumped sources extend high-beam range beyond 600 meters through phosphor-converted white light emission. Luxury vehicle programs specify laser modules for nighttime Autobahn performance, creating upstream demand for thermal management substrates from northern Italian suppliers.
- Dynamic Bending:Swiveling projector modules linked to steering angle sensors adjust beam direction through mechanical actuation.
- Light Spot Control:Selective illumination of detected pedestrians or road hazards through targeted spotlight projection.
Matrix Lighting commands the largest installed value position, though Laser Lighting is expanding most quickly as extended-range functionality penetrates flagship segments.
End User:
Specification authority is consolidating at fleet holding-company level, displacing individual operator discretion and reshaping procurement channel structures.
- Electric Vehicles:Commercial electrification programs across Milan logistics corridors specify adaptive lighting as standard fitment for nighttime fleet safety compliance. Long-term leasing structures bundle matrix LED modules into total-cost-of-ownership calculations, centralizing technical committee authority over regional dealer networks.
- Luxury Vehicles:Flagship platforms from Turin and Modena assembly plants integrate laser-matrix hybrid architectures with 48V electrical systems. Emilia-Romagna OEMs specify 25,000+ pixel densities for signature lighting differentiation, driving tier-1 supplier validation investments.
- Passenger Vehicles:Mass-market platforms face procurement softening as adaptive functionality remains optional equipment.
- Commercial Vehicles:Heavy-duty logistics operators in northern Italy specify dynamic bending systems for motorway corridor safety.
Electric Vehicles hold the steepest expansion trajectory, while Luxury Vehicles retain the highest per-unit value capture.
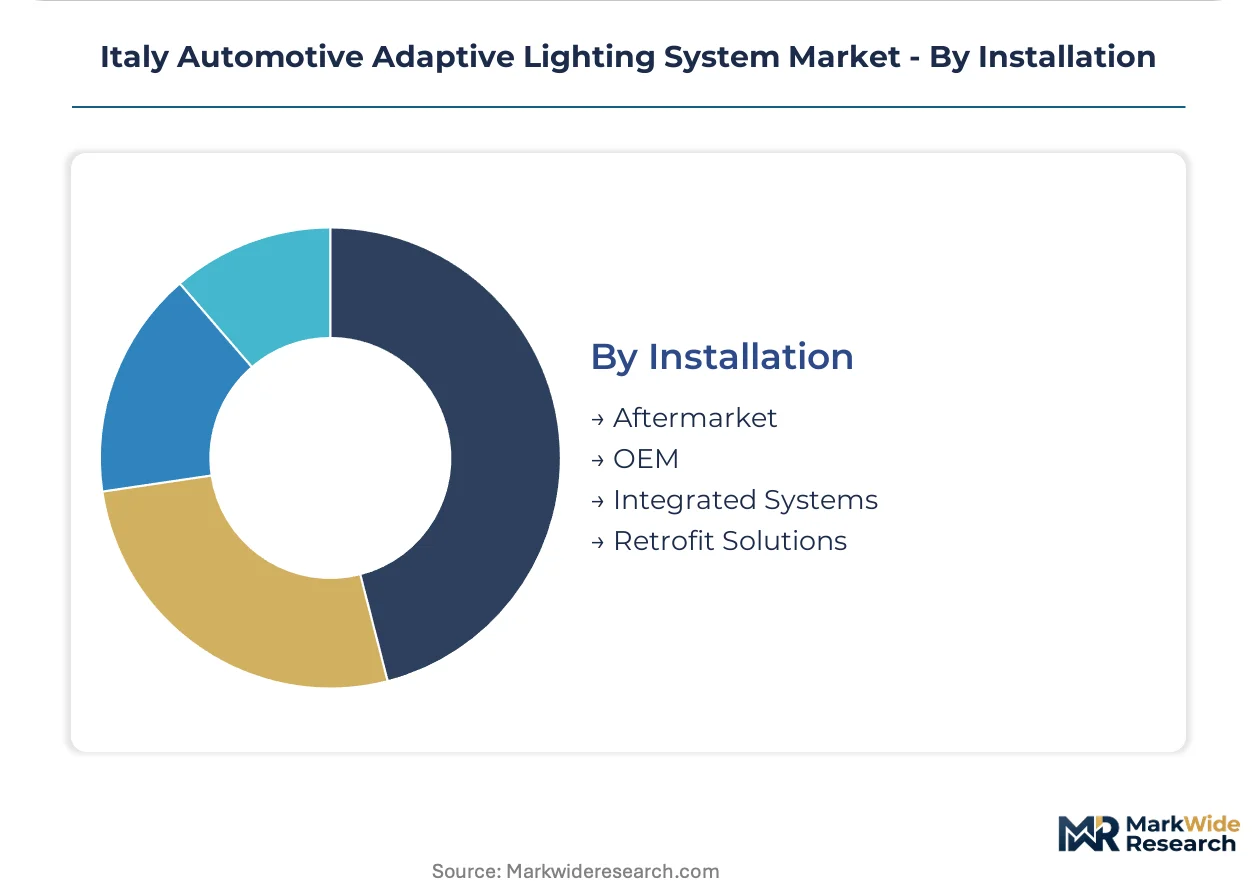
Installation:
Channel margins diverge sharply between assembly-line integration with full CAN bus synchronization and aftermarket retrofit with legacy electrical compatibility constraints.
- OEM:Factory installation captures preponderant value flow through synchronized controller area network timing and ISO 26262 ASIL-B functional safety certification. Turin and Milan OEM assembly plants mandate matrix lighting compatibility for premium platform launches, embedding adaptive controllers within 48V electrical architectures.
- Aftermarket:Retrofit solutions for aging premium fleets expand through Milan and Rome metropolitan service networks, though halogen substitution kits divert maintenance spending from OEM-specified systems. Central-southern channels remain underdeveloped for premium adaptive retrofits.
- Integrated Systems:Pre-wired lighting-sensor fusion modules for ADAS-tier supplier partnerships.
- Retrofit Solutions:Standalone adaptive controller units for legacy 12V vehicle pools.
OEM installation dominates absolute value flow, while Aftermarket is gaining share fastest as fleet renewal cycles extend and premium vehicle pools age.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle fleet operators and premium OEM engineering centers concentrate procurement authority across northern Italy's industrial corridor. Specification decisions centralize at holding-company level for commercial electrification programs. Regional variance tracks electrification infrastructure density and proximity to tier-1 supplier engineering bases.
Lombardy
Milan logistics corridors drive commercial fleet procurement for nighttime safety compliance. Long-term leasing structures bundle matrix LED modules into total-cost-of-ownership calculations. The Ministry of Infrastructure and Transport enforces EU General Safety Regulation type-approvals through regional certification offices.
Piedmont
Turin-based OEM assembly plants mandate adaptive driving beam compatibility for premium platform launches. Engineering centers specify 48V electrical architectures with integrated controller area network timing. The concentration of R&D facilities pulls validation investment toward pixel-level beam modulation technologies.
Emilia-Romagna
Modena and Bologna anchor luxury vehicle platform engineering with laser-matrix hybrid specifications. Tier-1 suppliers compress optical module footprints by 40% while maintaining ECE R123 homologation margins. Thermal management component demand concentrates among substrate fabricators across the regional supply base.
Lazio
Rome metropolitan aftermarket channels remain underdeveloped for premium retrofit solutions. Aging vehicle pools divert maintenance spending toward low-cost halogen substitution kits. Central-southern service networks lag northern corridors in adaptive lighting technical capacity.
Veneto
Commercial vehicle operators specify dynamic bending systems for motorway corridor safety across the alpine transit routes. Heavy-duty logistics procurement centralizes through Verona and Padua fleet management centers. Regional type-approval interpretation of United Nations Economic Commission for Europe amendments varies from northern enforcement schedules.
Italy Automotive Adaptive Lighting System Market Competitive Landscape
Player mix skews toward integrated tier-1 automotive suppliers with captive lighting divisions and specialized optical component fabricators. Consolidation pressure concentrates among matrix LED engineering bases competing for 25,000+ pixel density programs. Two strategic archetypes dominate: European-headquartered full-system integrators with sensor-fusion capabilities, and Asia-Pacific component specialists supplying thermal management substrates. Competitive moves center on strategic partnerships for lidar-transparent headlamp cover integration and backward integration into LED driver semiconductor sourcing.
Within the European integrated tier, HELLA KGaA Hueck & Co and Valeo Group exemplify full-system engineering archetypes with matrix lighting development bases. Magneti Marelli SpA occupies a position as the domestic supply chain anchor with historic manufacturing presence across Emilia-Romagna. These three represent the concentration of procurement relationships with Turin and Milan OEM engineering centers.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co |
| Valeo Group |
| Magneti Marelli SpA |
| Koito Manufacturing Co Ltd |
| Osram |
| Stanley Electric Co Ltd |
| Hyundai Mobis |
| Koninklijke Philips N.V. |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
ECE R48 type-approval protocols gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified entrants while rewarding tier-1 incumbents with OEM assembly-line premiums. Matrix LED validation timelines extend program costs, yet laser-module thermal management complexity sustains value capture for Emilia-Romagna substrate specialists.
Pricing Analysis
Prior-generation halogen retrofit kits, current-generation matrix LED assemblies, and next-generation laser-matrix hybrids stratify across premium, standard, and economy tiers. Certification grade under ECE R123 and pixel density specifications drive price differentiation, with OEM channel buyers exhibiting lowest price sensitivity versus aftermarket fleet operators facing cost compression from leasing structure bundling. Pricing pressure stems from semiconductor allocation volatility in LED driver IC sourcing.
Supply Chain Analysis
Germany and China anchor LED driver semiconductor and optical module fabrication, while Japan feeds laser diode phosphor conversion technologies. Italian assemblers draw from East Asian foundry output for controller ICs, Emilia-Romagna thermal substrates, and Bavarian precision optics. Single-source vulnerability concentrates in 48V electrical architecture components. Distribution runs through OEM technical committees in Turin and Milan, with aftermarket channels fragmenting across regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet holding-company consolidation across northern Italy logistics corridors concentrates procurement authority, displacing fragmented dealer-network discretion and amplifying buyer leverage in contract negotiations.
For Market Incumbents: Shield matrix LED engineering investments through captive thermal management substrate sourcing from Emilia-Romagna fabricators. Deepen backward integration into LED driver semiconductor procurement to mitigate East Asian foundry allocation volatility. Prioritize ISO 26262 ASIL-B certification maintenance as emerging entrants target validation shortcuts. For New Entrants and Emerging Players: Differentiate on lidar-transparent headlamp cover integration for ADAS-tier supplier partnerships. Target Rome and Naples metropolitan aftermarket channels where premium retrofit penetration lags northern corridors. Pursue centralized fleet technical committees in Milan logistics corridors with total-cost-of-ownership bundled offerings. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized automotive lighting divisions exhibiting stranded matrix LED engineering capacity. Long-term viability hinges on sensor-lighting convergence positioning rather than standalone illumination module production. Watch Euro 7 pre-compliance engineering slot allocations as inflection indicator for 2028+ platform pipeline depth.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Lighting Convergence Partnership | ADAS-tier supplier alliances in Bologna engineering centers accelerate lidar-transparent cover integration timelines. |
| Thermal Management Backward Integration | Emilia-Romagna substrate fabricators secure margin capture from laser module upstream demand concentration. |
| Central-Southern Aftermarket Expansion | Rome and Naples service network penetration addresses underdeveloped premium retrofit channel whitespace. |
| Euro 7 Pre-Compliance Positioning | Early alignment with emission-linked safety mandates secures Turin OEM platform engineering slots. |
| 48V Electrical Architecture Certification | ISO 26262 ASIL-B validation investments differentiate incumbent tier-1 suppliers from validation-shortcut entrants. |
Research Methodology
Desk research of ECE R48/R123 type-approval databases, vehicle production registries, and EU General Safety Regulation implementation guidance preceded structured interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributor operations heads, and fleet management technical committees. Secondary validation drew from Ministry of Infrastructure and Transport certification records, IHS Markit registration data, and Emilia-Romagna regional industrial surveys. Bottom-up module shipment analysis triangulated against top-down OEM platform content-per-vehicle estimates.
Variance decomposition across technology generation, vehicle propulsion architecture, OEM tier positioning, and regional production cluster underpinned analytical framework construction throughout the projection horizon. CAGRs derived from segment-level shipment trajectories weighted by average selling price evolution, with matrix LED pixel density penetration curves and laser module thermal management cost curves as automotive-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU General Safety Regulation enforcement continuity and semiconductor supply normalization; material deviation in regulatory amendment timelines or East Asian foundry capacity allocation would warrant model refresh. Recalibration cycles align with material shifts in ECE amendment interpretation and fleet electrification program acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global ESD Protection Devices Market
Others
Process Instrumentation Equipment Market
Others
US Quantum Computing Market
Others
Industrial Air Purifiers Market
Others
Construction Fabrics Market
Others
Smart Electric Curtain Market
Others
Internet Protocol Television (IPTV) Market
Others
Reduced-Risk Products (Rrps) Market
Others
Safety Instrumented System (SIS) Market
Others
US 3D Printing Construction Market
Others
Mobile Retina Services Market
Others
Surgical Simulation Market
Others
Asia-Pacific Intercom Devices Market
Others
Profilometer Market
Others
Global Application Testing Services Market
Others
Smart Home Platforms Market