
 Packaged Rice Market | 2026-2036
Packaged Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Rice Market Analytics
ISO 22000 certification is collapsing as a baseline entry barrier for new packaged rice suppliers, forcing smaller millers toward third-party audits or exit. KRBL Limited leverages its integrated Punjab-Haryana procurement network to sustain quality consistency across Basmati grades. Olam International Limited competes through African and Asian origin diversification, reducing single-crop dependency. Cargill, Incorporated dominates North American private-label channels with its Arkansas-Mississippi Delta milling infrastructure.
Packaged rice denotes milled, graded, and sealed rice products distributed in consumer or commercial formats, typically processed to moisture contents of 12-14 percent to prevent microbial degradation and extend shelf stability. Its primary purpose centers on food security, convenience, and standardization for household preparation and industrial food production. White rice occupies the largest volume share due to price accessibility and universal culinary integration, while Basmati rice commands premium positioning in Gulf Cooperation Council retail channels. Brown rice sustains faster growth in European and North American health-oriented segments, though from a smaller base. Pouch packaging is displacing traditional bulk bags in urban markets, driven by single-household consumption patterns and e-commerce logistics requirements.
The FDA enforces pesticide residue thresholds and allergen labeling for rice imports into the United States, directly shaping supplier compliance costs and origin selection. India's FSSAI mandates iron, folic acid, and vitamin B12 fortification in distributed packaged rice, creating reformulation obligations for exporters targeting government programs. The EU's EFSA evaluates arsenic limits in rice-based foods, influencing maximum permissible levels for European-bound shipments. Stakeholders must monitor evolving fortification mandates and residue protocols across destination markets to preserve access and avoid consignment rejections at port.
Market Dynamics
ISO 22000 certification is collapsing as a baseline entry barrier for new packaged rice suppliers, forcing smaller millers toward third-party audits or exit. This regulatory compression is reshaping competitive positioning across procurement networks and export channels.
Growth Catalysts
- FSSAI Fortification Mandates:India's iron, folic acid, and vitamin B12 requirements for distributed packaged rice create reformulation obligations that favor organized millers with laboratory infrastructure and quality assurance protocols.
- Processed Rice Diversification:Food manufacturers are expanding rice-based ingredient applications into convenience foods, ready-to-eat meals, and extruded snack formats, pulling volume through industrial procurement channels.
- Basmati Concentration in GCC:Saudi Arabia and the UAE are consolidating premium rice demand through centralized retail consolidation and hospitality sector procurement standardization.
Market Restraints
- Arsenic Threshold Friction:The EU's EFSA evaluations of arsenic limits in rice-based foods create maximum permissible level uncertainty that delays European-bound shipment clearances and raises testing costs.
- Punjab-Haryana Procurement Concentration:Quality Basmati sourcing depends on a narrow Indo-Gangetic belt where water stress and stubble burning regulations threaten yield consistency and price stability.
- Moisture Control Capital Intensity:Achieving 12-14 percent moisture content for shelf stability requires precision drying infrastructure that small millers cannot finance, ceding volume to integrated processors.
Strategic Opportunities
- Brown Rice Health Segmentation:European and North American retailers are carving dedicated shelf space for whole-grain varieties, rewarding suppliers with organic certification and glycemic index testing capabilities.
- Pouch Packaging E-commerce Integration:Single-household consumption patterns and last-mile logistics requirements are opening urban markets to flexible-format packaging that bulk bags cannot serve.
- African Origin Diversification:Sourcing from multiple Asian and African origins reduces single-crop dependency and hedges against monsoon variability in any one geography.
Industry Challenges
- Fortification Technical Integration:Blending iron, folic acid, and vitamin B12 without altering cooking properties or shelf life requires food science expertise scarce among traditional millers.
- Multi-Jurisdiction Compliance Synchronization:Simultaneously satisfying FDA pesticide residue thresholds, FSSAI fortification mandates, and EFSA arsenic limits demands dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Rice Market |
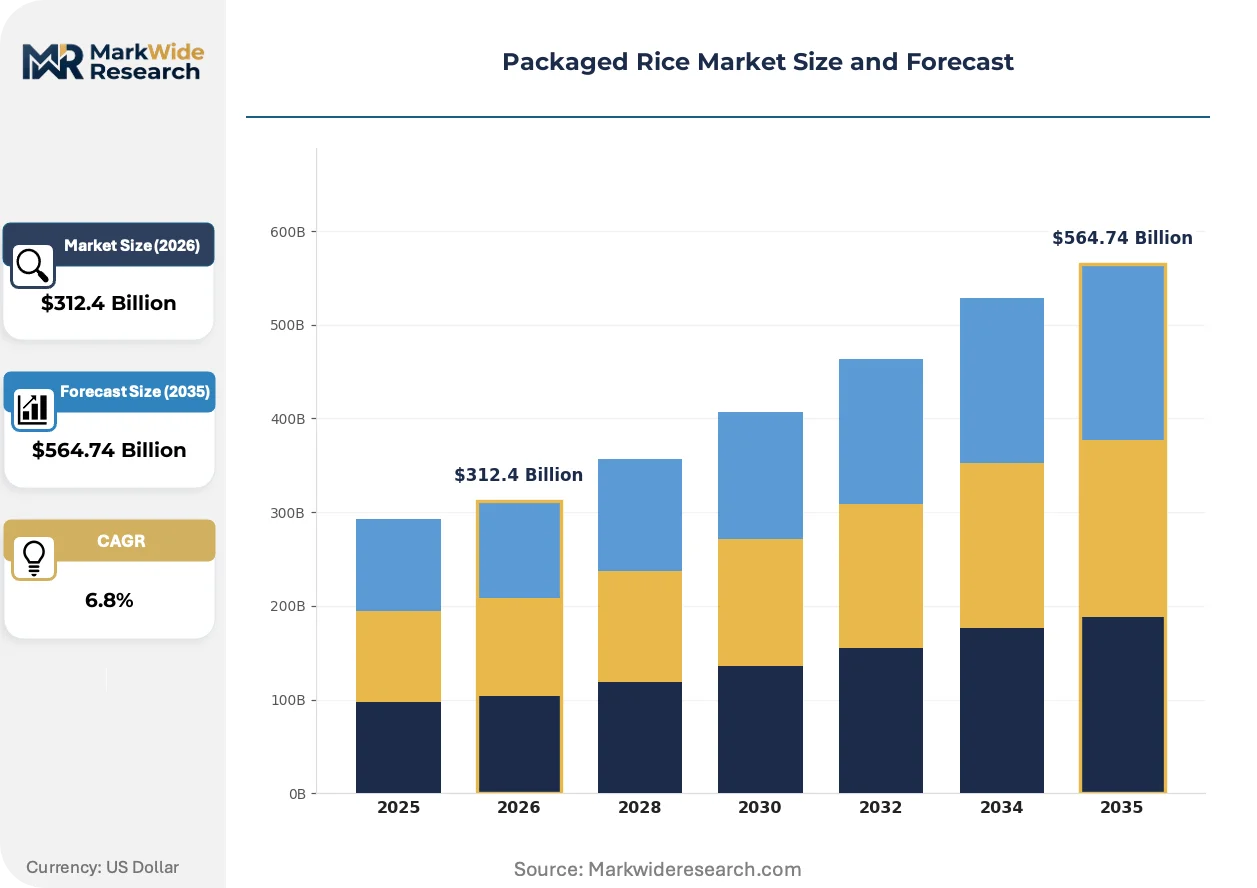
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Jasmine Rice, Basmati Rice Packaging Type: Bags, Boxes, Pouches, Tins Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale Distributors End User: Households, Restaurants, Cafeterias, Food Manufacturers |
| Companies Covered | Ebro Foods S.A., Charoen Pokphand Foods Public Company Limited, KRBL Limited, Ricegrowers Limited, Olam International Limited, LT Foods Limited, China National Cereals, Oils and Foodstuffs Corporation, Cargill, Incorporated, Riceland Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Rice Market Evolving Landscape
Processing technology and packaging formats are actively reshaping how rice moves from mill to consumer, with implications for shelf life, traceability, and channel access. These shifts favor capital-intensive operators with quality assurance infrastructure.
Precision moisture monitoring systems using near-infrared spectroscopy are decomposing traditional batch-drying methods that relied on manual sampling and fixed time cycles. Large integrated millers in Arkansas and the Mississippi Delta are adopting these sensors at line speed, enabling real-time moisture adjustment that reduces over-drying losses and energy consumption. The technology is compressing quality variation between production runs and tightening specification windows demanded by private-label retail contracts.
The EU Green Deal's Farm to Fork strategy is tightening residue monitoring and sustainability documentation requirements for agricultural imports into European markets. This policy framework is forcing exporters to implement blockchain-enabled traceability systems that track pesticide application, water usage, and carbon footprint at the farm level. Basmati suppliers targeting German and French retail channels are most affected, with several redirecting shipments toward Middle Eastern markets with less stringent documentation requirements.
Urban household downsizing is fragmenting bulk purchasing patterns that once dominated rice distribution in developing markets. Single-person and dual-income households in Indian and Southeast Asian cities are rejecting 25-kilogram sacks in favor of 1-5 kilogram pouches available through quick-commerce platforms. This channel rotation is visible most acutely in Mumbai, Bangalore, and Jakarta, where 10-minute delivery apps are capturing share from traditional kirana stores and mandi aggregators.
Packaged Rice Market Segmentation
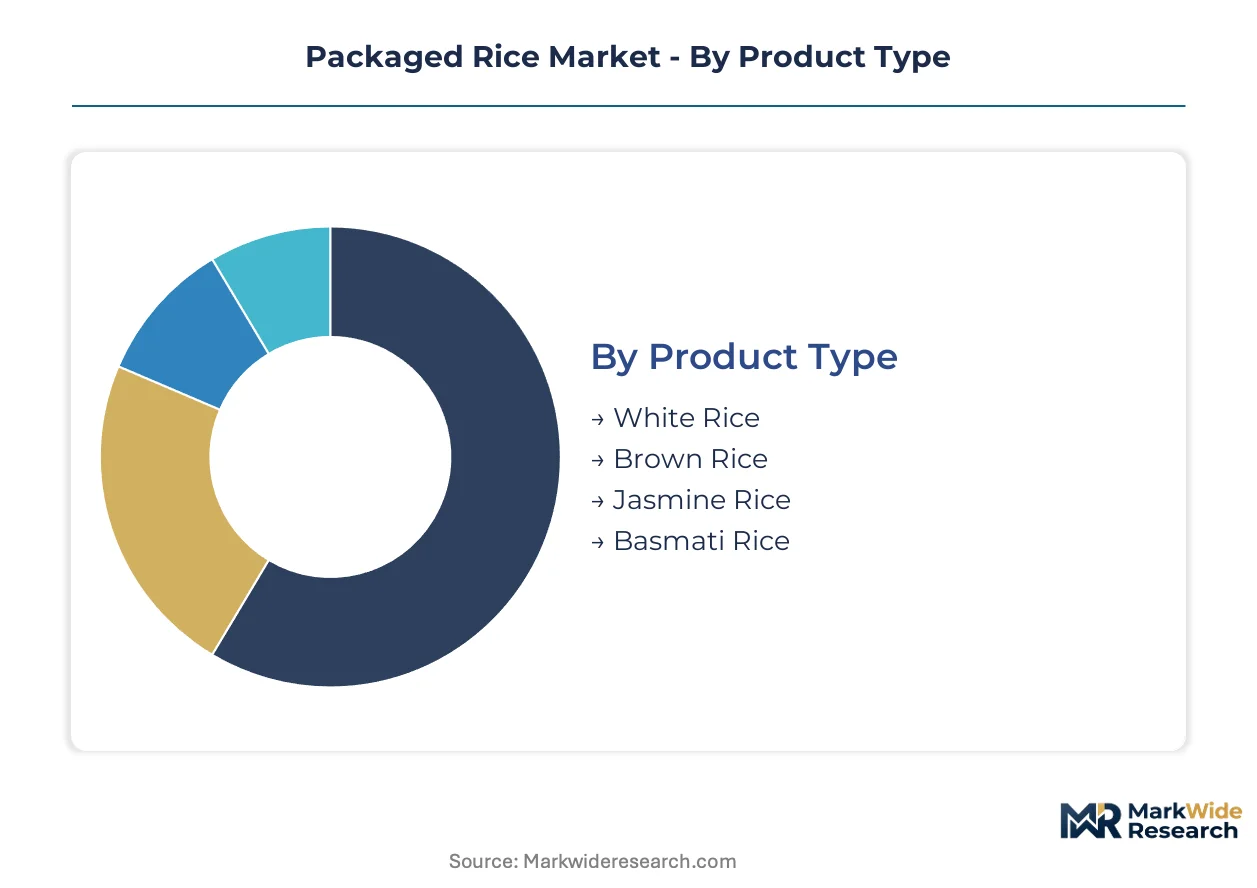
Segmentation in packaged rice determines procurement specifications, shelf-life engineering, and channel economics. Product type dictates moisture targets and fortification protocols. Packaging format shapes logistics costs and e-commerce compatibility. Distribution channel and end-user segmentation govern volume scale versus margin profiles.
Product Type:
White rice and Basmati dominate institutional procurement through food service distributors, while brown rice gains traction in premium retail channels. Jasmine rice concentrates in Southeast Asian export corridors and ethnic grocery networks.
- White Rice:Milled to remove bran and germ layers, achieving 12-14 percent moisture content for shelf stability. Demand concentrates in price-sensitive household segments across South Asian and African markets, constrained by razor-thin margins that favor high-volume millers with integrated drying infrastructure.
- Basmati Rice:Long-grain aromatic variety aged 6-12 months to develop characteristic fragrance and elongation properties. Saudi Arabia and UAE retail consolidation drives premium positioning, with FSSAI fortification mandates adding compliance costs for Indian exporters targeting government distribution programs.
- Brown Rice:Whole-grain format retaining bran layer with higher fiber content and shorter shelf life. European health-oriented retailers and North American organic channels represent the primary demand nodes.
- Jasmine Rice:Thai and Cambodian origin aromatic variety with sticky texture profile. Southeast Asian restaurants and diaspora communities in North America and Australia sustain import volumes.
White rice dominates installed base. Brown rice is where expansion concentrates.
Packaging Type:
Cost tiers separate bulk institutional formats from consumer-ready units. Capital intensity and barrier properties define competitive viability across each tier.
- Bags:Woven polypropylene or laminated paper constructions in 5-25 kilogram sizes. Wholesale distributors and traditional retail in South Asia and Africa represent the core channel, though urban shift toward smaller units is eroding volume share.
- Pouches:Multi-layer flexible films with moisture and oxygen barriers in 1-5 kilogram formats. Online retailers and quick-commerce platforms in Mumbai, Bangalore, and Jakarta drive steepest expansion trajectory as single-household consumption fragments bulk purchasing patterns.
- Boxes:Cardboard secondary packaging for gift and premium segments. Middle Eastern retail consolidation during festival periods sustains seasonal demand.
- Tins:Metal containers for ultra-premium and ceremonial gift markets. Limited to Basmati grades in GCC hospitality procurement.
Bags retain volume leadership. Pouches capture all incremental growth.
Distribution Channel:
Channel selection determines traceability requirements and payment terms. Modern trade imposes certification burdens that traditional wholesale avoids.
- Supermarkets:Organized retail with barcode traceability and ISO 22000 supplier qualification. Saudi Arabia and UAE retail consolidation favors centralized procurement with private-label penetration.
- Online Retailers:E-commerce platforms and quick-commerce apps requiring 1-5 kilogram pouch formats. Indian and Indonesian urban markets show fastest share gain as 10-minute delivery apps displace kirana stores.
- Convenience Stores:Small-format urban retail with limited SKU breadth. Emergency purchase occasions and transit-hub locations define the use case.
- Wholesale Distributors:Bulk aggregation for restaurants, cafeterias, and institutional buyers. Price transparency and credit terms dominate supplier selection.
Wholesale distributors move the most tonnage. Online retailers are climbing the fastest.
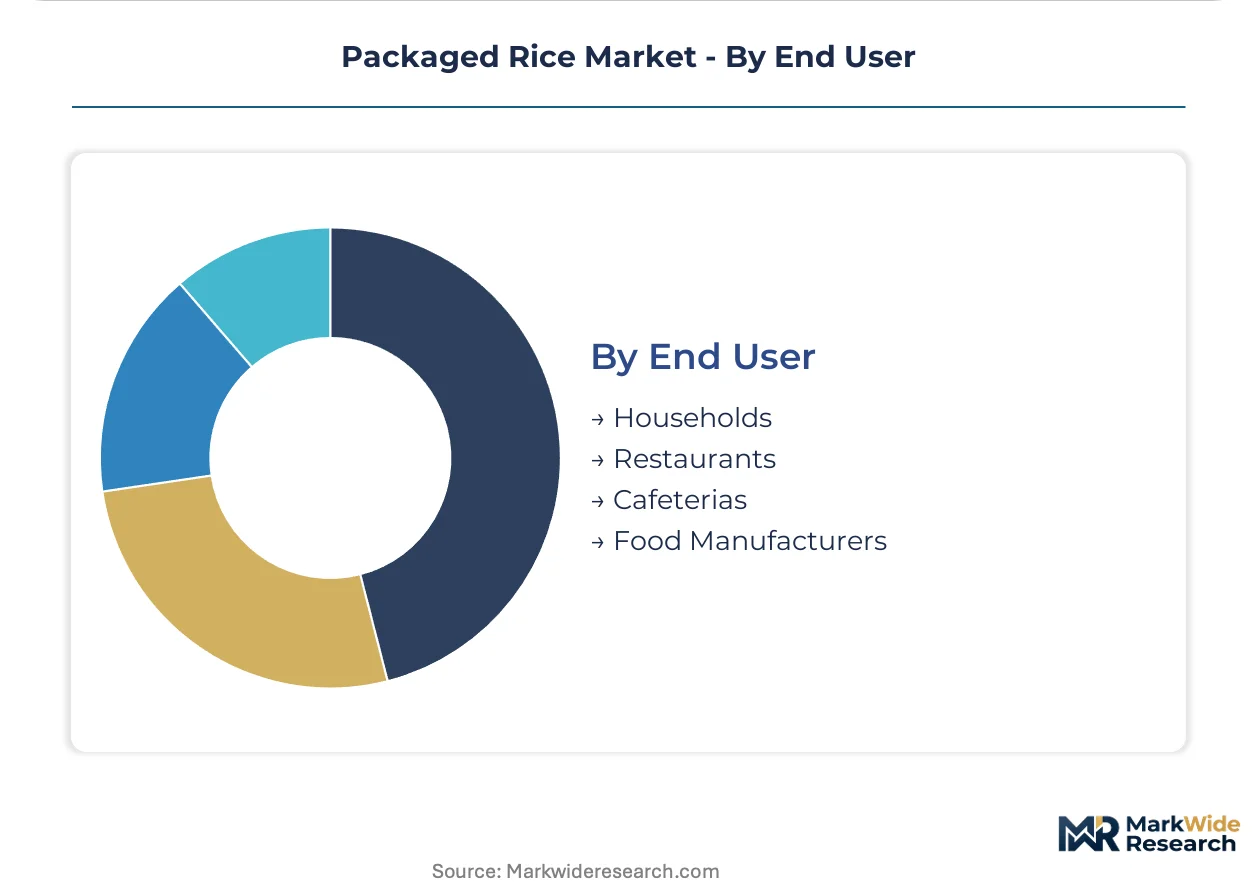
End User:
Application requirements diverge sharply on specification tolerance, delivery frequency, and fortification mandates.
- Households:Individual consumers purchasing through retail or e-commerce channels. Convenience and portion sizing now outweigh price per kilogram in urban Indian and Southeast Asian markets.
- Restaurants:Food service operations requiring consistent grain elongation and cooking behavior. GCC hospitality sector procurement standardization favors certified Basmati suppliers with annual contract structures.
- Cafeterias:Institutional feeding programs including schools, hospitals, and corporate facilities. India's FSSAI fortification mandates apply directly to government-sourced volumes.
- Food Manufacturers:Industrial processors of rice flour, extruded snacks, and ready-to-eat meals. FDA pesticide residue thresholds and allergen labeling requirements shape origin selection for US-bound ingredients.
Households represent the deepest installed base. Food manufacturers are where specification complexity is expanding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household procurement in Saudi Arabia and the UAE concentrates premium Basmati demand through centralized retail consolidation, while India's FSSAI fortification mandates reshape export specifications across government distribution channels.
India
Punjab and Haryana millers supply quality Basmati through integrated procurement networks anchored in the Indo-Gangetic belt. FSSAI mandates iron, folic acid, and vitamin B12 fortification for government-sourced packaged rice, forcing laboratory infrastructure investments. Mumbai and Bangalore quick-commerce platforms displace traditional kirana stores with 1-5 kilogram pouch formats.
United States
Private-label retail channels dominate volume through Arkansas-Mississippi Delta milling infrastructure serving North American households. FDA pesticide residue thresholds and allergen labeling requirements shape origin selection for rice imports. California's Sacramento Valley hosts specialty brown rice production targeting health-oriented West Coast consumers.
Saudi Arabia
Centralized retail consolidation and hospitality sector procurement standardization drive premium Basmati positioning in GCC markets. MOHAP food safety regulations align with import quality protocols for distributed packaged rice. Riyadh and Jeddah retail chains enforce ISO 22000 supplier qualification for private-label penetration.
Germany
EFSA arsenic limit evaluations create maximum permissible level uncertainty that delays European-bound shipment clearances. EU Green Deal Farm to Fork strategy forces blockchain-enabled traceability documentation for pesticide application and carbon footprint tracking. Frankfurt and Hamburg import channels redirect Basmati volumes toward Middle Eastern markets with less stringent sustainability requirements.
Thailand
Jasmine rice exports concentrate in Southeast Asian restaurant supply and diaspora community networks across North America and Australia. The country's national agricultural regulator enforces residue monitoring for export-bound aromatic varieties. Bangkok and Chiang Rai processing clusters serve ethnic grocery procurement channels with sticky-texture grain specifications.
Packaged Rice Market Competitive Landscape
Player mix skews toward integrated millers with captive procurement networks and diversified origin traders with multi-crop hedging capabilities. The market structure compresses around ISO 22000 certification requirements that smaller operators cannot finance, creating tiered consolidation between laboratory-equipped processors and traditional millers. Three archetypes dominate: Punjab-Haryana integrated Basmati specialists, Arkansas-Mississippi Delta private-label suppliers, and Singapore-based multi-origin trading houses. Competitive moves center on African and Asian origin diversification and precision moisture monitoring technology licensing.
Among India-based integrated processors, KRBL Limited and LT Foods Limited exemplify the Punjab-Haryana procurement archetype with laboratory-equipped quality assurance infrastructure. Cargill, Incorporated anchors North American private-label positioning through scale-driven Arkansas-Mississippi Delta milling capacity. Olam International Limited occupies the multi-origin trading tier with African and Asian sourcing diversification that reduces single-crop dependency.
| Leading Market Players |
|---|
| Ebro Foods S.A. |
| Charoen Pokphand Foods Public Company Limited |
| KRBL Limited |
| Ricegrowers Limited |
| Olam International Limited |
| LT Foods Limited |
| China National Cereals, Oils and Foodstuffs Corporation |
| Cargill, Incorporated |
| Riceland Foods Inc. |
| Others |
Value Network & Pricing Analysis
Arkansas-Mississippi Delta milling scale compresses per-unit processing costs below smaller regional competitors, concentrating supply-side power among integrated operators while establishing price floors that traditional millers cannot match without laboratory-equipped quality infrastructure.
Pricing Analysis
Annual offtake contracts with Thai export price indexation dominate Basmati procurement in Saudi Arabia and the UAE, with premiums attaching to aged grades and FSSAI fortification compliance. Price differentiation separates ISO 22000-certified suppliers from uncertified millers in GCC retail channels, while private-label penetration in North America intensifies cost compression. Margins are tightening due to precision moisture monitoring capital requirements. Food manufacturers exhibit lowest price sensitivity given specification tolerance for industrial applications, whereas urban Indian households through quick-commerce platforms show highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Strait of Hormuz transit underwrites GCC-bound Basmati volumes from Indian Punjab-Haryana clusters, creating logistics vulnerability that multi-origin traders hedge through African and Asian sourcing diversification. Supply draws from India, Thailand, and Vietnam for aromatic varieties, with Arkansas-Mississippi Delta anchoring North American long-grain production. Paddy procurement, precision drying infrastructure, and flexible-format pouch film constitute critical input dependencies. Single-crop concentration in the Indo-Gangetic belt presents monsoon-driven yield volatility. Distribution runs through wholesale distributors for institutional volumes, with online retailers capturing fastest-growing urban household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Saudi Arabia and UAE retail consolidation, with centralized procurement departments extracting compliance concessions that fragment supplier margins across smaller millers unable to finance ISO 22000 certification.
For Market Incumbents: Secure backward integration into Punjab-Haryana paddy procurement networks to defend Basmati quality consistency against water-stress yield volatility, while locking in multi-year offtake agreements with GCC hospitality procurement standardization programs. Channel control through direct quick-commerce platform partnerships in Mumbai and Bangalore prevents margin erosion from aggregator intermediation. Laboratory infrastructure investment for FSSAI fortification compliance represents the critical defensive lever against organized miller competition. For New Entrants and Emerging Players: Differentiate on organic brown rice certification targeting European health-oriented retailers and North American West Coast consumers, where glycemic index testing capabilities command shelf-space premiums absent from commodity white rice segments. The most penetrable white space sits in African origin diversification for Asian traders seeking monsoon hedges, with e-commerce pouch packaging for single-household urban Indian consumption offering the clearest go-to-market angle through 10-minute delivery app partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated millers with captive procurement networks and annual contract structures serving GCC retail consolidation, as opposed to spot-market-dependent traditional operators. Long-term viability over the projection horizon favors laboratory-equipped processors with multi-origin hedging capabilities over single-belt concentrators. The acquisition target archetype combines Punjab-Haryana Basmati specialization with African sourcing diversification. The signal to watch is FSSAI fortification mandate expansion into additional micronutrients, which would accelerate laboratory infrastructure requirements and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Moisture Monitoring Deployment | Near-infrared spectroscopy adoption at Arkansas-Mississippi Delta mills tightens specification windows for private-label contracts. |
| Blockchain Traceability Integration | Farm-to-Fork documentation satisfies EU Green Deal requirements for German and French retail channel access. |
| African Origin Diversification | Multi-crop hedging through Asian and African sourcing reduces monsoon dependency for Singapore-based trading houses. |
| Quick-Commerce Pouch Format Expansion | 1-5 kilogram flexible packaging captures Mumbai and Bangalore household fragmentation from bulk purchasing patterns. |
| FSSAI Fortification Laboratory Investment | Iron, folic acid, and vitamin B12 blending capability preserves Indian government distribution program eligibility. |
Research Methodology
The analysis maps white rice, Basmati, brown rice, and Jasmine sub-sectors, each validated through procurement directors at integrated millers, quality assurance leads at export trading houses, retail category buyers in Saudi Arabia and the UAE, and food manufacturing ingredient sourcing managers. Primary interview findings were cross-referenced with customs and trade flow databases, FSSAI regulatory filings, FDA import refusal data, and EU EFSA scientific opinions. Bottom-up segment sizing and top-down macroeconomic anchoring were reconciled through iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, packaging format, distribution channel, and end-user segmentation dimensions, with CAGRs derived from trend extrapolation moderated by regulatory inflection assessment. Forecast inputs incorporated FSSAI fortification mandate implementation timelines and EU arsenic limit evaluation trajectories.
Material uncertainties — monsoon variability in the Indo-Gangetic belt, EU Green Deal traceability requirement tightening, and GCC retail consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and procurement pattern continuity. Practitioners should keep alternative scenarios live as FSSAI micronutrient expansion and EFSA limit finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Ready Meals Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
Canned Soup Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
North America Ready Meals Market