
 Ready Meals Market | 2026-2036
Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Ready Meals Market Intelligence
The capability gap between high-volume, automated manufacturing and small-batch artisanal production is unwinding traditional market structures. Large-scale players like Nestlé S.A. leverage extensive distribution networks to dominate the frozen and shelf-stable categories. Hormel Foods Corporation specializes in protein-centric meal solutions for specific consumer segments. Meanwhile, Conagra Brands Inc. competes across a diversified portfolio targeting various dietary preferences.
Ready meals are fully or partially cooked food products, packaged for long shelf life and convenience. Many shelf-stable varieties utilize retort processing to achieve commercial sterility, while chilled products often use Modified Atmosphere Packaging (MAP) to preserve freshness. The frozen product type continues to command the largest market share by volume, though the chilled segment shows faster value growth. Ingredient-based differentiation, such as organic and gluten-free options, creates high-margin opportunities for specialized producers.
Food safety standards from the United States' FDA and the European Food Safety Authority (EFSA) dictate permissible ingredients and processing methods. Concurrently, labeling regulations from these bodies and India's FSSAI mandate clear nutritional and allergen information, shaping consumer choice. The primary strategic decision for manufacturers centers on balancing cost with the transition to sustainable packaging materials.
Market Dynamics
The central dynamic in the ready meals market is the escalating tension between consumer demand for fresh, minimally processed food and the operational need for extended shelf life. This conflict drives innovation in non-thermal processing and advanced packaging to deliver convenience without perceived compromises on health.
Growth Catalysts
- High-Pressure Processing (HPP):This non-thermal pasteurization technology extends the shelf life of chilled ready meals without chemical preservatives or heat, meeting demand for "clean label" products from health-conscious consumers.
- Urbanization in Emerging Economies:Rapidly growing urban populations and an increase in dual-income households in countries like India and Brazil are expanding the consumer base for convenient, time-saving food solutions.
- Mandatory Nutritional Labeling:Regulations like front-of-pack labeling in Mexico and other Latin American countries encourage manufacturers to reformulate products with lower sodium, sugar, and fat, creating a catalyst for healthier product lines.
Market Restraints
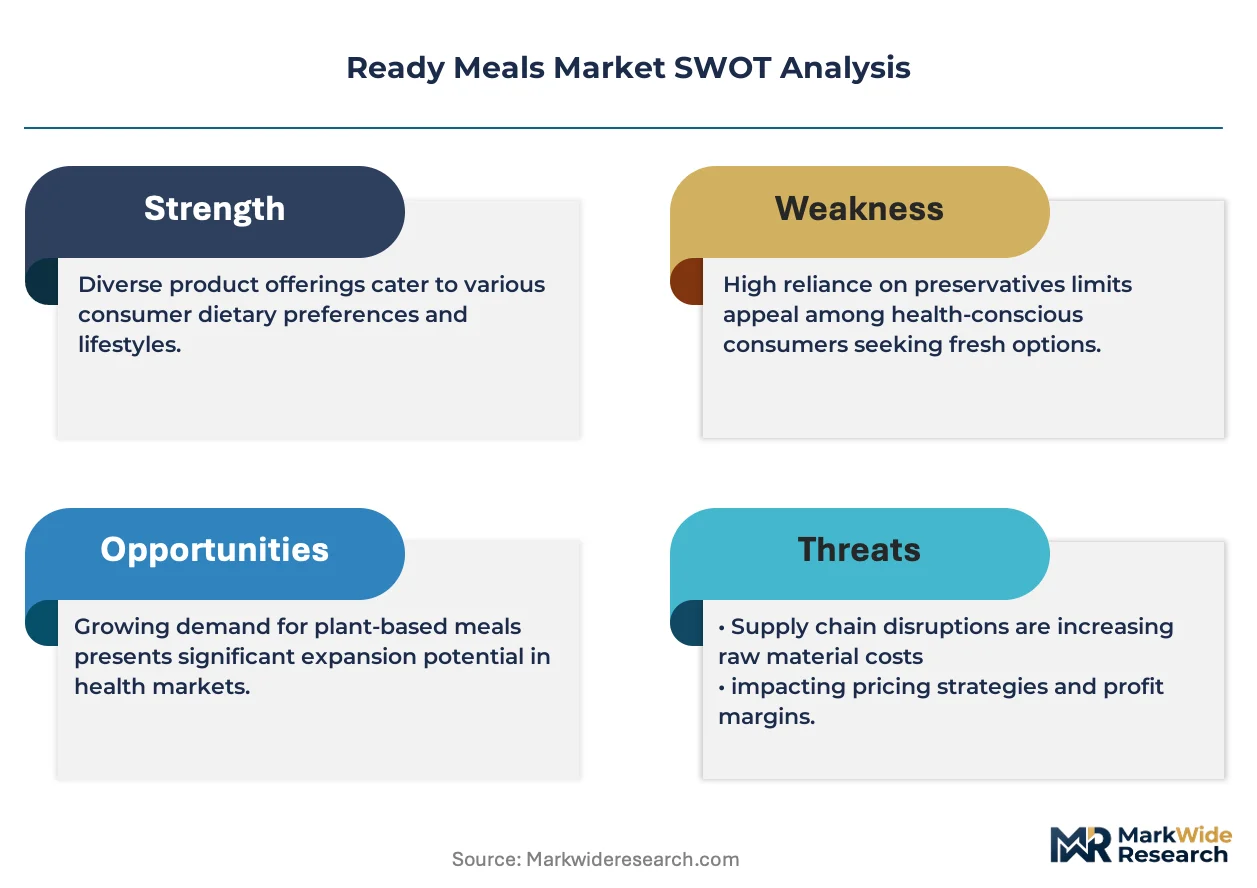
- Input Cost Volatility:Fluctuations in the prices of core ingredients such as proteins, grains, and specialty vegetables create significant margin pressure and make cost management a persistent challenge for manufacturers.
- Cold Chain Infrastructure Gaps:In many developing regions, inadequate or unreliable cold chain logistics limit the distribution and market penetration of chilled and frozen ready meals, favoring more resilient shelf-stable formats.
- Consumer Perception Barriers:A lingering skepticism among some consumer segments regarding the freshness, nutritional quality, and taste of pre-packaged meals acts as a restraint, leading to substitution with fresh-cooked or foodservice options.
Strategic Opportunities
- Plant-Based Formulations:The growing consumer interest in veganism and flexitarian diets creates a high-margin opportunity for innovative, plant-based ready meals that deliver on both taste and nutritional profiles.
- Direct-to-Consumer (DTC) Models:Subscription-based DTC services enable manufacturers to bypass retail gatekeepers, build direct customer relationships, and offer personalized meal plans tailored to specific dietary needs or preferences.
- Geriatric Nutrition Focus:Developing ready meals specifically formulated for the elderly—with modified textures, fortified nutrients, and portion control—addresses an underserved demographic with distinct nutritional requirements in aging populations.
Industry Challenges
- Sustainable Packaging Transition:Migrating from multi-layer plastics to recyclable or compostable packaging alternatives presents a major operational challenge, requiring significant R&D investment to ensure product safety and maintain shelf stability.
- Regulatory Divergence:Navigating the complex and often conflicting food safety and labeling standards between major markets, such as those set by the FDA and EFSA, increases compliance costs and slows international expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready Meals Market |
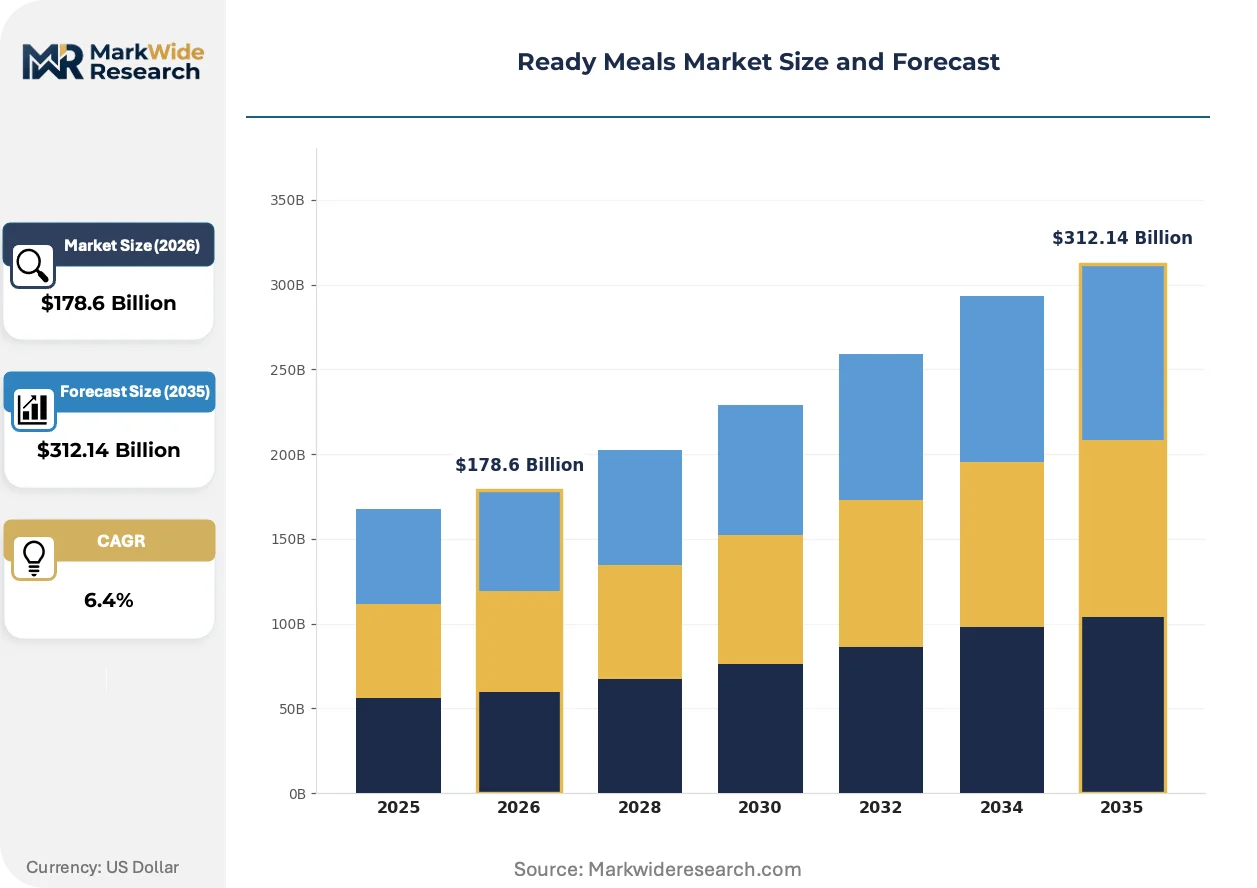
| Market Size in 2026 | $178.6 Billion |
| Market Size in 2035 | $312.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Chilled, Shelf-Stable, Fresh Ingredients: Vegetarian, Gluten-Free, Organic, High-Protein End User: Busy Professionals, Families, Students, Seniors Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice |
| Companies Covered | General Mills Inc., Unilever PLC, Nestlé S.A., Hormel Foods Corporation, Nomad Foods Limited, Conagra Brands Inc., Tyson Foods Inc., McCain Foods Limited, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready Meals Market Strategic Shifts & Innovations
Processing technologies and material science are enabling a new generation of ready meals that challenge traditional definitions of packaged food. These innovations focus on delivering enhanced freshness, targeted nutrition, and greater transparency, fundamentally altering consumer expectations and competitive dynamics.
Modified Atmosphere Packaging (MAP) is a key technology that alters the gas composition within a package to slow spoilage. Producers of premium chilled ready meals targeting grocery and specialty food retailers are the primary adopters. MAP technology is decomposing the rigid boundary between fresh-prepared and packaged meals, allowing chilled products to offer a longer shelf life while retaining a "just-made" sensory quality.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes stringent targets for material recyclability and the inclusion of recycled content. This mandate is forcing a systemic shift in packaging design, pushing manufacturers away from traditional multi-layer films. The shelf-stable and frozen categories, which depend on high-barrier packaging, are most affected and must accelerate investment in monomaterial solutions.
A distinct consumer shift toward personalized and functional nutrition is creating demand for meals that address specific health goals or dietary restrictions. This trend disrupts the mass-market model of one-size-fits-all products, creating openings for niche brands specializing in keto, low-FODMAP, or diabetic-friendly options. This movement is most visible in developed markets like the United States and Australia, often powered by direct-to-consumer platforms.
Ready Meals Market Segmentation
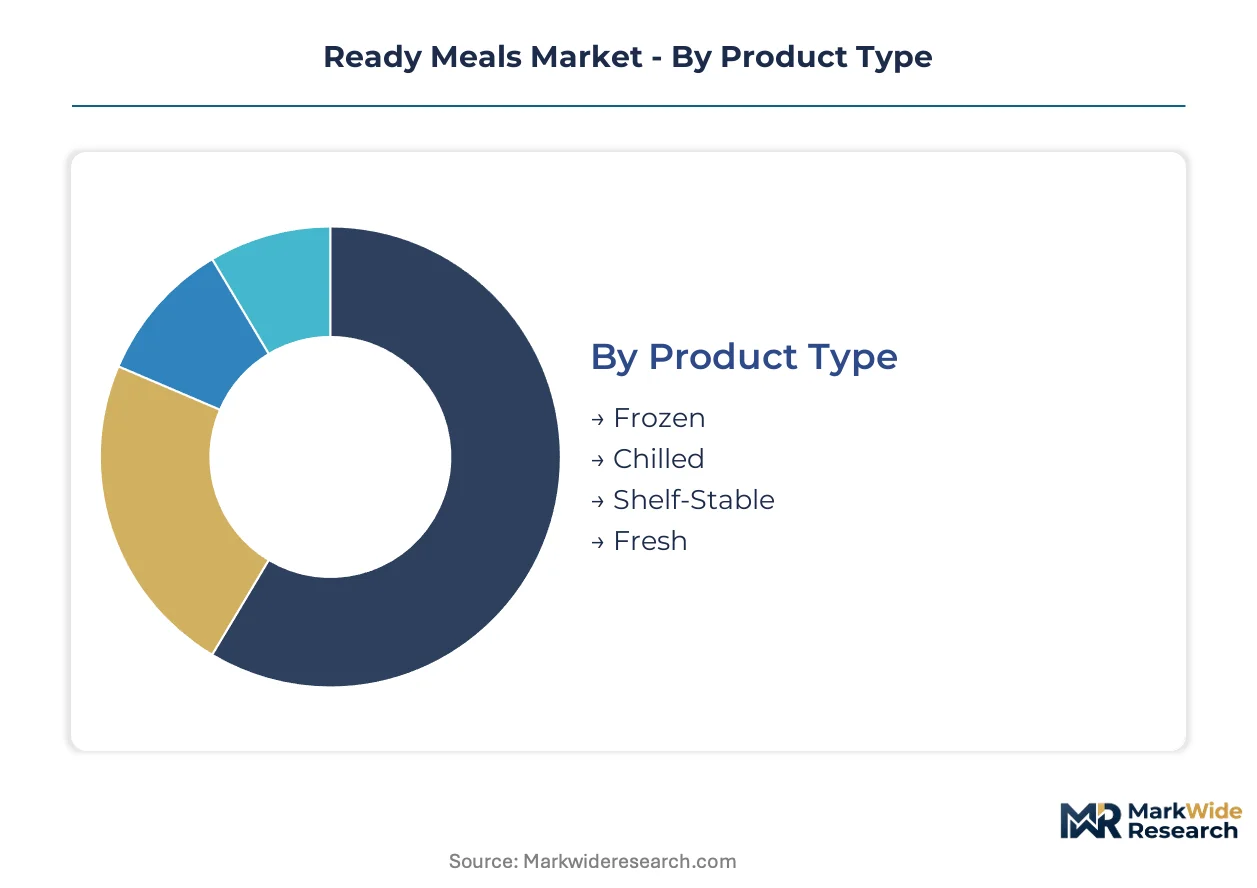
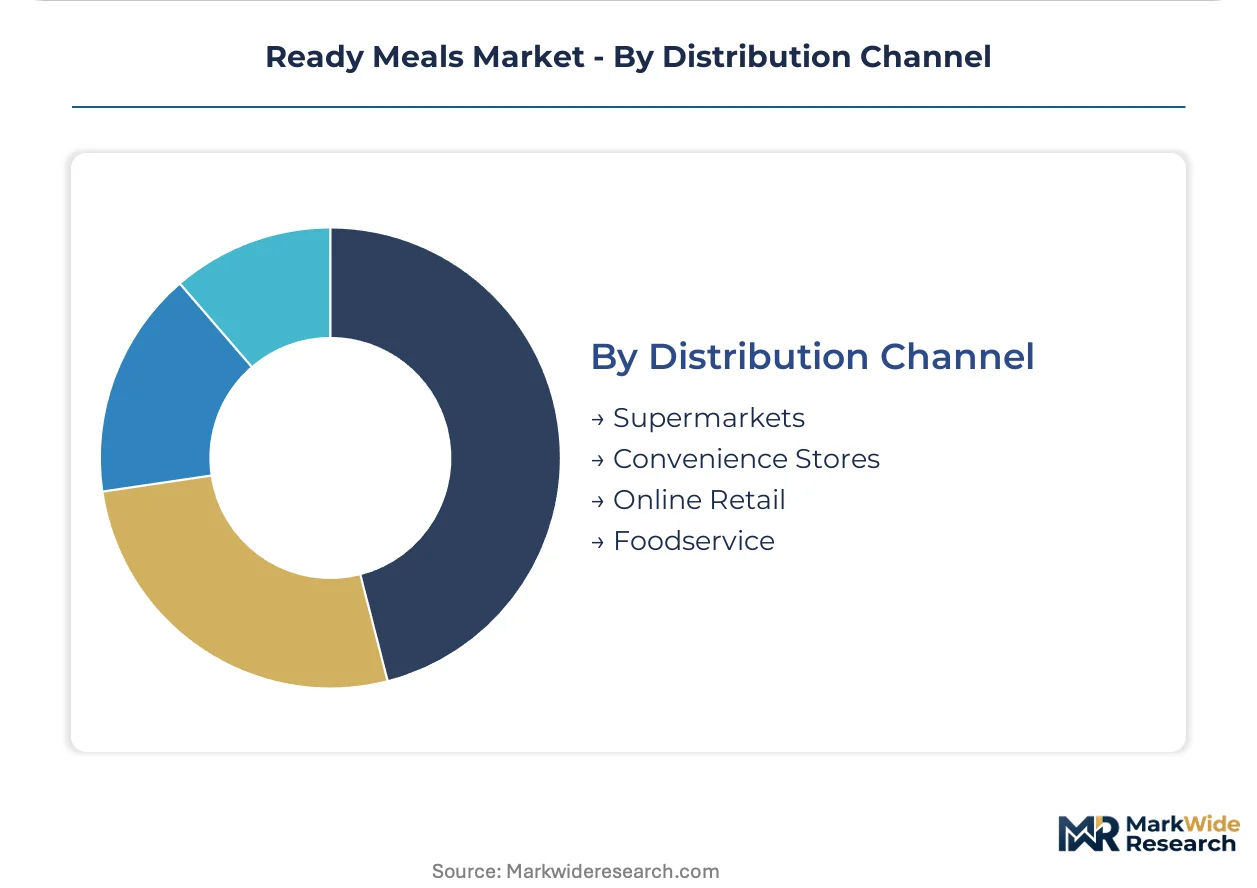
Market segmentation provides a granular view of the Ready Meals sector, dissecting the diverse product offerings, consumer preferences, and distribution pathways. This analysis helps manufacturers identify high-growth niches and tailor their strategies to specific demand drivers within the broader market landscape. Understanding these distinct segments is crucial for navigating competitive dynamics and optimizing product portfolios.
Product Type:
The segmentation by product type highlights varying degrees of consumer perception regarding freshness and nutritional quality, creating distinct substitution pressures across categories.
- Frozen:These products are fully cooked or partially prepared meals that are flash-frozen to preserve quality, offering extended shelf life and convenience. Demand for frozen ready meals remains robust in developed markets like the United States due to established cold chain infrastructure and wide retail availability.
- Chilled:Chilled ready meals are typically fresh or minimally processed, requiring refrigeration and offering a shorter shelf life than frozen or shelf-stable alternatives. Innovations in Modified Atmosphere Packaging (MAP) and High-Pressure Processing (HPP) are driving value growth for chilled products, particularly in European grocery chains.
- Shelf-Stable:These ready meals undergo retort processing to achieve commercial sterility, allowing storage at ambient temperatures for extended periods without refrigeration. Shelf-stable formats are crucial for market penetration in developing regions where cold chain infrastructure is less reliable.
- Fresh:Fresh ready meals are minimally processed, often requiring immediate consumption or short-term refrigeration, and are typically found in deli sections or specialized meal kit services.
Frozen ready meals retain volume leadership; chilled products hold the steepest expansion curve.
Ingredients:
Ingredient-based segmentation reveals varying cost structures and margin opportunities, as specialized formulations command premium pricing.
- Organic:These ready meals use ingredients certified as organic, free from synthetic pesticides, fertilizers, and genetically modified organisms. Organic options create high-margin opportunities for specialized producers targeting health-conscious consumers in markets such as Australia and Germany.
- High-Protein:Formulations emphasizing increased protein content cater to consumers focused on fitness, muscle building, or satiety, often featuring lean meats, legumes, or plant-based protein sources. This segment sees strong demand from athletes and active individuals seeking functional nutrition.
- Vegetarian:Vegetarian ready meals exclude meat, poultry, and fish, focusing on plant-based ingredients, eggs, and dairy.
- Gluten-Free:These products are formulated without gluten-containing grains like wheat, barley, or rye, addressing the needs of individuals with celiac disease or gluten sensitivity.
Organic formulations offer high-margin opportunities; high-protein options are expanding most quickly among health-conscious consumers.
End User:
Understanding end-user segments is critical for tailoring product development and marketing strategies to specific lifestyle demands.
- Busy Professionals:This demographic prioritizes convenience and time-saving solutions, seeking quick, easy-to-prepare meals that fit demanding schedules. Busy professionals in urban centers across the United States are a primary expansion force for the ready meals market.
- Seniors:Ready meals for the elderly often feature modified textures, fortified nutrients, and portion control to address distinct nutritional requirements and ease of consumption. This underserved demographic in aging populations, particularly in Japan and Western Europe, represents a significant strategic opportunity.
- Families:Family-sized ready meals offer convenience for households, reducing cooking time and effort for multiple servings.
- Students:Students seek affordable, convenient, and easy-to-store meal options, often favoring single-serve or budget-friendly formats.
Busy professionals drive significant volume; the seniors segment represents a rapidly emerging demographic for specialized offerings.
Distribution Channel:
The choice of distribution channel significantly impacts market reach and operational efficiency, determining access to diverse consumer segments.
- Supermarkets:Large retail chains offer extensive shelf space and broad geographic reach, making them the primary channel for mass-market ready meal brands. Supermarkets serve as a foundational channel for large-scale players like Nestlé S.A. to distribute frozen and shelf-stable categories.
- Online Retail:E-commerce platforms, including dedicated meal delivery services and grocery e-tailers, provide convenience and direct access to consumers, enabling personalized meal plans. Subscription-based direct-to-consumer (DTC) models are gaining traction, especially in the United States, by bypassing traditional retail gatekeepers.
- Convenience Stores:These smaller retail outlets offer quick access to grab-and-go meal solutions, catering to immediate consumption needs.
- Foodservice:This channel includes ready meals supplied to institutions, catering services, and restaurants for bulk preparation or quick serving.
Supermarkets remain the primary sales channel; online retail is gaining share fastest through direct-to-consumer models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between developed markets and emerging economies. Consumers in the United States often command premium options, while price sensitivity in India drives demand for value-oriented ready meals. This dynamic shapes investment priorities and product development across different regions.
United States
Demand from busy professionals and a robust cold chain infrastructure fuels the ready meals market in the United States. The FDA's food safety standards influence processing methods and ingredient disclosure for manufacturers. Urban centers like New York City see high adoption of convenient, healthy meal solutions from specialized producers.
Germany
Health-conscious consumers in Germany seek organic and clean-label ready meal options. EFSA regulations, alongside national food laws, ensure strict quality and ingredient transparency. The Rhine-Main region actively develops advanced packaging solutions for chilled products to extend shelf life.
India
Urbanization and increasing dual-income households expand the consumer base for convenient meals in India. The FSSAI mandates clear nutritional and allergen information, shaping consumer trust. Major metropolitan areas like Mumbai are witnessing a surge in demand for shelf-stable and affordable ready meal formats.
Brazil
Rapidly growing urban populations in Brazil create strong demand for time-saving food solutions. ANVISA, the national health surveillance agency, oversees food safety and labeling requirements for packaged foods. São Paulo's food processing clusters focus on developing culturally relevant and accessible ready meal options.
Japan
Aging populations and single-person households drive demand for portion-controlled, nutrient-fortified ready meals in Japan. The Ministry of Health, Labour and Welfare sets standards for food additives and nutritional claims. Tokyo's innovative food tech companies are exploring geriatric nutrition solutions and automated meal preparation.
Ready Meals Market Key Industry Players
Concentration sits with large, diversified food conglomerates leveraging extensive distribution networks, particularly in the frozen and shelf-stable categories. The market exhibits a tiered structure, from global mass-market players to specialized niche producers focused on high-margin opportunities. Strategic archetypes include those focused on broad consumer segments and others targeting specific dietary preferences. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and adapt to evolving consumer demands.
Within the established mass-market segment, Nestlé S.A. exemplifies a global player with vast reach across frozen and shelf-stable categories, leveraging its extensive manufacturing and distribution capabilities. Hormel Foods Corporation occupies a position specializing in protein-centric meal solutions, catering to specific consumer segments seeking functional nutrition. Conagra Brands Inc. further represents a diversified portfolio approach, targeting various dietary preferences and product types, from frozen to shelf-stable, to maintain broad market relevance.
| Leading Market Players |
|---|
| General Mills Inc. |
| Unilever PLC |
| Nestlé S.A. |
| Hormel Foods Corporation |
| Nomad Foods Limited |
| Conagra Brands Inc. |
| Tyson Foods Inc. |
| McCain Foods Limited |
| The Kraft Heinz Company |
| Others |
Cost & Logistics Intelligence
The United States FDA and European EFSA regulations gate supply qualification and simultaneously drive price differentiation for ready meals. These stringent food safety and labeling standards influence ingredient sourcing, processing methods, and ultimately, consumer perception of product value.
Pricing Analysis
The customization-premium spread dictates pricing across the ready meals market, with personalized meal plans commanding higher prices than standard retail offerings. Per-unit transactional pricing dominates mass-market retail, while subscription models gain traction in direct-to-consumer channels. Price differentiation stems from organic certification, high-pressure processing (HPP) adoption, and convenience features like modified atmosphere packaging (MAP). Pricing pressure originates from input cost volatility for proteins and specialty vegetables, impacting mass-market margins. Students and budget-conscious families represent the most price-sensitive segments, while busy professionals prioritize convenience over cost.
Supply Chain Analysis
India, with its expanding urban populations, anchors the supply of shelf-stable ready meals, leveraging retort processing for extended ambient storage. Developed markets like the United States and Germany concentrate on chilled and frozen product supply, supported by robust cold chain infrastructure. The supply chain draws from key inputs such as proteins, grains, specialty vegetables, and advanced packaging materials. A structural risk involves cold chain infrastructure gaps in emerging economies, limiting distribution for chilled and frozen formats. Distribution runs primarily through large supermarkets, with online retail and direct-to-consumer models expanding rapidly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ready meals market exhibits a defensive moat, largely due to regulatory entrenchment and established cold chain infrastructure. This provides stability for large players while creating specific entry points for agile innovators.
For Market Incumbents: Shield established market share from consumer skepticism regarding freshness by investing in non-thermal processing technologies like HPP and MAP. Diversify product portfolios into plant-based formulations to capture evolving dietary preferences and mitigate input cost volatility. Leverage extensive distribution networks to push innovative, sustainable packaging solutions across all product types, addressing environmental concerns. For New Entrants and Emerging Players: The service-layer gap in highly personalized and functional nutrition offers a clear entry point for new brands. Target underserved demographics like seniors with nutrient-fortified, texture-modified meals in developed markets like Japan. Focus on direct-to-consumer (DTC) subscription models, building brand loyalty through tailored meal plans and transparent ingredient sourcing. This approach bypasses traditional retail gatekeepers and offers direct customer feedback. For Investors and Strategic Acquirers: The European Union’s Packaging and Packaging Waste Regulation reshapes the acquisition landscape, favoring companies with advanced sustainable packaging solutions. Long-term viability hinges on companies capable of balancing convenience with perceived health benefits and environmental responsibility. Target specialized producers with proprietary non-thermal processing IP or strong market positions in high-margin segments like organic or plant-based offerings. The adoption rate of monomaterial packaging across major brands signals a critical inflection point.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in HPP/MAP Technology | Extends shelf life for chilled products without preservatives, appealing to health-conscious consumers. |
| Develop Plant-Based Product Lines | Captures demand from vegan and flexitarian consumers, expanding market reach. |
| Transition to Monomaterial Packaging | Addresses regulatory mandates and consumer demand for environmentally sustainable packaging solutions. |
| Expand Direct-to-Consumer Channels | Builds direct customer relationships and enables personalized meal plans, bypassing retail. |
| Formulate Geriatric-Specific Meals | Addresses the distinct nutritional needs of aging populations, tapping into an underserved demographic. |
Research Approach
A standing panel of food technologists, retail category managers, and supply chain logistics experts provided ongoing calibration for market data. This primary research was rigorously validated through secondary sources, including FDA filings, EFSA reports, industry association publications, and retail sales data. A robust methodology combined bottom-up market sizing with top-down validation, ensuring comprehensive coverage.
Outputs were consistently validated against external benchmarks, ensuring forecast accuracy across the analysis window. The analytical framework modeled key segmentation dimensions including product type, ingredients, end-user, and distribution channel. Compound Annual Growth Rates (CAGRs) were derived from historical data and projected trends, incorporating factors such as urbanization rates and HPP adoption. This approach provided a detailed quantitative outlook.
Forecasts assume regulatory continuity in FDA and EFSA standards; material policy shifts would require re-modeling. Projections account for potential impacts from input cost volatility and the challenges associated with sustainable packaging transitions. Recalibration cycles align with material shifts in these named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Peanut Butter Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Tortilla Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Instant Soup Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Packaged Burgers Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Canned Goods Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Packaged Currants Market