
 Canned Tropical Fruit Market | 2026-2036
Canned Tropical Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Tropical Fruit Market Analysis
Food service buyers is bifurcating demand away from traditional household purchasers as restaurant chains and institutional caterers expand tropical fruit applications in smoothies, desserts, and fusion cuisine. Dole Food Company leverages its plantation-to-can vertical infrastructure across Philippine and Thai operations to secure year-round pineapple supply. Del Monte Foods anchors North American retail shelf presence through long-standing private-label and branded contracts with mass-market grocers. Goya Foods differentiates within Hispanic and Caribbean demographic channels where consumer preference for papaya and mixed fruit formats runs strongest.
Canned tropical fruit comprises peeled, cored, and syrup- or juice-packed fruit segments thermally processed in hermetically sealed metal containers to achieve commercial sterility and shelf stability exceeding 24 months. The category serves retail households, food manufacturers requiring standardized ingredient inputs, and export traders arbitraging seasonal harvest gaps between hemispheres. Pineapple dominates volume throughput due to established mechanized peeling infrastructure and consistent global demand, while mango commands margin premiums in European and North Asian markets where fresh supply remains seasonal. Pouch packaging is gaining traction among convenience-oriented households and outdoor recreation segments despite metal can dominance in traditional retail and food service procurement.
FDA regulations govern acidified food classification and scheduled process filing for canned tropical fruit sold in the United States, while EU F-Gas Regulation and REACH compliance shape refrigerant and packaging material choices for European-bound shipments. BIS standards in India mandate specific preservative limits and nutritional labeling disclosures that constrain formulation flexibility for imported brands. Stakeholders must monitor evolving extended producer responsibility frameworks for single-use packaging across multiple jurisdictions where post-consumer can recovery rates increasingly influence retailer procurement criteria.
Market Dynamics
Food service procurement consolidation is concentrating volume among institutional buyers who demand year-round supply contracts and standardized tropical fruit specifications that traditional retail channels cannot match.
Growth Catalysts
- Extended Producer Responsibility frameworks:EU packaging recovery mandates are incentivizing steel can recyclability investments that align with retailer sustainability scorecards.
- Food service menu innovation:Quick-service chains in Southeast Asia are embedding canned pineapple and mango into limited-time dessert and beverage offerings.
- Mechanized peeling infrastructure:Thai processing facilities deploy automated coring lines that reduce labor dependency and stabilize throughput during peak harvest windows.
Market Restraints
- Raw material seasonality:Fresh mango harvest gaps in India and Pakistan compress processing windows and force inventory carry costs.
- BIS additive limits:India's FSSAI-enforced preservative caps restrict formulation flexibility for imported canned fruit brands.
- Flexible pouch substitution:Retort pouch formats are capturing convenience-oriented household segments despite metal can dominance in food service.
Strategic Opportunities
- Underpenetrated African markets:Urbanization in Nigeria and Kenya is expanding cold chain infrastructure that enables shelf-stable tropical fruit distribution.
- EU F-Gas refrigerant phase-down:The regulation is accelerating investment in ambient-stable processing that reduces energy-intensive cold storage requirements.
- Direct-to-institution e-procurement:Digital platforms are disintermediating traditional distributor layers between Southeast Asian processors and European food service operators.
Industry Challenges
- Thermal process engineering talent:Scheduled process filing expertise for acidified foods is concentrated among aging specialists in the United States and Europe.
- Dual certification timelines:Simultaneous FDA and EU organic compliance requires 18-24 month validation cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Tropical Fruit Market |
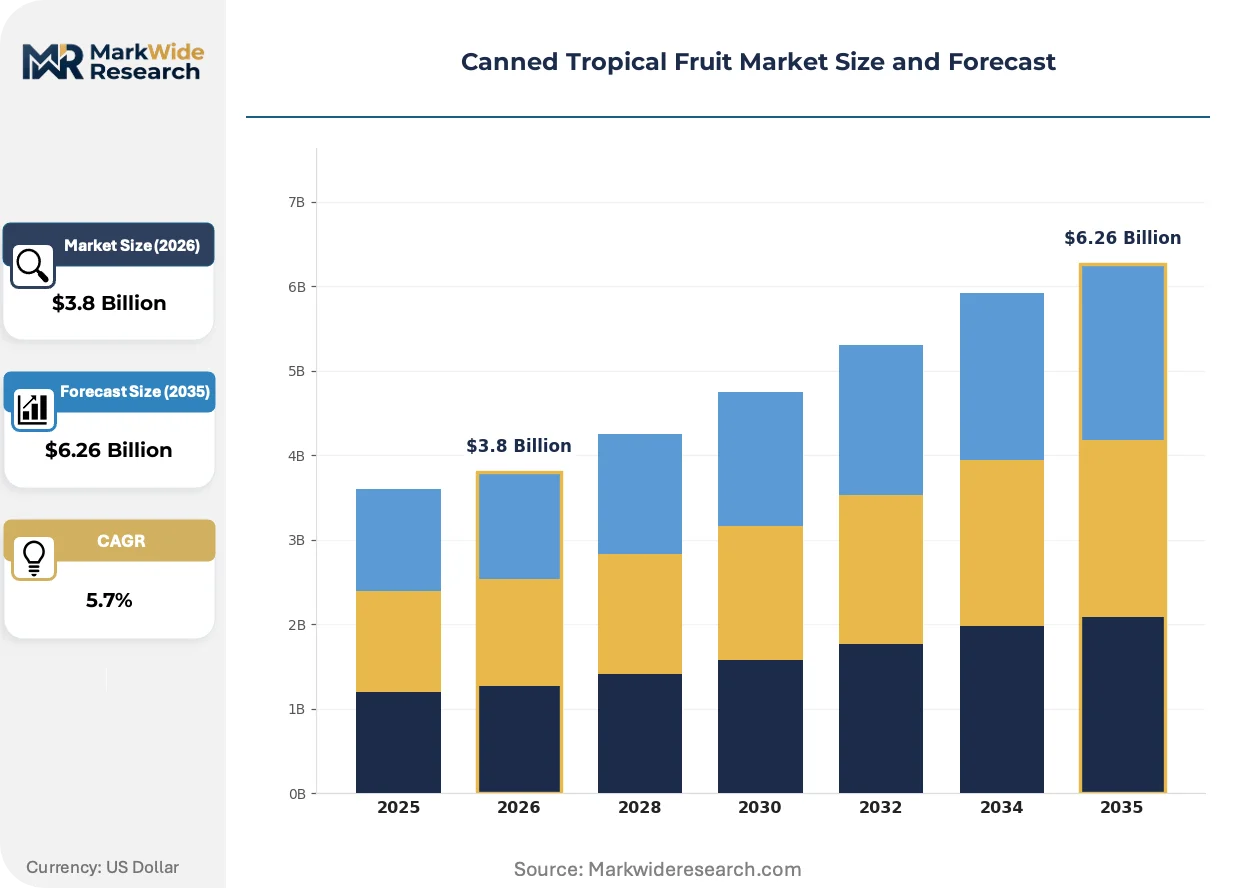
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pineapple, Mango, Papaya, Mixed Fruit Packaging Type: Can, Jar, Pouch, Bulk Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores End User: Households, Food Service, Manufacturers, Exporters |
| Companies Covered | Dole Food Company, Del Monte Foods, The Kraft Heinz Company, Bonduelle, Conagra Brands, Goya Foods, Seneca Foods Corporation, Rhodes Food Group, Siam Pineapple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Tropical Fruit Market Emerging Trajectories
Processing technology and packaging formats are converging to reduce energy intensity and extend shelf stability without synthetic preservatives, while regulatory pressure on refrigerants and additives accelerates clean-label formulation investments.
Retort pouch laminates with aluminum oxide barrier coatings are supplanting traditional three-piece steel cans in European retail channels. German and Dutch supermarket chains are adopting these formats for single-serve tropical fruit portions. The shift is compressing metal can order volumes while expanding margin capture for flexible packaging converters.
EU F-Gas Regulation phase-down schedules are forcing processing facilities to abandon hydrofluorocarbon-based refrigeration. Thai and Philippine canneries are retrofitting lines with ammonia-based cooling systems. The transition extends equipment depreciation timelines but locks in compliance ahead of 2030 bans.
Consolidated food service purchasing is compressing supplier rosters and demanding audited traceability from plantation to can. Major contract caterers in the United Kingdom and France now require blockchain-verified origin documentation. Smaller processors lacking integrated plantation control are losing tender eligibility to vertically integrated competitors.
Canned Tropical Fruit Market Segmentation
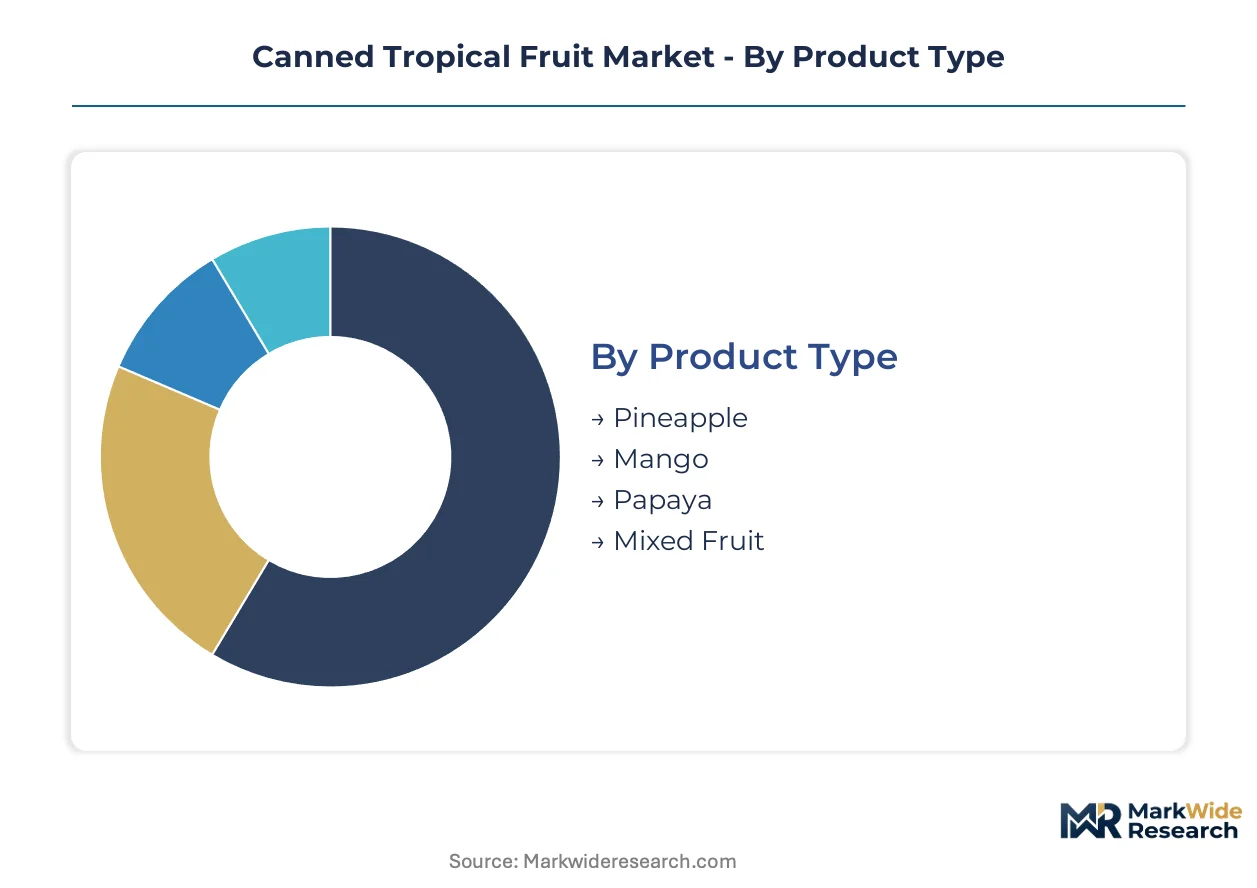
Segmentation in canned tropical fruit reveals how substitution pressures and procurement consolidation are reshaping volume flows across product formats and customer types. Understanding these fault lines exposes where margin compression concentrates and where pricing power persists.
Product Type:
Flexible pouch formats and ambient-stable purees are displacing traditional canned segments in convenience-oriented channels, forcing product-level differentiation on processing integrity and origin credentials.
- Pineapple:Mechanically peeled and cored rings or chunks packed in juice or light syrup. Thai and Philippine processing clusters supply year-round volumes to quick-service chains embedding pineapple into limited-time dessert menus.
- Mango:Sliced or halved Kent and Alphonso varieties processed during compressed harvest windows. European and North Asian markets command premium positioning where fresh supply gaps persist seasonally.
- Papaya:Firm-ripe cultivars from Central American origins serve Hispanic and Caribbean demographic channels with distinct color and texture specifications.
- Mixed Fruit:Standardized blends of pineapple, papaya, guava, and nata de coco targeting food manufacturers requiring consistent ingredient inputs for yogurt and bakery applications.
Pineapple anchors the volume base while mango gains share at the steepest rate.
Packaging Type:
Cost tiers separate commodity bulk shipments from premium single-serve formats where shelf differentiation and portion control justify material investments.
- Can:Three-piece steel containers with hermetic double-seam closures dominate food service procurement and export trade due to mechanical durability and established recycling infrastructure.
- Jar:Glass containers with lug or twist-off closures serve retail gift segments and organic-positioned lines where visual product inspection influences purchase decisions.
- Pouch:Retort laminates with aluminum oxide barriers capture European retail single-serve portions. German and Dutch supermarket chains compress metal can order volumes through format conversion.
- Bulk:Aseptic bag-in-box or steel drum formats supply food manufacturers requiring standardized tropical fruit inputs at industrial scale for further processing.
Can formats retain the volume base while pouch configurations expand most quickly in premium retail channels.
Distribution Channel:
Customer type concentration is bifurcating procurement patterns between consolidated institutional buyers and fragmented household purchasers with divergent service requirements.
- Supermarkets:Mass-market grocers anchor North American retail presence through long-standing branded and private-label shelf placements with quarterly promotional calendars.
- Online Retail:Direct-to-consumer platforms serve subscription-oriented households and bulk purchasers seeking variety packs unavailable in conventional retail assortments.
- Wholesalers:Traditional distributor layers face disintermediation as digital platforms connect Southeast Asian processors directly to European food service operators.
- Convenience Stores:Small-format urban retail in African markets leverages ambient-stable distribution where cold chain infrastructure remains underdeveloped.
Supermarkets anchor the volume base while online retail climbs the fastest among convenience-oriented segments.
End User:
Application maturity varies sharply between stable ingredient demand from manufacturers and volatile menu-driven procurement from food service innovators.
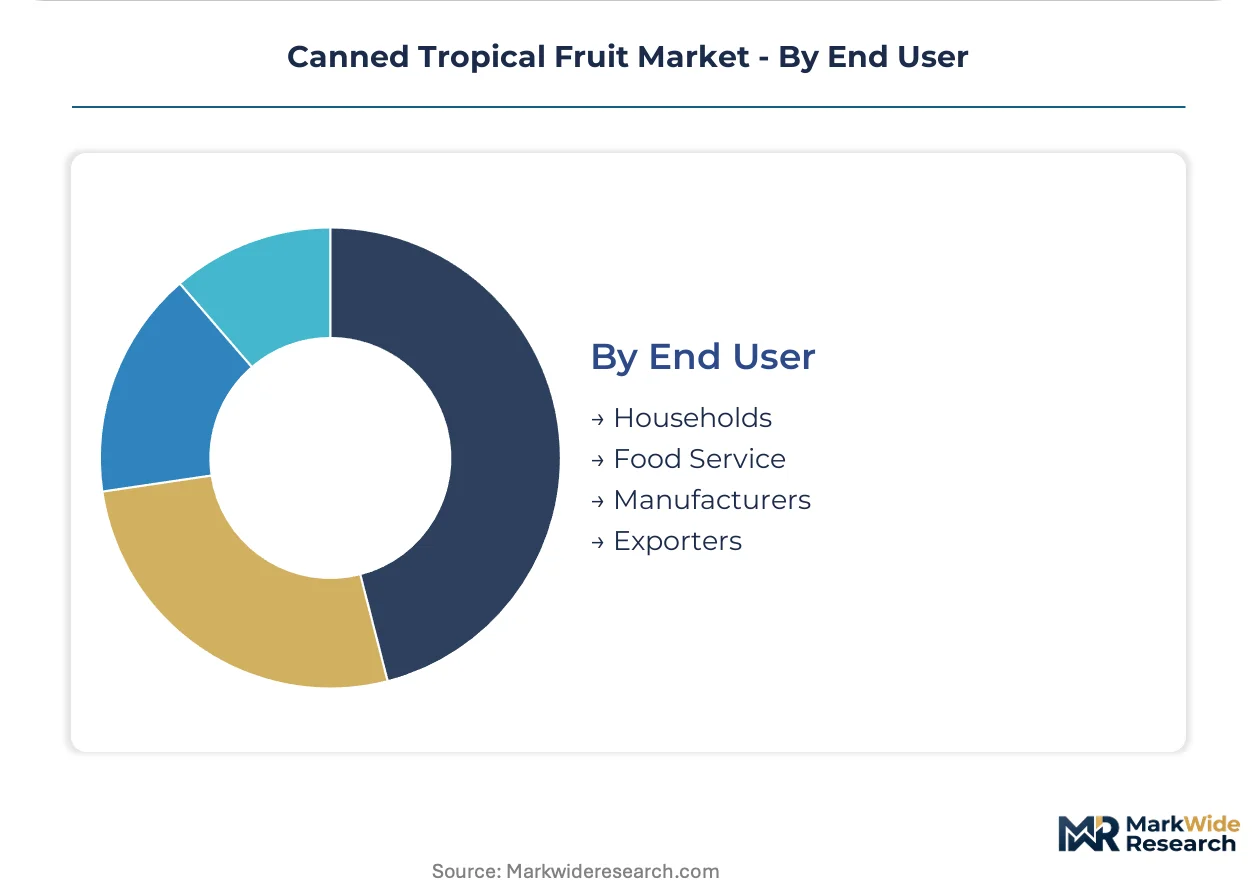
- Households:Traditional retail purchasers favoring pantry-stocking formats for home dessert and breakfast applications, now fragmenting toward convenience-oriented pouch alternatives.
- Food Service:Restaurant chains and institutional caterers demand year-round supply contracts with standardized specifications that traditional retail channels cannot match.
- Manufacturers:Food processors requiring thermally stabilized fruit inputs with consistent Brix and acidity specifications for yogurt, ice cream, and bakery production lines.
- Exporters:Traders arbitraging seasonal harvest gaps between hemispheres, sourcing from Thai and Philippine clusters for re-export to deficit markets.
Households anchor the volume base while food service gains share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service procurement consolidation is bifurcating demand patterns across major consuming countries, with institutional buyers in the United States, Germany, Thailand, Philippines, and Brazil driving contract standardization while retail channels fragment toward convenience formats.
United States
Quick-service chains and institutional caterers anchor North American tropical fruit demand through year-round supply contracts. FDA acidified food regulations govern scheduled process filing requirements for canned pineapple and mango imports. California and Florida distribution hubs handle bulk shipments from Southeast Asian processors for redistribution to national food service networks.
Germany
Retail chains in the Netherlands and German markets are accelerating pouch format adoption for single-serve tropical fruit portions. EU F-Gas Regulation phase-down schedules force processing facilities to abandon hydrofluorocarbon-based refrigeration systems. Hamburg and Rotterdam port clusters serve as consolidation points for Thai and Philippine canned fruit entering European distribution.
Thailand
Mechanized peeling infrastructure in Thai processing facilities reduces labor dependency during peak pineapple harvest windows. BIS standards compliance requirements for Indian-bound exports constrain preservative formulation flexibility. Bangkok and Chonburi industrial zones host vertically integrated canneries supplying year-round volumes to quick-service chains across Asia and Europe.
Philippines
Plantation-to-can vertical integration secures raw material proximity for pineapple processors serving export markets. FSSAI-enforced additive caps in India restrict market access for brands exceeding preservative limits. Mindanao and Luzon growing regions concentrate mechanized coring lines that stabilize throughput during compressed harvest windows.
Brazil
Urbanization in São Paulo and Rio de Janeiro expands cold chain infrastructure enabling shelf-stable tropical fruit distribution to emerging retail channels. ANVISA pharmaceutical and food safety standards govern import requirements for processed fruit products. São Paulo state processing clusters supply papaya and mixed fruit formats to Hispanic demographic channels across South America.
Canned Tropical Fruit Market Vendor Landscape
Player mix skews toward plantation-integrated multinationals with captive raw material supply. Three to five vertically integrated operators control the majority of export volume from Southeast Asian processing clusters. The competitive terrain separates into three archetypes: plantation-owning integrated processors, contract-dependent toll canners, and regional brand marketers. Capacity expansion and backward integration into growing operations represent the dominant competitive moves as processors seek tender eligibility for consolidated food service contracts.
Among the integrated multinationals, Dole Food Company, Del Monte Foods, and Goya Foods occupy distinct positioning vectors. Dole Food Company exemplifies the plantation-integrated archetype through Philippine and Thai operations. Del Monte Foods anchors North American retail presence through long-standing mass-market grocer relationships. Goya Foods represents demographic-channel specialization within Hispanic and Caribbean markets where papaya and mixed fruit preferences concentrate.
| Leading Market Players |
|---|
| Dole Food Company |
| Del Monte Foods |
| The Kraft Heinz Company |
| Bonduelle |
| Conagra Brands |
| Goya Foods |
| Seneca Foods Corporation |
| Rhodes Food Group |
| Siam Pineapple |
| Others |
Supply Flow & Price Mechanics
Mechanized peeling infrastructure at Thai and Philippine processing facilities generates throughput scale that compresses unit costs and establishes price floors for export-grade pineapple. This concentration of processing capacity in Southeast Asian clusters enables year-round supply contracts that food service buyers leverage for volume discounts, while smaller toll canners without captive plantation supply face margin compression during compressed mango harvest windows.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate institutional procurement, linking pineapple and mango pricing to regional harvest benchmarks. Three-tier pricing structure across premium organic lines, standard retail grades, and economy bulk formats separates certified BIS-compliant exports from commodity spot volumes. Cost compression in economy tiers is intensifying because retort pouch substitution in European retail channels erodes metal can premiums. Food service operators exhibit lowest price sensitivity due to menu embedding requirements, while household purchasers in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Inventory carry costs during India and Pakistan mango harvest gaps extend lead times for Alphonso and Kent variety processors. Supply concentrates in Thailand, the Philippines, and India, with mechanized coring lines and thermal processing equipment drawing from steel can sheet, tropical fruit pulp, and syrup concentrate inputs. Single-source vulnerability in plantation-dependent processors without geographic diversification creates tender eligibility risk. Distribution runs through Rotterdam and Hamburg port clusters for European food service, with direct e-procurement platforms disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as food service menu innovation accelerates canned tropical fruit penetration beyond traditional household pantry applications.
For Market Incumbents: Secure backward integration into Mindanao and Luzon growing regions to lock in raw material proximity for pineapple supply. Defend tender eligibility by investing in blockchain-verified traceability systems that major UK and French contract caterers now mandate. Retort pouch substitution in German and Dutch retail channels represents the most pressing substitution threat requiring format diversification. For New Entrants and Emerging Players: Anchor in Nigerian and Kenyan urban distribution where cold chain gaps favor ambient-stable formats and local processing capacity remains scarce. Target convenience store channels in underpenetrated African markets with single-serve pouch configurations. Pursue direct-to-institution e-procurement platforms as the primary go-to-market angle, bypassing established distributor markups. For Investors and Strategic Acquirers: Plantation-integrated processors with FDA and EU organic dual certification command scarcity premia in consolidated food service procurement. Long-term viability hinges on ambient-stable processing investments that reduce energy-intensive cold storage exposure ahead of EU F-Gas phase-down deadlines. Monitor blockchain traceability adoption rates among UK and French contract caterers as the inflection signal for tender eligibility thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growing Operations | Captive pineapple supply from Mindanao plantations locks in year-round throughput for export contracts. |
| Retort Pouch Format Expansion | Aluminum oxide barrier laminates capture German and Dutch supermarket single-serve portion demand. |
| Blockchain Traceability Implementation | Verified origin documentation satisfies UK and French contract caterer procurement mandates. |
| Ammonia-Based Cooling Retrofit | EU F-Gas Regulation compliance ahead of 2030 bans secures European market access. |
| Direct E-Procurement Platform Launch | Digital disintermediation connects Thai processors directly to European food service operators. |
Methodological Framework
Desk research of customs trade databases, FSSAI additive regulation filings, and EU packaging recovery directive texts preceded structured interviews with Thai cannery operations managers, European food service procurement directors, and Indian import compliance officers. Primary fieldwork with Philippine plantation controllers and German retail category buyers was validated against secondary sources including FDA acidified food process filings and BIS nutritional labeling standards. Bottom-up volume modeling from processing facility throughput data was triangulated with top-down demand aggregation across food service and retail channels.
Variance decomposition across product type, packaging format, and end-user segments structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory analysis incorporating mechanized peeling capacity expansion rates, EU F-Gas retrofit timelines, and food service contract renewal patterns. Modeled inputs included seasonal harvest gap durations, retort pouch adoption curves in European retail, and BIS compliance cost escalations for imported brands.
Material uncertainties — raw material seasonality compression, regulatory additive limit revisions, and flexible packaging substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding plantation yield stability and food service procurement consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Cook-In-Bags Market
Packaged Foods
Dried Honey Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Freekeh Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Tortilla Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market