
 Cold and Hot Tool Steel Market | 2026-2036
Cold and Hot Tool Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Cold and Hot Tool Steel Market Insights
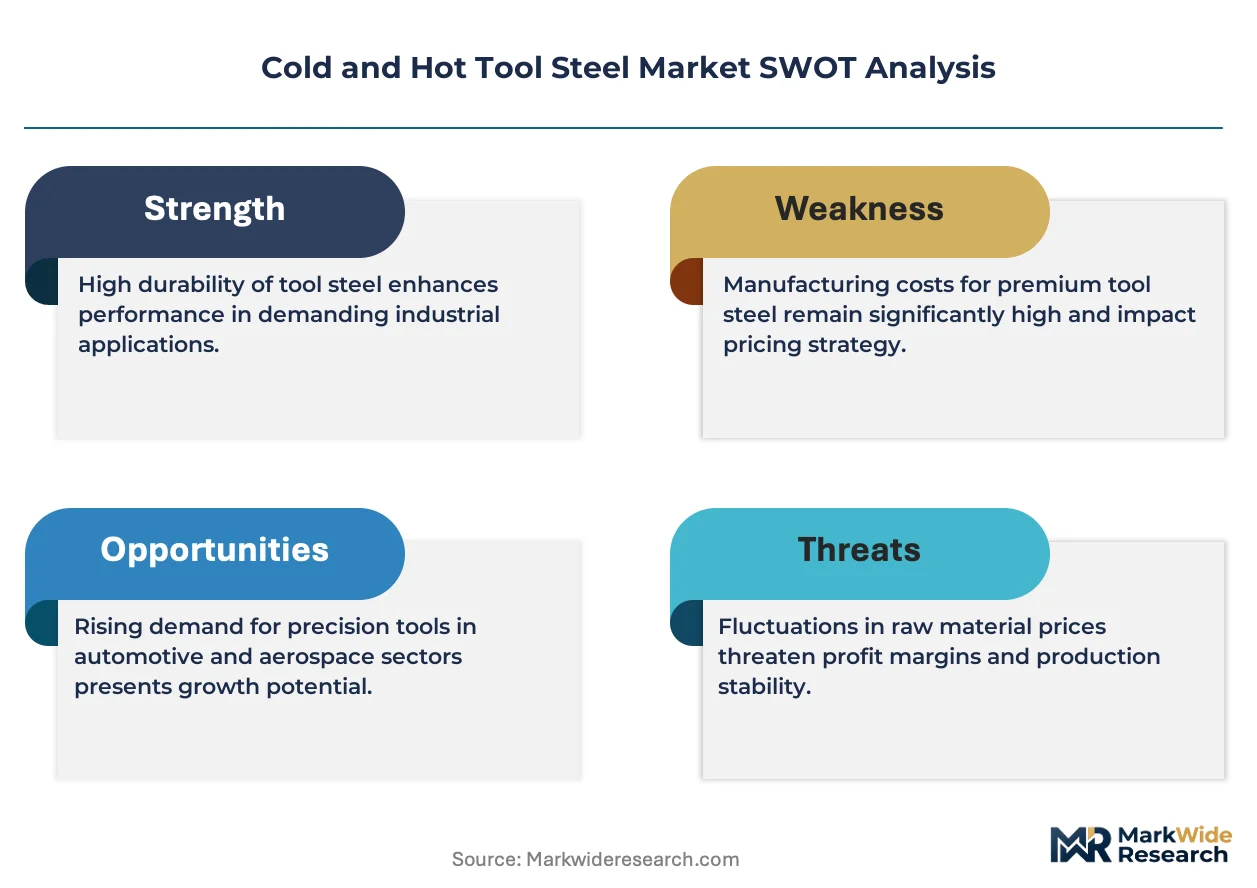
The capital-intensity divergence between integrated mills and specialty converters is reorganizing competitive hierarchies in tool steel supply. voestalpine High Performance Metals leverages its Donawitz steelworks for backward integration into premium billet supply. Bohler Edelstahl Group anchors its position through captive powder metallurgy capacity for high-speed steel grades. Uddeholm AB competes from Hagfors with concentrated investment in vacuum arc remelting for aerospace-qualified material.
Cold and hot tool steels are alloyed ferrous materials formulated for hardness retention above 600°C, with hot-work grades containing chromium, molybdenum, and vanadium for thermal fatigue resistance in die casting and forging operations. High-Speed Steel commands the largest value share due to its irreplaceability in machining superalloys, while Alloy Tool Steel generates the deepest margin pools from custom specifications for precision molding. Die Casting and Forging applications within the metal fabrication sector absorb the majority of hot-work tonnage, with Cold Heading representing the fastest-growing demand node for automotive fastener production.
REACH and RoHS frameworks in Europe restrict hexavalent chromium surface treatments, pushing mills toward trivalent alternatives and vacuum coating compatibility. China's SAMR enforces GB standards for tool steel classification that determine import eligibility and domestic procurement preferences. Stakeholders must monitor evolving alloy surcharge mechanisms and scrap availability constraints as decarbonization mandates reshape electric arc furnace economics.
Market Dynamics
Electric arc furnace economics are tightening under emissions mandates, forcing specialty steel producers to reconfigure scrap sourcing and alloy surcharge mechanisms while aerospace die-forging demand concentrates in Ruhr and Hagfors industrial clusters.
Growth Catalysts
- Aerospace die-forging expansion:Turbine blade production is pulling premium hot-work grades into long-term supply agreements with mill operators in Germany.
- REACH substitution mandates:Hexavalent chromium restrictions are accelerating trivalent surface treatment adoption across European tooling supply chains.
- China's dual carbon enforcement:GB standards for electric arc furnace emissions are filtering domestic capacity toward higher-grade alloy production.
Market Restraints
- Scrap availability constraints:Decarbonization mandates are compressing ferrous scrap flows into specialty converter networks, elevating input cost volatility.
- Supply concentration risk:Vacuum arc remelting capacity clusters in Sweden and Austria, creating single-source dependencies for aerospace-qualified material.
- Powder metallurgy substitution:Additive manufacturing feedstocks are capturing prototype and low-volume die applications from conventional billet routes.
Strategic Opportunities
- India's tooling import gap:BIS certification requirements are creating captive supply openings for integrated mills with vacuum degassing capability.
- Cold heading automotive fasteners:Electric vehicle platform standardization is driving precision fastener demand requiring custom alloy specifications.
- EU Green Deal funding:Carbon border adjustment mechanisms are incentivizing EAF retrofits with hydrogen-ready furnace technology.
Industry Challenges
- Vacuum metallurgy skill scarcity:Qualified technicians for vacuum arc remelting and electroslag refining operations are concentrated in aging workforce pools across Central Europe.
- Aerospace certification timelines:Nadcap and OEM-specific material qualifications require 18-36 month validation cycles that freeze formulation innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold and Hot Tool Steel Market |
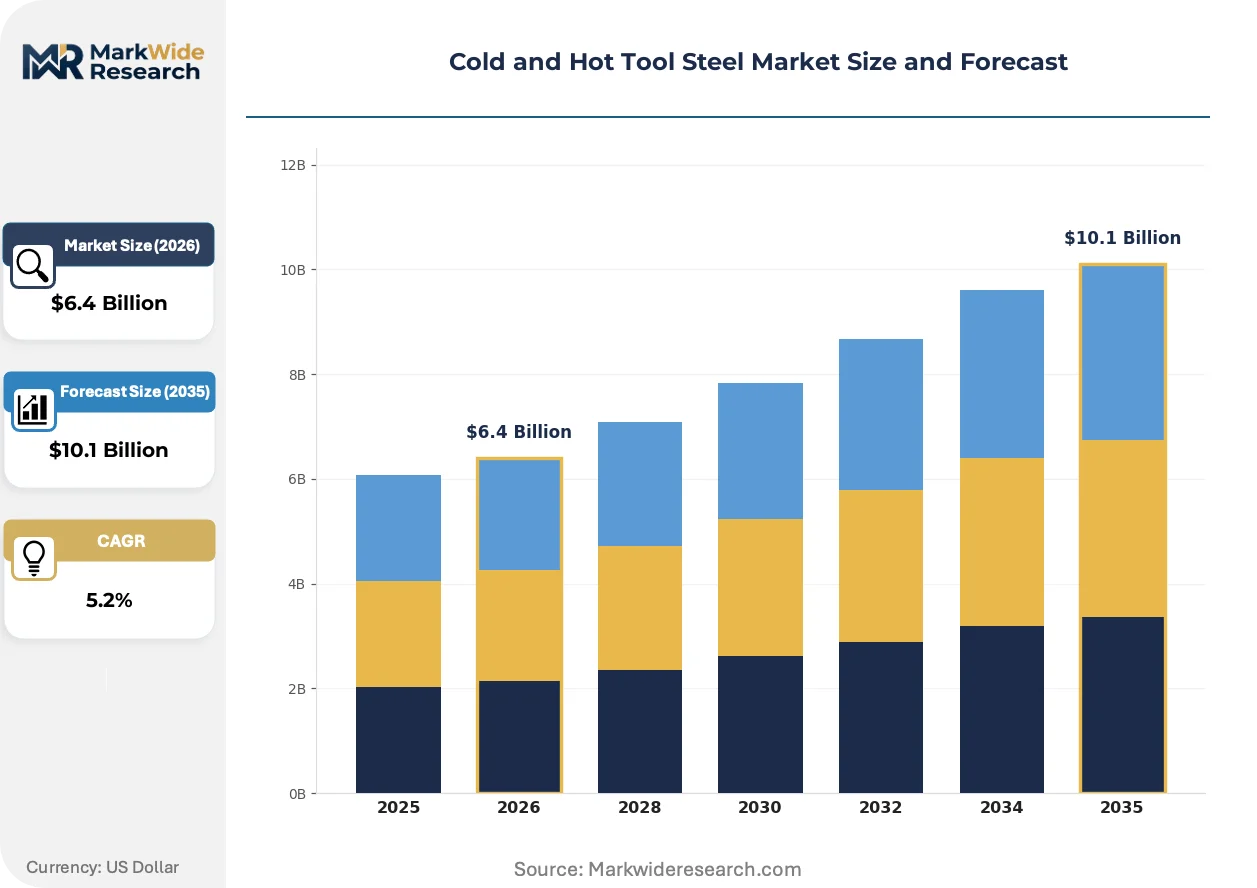
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Steel, Stainless Tool Steel, Carbon Tool Steel, Alloy Tool Steel, Shock-Resistant Steel Application: Cutting Tools, Die Casting, Molding, Forging, Cold Heading, Extrusion End User Industry: Metal Fabrication, Aerospace Manufacturing, Defense Production, Electronics Assembly, Consumer Goods Manufacturing Form: Sheets, Bars, Plates, Wire, Rods, Blocks |
| Companies Covered | voestalpine High Performance Metals, Bohler Edelstahl Group, Uddeholm AB, Daido Steel, Hitachi Metals, Qilu Steel Corporation, ThyssenKrupp Steel AG, Carpenter Technology Corporation, Schmiedewerke Gröditz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold and Hot Tool Steel Market Trends and Innovations
Powder metallurgy high-speed steel is compressing conventional ingot metallurgy margins while regulatory frameworks accelerate coating and recycling technology substitution across European and Asian supply bases.
Near-net-shape powder metallurgy is supplanting conventional forged billet for high-speed steel cutting tools. Japanese machine tool builders are specifying PM grades for superalloy machining applications. This transition is compressing lead times from melt to finished tool by 40 percent while concentrating margin capture among captive powder producers.
REACH Annex XVII restrictions on hexavalent chromium are forcing hard-chrome plating substitution across European die-casting supply chains. Trivalent chromium and physical vapor deposition coatings are gaining specification share in automotive molding applications. German toolmakers are qualifying vacuum-coated alternatives ahead of 2024 enforcement deadlines.
Buyers are consolidating supplier panels around mills with integrated vacuum metallurgy and captive billet supply. Tier-one automotive fastener producers are reducing qualified sources from twelve to four across cold-heading grade portfolios. This concentration is most visible in Germany's Ruhr cluster where backward-integrated producers capture multi-year framework agreements.
Cold and Hot Tool Steel Market Segmentation
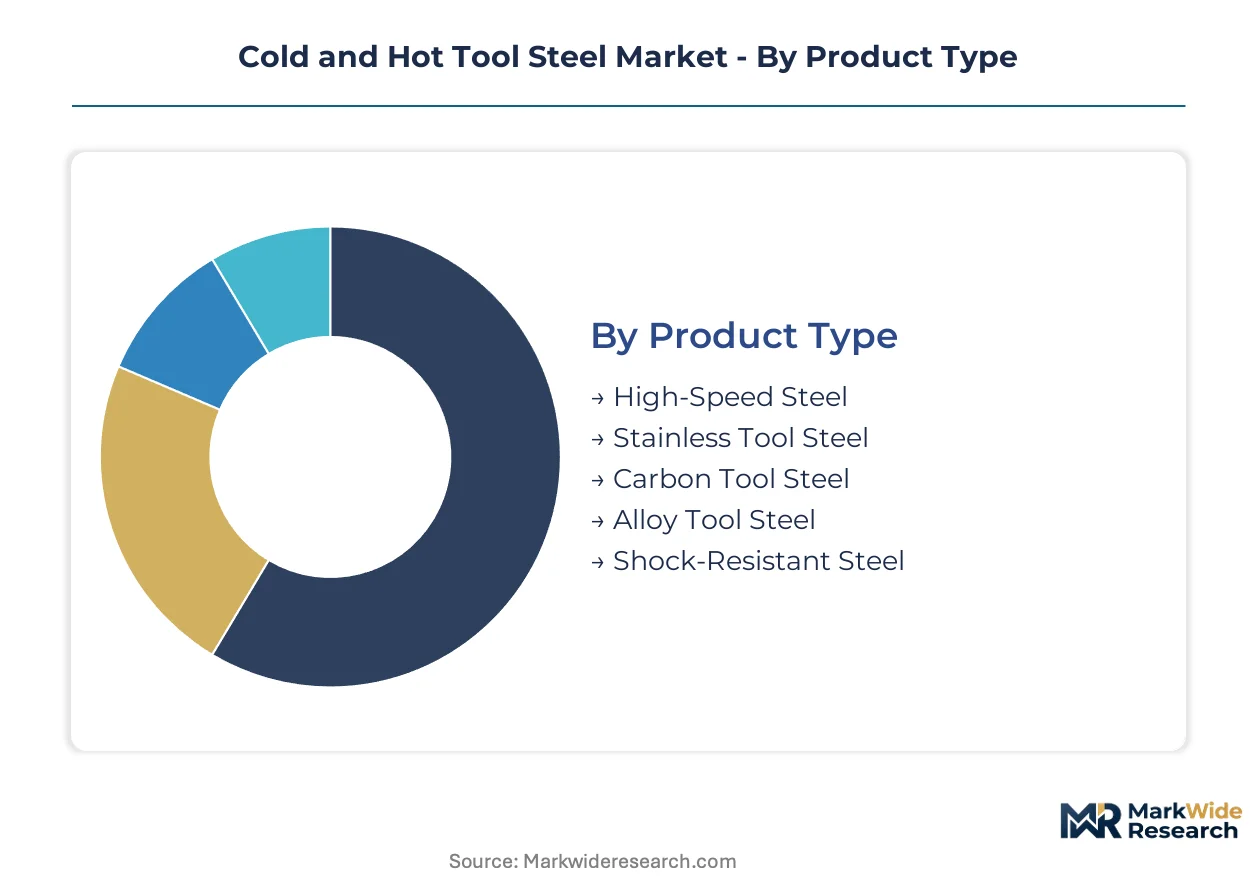
Segmentation in tool steel markets reveals where powder metallurgy and alternative materials exert the strongest displacement pressure. Buyers align specifications to thermal fatigue requirements, surface finish demands, and certification burdens that vary sharply across product categories.
Product Type:
Substitution pressure from cemented carbides and additive manufacturing feedstocks falls unevenly across alloy systems, with carbon grades facing the steepest displacement while high-performance grades defend position through irreplaceable heat resistance.
- High-Speed Steel:Tungsten-molybdenum-vanadium alloy systems retain hardness above 600°C through secondary hardening precipitation. Aerospace turbine blade machining in Germany's Ruhr cluster specifies PM-HSS grades for superalloy cutting, locking in long-term supply agreements despite carbide competition.
- Alloy Tool Steel:Chromium-molybdenum formulations dominate precision molding dies where thermal cycling resistance determines tool life. Automotive fastener cold-heading operations in China's Yangtze River Delta concentrate demand for custom Cr-Mo-V specifications with vacuum-degassed cleanliness.
- Stainless Tool Steel:Martensitic grades with 12-18% chromium serve medical molding and food processing dies requiring corrosion resistance.
- Carbon Tool Steel:Water-hardening grades face accelerating displacement from bimetallic and surface-engineered alternatives in woodworking and low-wear applications.
- Shock-Resistant Steel:Medium-carbon silicon-manganese formulations absorb impact loads in pneumatic tool bits and shear blades for construction equipment manufacturing.
High-Speed Steel anchors the volume base while Alloy Tool Steel gains share at the steepest rate.
Application:
Cost tier stratification separates commodity cutting inserts from precision die systems where material qualification timelines extend 18-36 months.
- Die Casting:Hot-work grades with 5% chromium and vanadium additions resist thermal fatigue in aluminum and magnesium injection molding. German automotive suppliers specify Uddeholm Orvar Supreme for transmission housing dies, prioritizing heat-checking resistance over initial cost.
- Cold Heading:Medium-alloy grades with controlled carbide morphology form precision fasteners for electric vehicle battery trays and structural assemblies. Tier-one suppliers in India's Pune-Ahmedabad corridor qualify captive EAF sources for BIS-certified wire rod.
- Cutting Tools:Indexable inserts and solid round tools consume the majority of high-speed steel powder metallurgy output.
- Molding:Plastic injection and blow molding dies specify P20-type prehardened grades for shorter production runs.
- Forging:Isothermal and hot-die forging of aerospace alloys demands premium hot-work grades with electroslag-refined cleanliness.
- Extrusion:Copper and aluminum profile dies use H13-type grades with nitrided surfaces for abrasive wear resistance.
Die Casting commands the highest value per kilogram while Cold Heading expands most quickly through automotive electrification.
End User Industry:
Customer type determines specification stringency, with aerospace and defense enforcing Nadcap material qualifications that freeze formulation choices for multi-year program lives.
- Aerospace Manufacturing:Turbine disk and blade forging dies require vacuum arc remelted hot-work grades with ultrasonic-tested cleanliness. Sweden's Hagfors cluster supplies qualified material to Safran and Rolls-Royce under decade-long framework agreements.
- Metal Fabrication:General-purpose stamping and forming tools absorb standard grades through distributor channels with minimal technical support.
- Defense Production:Armor plate forming and artillery component forging specifies shock-resistant grades with proven ballistic performance.
- Electronics Assembly:Connector pin and semiconductor leadframe stamping demands precision-ground wire with tight dimensional tolerances.
- Consumer Goods Manufacturing:Appliance and hardware tooling prioritizes cost-optimized grades with acceptable tool life for shorter production campaigns.
Metal Fabrication provides the broadest volume foundation while Aerospace Manufacturing commands the deepest margin pools.
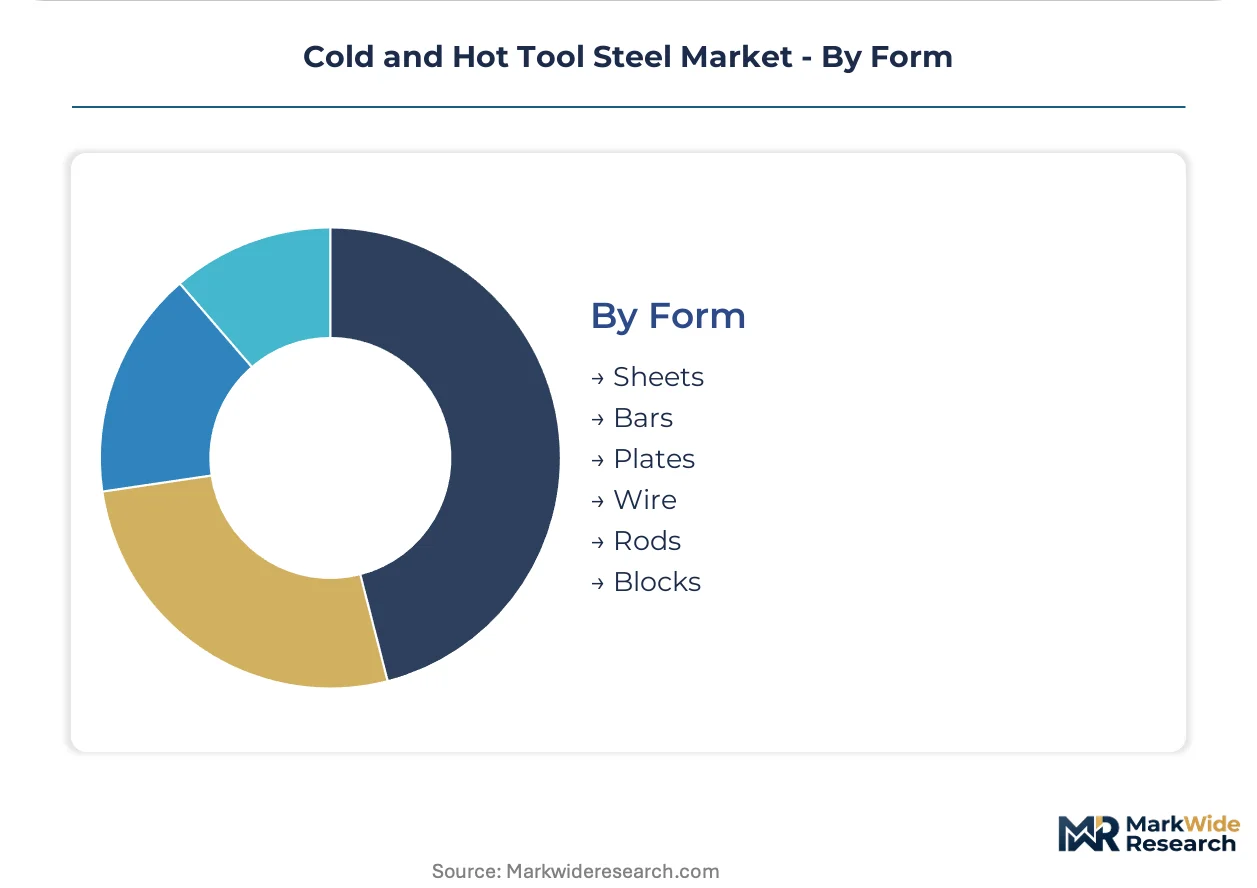
Form:
Supply concentration in long products versus flat products reflects rolling mill configuration and downstream processing economics.
- Bars:Round and square bars dominate cutting tool blank production with diameters from 6mm to 300mm. Austrian and Swedish mills control premium bar supply through integrated forging and heat treatment.
- Plates:Thicknesses from 10mm to 200mm serve mold base and die shoe applications requiring subsequent CNC machining.
- Sheets:Thin-gauge cold-work grades form intricate punch and die components through wire EDM and grinding.
- Wire:Cold-heading quality wire rod requires central segregation control and spheroidized annealing for automotive fastener production.
- Rods:Precision-ground drill rod serves tool and die maintenance with tight diameter tolerances.
- Blocks:Forged rectangular blocks provide near-net-shape starting stock for large forging dies and mold cavities.
Bars constitute the highest shipment volume while Plates capture expanding share through mold standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's Ruhr cluster outstrips Yangtze River Delta producers by double-digit margins on aerospace-qualified grades. Specialty converters in Sweden and Austria command premiums through captive vacuum metallurgy capacity. Scrap availability constraints and emissions mandates are reshaping regional cost structures.
Germany
Turbine blade forging dies for Rolls-Royce and Safran programs pull premium hot-work grades into decade-long supply agreements. REACH Annex XVII hexavalent chromium restrictions accelerate trivalent surface treatment adoption across die-casting supply chains. The Ruhr industrial cluster concentrates specialized high-speed steel production around backward-integrated mills with captive billet supply.
China
Automotive fastener cold-heading operations in the Yangtze River Delta drive custom Cr-Mo-V specification demand with vacuum-degassed cleanliness requirements. SAMR-enforced GB standards for electric arc furnace emissions filter domestic capacity toward higher-grade alloy production. Shandong Peninsula EAF operators face tightening dual carbon goals from MEE that elevate input cost volatility.
Sweden
Vacuum arc remelted hot-work grades with ultrasonic-tested cleanliness serve isothermal and hot-die forging of aerospace alloys. Nadcap material qualifications freeze formulation choices for multi-year program lives with OEMs. The Hagfors cluster supplies qualified material under long-term framework agreements, creating single-source dependencies for aerospace-qualified output.
United States
Defense production armor plate forming and artillery component forging specifies shock-resistant grades with proven ballistic performance. EPA emissions oversight shapes electric arc furnace economics for specialty steel producers reconfiguring scrap sourcing. Carpenter Technology Corporation anchors domestic vacuum metallurgy capability for aerospace and defense material qualifications.
India
Tier-one automotive fastener producers in the Pune-Ahmedabad corridor qualify captive EAF sources for BIS-certified wire rod. PLI scheme incentives for advanced manufacturing create captive supply openings for integrated mills with vacuum degassing capability. Domestic tooling import gaps concentrate demand around certified domestic producers meeting automotive OEM qualification timelines.
Cold and Hot Tool Steel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tool steel supply base. Premium-grade producers with captive vacuum metallurgy and powder metallurgy capacity capture margin pools in aerospace and precision molding applications. Scale-driven integrated mills compete on billet cost and alloy surcharge flexibility for general-purpose grades. Strategic moves concentrate on backward integration into premium billet supply and multi-year framework agreements with tier-one automotive and aerospace OEMs.
Among European specialty converters, voestalpine High Performance Metals, Bohler Edelstahl Group, and Uddeholm AB exemplify the technology-leadership archetype through integrated vacuum metallurgy capacity. These Austrian and Swedish entities occupy positions where captive powder metallurgy and vacuum arc remelting capabilities create qualification barriers for aerospace and defense material supply. Japanese producers Daido Steel and Hitachi Metals represent the Asia-Pacific premium-grade anchor, while Carpenter Technology Corporation sits within the North American defense-qualified supplier tier.
| Leading Market Players |
|---|
| voestalpine High Performance Metals |
| Bohler Edelstahl Group |
| Uddeholm AB |
| Daido Steel |
| Hitachi Metals |
| Qilu Steel Corporation |
| ThyssenKrupp Steel AG |
| Carpenter Technology Corporation |
| Schmiedewerke Gröditz |
| Others |
Pricing and Supply Chain Analysis
Powder metallurgy feedstock substitution for conventional ingot routes simultaneously shifts supply geography toward captive PM producers in Austria and Japan while compressing pricing premiums for standard high-speed steel grades. This displacement concentrates margin capture among vacuum metallurgy-integrated mills while forcing commodity-grade producers into alloy surcharge volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order aerospace-qualified grades from standard catalog offerings. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and vacuum remelt cycles. Cost compression in standard grades is intensifying because scrap availability constraints elevate electric arc furnace input volatility. Tier-one automotive fastener producers show highest price sensitivity through consolidated supplier panels, while aerospace OEMs accept premium positioning for Nadcap-qualified material.
Supply Chain Analysis
Vacuum arc remelting capacity chokepoints in Sweden and Austria tether aerospace-qualified output to single-source dependencies. Geographic supply concentrates in Germany, China, and Sweden for differentiated grades, with India emerging for BIS-certified cold-heading wire. Raw material flows draw from ferrous scrap networks, tungsten concentrates, and ferrovanadium additions. Single-source vulnerability runs through Hagfors and Donawitz clusters for qualified billet. Distribution runs through mill-direct framework agreements for premium grades and distributor channels for general-purpose tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold and hot tool steel market sits at a platform-economics inflection where Nadcap certification interoperability creates winner-take-most dynamics among qualified suppliers. Ecosystem consolidation around multi-year OEM framework agreements is freezing formulation choices and locking out non-integrated competitors.
For Market Incumbents: Fortify captive vacuum metallurgy capacity against powder metallurgy substitution threats from Japanese PM specialists. Deepen backward integration into premium billet supply through EAF retrofits with hydrogen-ready furnace technology. Secure multi-year framework agreements with tier-one automotive fastener producers before India's PLI scheme matures domestic competition.
For New Entrants and Emerging Players: Lead with vacuum degassing capability targeting India's BIS-certified wire rod gap in the Pune-Ahmedabad corridor. The most penetrable segment sits in cold-heading grades for electric vehicle platform standardization. Go-to-market leverage rests on qualifying captive EAF sources ahead of domestic incumbent capacity expansion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty steel converters lacking powder metallurgy integration. Long-term viability favors platforms with Nadcap-qualified vacuum arc remelting and captive aerospace customer relationships. The signal to watch is OEM consolidation of supplier panels from twelve to four qualified sources across grade portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premium Billet Supply | voestalpine's Donawitz steelworks secures captive input for aerospace-grade hot-work steel. |
| Powder Metallurgy Capacity Expansion | Bohler Edelstahl Group defends margin pools through captive PM-HSS for superalloy machining. |
| Long-term Supply Agreement with OEMs | Uddeholm AB locks decade-long frameworks with Safran and Rolls-Royce for turbine blade dies. |
| Hydrogen-Ready EAF Retrofit | Ruhr cluster producers capture EU Green Deal funding for carbon border adjustment compliance. |
| Certification Investment for BIS Compliance | Integrated mills with vacuum degassing qualify for India's automotive fastener import substitution. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at specialty steel converters, procurement leads at Tier 1 automotive fastener producers, and technical R&D directors at vacuum metallurgy facilities; and secondary validation through customs and trade data, SEC 10-K filings of listed producers, and ECHA REACH enforcement documentation. Bottom-up triangulation against top-down production capacity estimates anchored volume and value outputs.
Across the analysis window, forecasts modeled product type segmentation by alloy system, application segmentation by thermal fatigue requirement, and end-user segmentation by certification burden. CAGRs derived from production capacity expansion schedules, OEM qualification timelines, and scrap availability projections. Industry-specific inputs included electric arc furnace emissions compliance costs and powder metallurgy penetration curves in cutting tool specifications.
Underlying assumptions cover sustained aerospace production rates and REACH enforcement timelines, with deviation risk concentrated in China's dual carbon policy stringency and ferrous scrap flow disruptions. Practitioners should keep alternative scenarios live as hydrogen-ready furnace economics and additive manufacturing feedstock substitution evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wood-Burning Tool Market
Tools
Belt File Sander Market
Tools
3D Milling Machines Market
Tools
Global Cutting Discs Market
Tools
Masonry Cleaners Market
Tools
Hand and Power Tools Market
Tools
Deburring Tool Market
Tools
Land Survey Equipment Market
Tools
Europe Paint Spray Guns Market
Tools
Grinding Machines Market
Tools
Global Scarifiers Market
Tools
US Power Tools Market
Tools
Tool Pliers Market
Tools
Europe Power Tools Market
Tools
Post Drivers Market
Tools
Digital Laser Levels Market