
 Global Cannabis Market | 2026-2036
Global Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cannabis Market Analysis
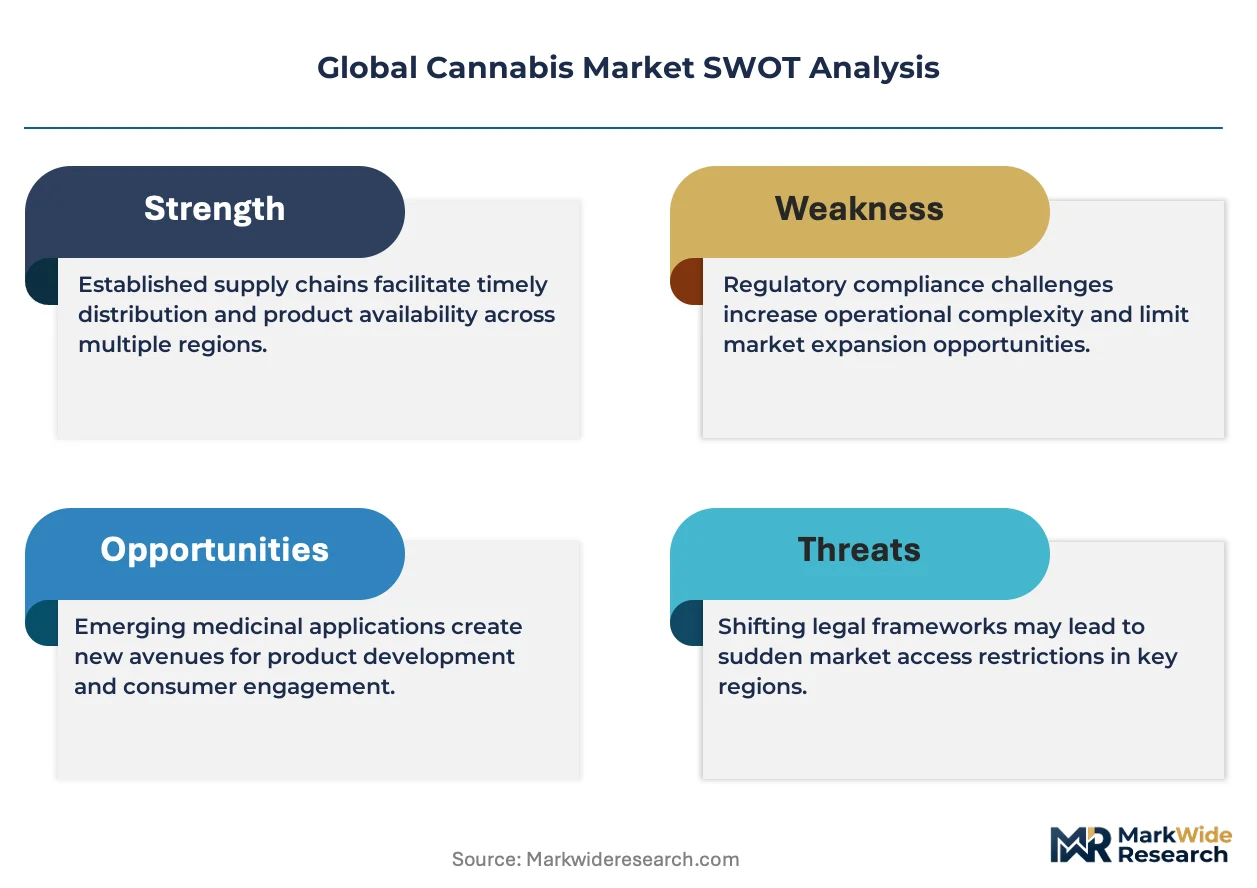
The gap between premium craft flower and bulk commodity biomass is broadening as testing protocols and terpene profiling create measurable quality tiers. Curaleaf leverages multi-state retail footprints to sustain volume advantages across regulated US jurisdictions. Tilray Brands anchors its position through pharmaceutical-grade cultivation standards that differentiate medical supply contracts. Green Thumb Industries competes on operational density in limited-license state markets.
Cannabis comprises the dried flowering tops, resinous extracts, and derivative formulations of Cannabis sativa and Cannabis indica plants, containing phytocannabinoids such as delta-9-tetrahydrocannabinol and cannabidiol that interact with mammalian endocannabinoid receptors for therapeutic or psychoactive effect. Flower retains dominant volume share in mature recreational markets where combustion and vaporization remain preferred administration routes, while oil extracts capture expanding medical applications requiring precise dosing standardization. Edibles represent the fastest-growing product type as beverage and confectionery formats attract new consumer cohorts seeking non-inhalation alternatives.
US state-level frameworks operate alongside FDA prohibition of interstate commerce in THC products, creating fragmented compliance architectures that shape facility location and capital deployment. Health Canada's Cannabis Act establishes production standards that Aurora Cannabis navigates for international medical export eligibility. Germany's BfArM and Australia's TGA exemplify evolving medical access pathways that stakeholders must monitor as import substitution policies mature.
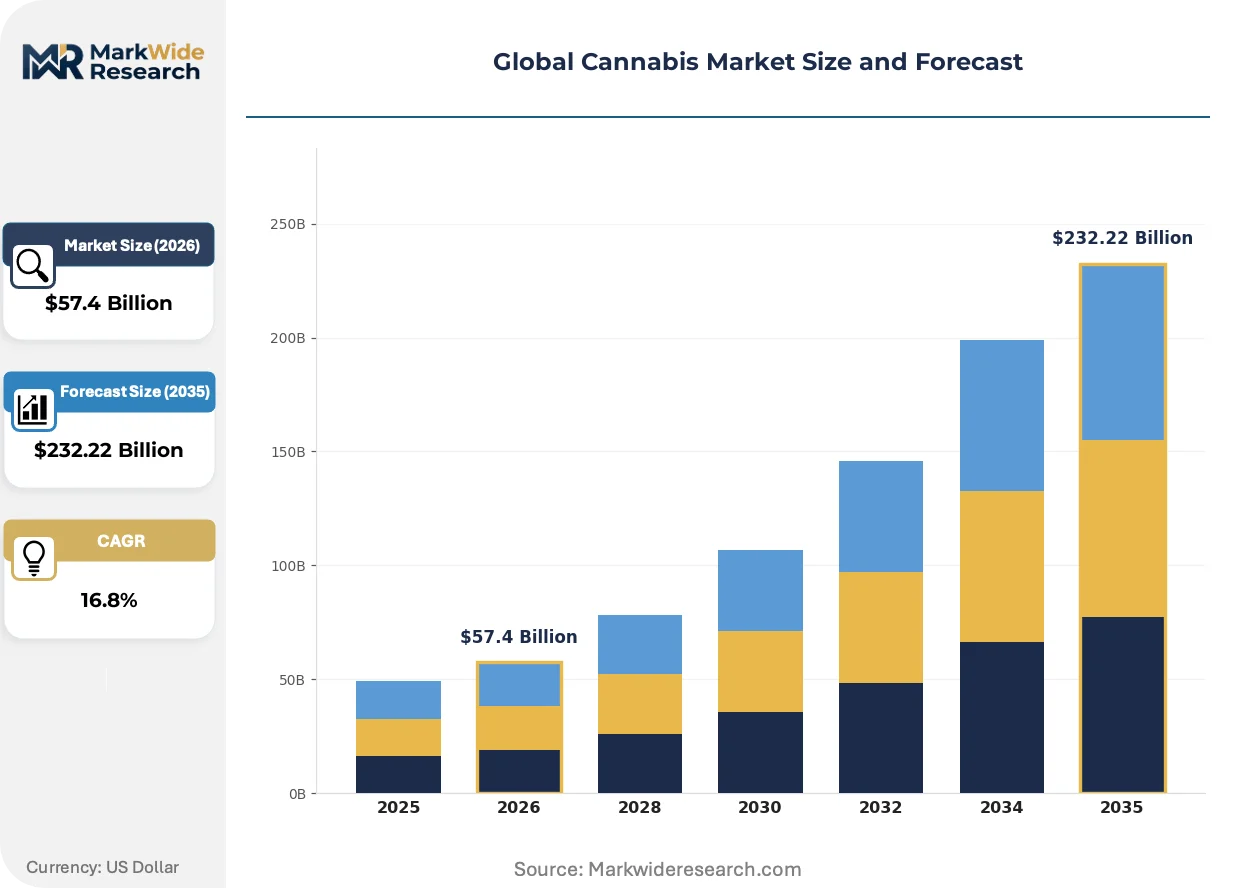
Market Dynamics
The divergence between pharmaceutical-grade cannabinoid production and unregulated hemp-derived alternatives is fragmenting compliance architectures and forcing capital toward GMP-certified facilities.
Growth Catalysts
- Germany's BfArM domestic cultivation licensing:The framework accelerates supply chain localization and reduces import dependency for medical-grade flower. Domestic producers gain pricing leverage against Canadian and Dutch imports.
- Pain management API demand:Pharmaceutical manufacturers are expanding cannabinoid sourcing for analgesic formulations. Synthetic biology platforms now enable consistent THC and CBD production at pharmaceutical purity standards.
- California's vertically integrated dispensary networks:Concentrated demand in limited-license jurisdictions creates operational density advantages. Retail-cultivation integration captures margin compression points in distribution.
Market Restraints
- US FDA interstate commerce prohibition:The ban on THC product movement across state lines forces redundant facility construction. Capital efficiency suffers as producers replicate infrastructure in each regulated jurisdiction.
- Energy-intensive indoor cultivation:Climate-controlled growing facilities face escalating electricity costs and carbon accounting pressure. Grid dependency in prohibition-era legacy markets compounds operational vulnerability.
- Illicit market price anchoring:Unregulated supply in federal prohibition environments caps legal pricing power. Tax-loaded retail products compete against untested but cheaper alternatives.
Strategic Opportunities
- Australia's TGA medical access expansion:The Special Access Scheme creates import substitution potential for GMP-certified exporters. Patient enrollment growth outpaces domestic cultivation capacity.
- Beverage and confectionery format innovation:Non-inhalation delivery systems attract new consumer cohorts seeking discretion and dosing precision. Nanoemulsion technology enables rapid onset and predictable bioavailability.
- EU Green Deal agricultural incentives:Carbon-neutral greenhouse construction qualifies for sustainable farming subsidies. Renewable energy integration reduces operational cost exposure.
Industry Challenges
- Phytocannabinoid analytical chemistry talent scarcity:Terpene profiling and contaminant testing require specialized laboratory expertise. Compensation inflation in quality assurance functions strains mid-tier producers.
- Multi-jurisdiction license maintenance complexity:Divergent state and national compliance timelines create administrative overhead. Renewal synchronization failures risk operational suspension.
- Legacy seed-to-sale system integration:Proprietary tracking platforms resist interoperability with emerging ERP standards. Data migration costs burden scaling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cannabis Market |
| Market Size in 2026 | $57.4 Billion |
| Market Size in 2035 | $232.22 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Oil, Edibles, Capsules Application: Medical, Recreational, Therapeutic, Personal Care Customer Type: Individual Consumers, Dispensaries, Pharmacies, Enterprises Distribution Channel: Online, Retail Stores, Specialty Shops, Direct Sales |
| Companies Covered | Curaleaf, Trulieve, Green Thumb Industries, Tilray Brands, Canopy Growth Corporation, Cresco Labs, Aurora Cannabis Inc., Verano Holdings, Ascend Wellness Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cannabis Market Emerging Trajectories
Automation, regulatory harmonization pressures, and consumption format diversification are compressing traditional competitive advantages while opening new value capture points across the supply chain.
Controlled-environment agriculture robotics is automating transplanting, defoliation, and harvesting operations in large-scale cultivation facilities. North American multi-state operators are deploying these systems to reduce labor cost volatility and improve batch consistency. The technology is compressing unit economics for biomass production while raising capital barriers for craft competitors.
Health Canada's GMP certification requirements for international medical exports are tightening quality assurance protocols. Producers seeking EU market access must demonstrate pharmaceutical-grade manufacturing standards that exceed domestic recreational requirements. Aurora Cannabis and peer exporters are restructuring cultivation workflows to maintain TGA and EMA eligibility.
Buyer preference is rotating toward solventless extraction methods that preserve native terpene profiles. Rosin and ice-water hash formats are displacing hydrocarbon-extracted concentrates in premium California and Colorado retail channels. This shift favors cultivators with genetics libraries optimized for trichome density rather than bulk yield alone.
Global Cannabis Market Segmentation
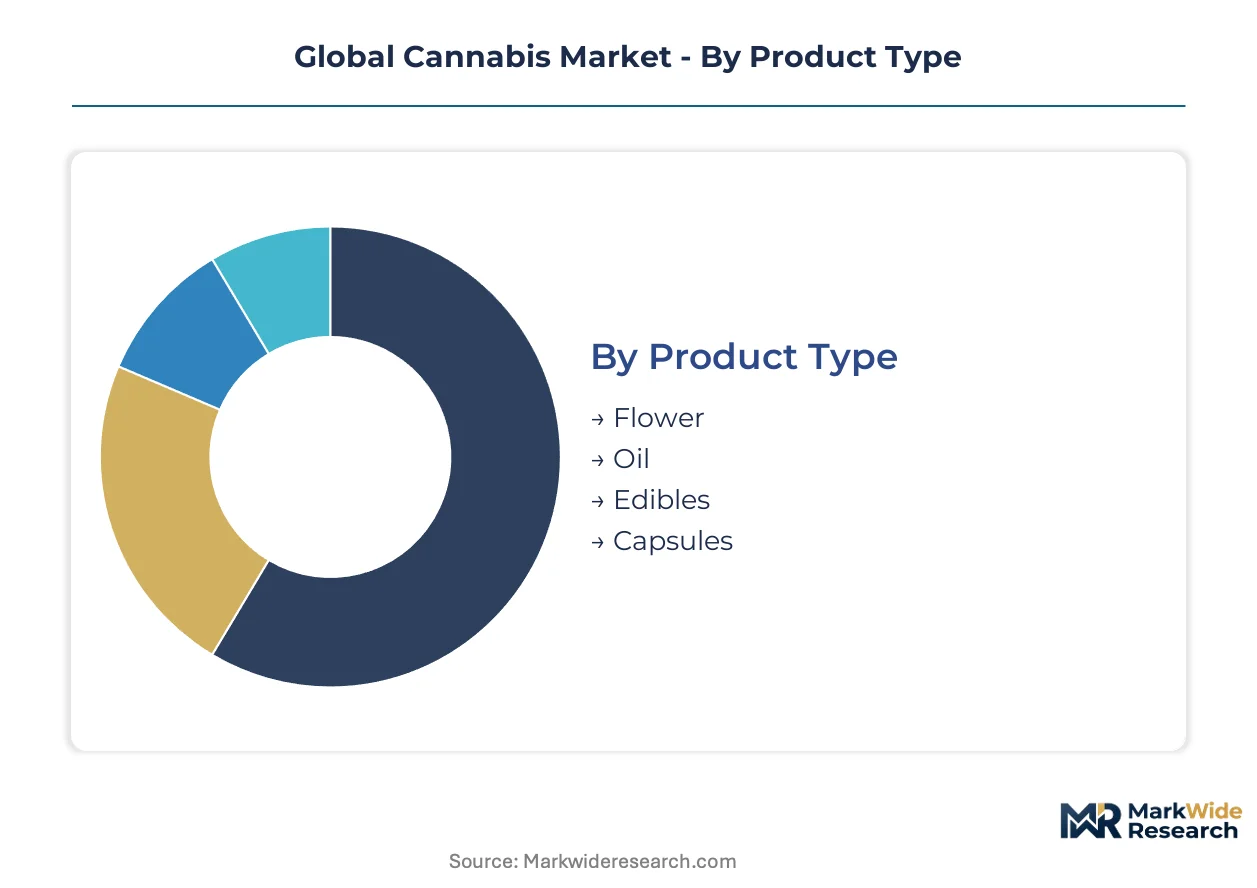
Cannabis segmentation reflects divergent regulatory pathways that fragment production standards and channel access. Product formats carry distinct compliance burdens that shape facility investment and margin structures across jurisdictions.
Product Type:
Flower commands Health Canada GMP certification for medical exports, while oil extracts face FDA pharmaceutical-grade scrutiny in investigational drug pathways. Edibles navigate dual food-safety and cannabinoid-potency testing regimes.
- Flower:Dried inflorescences with intact trichome structures delivering phytocannabinoid profiles through combustion or vaporization. California's vertically integrated dispensary networks concentrate demand for craft-tier genetics with verified terpene assays. BfArM import substitution policies favor domestic German cultivation for pharmaceutical-grade supply.
- Oil:Lipid-soluble concentrates standardized for cannabinoid potency in tincture, capsule, or vaporizer cartridge formulations. Australia's TGA Special Access Scheme drives import demand for GMP-certified oil extracts as patient enrollment outpaces domestic capacity.
- Edibles:Food-matrix products incorporating nanoemulsion technology for enhanced bioavailability.
- Capsules:Gelatin or vegetable-shell delivery systems enabling precise milligram dosing for medical protocols.
Leading the category by volume: Flower. Growing fastest: Edibles.
Application:
Medical use requires named regulator approvals that recreational channels bypass entirely. Therapeutic positioning occupies a regulatory gray zone between pharmaceutical claims and wellness marketing.
- Medical:Physician-authorized cannabinoid therapy for chronic pain, epilepsy, or chemotherapy-induced nausea requiring prescription documentation. Germany's statutory health insurance reimbursement for medical cannabis concentrates demand with BfArM domestic licensing reducing import dependency.
- Recreational:Adult-use consumption in state-legal frameworks without therapeutic indication claims. California and Colorado retail density creates competitive pressure on pricing as license saturation progresses.
- Therapeutic:Over-the-counter wellness positioning with structure-function claims stopping short of disease treatment.
- Personal Care:Topical formulations leveraging anti-inflammatory cannabinoid properties in cosmetic regulatory pathways.
Medical applications capture the highest per-gram pricing. Recreational channels drive absolute volume throughput.
Customer Type:
Procurement authority varies sharply by customer class, with pharmacies requiring wholesale distribution licenses that individual consumers bypass through direct retail access.
- Individual Consumers:End-users purchasing through licensed retail or delivery services for personal consumption. California's delivery-legal municipalities enable direct-to-consumer logistics models unavailable in pharmacy-restricted jurisdictions.
- Dispensaries:Vertically integrated retail-cultivation operators capturing margin compression points in limited-license states. Operational density in Illinois and New Jersey creates competitive moats against single-license competitors.
- Pharmacies:German and Australian distribution points for medical cannabis requiring BfArM or TGA wholesale authorization.
- Enterprises:Bulk procurement for product manufacturing, clinical research, or ingredient supply.
Dispensaries dominate US transaction volume. Pharmacies anchor medical-market value capture.
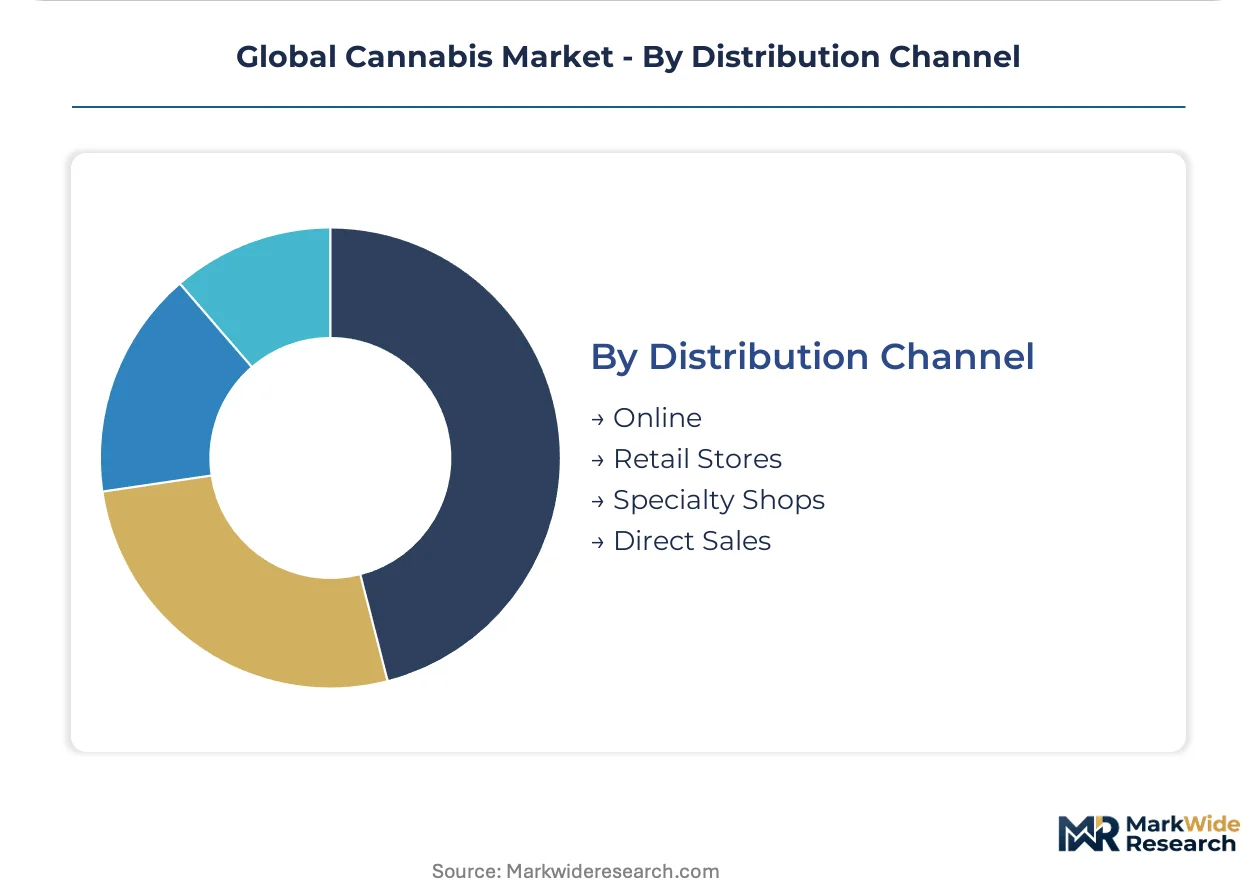
Distribution Channel:
Channel selection determines tax collection points and age-verification protocols that shape compliance cost structures.
- Online:E-commerce platforms with age-gating and prescription upload requirements for medical orders. California's Bureau of Cannabis Control regulates delivery logistics separately from brick-and-mortar licensing.
- Retail Stores:Physical dispensaries with point-of-sale seed-to-sale tracking integration. Canadian provincial retailers operate as Crown monopolies or licensed private operators under Health Canada distribution standards.
- Specialty Shops:Focused retailers emphasizing craft genetics or consumption accessories alongside core product.
- Direct Sales:Manufacturer-to-patient or manufacturer-to-processor transactions bypassing wholesale tiers.
Retail stores generate the highest per-location revenue concentration. Online channels are expanding most quickly in delivery-legal municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's vertically integrated dispensary networks anchor North American transaction density, while regulatory divergence across national frameworks fragments supply chain architecture into jurisdiction-specific operating models.
United States
State-legal recreational frameworks in California, Colorado, and Illinois drive absolute volume throughput. FDA prohibition of interstate THC commerce forces redundant facility construction in each regulated jurisdiction. Multi-state operators concentrate operational density in limited-license markets like New Jersey and Connecticut.
Germany
BfArM domestic cultivation licensing accelerates supply chain localization for medical-grade flower. Statutory health insurance reimbursement concentrates demand through pharmacy distribution channels. Domestic producers in North Rhine-Westphalia and Bavaria gain pricing leverage against Canadian and Dutch imports.
Canada
Health Canada's Cannabis Act establishes production standards for international medical export eligibility. GMP certification requirements tighten quality assurance protocols for EU and Australian market access. Aurora Cannabis and peer exporters restructure cultivation workflows to maintain TGA and EMA eligibility from Ontario and British Columbia facilities.
Australia
TGA Special Access Scheme creates import substitution potential for GMP-certified exporters as patient enrollment outpaces domestic cultivation capacity. Sydney and Melbourne clinical networks drive physician-authorized therapy adoption. Queensland greenhouse construction expands to capture renewable energy integration subsidies.
Netherlands
Office of Medicinal Cannabis maintains government monopoly on medical flower production for domestic and export supply. Rotterdam and Groningen cultivation clusters serve German and Italian import demand. Regulatory harmonization pressures with EU pharmaceutical standards reshape facility investment timelines.
Global Cannabis Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and terpene-profile dimensions. The vendor base organizes into three tiers: pharmaceutical-grade exporters, multi-state retail-cultivation integrators, and craft-tier genetic specialists. Consolidation pressures favor scale-driven operators with redundant license portfolios across fragmented US state frameworks. Dominant competitive moves include backward integration into captive cultivation supply and geographic license accumulation in limited-jurisdiction markets.
Within the multi-state retail-cultivation tier, Curaleaf and Green Thumb Industries occupy positions exemplifying operational density strategies in limited-license state markets. Tilray Brands anchors the pharmaceutical-grade export archetype through Health Canada GMP certification maintenance. These three entities represent contrasting pathways through regulatory fragmentation: retail footprint scale, operational concentration, and international medical compliance.
| Leading Market Players |
|---|
| Curaleaf |
| Trulieve |
| Green Thumb Industries |
| Tilray Brands |
| Canopy Growth Corporation |
| Cresco Labs |
| Aurora Cannabis Inc. |
| Verano Holdings |
| Ascend Wellness Holdings |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification ladders create a three-tier pricing structure across premium, standard, and economy levels that fragments procurement authority between pharmacy reimbursement channels and unregulated retail. GMP-certified German and Canadian producers command sustained premiums through BfArM and Health Canada validation, while California's vertically integrated dispensary networks compress margins via operational density advantages.
Pricing Analysis
Yield-per-square-meter anchors value-based pricing for indoor cultivation facilities competing on batch consistency and terpene assay verification. Certification grade and volume scale drive price differentiation between craft-tier genetics and bulk biomass. Cost compression in commodity flower is intensifying because illicit market price anchoring caps legal tax-loaded retail. Dispensary procurement teams exhibit highest price sensitivity; pharmaceutical buyers prioritize assay reliability over unit cost.
Supply Chain Analysis
Germany's BfArM domestic cultivation licensing is reshaping sourcing patterns for medical-grade flower across European pharmacy channels. Supply concentrates in Canada, the Netherlands, and Germany for GMP-certified exports, while California and Colorado anchor North American recreational throughput. Cultivation draws from specialized genetics libraries, climate-controlled infrastructure, and pharmaceutical-grade extraction equipment. Single-source vulnerability runs through proprietary seed-to-sale tracking platforms that resist ERP interoperability. Distribution runs through pharmacy wholesale tiers in medical markets and vertically integrated retail-cultivation networks in recreational jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Health Canada GMP certification creates a barrier-to-entry moat for international medical exporters. Regulatory fragmentation across US state frameworks compounds capital requirements for multi-jurisdiction operators.
For Market Incumbents: Cement operational density advantages in limited-license states through license portfolio accumulation and backward integration into captive cultivation supply. Aurora Cannabis and Tilray Brands demonstrate how pharmaceutical-grade certification investment defends against unregulated hemp-derived substitute pressure. Channel control through dispensary ownership captures margin compression points. For New Entrants and Emerging Players: Enter via Australia's TGA Special Access Scheme where patient enrollment growth outpaces domestic cultivation capacity. Germany's statutory health insurance reimbursement creates pharmacy-distribution white space for GMP-certified exporters. Nanoemulsion technology partnerships offer a go-to-market angle for beverage and confectionery format innovation. For Investors and Strategic Acquirers: Re-rating potential sits with multi-state operators holding redundant license portfolios across fragmented US jurisdictions given federal rescheduling momentum. Long-term viability favors scale-driven players with operational density in Illinois, New Jersey, and Connecticut. Monitor DEA rescheduling proceedings as the inflection signal for interstate commerce prohibition relief.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | Health Canada and EMA validation unlocks German pharmacy reimbursement and Australian TGA import eligibility. |
| Backward Integration into Cultivation | Captive supply of pharmaceutical-grade flower secures margin control against BfArM domestic substitution policies. |
| Nanoemulsion Technology Licensing | Rapid-onset beverage formulations attract new consumer cohorts seeking non-inhalation alternatives with predictable bioavailability. |
| Multi-State License Accumulation | Redundant regulatory footprints in limited-license jurisdictions build operational density moats against single-market competitors. |
| EU Green Deal Compliance Program | Carbon-neutral greenhouse construction qualifies for agricultural subsidies while reducing grid-dependency exposure. |
Methodological Framework
Document review covered Health Canada GMP guidance documents, BfArM licensing frameworks, TGA Special Access Scheme protocols, FDA enforcement discretion letters, and state-level cannabis control regulations, complemented by interviews with multi-state operator executives, pharmaceutical cultivation facility managers, pharmacy wholesale procurement leads, and regulatory affairs specialists. Secondary validation drew from customs trade data, SEC 10-K filings, and provincial retail sales disclosures. Bottom-up cultivation capacity modeling and top-down demand segmentation triangulated market sizing.
Segmentation outputs across product type, application, customer class, and distribution channel fed into a quantitative framework spanning the projection horizon. CAGRs were derived from patient enrollment trajectories, license issuance rates, and retail transaction velocity. Industry-specific forecast inputs included electricity cost curves for indoor cultivation and statutory health insurance reimbursement expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under federal rescheduling acceleration or interstate commerce prohibition enforcement shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Concentrate Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Europe Medical Cannabis Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market