
 Asia-Pacific Cannabidiol (CBD) Market | 2026-2036
Asia-Pacific Cannabidiol (CBD) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cannabidiol (CBD) Market Outlook
Buyer concentration among healthcare providers is expanding as hospital networks and specialty clinics consolidate procurement decisions across Australia and Southeast Asia. Aurora Cannabis Inc. leverages its GMP-certified cultivation infrastructure to supply pharmaceutical-grade extracts to licensed distributors. Canopy Growth Corporation anchors its regional position through partnerships with local manufacturers in Thailand and Australia. Elixinol Wellness differentiates via vertically controlled supply chains spanning organic hemp sourcing to finished tincture production.
Cannabidiol refers to a non-psychoactive phytocannabinoid extracted primarily from Cannabis sativa L., typically comprising standardized concentrations of CBD alongside trace tetrahydrocannabinol levels below regulatory thresholds, and serves therapeutic applications spanning anxiolytic, anti-inflammatory, and anticonvulsant indications. Oils and tinctures dominate current revenue pools due to established clinical dosing protocols and physician familiarity, while edibles represent the fastest-growing product type as food safety frameworks mature across the region. Healthcare applications command premium pricing through prescription channels, whereas personal care segments compete on brand positioning and retail shelf presence.
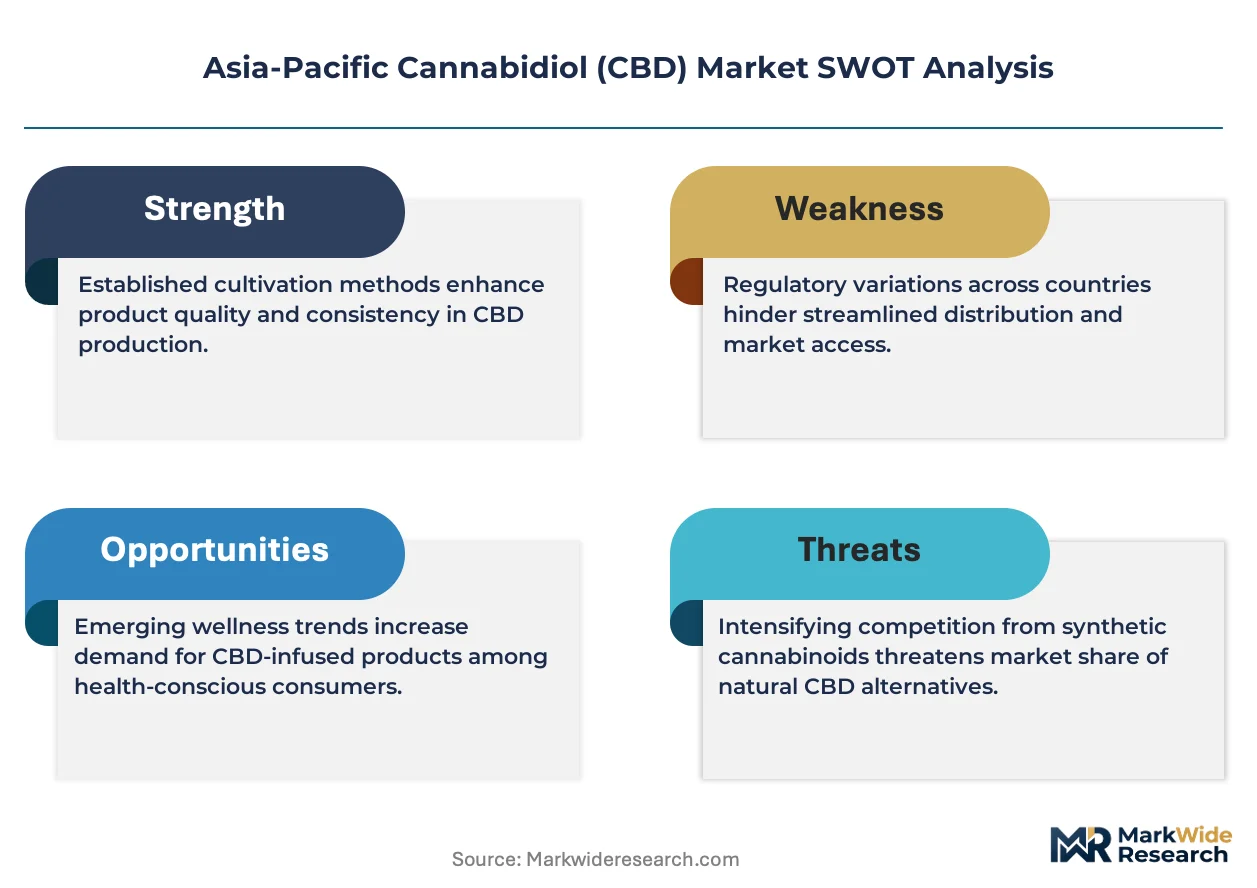
Australia's Therapeutic Goods Administration, Thailand's Food and Drug Administration, and South Korea's Ministry of Food and Drug Safety collectively determine market access through divergent scheduling classifications and import licensing requirements. The TGA's down-scheduling of low-dose CBD to Schedule 3 permits over-the-counter pharmacy sales, while Thailand's FDA manages cannabis extracts through controlled narcotics frameworks with gradual liberalization pathways. Stakeholders must monitor regulatory divergence across jurisdictions where a single product classification may trigger prescription requirements in one market and cosmetic registration in another.
Market Dynamics
Australia's Therapeutic Goods Administration down-scheduling of low-dose CBD products to Schedule 3 has triggered a structural reordering of distribution channels, shifting volume from specialty clinics toward pharmacy networks and forcing manufacturers to reconfigure packaging, dosing, and patient education protocols.
Growth Catalysts
- Thailand's FDA liberalization pathway:The controlled narcotics framework's gradual relaxation permits pharmaceutical manufacturers to register CBD extracts for specific therapeutic indications, opening hospital procurement channels.
- Medical cannabis clinic clustering:Concentration of prescribing infrastructure near major hospital networks in Bangkok and Australia's eastern states reduces patient access friction and accelerates prescription volumes.
- GMP-certified cultivation infrastructure:Pharmaceutical-grade extraction capabilities enable supply contracts with licensed distributors that standard agricultural processors cannot fulfill.
Market Restraints
- Import licensing fragmentation:Divergent scheduling classifications across Australia's TGA, Thailand's FDA, and South Korea's MFDS force manufacturers to maintain separate product formulations and compliance dossiers for each jurisdiction.
- Organic hemp supply concentration:Sourcing of certified organic raw material clusters in specific cultivation zones, creating geographic dependency and input cost volatility during seasonal disruptions.
- THC threshold technical limitation:Trace tetrahydrocannabinol levels must remain below regulatory thresholds, requiring sophisticated chromatographic separation that elevates processing costs relative to broad-spectrum alternatives.
Strategic Opportunities
- South Korea's MFDS regulatory tailwind:The ministry's cautious but progressive stance on cannabinoid research creates first-mover advantage for clinical trial sponsors establishing local evidence bases.
- Edibles as emerging application:Food safety framework maturation across Southeast Asia permits format diversification beyond oils and tinctures into shelf-stable consumer products.
- Personal care channel innovation:Cosmetic registration pathways in several Asia-Pacific jurisdictions allow topical CBD products to bypass prescription requirements entirely, accessing retail shelf presence.
Industry Challenges
- Pharmaceutical formulation talent scarcity:Shortage of professionals experienced in cannabinoid stability, bioavailability optimization, and controlled-substance handling within GMP environments.
- Multi-jurisdiction compliance capex intensity:Simultaneous maintenance of separate manufacturing lines, labeling systems, and quality documentation for prescription, pharmacy, and cosmetic regulatory tracks.
- Standardization delays across pharmacopeias:Absence of harmonized reference standards for CBD purity and impurity profiling complicates batch release and cross-border shipment acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cannabidiol (CBD) Market |
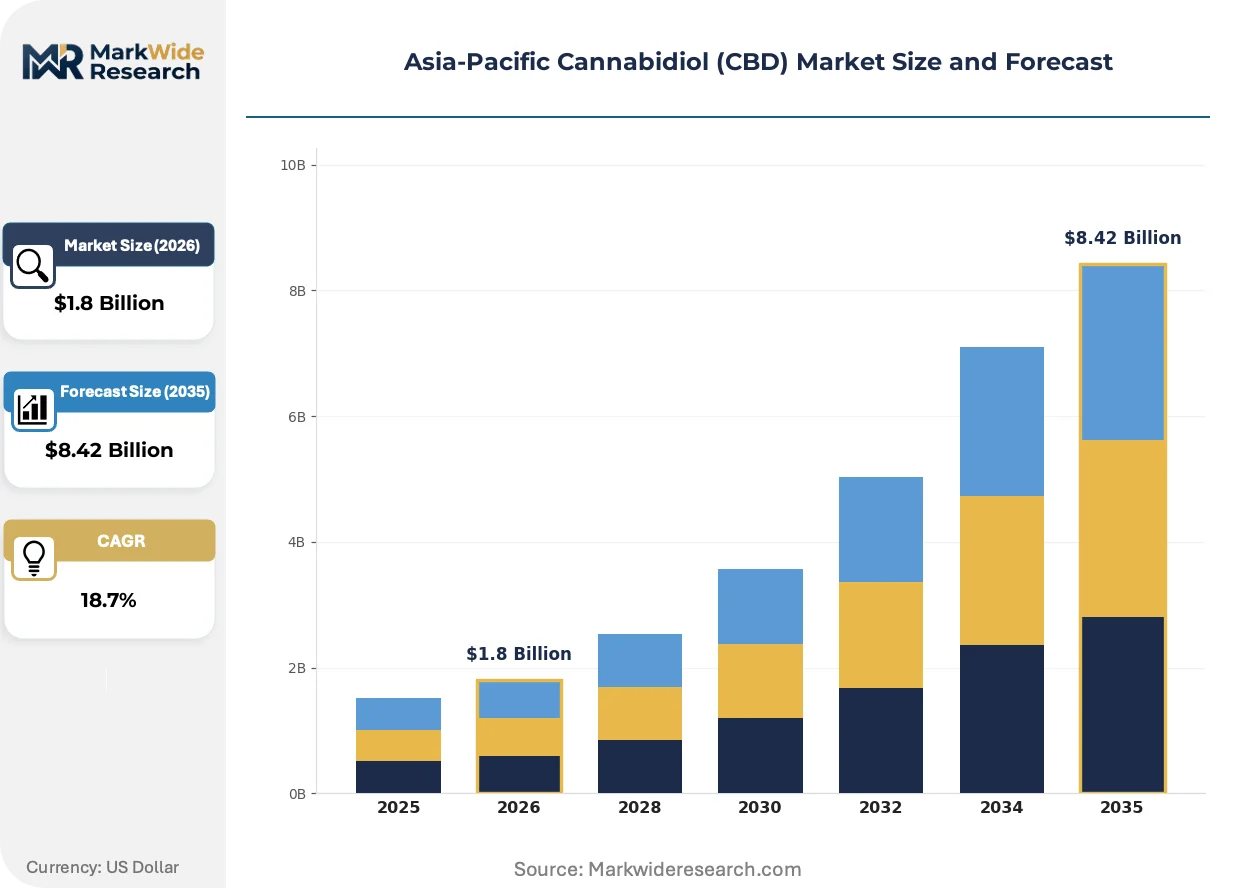
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Tinctures, Capsules, Edibles Application: Healthcare, Personal Care, Food & Beverage, Pet Care Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores End User: Consumers, Retailers, Manufacturers, Healthcare Providers |
| Companies Covered | Althea Group, Little Green Pharma, Cann Group Limited, Pharmahemp d.o.o, ENDOCA, Elixinol Wellness, Aurora Cannabis Inc., Canopy Growth Corporation, Green House Thailand, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cannabidiol (CBD) Market Strategic Shifts
Technology convergence and regulatory recalibration are compressing product development cycles while fragmenting distribution authority across new channel types. These shifts demand simultaneous investment in manufacturing flexibility and compliance infrastructure.
Supercritical CO2 extraction with integrated winterization and distillation is electrifying pharmaceutical-grade CBD production by enabling single-pass refinement to 99%+ purity. Australian and Thai contract manufacturers are retrofitting existing botanical extraction facilities at accelerated pace. This capability compression is collapsing the traditional multi-vendor supply chain into captive or tightly integrated production models.
South Korea's MFDS has established a dedicated cannabinoid research approval track that permits importation of pharmaceutical-grade extracts for clinical investigation, creating a regulated pathway previously unavailable. Domestic manufacturers are responding by establishing institutional review board relationships and investigator-initiated trial capabilities. The pharmaceutical application segment is most affected, with sponsors prioritizing neuropsychiatric and analgesic indications where local evidence gaps exist.
Hospital network procurement consolidation is compressing vendor qualification timelines and demanding outcome documentation that smaller suppliers cannot generate. Australia's eastern state health systems and Thailand's major metropolitan hospital groups are centralizing formulary decisions through specialized pharmacy and therapeutics committees. This concentration is most visible in oncology and palliative care verticals where CBD adjuvant therapy protocols are being standardized.
Asia-Pacific Cannabidiol (CBD) Market Segmentation
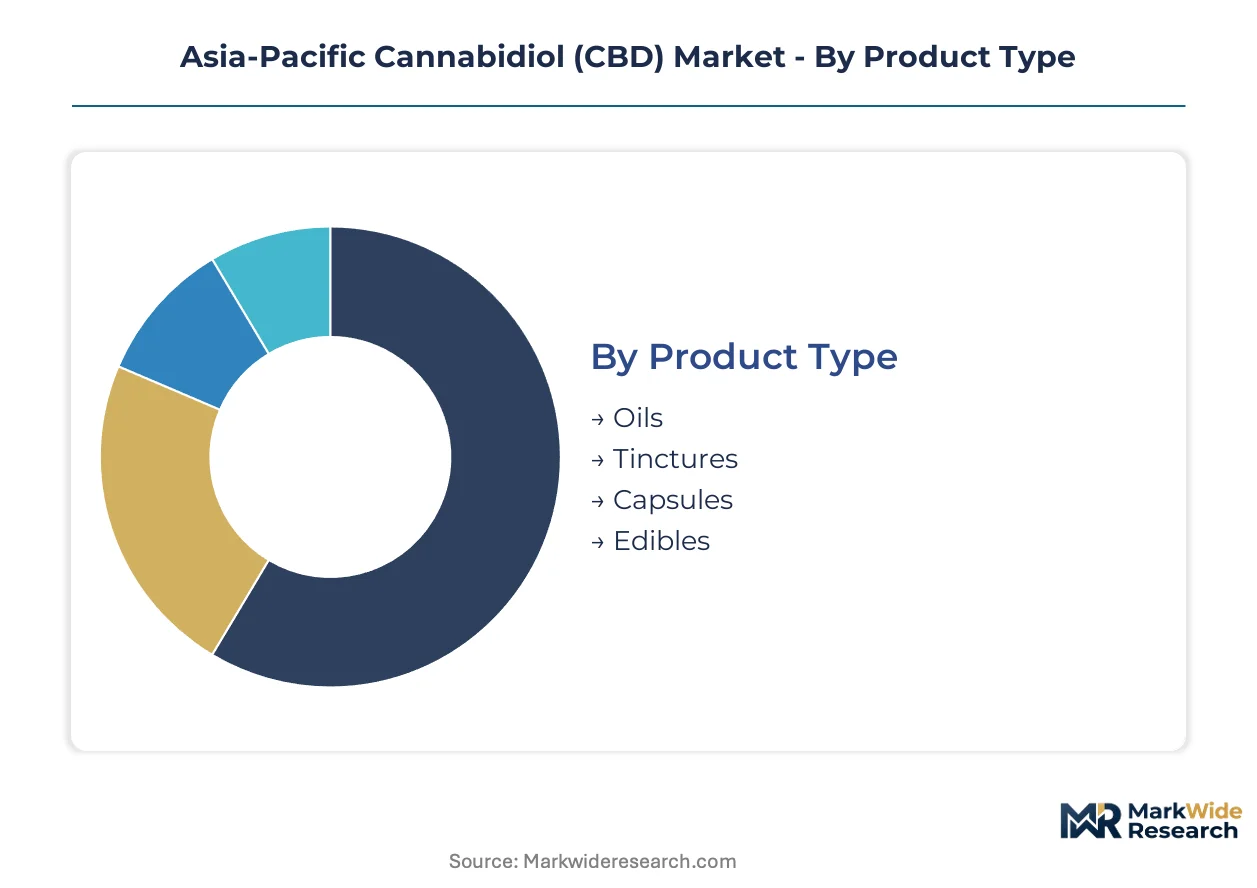
Segmentation in the Asia-Pacific CBD market reflects divergent regulatory pathways that partition products across prescription, pharmacy, and retail channels. Each category's structure determines compliance burden, margin profile, and geographic addressability.
Product Type:
Standalone therapeutic formats dominate prescription channels, while embedded food and beverage applications require separate safety certifications.
- Oils:Liquid extracts standardized to specific CBD concentrations with carrier oils enabling sublingual absorption. Demand clusters in Australia's eastern states where TGA Schedule 3 pharmacy sales require precise dosing instrumentation. Hospital procurement committees favor oils for their established bioavailability data and titration flexibility.
- Tinctures:Alcohol-based or glycerin-based formulations with extended shelf stability and rapid mucosal uptake. Thailand's medical cannabis clinics near Bangkok hospital networks specify tinctures for palliative care protocols where rapid onset matters. MFDS-regulated imports into South Korea prioritize tincture formats for clinical trial sponsors.
- Capsules:Encapsulated oil or isolate powder delivering fixed-dose convenience for chronic condition management.
- Edibles:Shelf-stable food products incorporating CBD isolate or broad-spectrum extract; food safety framework maturation across Southeast Asia enables format diversification beyond clinical applications.
Volume placements concentrate in Oils; the faster expansion belongs to Edibles.
Application:
Cost tier stratification separates premium pharmaceutical positioning from mass-market retail accessibility.
- Healthcare:Prescription and pharmacy-channel products targeting anxiolytic, anti-inflammatory, and anticonvulsant indications with clinical evidence requirements. Australia's TGA Schedule 3 rescheduling opened pharmacy distribution previously restricted to specialty clinics. Thailand's FDA narcotics framework permits hospital procurement for specific therapeutic indications.
- Personal Care:Topical formulations bypassing prescription requirements through cosmetic registration pathways in multiple Asia-Pacific jurisdictions. Premium pricing depends on brand positioning and retail shelf presence rather than clinical dossiers. Bangkok and Sydney metropolitan areas show concentrated demand for skincare and wellness applications.
- Food & Beverage:CBD-infused consumables requiring food safety compliance separate from pharmaceutical frameworks.
- Pet Care:Veterinary applications emerging through regulatory gray zones with limited formal approval pathways.
Revenue gravity centers on Healthcare; share gains are steepest in Personal Care.
Distribution Channel:
Channel selection determines regulatory touchpoint density and patient access friction.
- Pharmacies:Primary beneficiary of Australia's TGA down-scheduling, with pharmacy networks now capturing volume previously flowing through medical cannabis clinics. Pharmacist consultation requirements create patient education infrastructure that online channels cannot replicate.
- Online:Direct-to-consumer platforms serving markets with less restrictive import frameworks; South Korea's MFDS research approval track permits pharmaceutical-grade extract imports for investigational use.
- Supermarkets:Mass retail access contingent on food safety registrations rather than pharmaceutical scheduling.
- Specialty Stores:Concentrated in Thailand's Bangkok metropolitan region and Australia's eastern states where consumer education demands trained staff.
Patient access runs through Pharmacies; geographic reach expands fastest via Online.
End User:
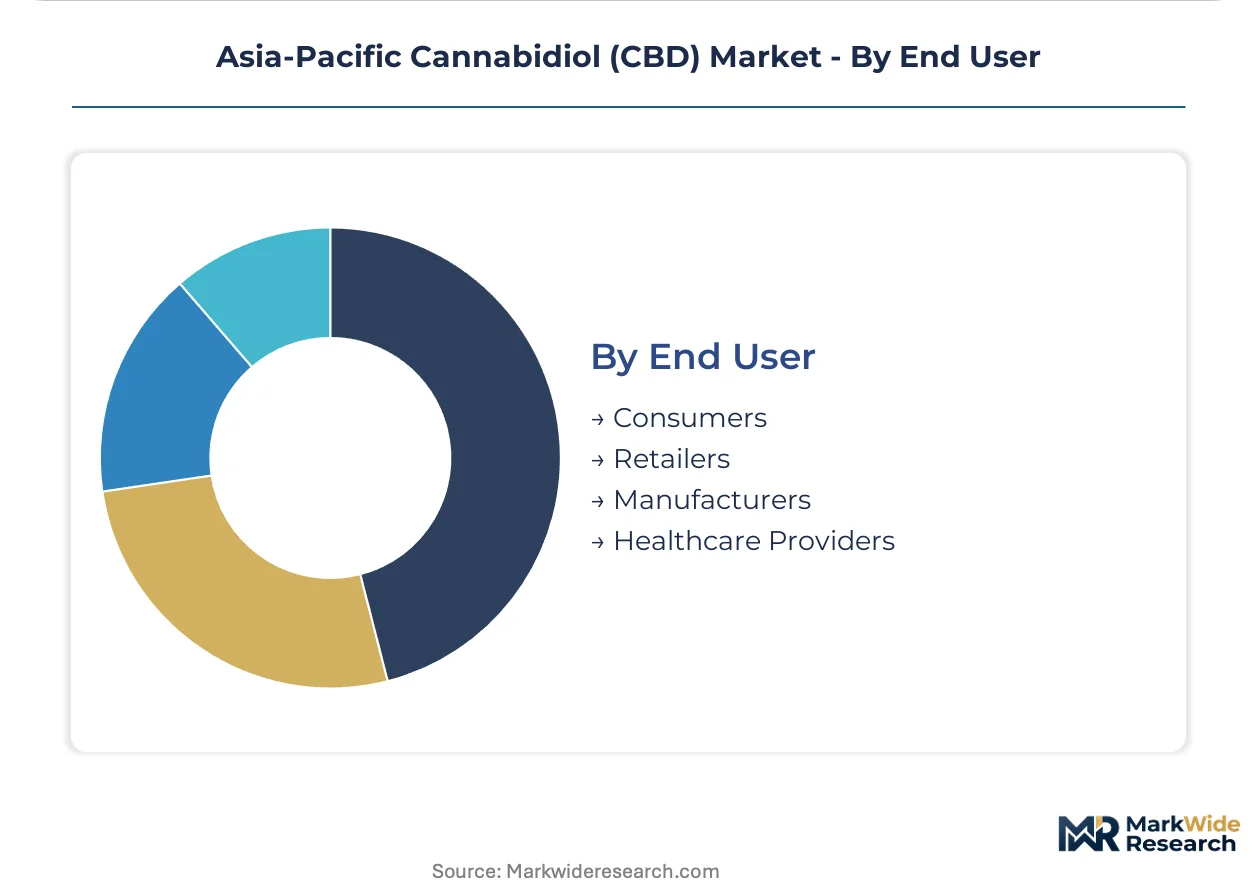
Procurement authority is consolidating among institutional buyers with formulary control.
- Healthcare Providers:Hospital networks and specialty clinics in Australia's eastern states and Thailand's Bangkok region centralizing CBD adjuvant therapy decisions through pharmacy and therapeutics committees. Oncology and palliative care verticals show strongest procurement concentration.
- Consumers:Direct purchasers through pharmacy and online channels; Australia's Schedule 3 availability expanded over-the-counter access without prescription requirements.
- Retailers:Pharmacy chains and specialty store operators managing shelf placement and patient education protocols.
- Manufacturers:Pharmaceutical companies and contract manufacturers requiring GMP-certified inputs for finished formulation production.
Procurement volume concentrates with Healthcare Providers; the consumer-direct channel is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified organic hemp cultivation clusters in Australia's Riverina region and Thailand's northern provinces supply the primary feedstock for pharmaceutical-grade extraction across the Asia-Pacific CBD corridor.
Australia
Hospital networks in New South Wales and Victoria centralize procurement for oncology adjuvant therapies, while the TGA's Schedule 3 down-scheduling shifted volume toward pharmacy channels. Sydney and Melbourne metropolitan areas concentrate medical cannabis clinics near major hospital complexes. GMP-certified extraction facilities in these states now serve both domestic prescription demand and export contracts to Southeast Asian markets.
Thailand
Bangkok's metropolitan hospital groups drive prescription volumes for palliative care protocols, supported by the FDA's controlled narcotics framework relaxation for specific therapeutic indications. The Ministry of Public Health's gradual liberalization pathway permits pharmaceutical manufacturers to register CBD extracts for hospital procurement. Chiang Mai and surrounding northern provinces host the dominant organic hemp cultivation zones supplying downstream processors.
South Korea
Clinical trial sponsors prioritize neuropsychiatric and analgesic indications where local evidence gaps persist, leveraging the MFDS dedicated cannabinoid research approval track. Seoul-based pharmaceutical companies import pharmaceutical-grade extracts for investigator-initiated trials. The capital region's institutional review board infrastructure supports accelerated trial initiation compared to other Asia-Pacific jurisdictions.
Japan
PMDA's cautious stance on cannabinoid therapeutics limits commercial scale, though research exemptions permit limited pharmaceutical-grade imports for academic investigation. Tokyo and Osaka academic medical centers host the primary cannabinoid research programs. The regulatory environment favors synthetic cannabinoid analogs over plant-derived CBD, constraining market development relative to regional peers.
New Zealand
MedSafe's prescription-only scheduling maintains specialty clinic dominance despite patient advocacy for pharmacy access expansion. Auckland and Wellington concentrate prescribing infrastructure for chronic pain and epilepsy indications. The country's Therapeutic Products Act implementation is recalibrating quality standards for imported pharmaceutical-grade extracts.
Asia-Pacific Cannabidiol (CBD) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cosmetic and food-safety registrations to bypass pharmaceutical compliance burdens. The market exhibits moderate concentration with three to five integrated operators controlling GMP-certified cultivation and extraction capacity. Two strategic archetypes dominate: vertically integrated pharmaceutical suppliers and specialized organic hemp processors. Competitive intensity centers on regulatory dossier completeness and hospital network procurement qualifications rather than price alone.
Within the integrated pharmaceutical tier, Aurora Cannabis Inc. and Canopy Growth Corporation exemplify the capital-intensive archetype combining GMP cultivation infrastructure with hospital distribution contracts. Elixinol Wellness occupies a distinct position emphasizing vertically controlled supply chains from organic sourcing through finished tincture production. Australian operators Althea Group, Little Green Pharma, and Cann Group Limited anchor the regional specialist segment with domestic cultivation licenses and TGA-compliant manufacturing capabilities. Thai entities including Green House Thailand leverage proximity to Bangkok's hospital networks and northern hemp cultivation zones. European-sourced suppliers Pharmahemp d.o.o and ENDOCA serve import-dependent markets where local extraction capacity remains underdeveloped.
| Leading Market Players |
|---|
| Althea Group |
| Little Green Pharma |
| Cann Group Limited |
| Pharmahemp d.o.o |
| ENDOCA |
| Elixinol Wellness |
| Aurora Cannabis Inc. |
| Canopy Growth Corporation |
| Green House Thailand |
| Others |
Value Chain & Pricing Dynamics
Hospital network procurement committees in Australia's eastern states and Thailand's Bangkok metropolitan region anchor contract-based long-term offtake agreements that compress pricing variability across pharmaceutical-grade CBD tiers. This buyer concentration forces manufacturers to absorb chromatographic separation costs while competing on GMP certification completeness rather than unit price alone.
Pricing Analysis
Volume placements cluster in pharmacy-channel oils at compressed margins, while tincture formats for hospital palliative care protocols retain premium positioning through bioavailability documentation and rapid onset claims. Price differentiation hinges on TGA Schedule 3 compliance tier and organic hemp certification status, with Thailand's FDA narcotics framework adding regulatory cost layers that widen spreads between prescription and pharmacy tiers. Pricing pressure stems from supercritical CO2 extraction facility overbuild across Australia's Riverina region, forcing toll processors to discount contract rates. Consumer-direct online channels exhibit highest price sensitivity; hospital procurement committees least so due to formulary standardization mandates.
Supply Chain Analysis
Single-source vulnerability sits with Australia's Riverina region and Thailand's northern provinces, where certified organic hemp cultivation clusters feed downstream GMP extraction. Raw material dependencies center on chromatography-grade CO2, pharmaceutical-grade ethanol for winterization, and isolate-ready packaging formats compliant with MFDS import specifications. Supply chain risk manifests as regulatory restriction divergence across TGA, FDA, and MFDS scheduling frameworks, forcing parallel compliance dossiers that fragment batch economics. Distribution runs through hospital procurement committees for prescription volumes, pharmacy networks for Schedule 3 products, and cosmetic registration pathways for personal care bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP-certified extraction capacity scarcity across Southeast Asia props pricing power for incumbent operators with validated hospital contracts. This supply constraint persists despite facility overbuild in Australian cultivation zones due to certification timeline bottlenecks.
For Market Incumbents: Hedge against Thailand's FDA liberalization acceleration by securing multi-year organic hemp supply contracts before northern province cultivation expands. Prioritize backward integration into chromatographic separation capabilities to defend margin position against toll processor discounting. Lock hospital network formulary status through oncology adjuvant therapy protocol standardization. For New Entrants and Emerging Players: Begin with cosmetic registration pathways in South Korea and Japan, where PMDA's research exemption track permits limited pharmaceutical-grade imports without full narcotics scheduling compliance. Target personal care shelf presence in Sydney and Bangkok metropolitan retail clusters before attempting prescription channel penetration. Lead with topical format launches that bypass clinical trial investment requirements entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian operators with TGA manufacturing licenses but constrained working capital for Schedule 3 pharmacy channel expansion. Long-term viability centers on captive organic hemp supply and hospital procurement committee relationships rather than brand equity. Watch MFDS clinical trial approval velocity as inflection indicator for South Korean market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | TGA Schedule 3 compliance unlocks pharmacy distribution previously restricted to specialty clinics. |
| Backward Integration | Captive organic hemp supply in Riverina or northern Thailand reduces input cost volatility during seasonal disruptions. |
| Hospital System Partnership | Formulary placement with Bangkok metropolitan hospital groups secures palliative care protocol standardization. |
| Manufacturing Scale-Up | GMP-certified extraction capacity expansion serves export contracts to MFDS-regulated South Korean clinical trial sponsors. |
| Geographic Expansion | Cosmetic registration in Japan bypasses PMDA's restrictive stance on plant-derived CBD therapeutics. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving pharmaceutical manufacturing executives, hospital pharmacy and therapeutics committee members, regulatory affairs leads at TGA and FDA, and organic hemp cultivation operators. Bottom-up volume estimates from cultivation license counts and extraction facility throughput reconciled against top-down pharmaceutical spending patterns across the analysis window.
Data-stream reconciliation combined patient access volume projections with pricing tier assumptions across prescription, pharmacy, and cosmetic channels. Segmentation modeling incorporated product format, application vertical, distribution channel type, and end-user procurement authority. CAGRs derived from regulatory timeline probability weighting and hospital network formulary adoption curve analysis, with supercritical CO2 extraction capacity buildout schedules and organic hemp yield variability as key forecast inputs.
Underlying measurement precision varies by segment; pharmacy-channel oils and tinctures carry tighter precision than emerging edibles and personal care categories where food safety framework maturation remains incomplete. Forecasts reflect documented assumptions regarding TGA scheduling stability, Thailand's FDA liberalization velocity, and MFDS research track expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
US Minor Cannabinoids Market