
 Cannabis Use Disorder Treatment Market | 2026-2036
Cannabis Use Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
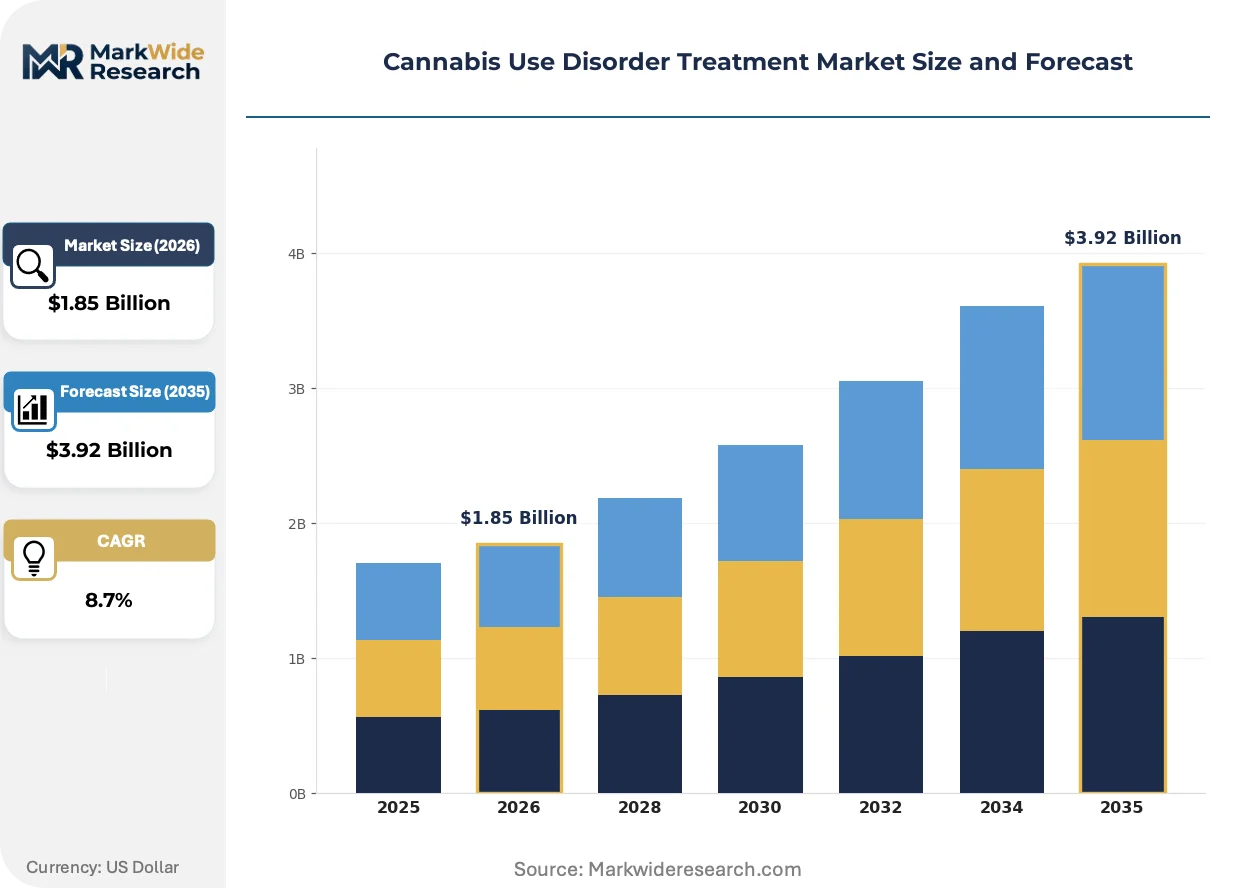
Cannabis Use Disorder Treatment Market Outlook
Treatment economics for cannabis use disorder is decoupling between premium pharmacotherapy and commodity behavioral services. Indivior PLC leverages its buprenorphine infrastructure to anchor opioid-cannabis comorbidity protocols. Jazz Pharmaceuticals competes through its neurology-focused commercial platform, while Alkermes PLC differentiates via depot formulation expertise applied to addiction medicine.
Cannabis use disorder treatment encompasses pharmacological interventions, psychosocial therapies, and structured rehabilitation designed to reduce dependency, manage withdrawal, and prevent relapse in individuals with problematic cannabis consumption. Therapeutic drugs targeting CB1 receptor modulation represent the highest-margin segment, while telehealth services are expanding fastest as delivery infrastructure normalizes post-pandemic. Behavioral therapy retains the largest volume footprint, though rehabilitation programs command premium pricing through residential intensity.
FDA oversees investigational new drug pathways for novel cannabinoid antagonists, while DEA scheduling determinations directly constrain prescription accessibility for scheduled compounds. State Medicaid programs increasingly influence reimbursement parity between pharmacotherapy and psychosocial interventions. Stakeholders must monitor how SAMHSA funding reauthorization and emerging FDA guidance on digital therapeutics reshape competitive boundaries between pharmaceutical and technology-enabled treatment modalities.
Market Dynamics
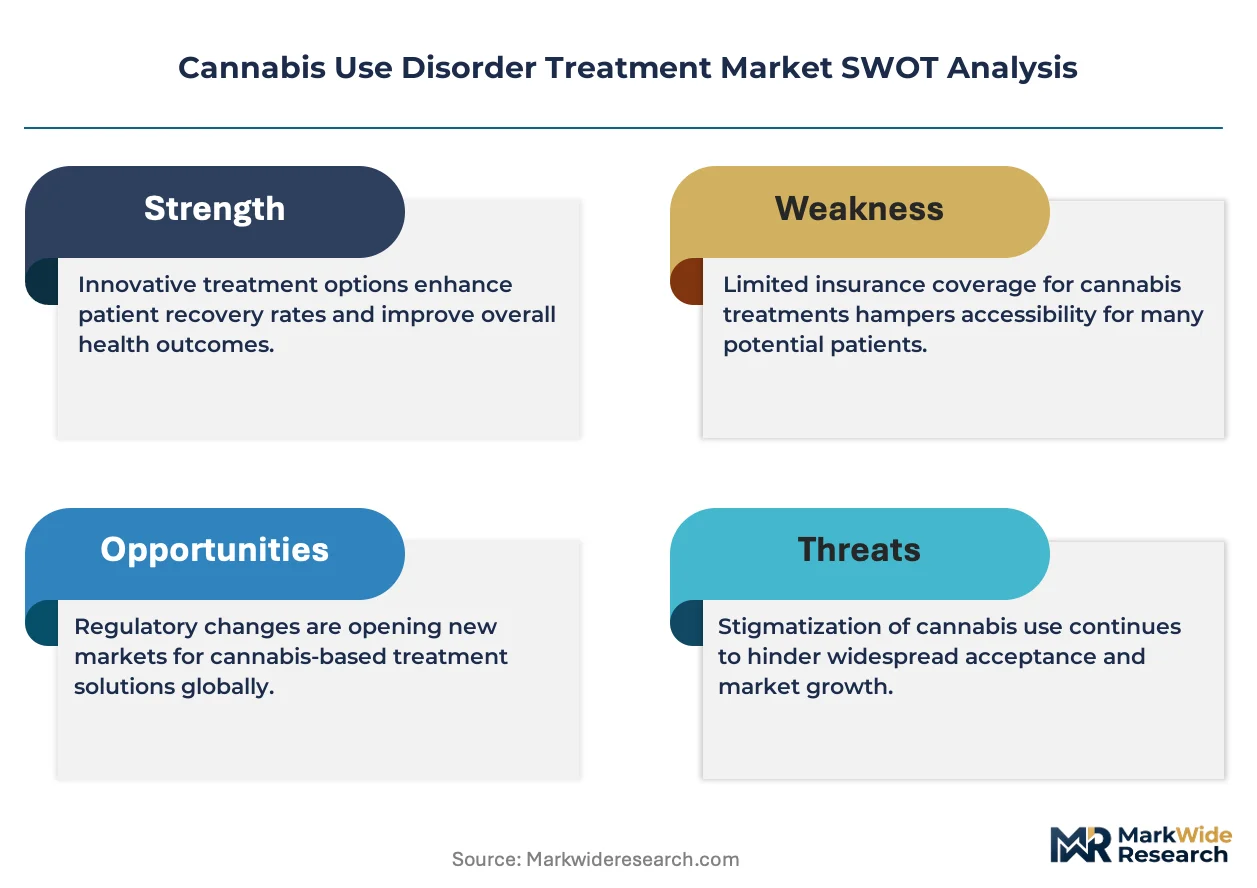
FDA scheduling reviews of cannabinoid antagonists are creating regulatory arbitrage between pharmaceutical and behavioral treatment modalities, while state Medicaid reimbursement parity rules are redrawing competitive boundaries across delivery channels.
Growth Catalysts
- Medicaid Reimbursement Parity:State-level mandates in California and New York now reimburse pharmacotherapy at rates matching psychosocial interventions, expanding provider participation.
- Telehealth Infrastructure Normalization:Post-pandemic regulatory flexibilities for remote prescribing of controlled substances are absorbing previously untreated rural populations into formal care pathways.
- Opioid-Cannabis Comorbidity Protocols:SAMHSA-funded integration programs are driving specialty addiction clinics to adopt unified treatment frameworks for dual-diagnosis patients.
Market Restraints
- DEA Scheduling Friction:Schedule I classification of cannabis itself creates research barriers and limits prescriber comfort with cannabinoid-targeting pharmaceuticals.
- Behavioral Service Commoditization:Group therapy and outpatient counseling face reimbursement compression as state budgets prioritize acute care over maintenance programs.
- Clinical Trial Recruitment Constraints:Stigma-associated hesitancy among cannabis users slows enrollment for novel antagonist development programs.
Strategic Opportunities
- Digital Therapeutics Pathway:FDA draft guidance on prescription digital therapeutics creates a regulatory channel for app-based cognitive behavioral interventions.
- Depot Formulation Expansion:Long-acting injectable platforms developed for alcohol and opioid use disorder are being repurposed for cannabis cessation protocols.
- Employer-Sponsored Coverage Gaps:Large self-insured employers in technology and finance sectors are adding substance use disorder benefits without parity constraints affecting commercial plans.
Industry Challenges
- Addiction Psychiatry Workforce Scarcity:Fellowship-trained specialists concentrate in academic medical centers, leaving community-based programs dependent on generalist providers.
- Integrated EHR Fragmentation:Behavioral health data silos within hospital systems impede care coordination between psychiatric and primary care settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Use Disorder Treatment Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Drugs, Behavioral Therapy, Support Groups, Rehabilitation Programs Delivery Model: In-person Therapy, Telehealth Services, Online Counseling, Group Sessions Client Type: Individuals, Families, Healthcare Providers, Institutional Clients Consumer Age Group: Adolescents, Young Adults, Adults, Seniors |
| Companies Covered | Indivior PLC, Zynerba Pharmaceuticals, Pfizer Inc., Jazz Pharmaceuticals, Aelis Farma, Adial Pharmaceuticals, Omeros Corporation, Alkermes PLC, Corbus Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Use Disorder Treatment Market Strategic Shifts
CB1 receptor modulation technologies are converging with digital biomarker platforms to enable precision dosing, while regulatory frameworks for combination drug-device products are maturing across major jurisdictions.
Peripheral CB1 antagonists with reduced central nervous system penetration are absorbing safety concerns that halted first-generation rimonabant development. Specialty addiction clinics in Massachusetts and Texas are piloting these compounds for metabolic and psychiatric endpoints simultaneously. The technology is absorbing liability risk that previously constrained pharmaceutical investment in the therapeutic class.
EMA's adaptive pathway pilot for psychiatric indications is accelerating conditional approval timelines for novel mechanisms in cannabis use disorder. Manufacturers are structuring rolling review submissions to align with FDA breakthrough therapy designations. European reimbursement agencies are demanding real-world evidence generation that US commercial plans are beginning to mirror.
Payers are unbundling residential rehabilitation from outpatient pharmacotherapy, creating distinct procurement streams with diverging margin structures. Behavioral health carve-out vendors are capturing employer contracts that previously flowed to integrated health systems. This bifurcation is most pronounced in Florida and Arizona, where for-profit treatment operators dominate network composition.
Cannabis Use Disorder Treatment Market Segmentation
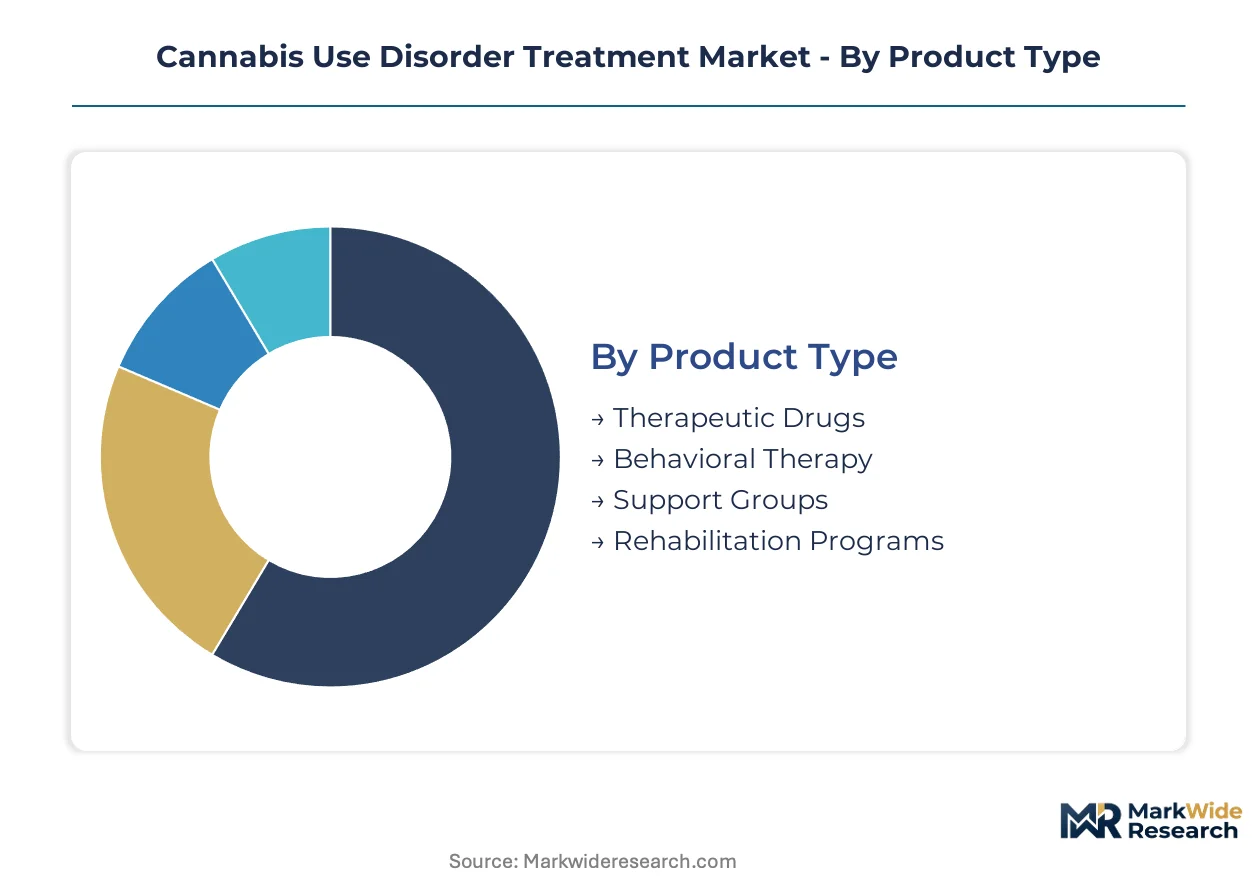
Treatment modality segmentation in cannabis use disorder reflects divergent regulatory pathways and reimbursement economics. Each category carries distinct certification burdens that shape competitive entry and margin structures across the value chain.
Product Type:
FDA approval requirements and DEA scheduling determinations create tiered barriers to entry across therapeutic interventions, with pharmacological segments facing the steepest compliance costs.
- Therapeutic Drugs:CB1 receptor antagonists and cannabinoid modulators require Phase III trials and NDA submission to FDA. Massachusetts General Hospital and Johns Hopkins anchor investigator-initiated studies for novel antagonists. Pricing power concentrates with compounds achieving breakthrough therapy designation.
- Behavioral Therapy:Cognitive behavioral interventions and motivational enhancement therapy operate under state licensure frameworks without federal drug approval. Medicaid reimbursement parity in California and New York has expanded provider networks for this segment.
- Support Groups:Peer-led facilitation models minimize regulatory overhead. Community-based organizations in Texas and Florida dominate delivery.
- Rehabilitation Programs:Residential intensity commands premium pricing through Joint Commission accreditation. Arizona and Florida operators lead for-profit network penetration.
Behavioral Therapy sits at the top of the volume ranking, with Therapeutic Drugs climbing the fastest.
Delivery Model:
Cost tier differentiation separates capital-intensive in-person infrastructure from scalable digital platforms, with hybrid models emerging as the dominant margin structure.
- In-person Therapy:Clinic-based delivery requires physical facility investment and state licensure. Urban concentration in Los Angeles, Chicago, and Miami creates access deserts in rural counties.
- Telehealth Services:Post-pandemic DEA flexibilities for controlled substance prescribing have normalized remote care. Rural populations in Montana and Wyoming access specialists previously unavailable within 200 miles.
- Online Counseling:Asynchronous text and video platforms operate under state telehealth parity laws. Employer-sponsored contracts in technology sectors absorb premium pricing.
- Group Sessions:Cost efficiency per patient-hour drives Medicaid preference. Community health centers in New York and Pennsylvania scale this model.
Telehealth Services are expanding most quickly, though In-person Therapy retains the highest reimbursement rates.
Client Type:
Customer concentration patterns split between fragmented individual demand and concentrated institutional procurement with diverging contract structures.
- Individuals:Direct-pay patients respond to stigma-reduction marketing and privacy guarantees. Out-of-pocket spending concentrates in coastal metropolitan areas.
- Families:Intervention-driven demand for adolescent cases carries higher price elasticity. Parental decision-making dominates this segment.
- Healthcare Providers:Hospital systems and primary care networks embed screening protocols. EHR integration requirements favor established vendors.
- Institutional Clients:Correctional facilities and Veterans Affairs medical centers procure through federal contracting vehicles. SAMHSA block grants fund state-level program expansion.
Healthcare Providers represent the largest addressable base, with Institutional Clients gaining share fastest through federal procurement reform.
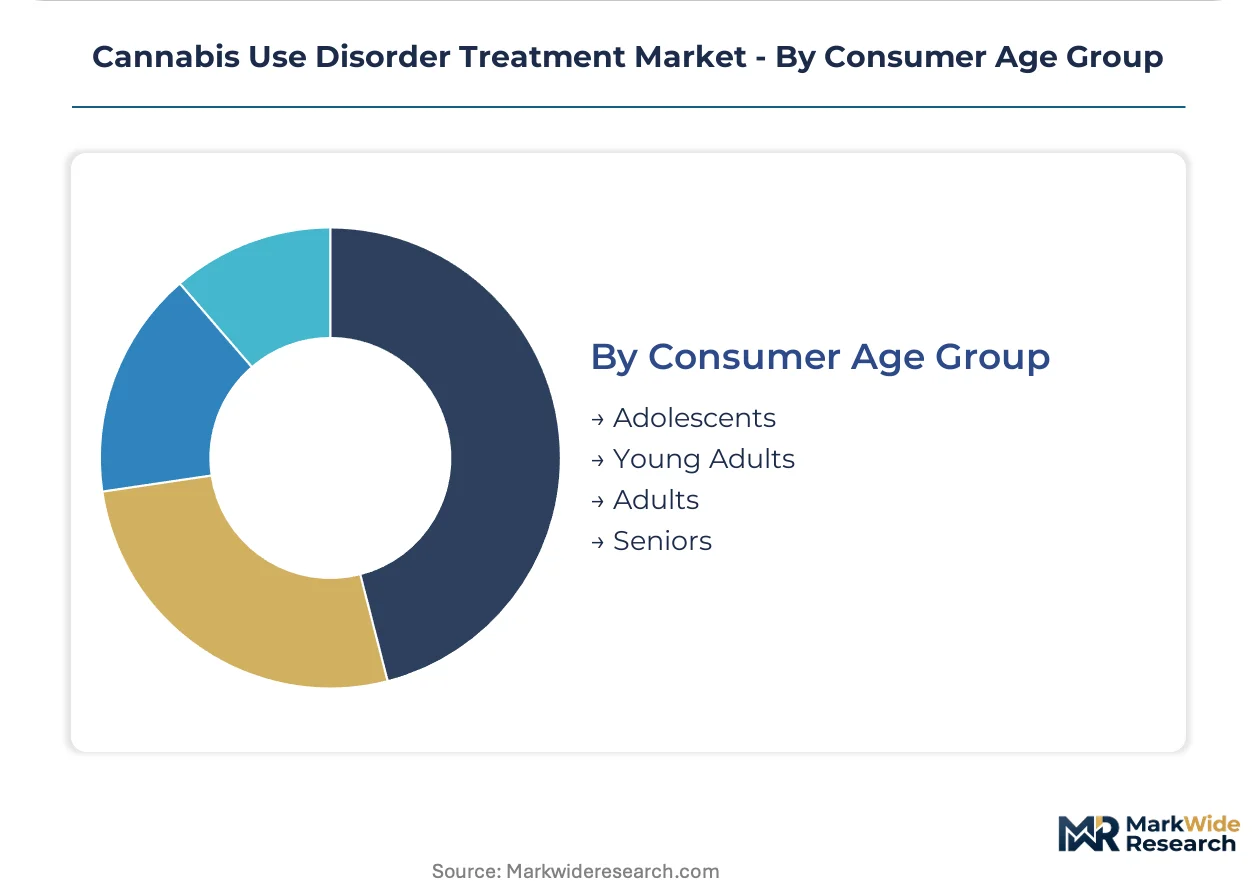
Consumer Age Group:
Application-specific protocols and developmental considerations drive segmentation, with adolescent interventions facing distinct regulatory and clinical frameworks.
- Adolescents:Family-based therapy models and school-linked screening programs dominate. FDA has approved no pharmacotherapy specifically for under-18 cannabis use disorder.
- Young Adults:College counseling centers and early career employee assistance programs absorb demand. This cohort shows highest telehealth adoption rates.
- Adults:Workforce-integrated treatment and primary care screening expansion target this segment. Commercial insurance parity enforcement has expanded coverage.
- Seniors:Medical cannabis comorbidity and polypharmacy concerns complicate treatment. Geriatric psychiatry fellowship scarcity limits specialist access.
Adults command the largest treatment volume, with Young Adults showing the steepest expansion trajectory as employer benefits normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially higher treatment infrastructure density than Canada, though both jurisdictions grapple with divergent federal-state regulatory frameworks that reshape patient access pathways.
United States
State-level legalization waves in California and New York have expanded the treatment-eligible population while Medicaid reimbursement parity mandates now match pharmacotherapy rates to psychosocial interventions. SAMHSA block grant reauthorization debates in Congress are reshaping funding flows for specialty addiction clinics. Massachusetts General Hospital and Johns Hopkins anchor investigator-initiated trials for novel CB1 antagonists in Boston and Baltimore corridors.
Germany
BfArM oversight of narcotic prescriptions creates stricter gateway controls than US equivalents, though statutory health insurance expansion for addiction medicine is absorbing previously untreated cohorts. EMA adaptive pathway pilots for psychiatric indications are accelerating conditional approval timelines for cannabinoid modulators. Heidelberg and Berlin academic medical centers coordinate multicenter trials through the German Center for Mental Health.
United Kingdom
NHS England's integrated care systems are embedding cannabis use disorder screening within primary care networks at scale unmatched by continental European counterparts. NICE guidance updates on pharmacotherapy for substance use disorders are redrawing formulary inclusion criteria. London's South London and Maudsley NHS Foundation Trust operates Europe's largest addiction psychiatry fellowship pipeline.
Canada
Health Canada cannabis regulations permit adult recreational use while paradoxically constraining clinical research into cessation pharmacotherapy through residual scheduling friction. Provincial health authority procurement of telehealth addiction services is absorbing rural access gaps in Manitoba and Saskatchewan. Centre for Addiction and Mental Health in Toronto anchors federal funding for cannabis and mental health comorbidity studies.
Australia
TGA Special Access Scheme pathways for unapproved cannabinoid medicines create regulatory arbitrage between prescription access and research enrollment. State-based drug and alcohol services in New South Wales and Victoria are piloting integrated opioid-cannabis comorbidity protocols. University of Sydney's Brain and Mind Centre coordinates national trial networks for novel antagonist development.
Cannabis Use Disorder Treatment Market Competitive Environment
Top-tier vendors anchor FDA-approved pharmacotherapy segments, while mid-tier specialists populate behavioral therapy and digital therapeutic niches. The competitive structure fragments across pharmaceutical developers, specialty addiction clinic operators, and telehealth platform providers with divergent capital intensity requirements. Three archetypes dominate: neurology-focused commercial platforms, depot formulation specialists, and buprenorphine infrastructure extenders. Consolidation pressures concentrate in pharmaceutical segments through breakthrough therapy designation races, while behavioral service markets face margin compression from reimbursement parity enforcement.
Within the pharmaceutical developer tier, Indivior PLC and Jazz Pharmaceuticals exemplify divergent platform strategies—one leveraging existing addiction medicine infrastructure, the other deploying neurology commercial capabilities. Alkermes PLC occupies a distinct position through depot formulation expertise repurposed from alcohol and opioid use disorder portfolios. These three entities represent the competitive anchors around which second-wave CB1 antagonist developers and digital therapeutic entrants are positioning.
| Leading Market Players |
|---|
| Indivior PLC |
| Zynerba Pharmaceuticals |
| Pfizer Inc. |
| Jazz Pharmaceuticals |
| Aelis Farma |
| Adial Pharmaceuticals |
| Omeros Corporation |
| Alkermes PLC |
| Corbus Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Medicaid procurement offices in California and New York anchor reimbursement rate-setting for pharmacotherapy and behavioral interventions alike, creating a bifurcated pricing model where premium residential rehabilitation commands out-of-pocket margins while telehealth services absorb volume at compressed rates. This buyer concentration forces providers to unbundle service components or risk exclusion from state-formulary networks.
Pricing Analysis
The bundled-vs-unbundled service split separates residential rehabilitation packages from à-la-carte outpatient pharmacotherapy and telehealth modules. Three-tier pricing structure across premium, standard, and economy levels reflects Joint Commission accreditation status, with Arizona and Florida for-profit operators capturing premium tiers through residential intensity. Cost compression in behavioral group therapy intensifies because state Medicaid programs prioritize acute episodes over maintenance protocols. Institutional clients at Veterans Affairs medical centers exhibit lowest price sensitivity, while direct-pay individuals in coastal metropolitan areas absorb highest out-of-pocket exposure.
Supply Chain Analysis
Direct-to-specialty-clinic channels handle DEA-scheduled pharmaceutical distribution, while telehealth platforms bypass physical infrastructure entirely. Active pharmaceutical ingredient manufacturing for CB1 antagonists concentrates in India, Switzerland, and the United States. Formulation development draws from specialized addiction psychiatry expertise concentrated at Massachusetts General Hospital and Johns Hopkins. Single-source vulnerability in fellowship-trained prescriber pipelines creates bottleneck risk for pharmacotherapy expansion. Distribution runs through specialty pharmacy networks for controlled substances and employer-sponsored carve-out vendors for behavioral services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as employer benefits in technology and finance sectors shift toward integrated substance use disorder coverage without parity constraints, elevating demand for premium-tier pharmacotherapy and coordinated care protocols.
For Market Incumbents: Deploy depot formulation expertise to extend long-acting injectable platforms from alcohol and opioid portfolios into cannabis cessation protocols. Acquire telehealth infrastructure to capture Medicaid reimbursement parity expansion in California and New York. Digital therapeutic entrants threaten traditional behavioral service margins through FDA prescription digital therapeutics pathways. For New Entrants and Emerging Players: Enter via employer-sponsored coverage gaps in technology and finance sectors where commercial plans lack parity constraints. Target rural access deserts in Montana and Wyoming where telehealth infrastructure absorbs previously untreated populations. Pursue SAMHSA-funded integration programs for opioid-cannabis comorbidity protocols as the fastest-penetrable institutional channel. For Investors and Strategic Acquirers: Specialty addiction clinic operators with Joint Commission accreditation are the most active acquirer in this space, consolidating for-profit networks in Florida and Arizona. Long-term viability hinges on FDA breakthrough therapy designation races for novel CB1 antagonists. Monitor DEA scheduling review outcomes as the critical inflection signal for pharmaceutical investment thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Formulation Expansion | Repurposes Alkermes PLC's long-acting injectable expertise for cannabis cessation protocols. |
| Digital Therapeutics Pathway | FDA draft guidance enables app-based cognitive behavioral interventions with prescription status. |
| Telehealth Infrastructure Normalization | Post-pandemic DEA flexibilities absorb rural populations in Montana and Wyoming. |
| Medicaid Reimbursement Parity | California and New York mandates expand provider participation in pharmacotherapy networks. |
| Opioid-Cannabis Comorbidity Integration | SAMHSA-funded programs drive unified treatment frameworks at specialty addiction clinics. |
Study Parameters
Bottom-up treatment modality modeling reconciled against top-down regulatory pathway tracking forms the analytical core of this study. Primary interviews with addiction psychiatry fellowship directors, specialty clinic operators, Medicaid formulary managers, and pharmaceutical regulatory affairs leads were validated against FDA filings, ClinicalTrials.gov protocols, SAMHSA block grant disbursement records, and state-level telehealth parity legislation. Secondary sources include DEA scheduling determinations, Joint Commission accreditation databases, and employer-sponsored benefits plan documents. Top-down prescription volume tracking from specialty pharmacy networks was triangulated against bottom-up service delivery capacity estimates.
Historical trendline analysis of treatment episode volume and reimbursement rate evolution informed the projection framework across the analysis window. Segmentation dimensions modeled include treatment modality, delivery model, client type, and consumer age group, with regional regulatory clusters capturing FDA, EMA, and Health Canada pathway divergence. CAGRs were derived from regression analysis of episode volume growth against reimbursement expansion trajectories. Forecast inputs incorporate DEA scheduling review timelines and Medicaid parity mandate adoption curves.
Inputs from FDA advisory committee proceedings and state Medicaid program rate filings were available through the study window; gaps in real-world evidence generation for peripheral CB1 antagonists introduce uncertainty bands around pharmacotherapy adoption curves. Forecasts reflect assumptions regarding telehealth regulatory flexibilities and SAMHSA funding reauthorization trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Cannabidiol (CBD) Oil Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
US Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Cannabidiol Extract Market