
 Europe Cannabidiol (CBD) Market | 2026-2036
Europe Cannabidiol (CBD) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cannabidiol (CBD) Market Foresight
Cosmetics application is hardening as the fastest-expanding end-use vertical for European CBD producers. Endoca leverages its certified organic extraction infrastructure to supply major beauty brands across Northern Europe. Cibdol anchors its position through pharmaceutical-grade oil formulations that meet stringent Novel Food authorization requirements. Essentia Pura differentiates via toll manufacturing partnerships that allow white-label cosmetics clients to bypass capital-intensive extraction investments.
Cannabidiol denotes a non-psychoactive phytocannabinoid extracted primarily from hemp cultivars containing less than 0.2% THC under EU agricultural standards, typically isolated through supercritical CO2 extraction or ethanol winterization to achieve 99% purity crystalline or full-spectrum oil formats for therapeutic and consumer applications. Oils retain the dominant revenue share within product type segmentation due to established medical prescribing patterns and tincture versatility, while edibles face steeper Novel Food validation timelines that compress near-term margin pools. Medical application commands premium pricing through pharmacy channels, though nutraceuticals compete aggressively on unit economics via direct-to-consumer online distribution.
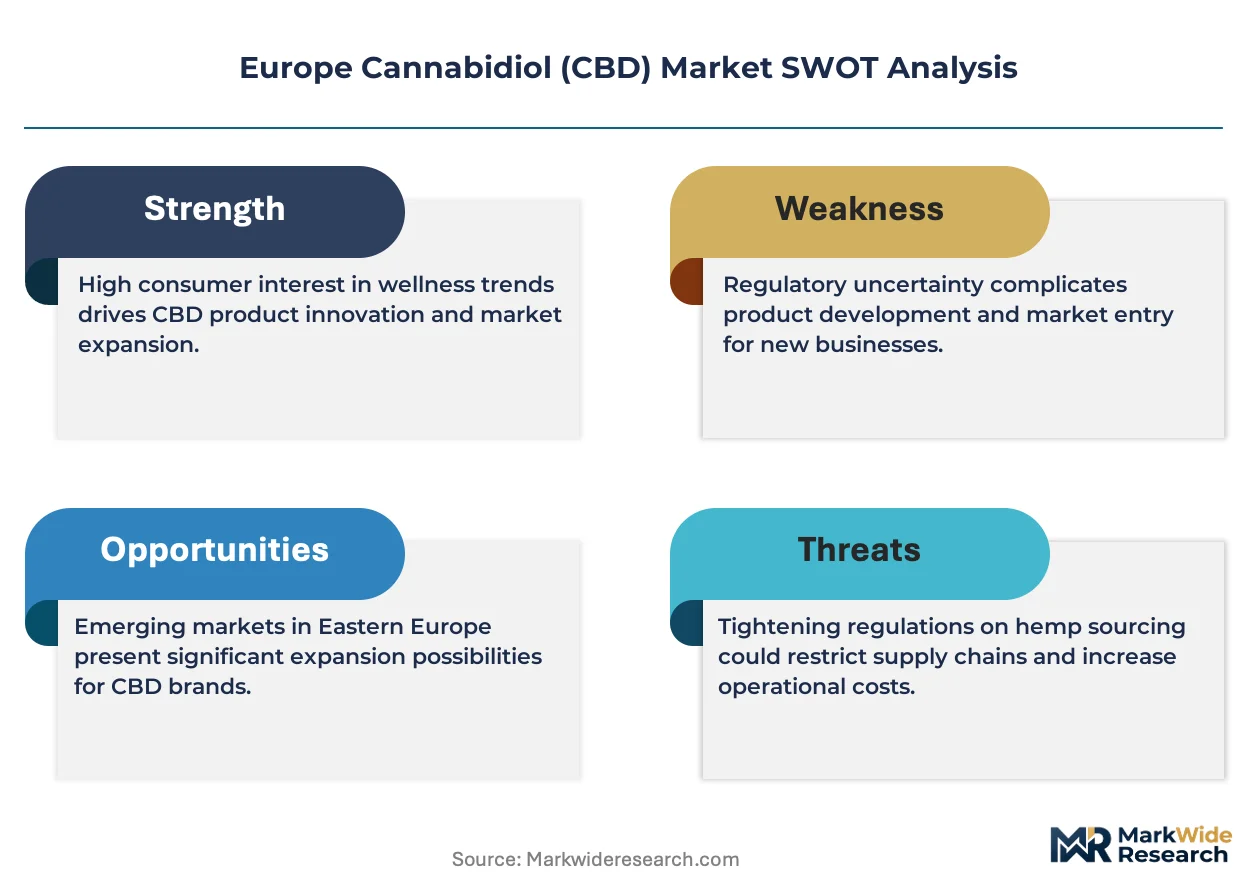
EMA guidance on cannabinoid-based therapeutics and the EU Novel Food Catalogue shape product authorization pathways, with EFSA safety evaluations determining whether CBD extracts qualify for food and supplement marketing. National regulators in Germany, the Netherlands, and Italy apply divergent enforcement intensity to cosmetic claims and THC threshold testing, fragmenting compliance costs for cross-border suppliers. Stakeholders must monitor pending EFSA opinions and member-state transposition of the EU Cannabis Agency framework to anticipate which distribution channels will unlock next.
Market Dynamics
The EU Court of Justice's 2020 ruling that CBD is not a narcotic under UN conventions continues to reshape national licensing frameworks across member states. This judicial precedent fragments enforcement intensity while creating divergent commercial pathways for extraction, formulation, and distribution stakeholders.
Growth Catalysts
- EMA guidance on cannabinoid-based therapeutics:The European Medicines Agency's evolving framework accelerates pharmaceutical-grade CBD authorization, enabling pharmacy distribution channels in Germany and the Netherlands.
- Cosmetics formulators:Skincare and haircare manufacturers across Northern Europe are expanding CBD incorporation, driving demand for certified organic extraction infrastructure and toll manufacturing partnerships.
- Supercritical CO2 extraction:This purification technology achieves 99% purity crystalline formats, satisfying stringent Novel Food authorization requirements and medical prescribing patterns.
Market Restraints
- Novel Food validation timelines:EFSA safety evaluations compress near-term margin pools for edibles, forcing capital lockup during multi-year authorization processes.
- THC threshold compliance:EU agricultural standards mandate less than 0.2% THC content, requiring costly winterization and testing protocols that strain smaller cultivators.
- Input cost volatility:Organic hemp biomass prices fluctuate with weather-dependent yields across Baltic and Eastern European growing regions.
Strategic Opportunities
- Medical reimbursement expansion:Germany's pharmacy distribution channels and evolving reimbursement policies create the region's most developed commercial pathway for prescription CBD oils.
- White-label cosmetics partnerships:Toll manufacturing arrangements allow beauty brands to bypass capital-intensive extraction investments while accessing pharmaceutical-grade formulations.
- EFSA opinion finalization:Pending safety evaluations for food and supplement marketing will unlock direct-to-consumer nutraceutical channels currently constrained by regulatory uncertainty.
Industry Challenges
- Novel Food dossier preparation:The technical expertise required for EFSA-compliant safety submissions exceeds in-house capabilities of most mid-size extractors, forcing reliance on specialized regulatory consultants.
- Cross-border compliance fragmentation:National regulators in Italy, France, and Spain apply divergent cosmetic claims enforcement and THC testing protocols, multiplying certification costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cannabidiol (CBD) Market |
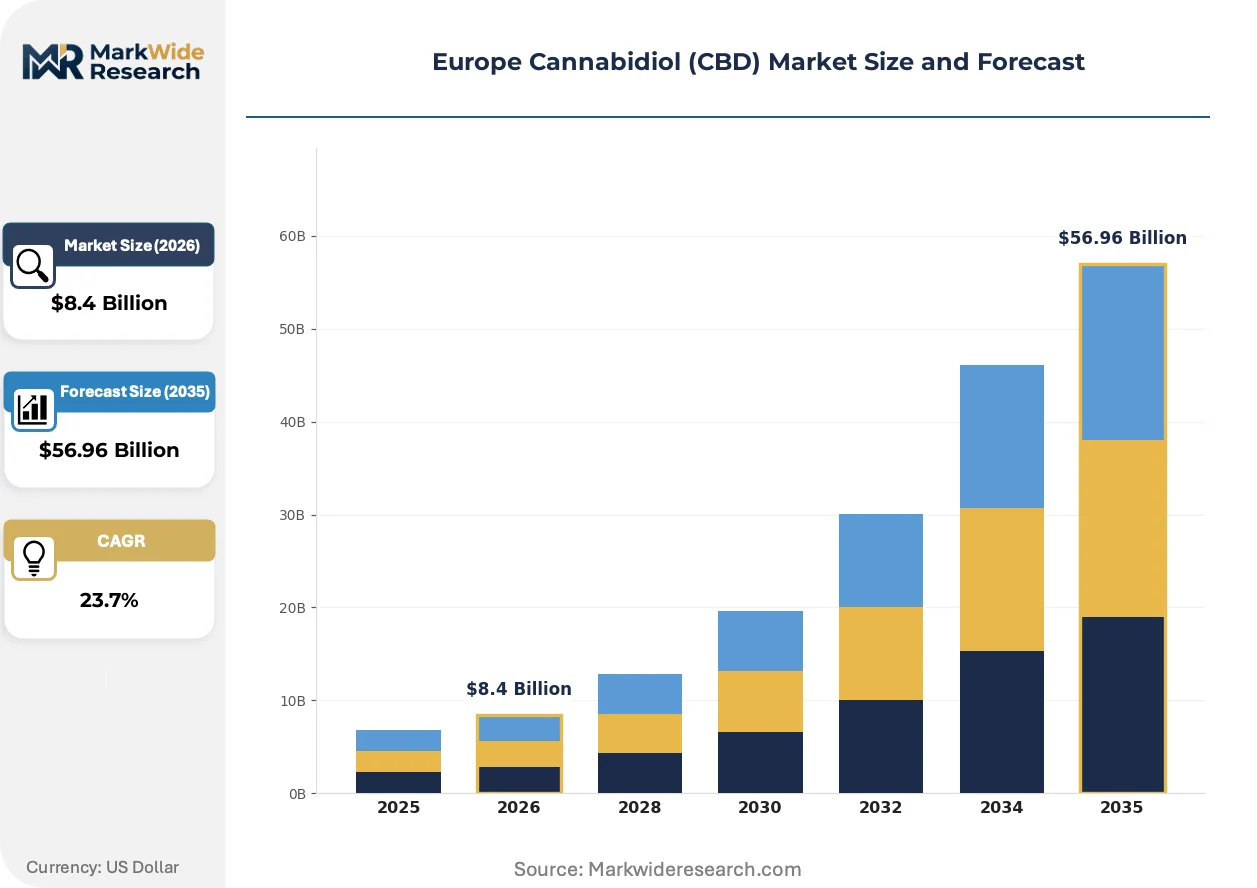
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $56.96 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Edibles, Capsules, Topicals Application: Medical, Cosmetics, Nutraceuticals, Beverage Distribution Channel: Online, Pharmacies, Retail Stores, Dispensaries End User: Consumers, Healthcare Providers, Retailers, Manufacturers |
| Companies Covered | Aurora Cannabis, Endoca, Candropharm, Formula Swiss, Cibdol, Canopy Growth Corporation, Essentia Pura, Elixinol, Tilray, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cannabidiol (CBD) Market Shifts & Advancements
Formulation science and regulatory clarity are actively reshaping competitive positioning across extraction, pharmaceutical, and consumer packaged goods segments. Three developments merit particular attention.
Supercritical CO2 extraction systems are converging with ethanol winterization protocols to produce full-spectrum oils that retain minor cannabinoids while meeting pharmaceutical purity standards. German and Dutch medical cannabis distributors are adopting these hybrid methods at accelerated pace. This technological convergence is enabling premium pricing through pharmacy channels while compressing margins for legacy ethanol-only processors.
The EU Novel Food Catalogue and pending EFSA opinions are restructuring market access pathways for ingestible CBD products. Industrial consequence includes forced pivot toward topical and cosmetic applications where regulatory friction remains lower. Edible and supplement manufacturers in the UK and Ireland are most affected, accelerating investment in dermal delivery science and transdermal patch formulations.
Pharmacy channel consolidation is displacing direct-to-consumer online distribution as the preferred procurement model for therapeutic-grade CBD. German statutory health insurance reimbursement eligibility is replacing price-sensitive e-commerce volume. This channel rotation is most visible in pain management and epilepsy adjacencies, where prescriber relationships and formulary inclusion determine market access.
Europe Cannabidiol (CBD) Market Segmentation
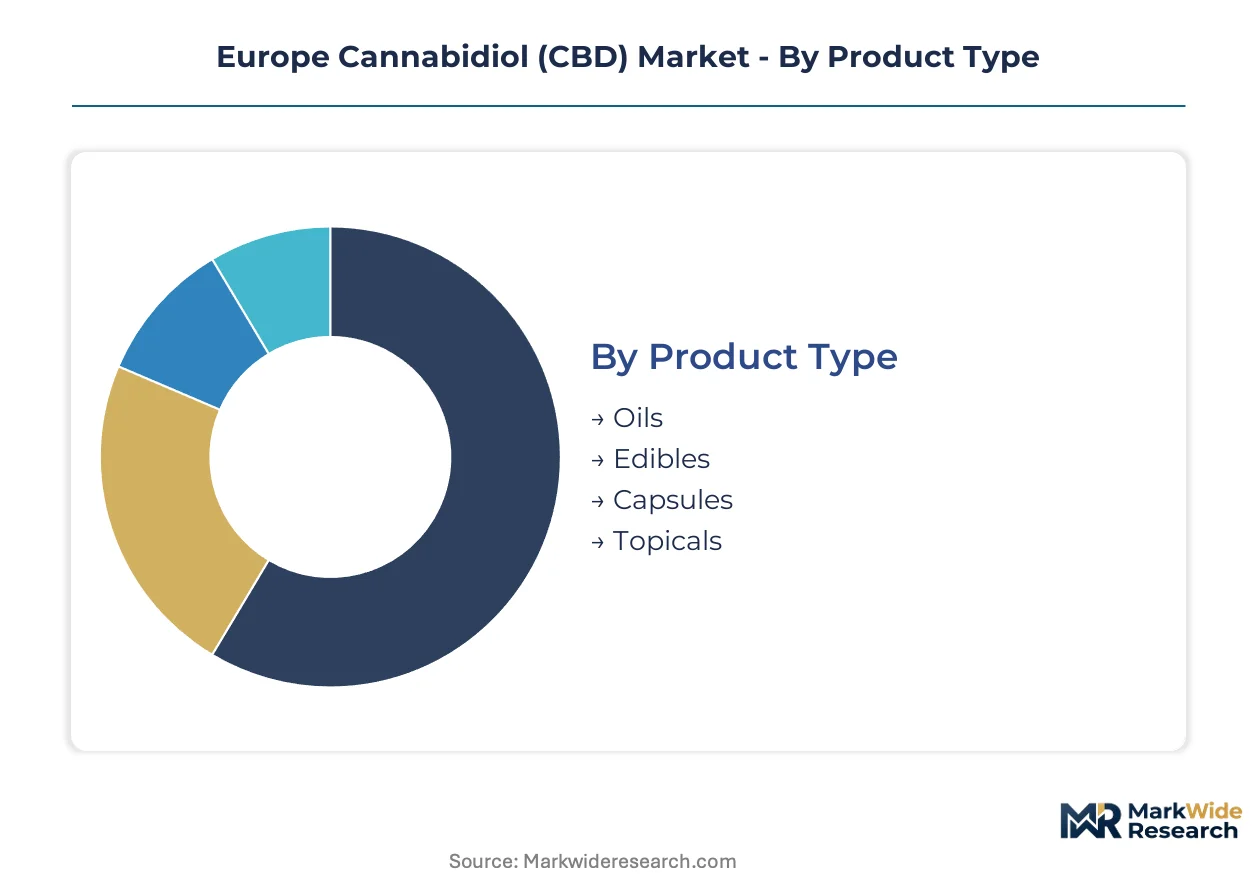
Europe's CBD market exhibits sharp fragmentation across product formats and procurement channels. Buyers navigate divergent regulatory thresholds—pharmaceutical-grade oils face EMA oversight while cosmetics operate under lighter cosmetic claims frameworks. Understanding where volume concentrates versus where margins expand determines supplier positioning.
Product Type:
Purchasing decisions here pivot on bioavailability requirements and route-of-administration preferences among therapeutic versus wellness-oriented users.
- Oils:Full-spectrum and isolate formulations delivered via tincture or dropper dominate medical prescribing patterns across Germany and the Netherlands. Pharmacy reimbursement eligibility for epilepsy and chronic pain indications locks in volume concentration here. Supercritical CO2 extraction infrastructure investments by Northern European processors reinforce supply reliability.
- Edibles:Gummies, chocolates, and infused food products face protracted EFSA Novel Food validation timelines that compress near-term commercial viability. Irish and UK manufacturers have pivoted toward topical development pending regulatory clarity. Margin pressure intensifies as capital remains locked in multi-year safety dossier preparation.
- Capsules:Precise dosing formats appeal to nutraceutical consumers seeking pharmaceutical-like regimentation without prescription requirements.
- Topicals:Creams, balms, and transdermal patches bypass ingestible regulatory friction while capturing cosmetics-adjacent demand.
Volume sits with oils; growth tilts toward topicals.
Application:
End-use economics separate premium-priced therapeutic channels from volume-driven wellness categories.
- Medical:Prescription CBD for epilepsy, multiple sclerosis spasticity, and chemotherapy-induced nausea commands reimbursement-backed pricing through German pharmacy networks. EMA guidance on cannabinoid-based therapeutics accelerates formulary inclusion. Dutch hospital pharmacies are expanding centralized compounding capabilities.
- Cosmetics:Skincare and haircare integration is expanding most quickly across Nordic markets where organic certification commands shelf-space premiums. Certified organic extraction partnerships enable white-label supply to major beauty brands. Regulatory enforcement on cosmetic claims remains lighter than ingestible categories.
- Nutraceuticals:Food supplements and wellness capsules compete aggressively through direct-to-consumer online distribution.
- Beverage:Functional drinks face steep Novel Food barriers similar to edibles, constraining commercial scale.
Medical captures margin concentration; cosmetics shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines compliance burden intensity and customer relationship depth.
- Online:Direct-to-consumer platforms dominate nutraceutical and wellness oil sales across jurisdictions with lighter enforcement. German consumers increasingly bypass e-commerce for pharmacy procurement as reimbursement eligibility expands.
- Pharmacies:German statutory health insurance coverage for specific indications has rotated procurement toward Apotheke channels. Prescriber relationships and formulary inclusion now determine market access for therapeutic-grade products.
- Retail Stores:Health food shops and specialty wellness retailers serve cosmetics and supplement demand in the Netherlands and Austria.
- Dispensaries:Cannabis-specific retail operates under national licensing frameworks with concentrated presence in the Netherlands.
Pharmacy channels are displacing online for therapeutic segments; retail stores retain cosmetics volume leadership.
End User:
Stakeholder sophistication varies dramatically across prescription, wellness, and industrial procurement contexts.
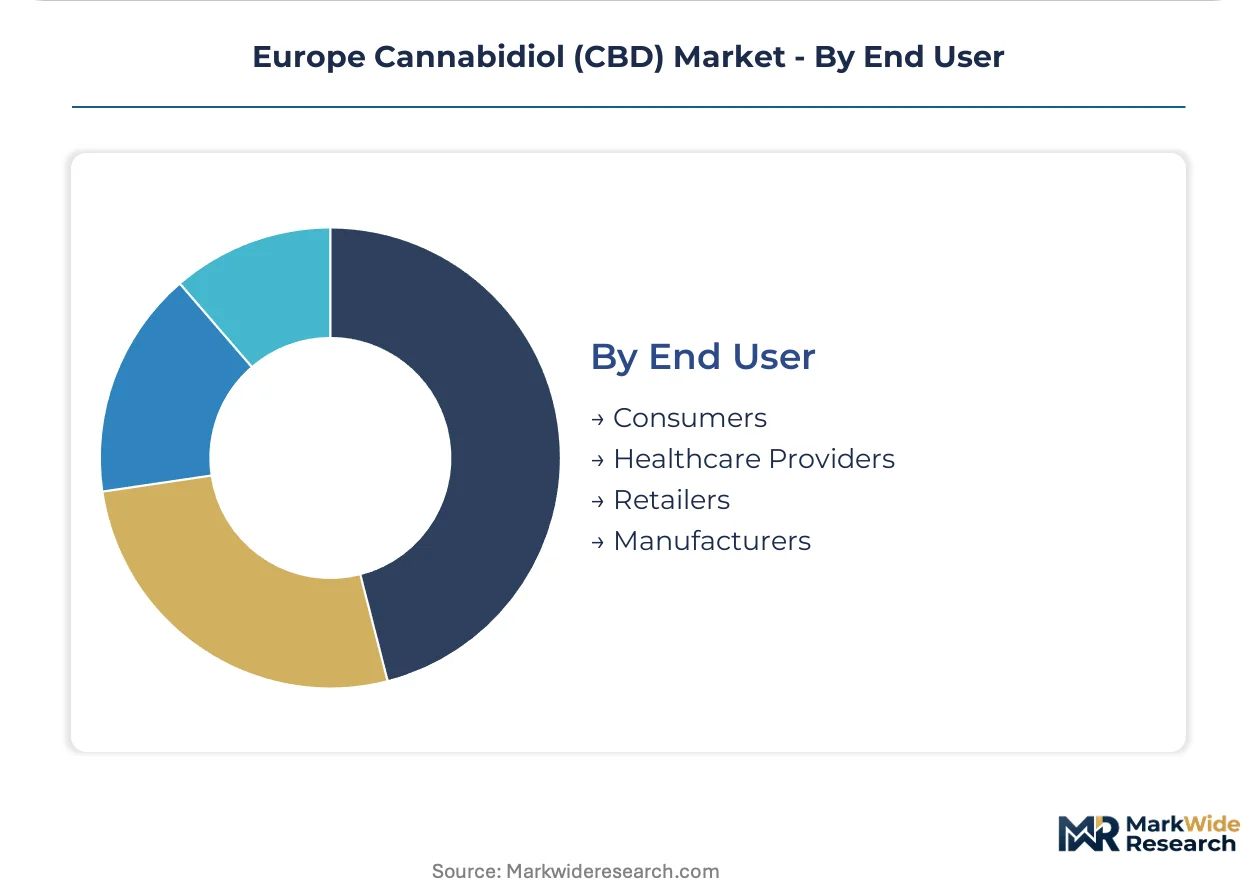
- Consumers:Individual purchasers split between price-sensitive online wellness buyers and reimbursement-qualifying patients accessing pharmacy networks. German statutory insurance expansion is elevating the latter segment's commercial weight.
- Healthcare Providers:Neurologists, pain specialists, and oncology prescribers in Germany and the Netherlands drive pharmaceutical-grade oil demand through formulary inclusion decisions.
- Retailers:Health food chains and beauty retailers across Northern Europe negotiate white-label supply agreements with certified organic extractors.
- Manufacturers:Cosmetics formulators and beverage companies source toll-manufactured CBD to bypass capital-intensive extraction infrastructure.
Healthcare providers command pricing power; manufacturers represent the fastest-climbing procurement segment as toll partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's CBD production concentrates in Northern European hemp cultivation belts, while consumption gravitates toward Germany's pharmacy networks and the UK's wellness retail corridors. This geographic split shapes cross-border supply chain configurations and regulatory compliance investments.
Germany
Pharmacy distribution channels dominate CBD procurement, with statutory health insurance reimbursement eligibility expanding for epilepsy and chronic pain indications. The Federal Institute for Drugs and Medical Devices (BfArM) oversees medical cannabis licensing under the Cannabis Agency framework. Cologne and Berlin host the densest clusters of pharmaceutical-grade extraction facilities serving Apotheke networks.
United Kingdom
Wellness-oriented consumers drive demand through direct-to-online platforms and health food retail chains. The Food Standards Agency maintains the Novel Food authorization pathway for ingestible CBD products. London and the Southeast corridor concentrate white-label cosmetics formulators sourcing toll-manufactured extracts.
Netherlands
Medical cannabis distributors leverage centralized hospital pharmacy compounding capabilities for therapeutic-grade oils. The Office of Medicinal Cannabis regulates cultivation quotas and quality standards under the Opium Act exemptions. The Randstad region, particularly Rotterdam and The Hague, anchors supercritical CO2 extraction infrastructure.
Switzerland
Cosmetics manufacturers exploit the 1% THC threshold advantage over EU standards to develop premium skincare formulations. Swissmedic oversees pharmaceutical applications while cosmetic claims face lighter cantonal enforcement. The Zurich-Geneva axis hosts certified organic extraction partnerships supplying Nordic beauty brands.
Italy
Industrial hemp processors supply biomass to Northern European extractors while domestic cosmetic brands integrate CBD into regional beauty products. The Ministry of Health applies variable enforcement intensity to THC testing protocols across member states. Emilia-Romagna and Lombardy concentrate cultivation cooperatives and toll manufacturing arrangements.
Europe Cannabidiol (CBD) Market Competitive Landscape
Top-tier vendors anchor pharmacy and medical channels, while mid-scale specialists populate cosmetics and white-label supply tiers. The vendor base splits between vertically integrated cultivator-extractors and toll-manufacturing intermediaries. Three archetypes dominate: certified organic extraction specialists, pharmaceutical-grade oil formulators, and toll manufacturing partners. Competitive moves concentrate on Novel Food dossier preparation capabilities and pharmacy channel reimbursement eligibility.
Among Northern European extraction specialists, Endoca, Cibdol, and Essentia Pura occupy distinct positioning vectors. Endoca represents the certified organic infrastructure archetype, anchoring supply relationships with major beauty brands. Cibdol exemplifies pharmaceutical-grade formulation specialization aligned with stringent EFSA authorization requirements. Essentia Pura sits within the toll manufacturing tier, enabling cosmetics clients to bypass capital-intensive extraction investments through white-label partnerships.
| Leading Market Players |
|---|
| Aurora Cannabis |
| Endoca |
| Candropharm |
| Formula Swiss |
| Cibdol |
| Canopy Growth Corporation |
| Essentia Pura |
| Elixinol |
| Tilray |
| Others |
Supply & Pricing Matrix
German pharmacy networks and cosmetics formulators concentrate procurement power across distinct CBD tiers, with reimbursement eligibility in medical channels anchoring premium pricing while white-label cosmetics contracts compete on volume scale.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade oils accelerates because EFSA Novel Food dossier preparation drains capital from smaller extractors unable to amortize compliance across scale. Three-tier pricing structure across pharmaceutical, certified organic, and industrial grades separates pharmacy-reimbursed tinctures from toll-manufactured cosmetics inputs and bulk isolate commodities. Price differentiation rests on extraction method certification—supercritical CO2 commands premium over ethanol winterization—and organic accreditation status. Nutraceutical direct-to-consumer buyers exhibit highest price sensitivity; German statutory insurance patients show lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Return flows of non-conforming biomass from Northern European processors to Baltic cultivators create reverse-logistics cost layers that compress margins for organic-certified suppliers. Supply concentrates in the Netherlands, Germany, and Switzerland for supercritical CO2 extraction infrastructure, while Italy and Poland feed raw hemp biomass upstream. Critical dependencies include organic hemp cultivation acreage, pharmaceutical-grade CO2 equipment, and winterization solvent supplies. Single-source vulnerability sits with supercritical equipment manufacturers in Germany and the Netherlands. Distribution runs through pharmacy wholesalers for medical tiers and toll-manufacturing intermediaries for cosmetics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic extraction capacity scarcity props pricing power for incumbent processors, constraining volume expansion for cosmetics brands dependent on toll partnerships.
For Market Incumbents: Anticipate margin compression from EFSA Novel Food authorization delays by securing backward integration into Baltic organic cultivation. Defend pharmacy channel positioning through BfArM licensing investments before EU Cannabis Agency framework transposition accelerates competitor entry. For New Entrants and Emerging Players: EMA guidance on cannabinoid-based therapeutics in Germany opens a window for pharmaceutical-grade oil specialization bypassing crowded nutraceutical e-commerce. Target white-label cosmetics supply to Nordic beauty brands seeking Swiss-certified organic extraction partnerships. For Investors and Strategic Acquirers: The window for entry favors toll-manufacturing intermediaries with EFSA dossier capabilities and established pharmacy wholesaler relationships. Monitor EFSA opinion finalization on CBD safety as inflection signal for ingestible channel unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Dossier Preparation | EFSA-compliant safety submissions determine market access for ingestible CBD categories. |
| Pharmacy Channel Integration | BfArM licensing and German statutory insurance reimbursement eligibility lock in therapeutic volume. |
| Organic Certification Investment | EU organic accreditation commands shelf-space premiums across Nordic cosmetics retail. |
| Toll Manufacturing Partnership | White-label supply agreements allow beauty brands to bypass capital-intensive extraction infrastructure. |
| Supercritical CO2 Capacity Expansion | Pharmaceutical-grade purity standards displace legacy ethanol processors in medical channels. |
Research Methodology
EMA guidance documents, EFSA Novel Food submissions, and BfArM licensing records formed the secondary backbone, cross-referenced against primary interviews with extraction facility operators, cosmetics formulators, pharmacy procurement managers, and regulatory affairs consultants. Bottom-up volume estimates from hemp biomass cultivation data and top-down market sizing from pharmacy dispensing records were triangulated to anchor projections.
Historical trendline analysis of medical cannabis reimbursement expansion and cosmetics CBD incorporation rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application vertical, distribution channel tier, and national regulatory cluster. CAGRs were derived from elasticity analysis of pharmacy volume growth and cosmetics white-label contract expansion, incorporating EFSA opinion timeline scenarios and EU Cannabis Agency implementation pacing.
Caveats apply where EFSA safety opinion delays, member-state THC threshold enforcement divergence, or organic hemp yield volatility could materially shift the outlook. Practitioners should monitor EFSA publication schedules and German statutory insurance formulary updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Trichome Separator/Extractor Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Europe Medical Cannabis Market
Cannabis/Marijuana
Global Cannabis Market
Cannabis/Marijuana
Global Marijuana Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
CBD Oil Market