
 Cannabis Vaporizers Market | 2026-2036
Cannabis Vaporizers Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Vaporizers Market Analysis
Medical users is consolidating as the fastest-expanding end-use vertical as clinic networks in Germany and Canada broaden patient access programs. Pax Labs Inc. leverages its technology leadership in precision temperature control to sustain premium positioning across North American dispensaries. Storz & Bickel GmbH & Co. KG anchors the medical-grade segment with convection-based hardware that meets strict clinic procurement standards. Firefly Vapor LLC differentiates through on-demand heating architecture that competes directly with session-style alternatives in the recreational channel.
Cannabis vaporizers are electronic inhalation devices that heat dried flower, oil, or concentrate to temperatures between 160°C and 230°C to release active cannabinoids without combustion, producing an aerosol rather than smoke for pulmonary delivery. The devices employ either conductive metal chambers, convective hot air streams, or hybrid systems with digital thermostats to regulate output consistency and preserve terpene profiles. Portable vaporizers occupy the largest volume tier as battery chemistry improvements shrink device footprints while extending session counts per charge. Desktop units retain the highest margin pools among product type categories due to their precision engineering and lower price sensitivity among medical users. Convection heating technology leads the technology dimension for flavor preservation, though hybrid heating systems are gaining traction among recreational users seeking faster heat-up times without sacrificing vapor quality.
The FDA regulates cannabis vaporizer hardware under tobacco product authority extensions, while state-level cannabis commissions in California, Colorado, and Michigan impose additional testing and labeling mandates that shape market access conditions. The EPA monitors battery disposal pathways for lithium-ion cells embedded in portable units, creating compliance obligations that favor manufacturers with established recycling partnerships. Stakeholders must monitor how evolving heavy metals testing standards from state cannabis agencies interact with federal device safety frameworks to determine which product architectures can clear dual compliance thresholds.
Market Dynamics
Clinic procurement networks in Germany and Canada are consolidating purchase volumes, forcing hardware manufacturers to adapt device specifications to institutional tender requirements rather than individual consumer preferences.
Growth Catalysts
- Medical Access Expansion:Germany's clinic network procurement standards now mandate precision temperature documentation, pulling device upgrades across the supply chain.
- Battery Chemistry Advances:Lithium-ion cell energy density improvements are shrinking portable unit footprints while extending session counts per charge.
- REACH Compliance Alignment:European hardware importers are leveraging RoHS and REACH testing reciprocity to streamline multi-market entry pathways.
Market Restraints
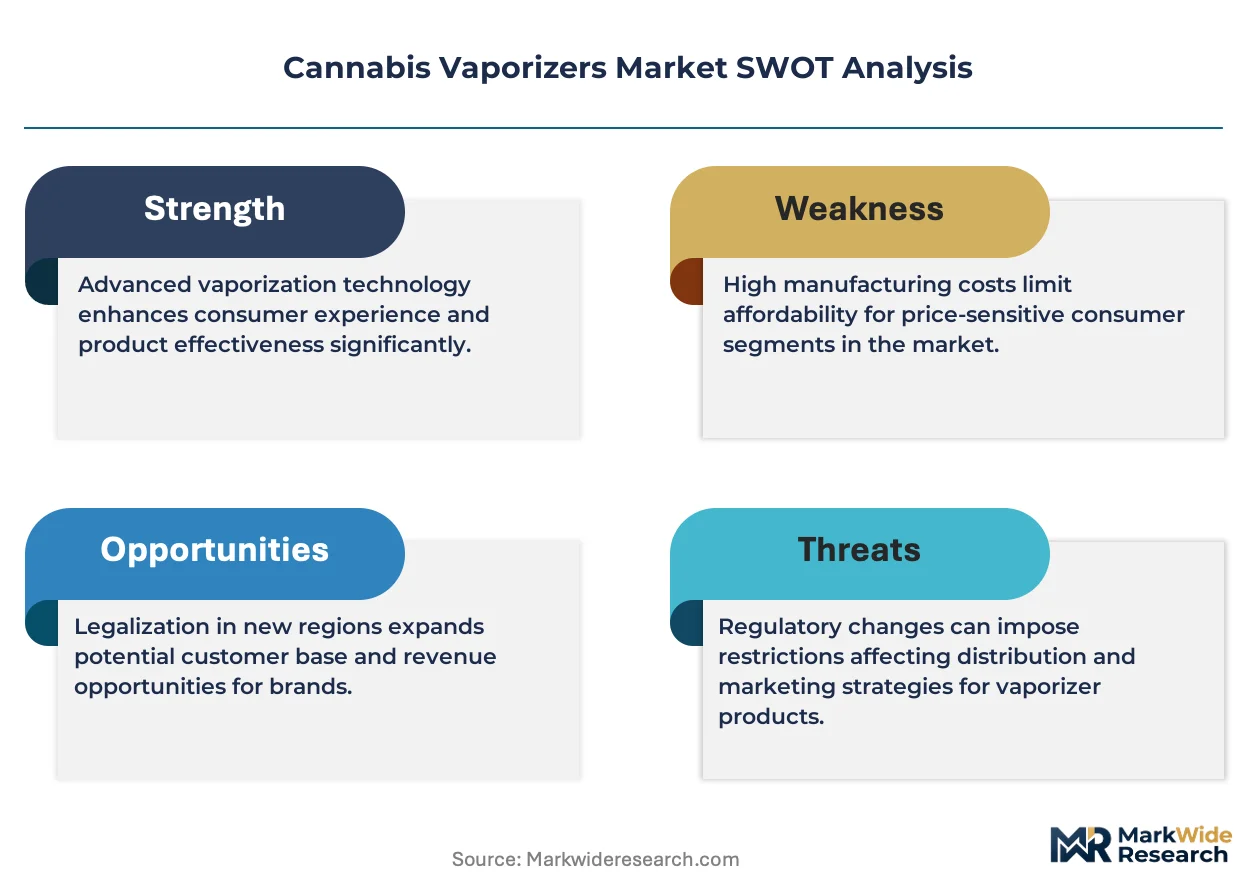
- FDA Enforcement Uncertainty:The agency's evolving posture on unapproved vaping devices creates documentation burdens that favor capital-rich manufacturers with dedicated compliance teams.
- Heavy Metals Testing Fragmentation:California, Colorado, and Michigan impose non-harmonized testing mandates that multiply certification costs for multi-state suppliers.
- Desktop Unit Substitution:High-performance portable units are capturing margin pools previously reserved for precision-engineered stationary devices in medical settings.
Strategic Opportunities
- Recycling Partnership Integration:The EPA's lithium-ion disposal monitoring creates first-mover advantages for manufacturers with established reverse logistics infrastructure.
- Hybrid Heating Architecture:Convection-conduction systems are opening recreational channel segments that prioritize heat-up speed without vapor quality sacrifice.
- Dispensary Channel Concentration:California's regulated retail network is raising barriers for unverified hardware brands, creating shelf-space scarcity value for compliant suppliers.
Industry Challenges
- Dual Compliance Architecture:Manufacturers must engineer products that satisfy both FDA device safety frameworks and state-level cannabis agency heavy metals standards simultaneously.
- Terpene Preservation Engineering:Medical-grade convection systems require specialized thermal engineering talent that concentrates in German and Swiss precision manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Vaporizers Market |
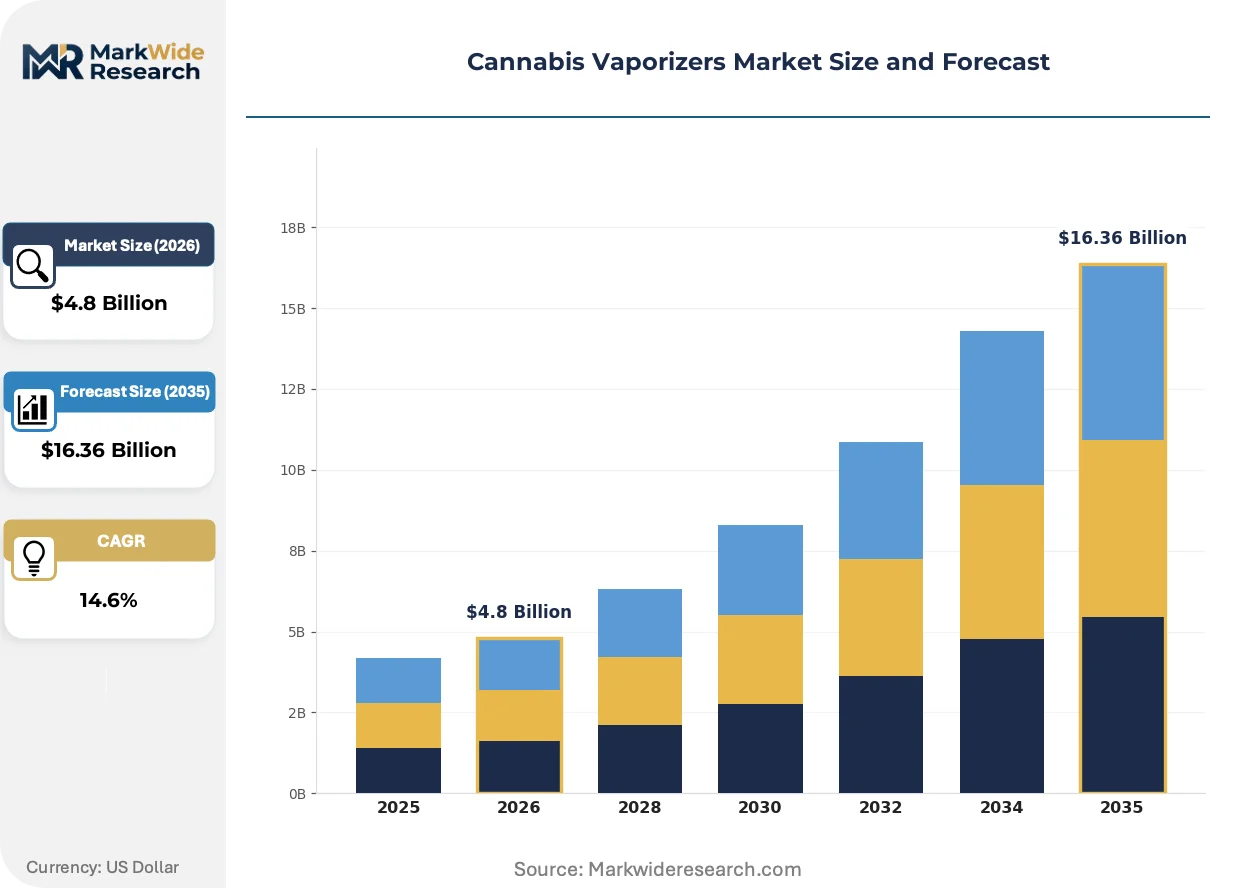
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Vaporizers, Desktop Vaporizers, Concentrate Vaporizers, Hybrid Vaporizers Technology: Convection Heating, Conduction Heating, Hybrid Heating, Digital Temperature Control End User: Medical Users, Recreational Users, Retail Consumers, Dispensaries Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Vape Shops |
| Companies Covered | Firefly Vapor LLC, Arizer Technologies Inc., Pax Labs Inc., Grenco Science Inc., Dr. Dabber Inc., Storz & Bickel GmbH & Co. KG, Boundless Technology LLC, Cloudious9 Inc., Greenlane Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Vaporizers Market Emerging Trajectories
Hardware architecture is pivoting from session-based to on-demand heating systems as user behavior fragments across medical protocol adherence and recreational spontaneity. This shift is compressing development cycles and rewiring supply chain priorities.
Hybrid heating systems combining conductive chambers with convective air streams are converging with demand from recreational users seeking faster heat-up times without sacrificing vapor quality. California dispensary buyers are specifying these architectures in procurement tenders at accelerating frequency. The technology is converging with session-style alternatives to create a middle-tier product category that captures price-sensitive premium demand.
The FDA's extension of tobacco product authority to cannabis vaporizer hardware is forcing manufacturers to tighten quality documentation and adverse event reporting protocols. State cannabis commissions in California, Colorado, and Michigan are layering additional testing mandates that create overlapping compliance obligations. Medical device suppliers with existing FDA relationships are repurposing quality management systems to address this dual framework.
Buyer concentration within Germany's expanding clinic networks is compressing procurement decision cycles from individual patient choice to institutional tender processes. Dispensary channel buyers in California are unbundling after-sales service expectations, demanding replaceable component architectures rather than integrated disposable units. This behavioral shift is most visible in medical-use verticals where total cost of ownership calculations now dominate capital expenditure approvals.
Cannabis Vaporizers Market Segmentation
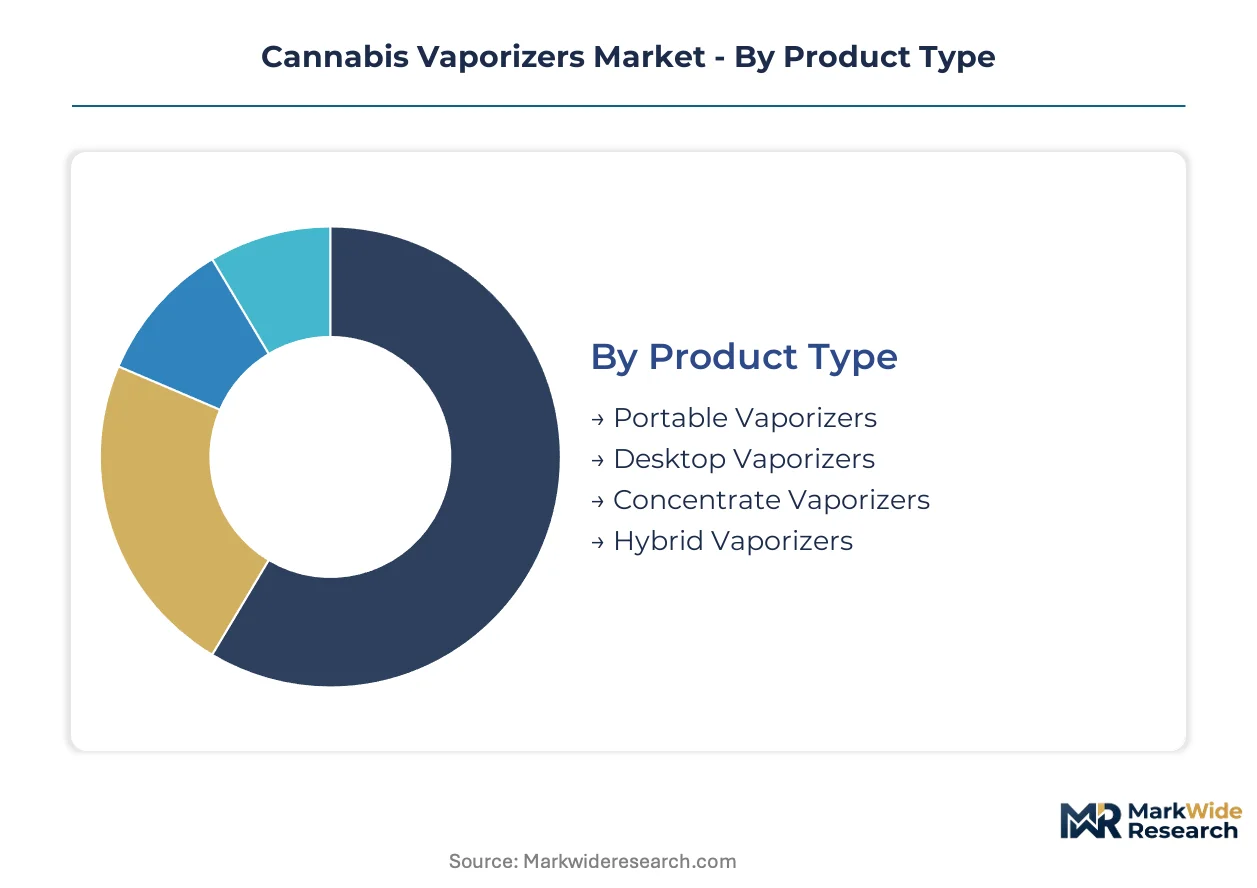
Segmentation in cannabis vaporizers reveals how hardware architectures align with divergent user protocols. Medical procurement networks favor precision-engineered stationary units, while recreational channels prioritize portability and rapid heat-up performance.
Product Type:
Portable units dominate unit volumes through battery chemistry advances, yet desktop systems command premium pricing pools in institutional settings.
- Portable Vaporizers:These handheld devices employ lithium-ion cells and conductive or hybrid heating chambers to deliver 8-15 sessions per charge. Demand concentrates in California's regulated dispensary channel where convenience-oriented recreational users drive replacement cycles. Battery energy density improvements continue shrinking device footprints without sacrificing thermal output consistency.
- Desktop Vaporizers:Stationary units feature precision convection heating and digital thermostats optimized for extended session protocols. Germany's expanding clinic networks now mandate these systems for patient access programs requiring documented temperature accuracy. The medical-grade segment rewards engineering depth with sustained margin premiums despite lower shipment volumes.
- Concentrate Vaporizers:Specialized hardware for oil and wax formulations employs ceramic or quartz atomization chambers.
- Hybrid Vaporizers:Dual-purpose architectures accommodating both flower and concentrate formats are gaining traction among multi-format users.
Today's leader: Portable Vaporizers. Tomorrow's challenger: Desktop Vaporizers.
Technology:
Heating methodology determines vapor quality, session efficiency, and regulatory compliance pathways across end-use verticals.
- Convection Heating:Hot air stream systems preserve terpene profiles through indirect thermal transfer without conductive surface contact. Medical users in Canada specify convection architectures for clinic procurement tenders requiring flavor fidelity and precise cannabinoid release curves. Swiss and German precision manufacturing clusters concentrate specialized thermal engineering talent for this segment.
- Hybrid Heating:Combined conductive-convective systems accelerate heat-up times while maintaining vapor quality thresholds. California dispensary buyers increasingly specify hybrid architectures in procurement tenders as recreational users reject session-style delays. The technology bridges medical precision expectations with recreational spontaneity preferences.
- Conduction Heating:Direct chamber contact systems offer simpler manufacturing and faster initial heat-up.
- Digital Temperature Control:Microprocessor-regulated thermostats enable precise output documentation for compliance frameworks.
Convection Heating anchors medical procurement standards. Hybrid Heating is gaining share fastest in recreational channels.
End User:
User category determines device specification priorities, from clinical protocol adherence to discretionary consumption patterns.
- Medical Users:Patients under clinician supervision require hardware with documented temperature accuracy, adverse event reporting compatibility, and institutional procurement certification. Germany's clinic network expansion is consolidating purchase volumes into tender processes that favor established medical device suppliers. Total cost of ownership calculations now dominate capital expenditure approvals over individual patient preference.
- Dispensaries:Regulated retail buyers in California and Colorado unbundle after-sales service expectations, demanding replaceable component architectures rather than integrated disposable units. Channel concentration raises barriers for unverified hardware brands, creating shelf-space scarcity value for compliant suppliers with established quality documentation.
- Recreational Users:Discretionary consumers prioritize portability, rapid heat-up, and aesthetic differentiation.
- Retail Consumers:General merchandise purchasers exhibit higher price sensitivity and lower technical specification engagement.
Medical Users concentrate procurement decision power. Dispensaries are rewiring distribution economics.
Distribution Channel:
Channel structure determines compliance burden intensity and customer education requirements for hardware differentiation.
- Online Retail:Direct-to-consumer platforms enable manufacturers to control product education and warranty service relationships. The FDA's evolving enforcement posture on unapproved vaping devices creates documentation burdens that favor capital-rich manufacturers with dedicated compliance teams capable of navigating federal and state framework overlaps.
- Specialty Stores:Cannabis-focused retailers provide hands-on demonstration and technical consultation that justifies premium positioning. California's regulated dispensary network concentrates demand in compliant channels where product testing mandates have eliminated unverified competitors.
- Vape Shops:Dedicated inhalation device retailers serve experienced users seeking component-level customization.
- Mass Merchandisers:General retail chains impose volume scale and price compression requirements.
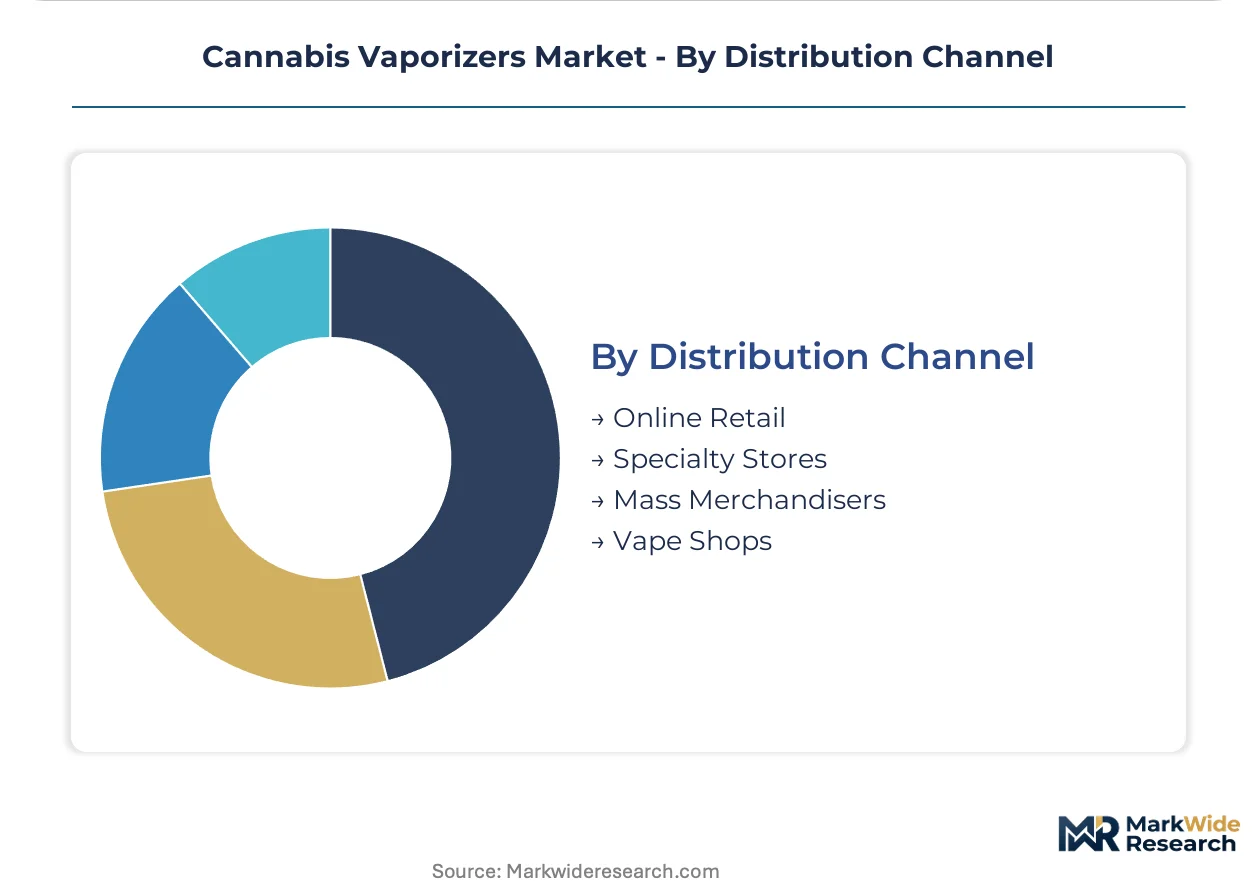
Specialty Stores capture premium positioning. Online Retail is expanding fastest as compliance documentation standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly operations to jurisdictions with lighter documentation burdens, exploiting cost-of-compliance gaps between federal frameworks and state-level cannabis agency mandates. This arbitrage is redrawing supply chain maps as capital-rich firms absorb multi-market certification costs while smaller competitors retreat to single-jurisdiction footprints.
United States
California's regulated dispensary channel concentrates demand for tested hardware, with product safety mandates eliminating unverified competitors from retail shelves. The FDA's evolving enforcement posture on unapproved vaping devices creates documentation burdens that favor manufacturers with dedicated compliance teams in San Francisco and Los Angeles. Precision engineering talent clusters in Silicon Valley are migrating toward medical-grade device architectures to serve clinic procurement networks.
Germany
Expanding clinic networks are consolidating purchase volumes into institutional tender processes that mandate precision temperature documentation and adverse event reporting compatibility. REACH and RoHS testing reciprocity streamlines multi-market entry for hardware importers, while BfArM oversight shapes medical device classification pathways. Stuttgart and Munich precision manufacturing clusters supply specialized thermal engineering talent for convection-based medical systems.
Canada
Health Canada's medical cannabis framework drives institutional procurement standards that favor hardware with documented cannabinoid release curves and flavor fidelity metrics. Clinic network expansion in Ontario and British Columbia is compressing decision cycles from individual patient choice to capital expenditure approvals based on total cost of ownership. Toronto's medical device engineering base is repurposing quality management systems to address dual FDA-Health Canada compliance thresholds.
Switzerland
Swissmedic's medical device oversight intersects with cantonal cannabis pilot programs to create a regulated testing ground for precision hardware. Zurich and Basel precision manufacturing clusters concentrate specialized talent for terpene preservation engineering that German and Canadian clinic networks specify in tenders. The country's neutrality in regulatory harmonization efforts positions it as a bridge jurisdiction for multi-market certification strategies.
United Kingdom
The MHRA's post-Brexit device safety framework is diverging from EU MDR alignment, creating certification complexity for hardware suppliers serving both markets. London's financial and regulatory consulting infrastructure supports manufacturers navigating overlapping FDA, MHRA, and emerging UK cannabis agency mandates. The city's position as a European headquarters hub concentrates compliance strategy functions for firms with multi-continental footprints.
Cannabis Vaporizers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical procurement networks favoring established device suppliers while recreational channels accommodate private-label entrants. The vendor base concentrates around three strategic archetypes: precision-engineered medical-grade specialists, convenience-optimized portable manufacturers, and hybrid-architecture innovators bridging both use cases. Competitive moves center on recycling partnership integration for EPA lithium-ion compliance and backward integration into ceramic atomization chamber production to secure component supply.
Within the medical-grade tier, Storz & Bickel GmbH & Co. KG anchors institutional procurement standards with German-engineered convection systems, while Pax Labs Inc. occupies a position across North American premium dispensary channels through precision temperature control positioning. Firefly Vapor LLC exemplifies the on-demand heating architecture competing for recreational spontaneity preferences against session-style alternatives.
| Leading Market Players |
|---|
| Firefly Vapor LLC |
| Arizer Technologies Inc. |
| Pax Labs Inc. |
| Grenco Science Inc. |
| Dr. Dabber Inc. |
| Storz & Bickel GmbH & Co. KG |
| Boundless Technology LLC |
| Cloudious9 Inc. |
| Greenlane Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Germany's clinic network procurement consolidation is mandating precision temperature documentation and adverse event reporting compatibility, forcing manufacturers to absorb specialized thermal engineering costs that stratify pricing across medical-grade and recreational tiers.
Pricing Analysis
Dispensary margin layers in California's regulated channel absorb testing and certification costs that unverified brands cannot pass through, compressing retail markups for compliant suppliers. Three-tier pricing structure across premium, standard, and economy levels separates convection-based medical systems from hybrid recreational units and basic conduction alternatives. Price differentiation hinges on FDA documentation depth and REACH testing reciprocity status. Cost compression in the portable segment is intensifying as battery chemistry advances commoditize thermal performance. Recreational users exhibit highest price sensitivity, while institutional medical procurement prioritizes total cost of ownership over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore handle European and Asia-Pacific hardware flows, with hub-and-spoke patterns radiating from California for North American dispensary fulfillment. Manufacturing concentrates in Germany, China, and Switzerland, with Stuttgart and Munich clusters supplying precision thermal components and Shenzhen handling lithium-ion cell integration and conductive chamber fabrication. Component sourcing draws from ceramic atomization specialists in Japan, quartz suppliers in the United States, and microprocessor vendors in Taiwan. Single-source vulnerability in Swiss terpene preservation engineering talent creates bottleneck risk for medical-grade convection systems. Distribution runs through compliant specialty stores and direct-to-consumer platforms with FDA documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery chemistry cost-down curves and medical procurement premium-tier specification shifts are expanding margin pools for manufacturers with dual FDA-state compliance architectures.
For Market Incumbents: Acquire specialized thermal engineering talent clusters in Germany and Switzerland to defend medical-grade positioning against portable unit substitution. Build backward integration into ceramic atomization chamber production to secure component supply against quartz price volatility. Channel control through exclusive dispensary partnerships in California creates defensive moats against unverified competitors. For New Entrants and Emerging Players: Begin with hybrid heating architecture development targeting California recreational users seeking faster heat-up without vapor quality sacrifice. White-space exists in EPA-compliant lithium-ion reverse logistics infrastructure, where first-mover recycling partnerships unlock shelf access. Concentrate vaporizer formats for oil and wax remain underpenetrated in Canadian clinic networks relative to flower systems. For Investors and Strategic Acquirers: Asymmetric upside sits with medical device suppliers repurposing FDA quality management systems for dual cannabis-tobacco compliance frameworks. Five-to-ten year viability favors firms with established BfArM and Health Canada institutional relationships over recreational-only brands. Watch for heavy metals testing harmonization signals between California, Colorado, and Michigan as inflection indicator for multi-state supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Heating Architecture Development | Captures California dispensary demand bridging medical precision with recreational spontaneity preferences. |
| REACH and RoHS Testing Reciprocity Investment | Streamlines multi-market entry for European hardware importers facing fragmented state mandates. |
| Lithium-Ion Reverse Logistics Partnership | Creates EPA compliance advantage and shelf-space scarcity value in regulated channels. |
| Precision Temperature Documentation Systems | Meets Germany's clinic network tender requirements for institutional procurement certification. |
| Ceramic Atomization Chamber Backward Integration | Secures supply chain control over concentrate vaporizer component sourcing from Japanese specialists. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hardware engineering directors, dispensary procurement managers, clinic network administrators, and regulatory affairs specialists at FDA-registered device firms with secondary validation against FDA 510(k) filings, state cannabis commission testing mandate databases, EPA lithium-ion disposal guidance documents, and BfArM medical device classification registers. Bottom-up shipment data from precision manufacturing clusters in Stuttgart, Munich, and Basel triangulated against top-down channel flow estimates.
Segment-weighting approaches distributed value and volume across product type, heating technology, end-user category, and distribution channel dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to medical access expansion rates, battery energy density improvement trajectories, and regulatory enforcement intensity indices. Forecast inputs included clinic network penetration assumptions for Germany and Canada, plus dispensary channel concentration metrics for California.
Several conditions sit outside the modeled scope, including potential FDA enforcement reversals, harmonization of heavy metals testing standards across state cannabis agencies, and breakthrough solid-state battery commercialization timelines. Forecast outputs reflect documented assumptions about procurement behavior continuity and regulatory framework stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
CBD Pouches Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Australia Legal Cannabis Market