
 Credit Insurance Market | 2026-2036
Credit Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Insurance Market Intelligence
Mid-sized enterprises with cross-border receivables is rotating toward structured credit insurance programs as open-account trade terms lengthen. Allianz Trade leverages proprietary buyer risk databases to price policies across fragmented supplier bases. Coface anchors its competitive position through public-private partnership frameworks in emerging economies. Atradius specializes in single-risk underwriting for capital goods exporters with concentrated buyer exposure.
Credit insurance is a risk transfer mechanism indemnifying sellers against buyer default or protracted payment delay, typically covering commercial and political risks on trade receivables with policy tenors ranging from ninety days to multiyear frameworks. Whole turnover policies dominate premium volume by covering entire receivable portfolios, while single risk coverage commands higher margins on bespoke transactions for project finance and capital equipment shipments. Trade credit coverage leads absolute premium generation across the coverage type dimension, though political risk attachment is expanding fastest in regions with sovereign stress and currency convertibility concerns.
Solvency II in Europe, state-level insurance commissioners in the United States, and the China Banking and Insurance Regulatory Commission impose capital adequacy and reserving standards that directly constrain product leverage and geographic deployment capacity. The EU Green Deal taxonomy and emerging climate risk disclosure mandates are beginning to filter into credit risk assessments for carbon-intensive supply chains. Stakeholders must monitor how regulatory divergence between jurisdictions fragments policy standardization and elevates compliance costs for multinational programs.
Market Dynamics
Supply chain finance digitization is compressing underwriting cycles and forcing insurers to embed real-time risk monitoring into policy structures. This structural shift is redistributing competitive advantage toward carriers with proprietary data infrastructure and API-native distribution platforms.
Growth Catalysts
- Solvency II capital frameworks:Risk-based capital requirements in Europe are standardizing product design and expanding addressable market depth for compliant carriers.
- Mid-sized exporters:Cross-border receivables growth in emerging markets is accelerating structured credit insurance uptake as open-account terms lengthen.
- Blockchain-enabled trade documentation:Smart contract automation is decomposing manual verification bottlenecks and shrinking policy issuance timelines.
Market Restraints
- Sovereign risk concentration:Political risk attachment in stressed jurisdictions is elevating loss ratios and constraining deployment capacity.
- Reinsurance capacity tightening:Catastrophe bond spreads and retrocession pricing are transmitting upward pressure to primary policy rates.
- Alternative risk transfer instruments:Trade receivables securitization and supply chain finance platforms are capturing premium flow from traditional indemnity structures.
Strategic Opportunities
- India's manufacturing corridors:Underpenetrated mid-market exporter bases linking Gujarat and Tamil Nadu to ASEAN hubs present white-space expansion potential.
- EU Green Deal taxonomy:Climate risk disclosure mandates are creating attachable coverage modules for carbon-intensive supply chain exposures.
- Embedded distribution partnerships:API integration with enterprise resource planning systems is opening direct-to-finance-channel placement routes.
Industry Challenges
- Data science talent scarcity:Underwriting teams lack sufficient machine learning expertise to operationalize alternative data streams for buyer risk scoring.
- Legacy core system fragmentation:Policy administration platforms built on decades-old architectures resist real-time data ingestion and automated claims adjudication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Insurance Market |
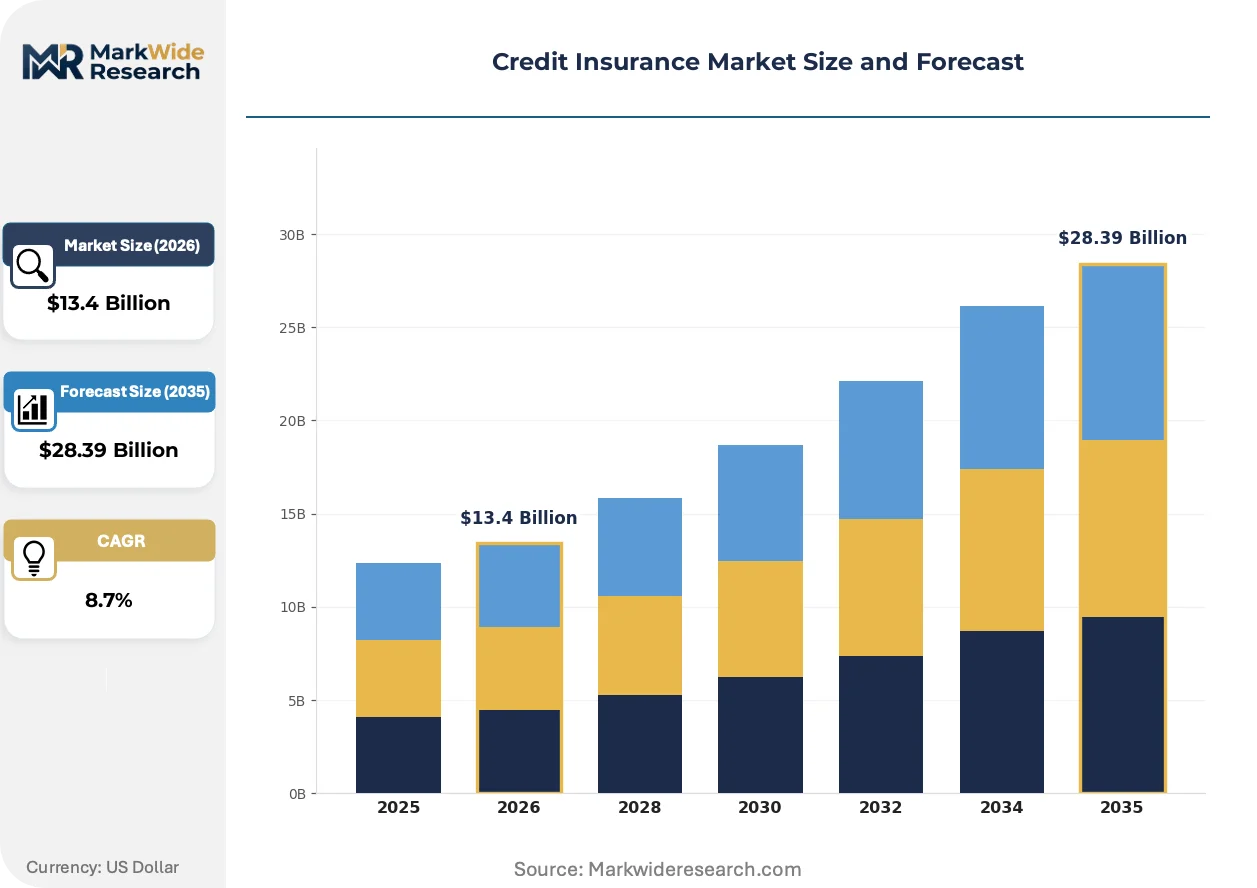
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $28.39 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Whole Turnover, Single Risk, Buyer Risk, Non-Cancelable Industry Vertical: Manufacturing, Wholesale, Retail, Services Coverage Type: Trade Credit, Political Risk, Credit Default, Business Interruption Client Size: Small Enterprises, Medium Enterprises, Large Corporations, Multinational Firms |
| Companies Covered | Allianz Trade, Atradius, Coface, American International Group, QBE Insurance Group, Chubb, Aon, Zurich Insurance Group, AXA XL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Insurance Market Strategic Shifts & Innovations
Artificial intelligence is decomposing traditional underwriting workflows and enabling dynamic risk pricing that responds to trade flow volatility in near-real time. This technological inflection is compressing carrier response windows and elevating data infrastructure to core competitive infrastructure.
Machine learning algorithms trained on proprietary buyer databases are decomposing static credit limit assignment into continuous monitoring protocols. Mid-sized exporters with fragmented supplier bases are adopting these tools fastest. The structural consequence is a compression in manual underwriting headcount and a shift toward algorithmic portfolio management.
CSRD disclosure requirements in Europe are mandating granular supply chain risk reporting that directly implicates trade credit exposure. Large corporates must now document counterparty default probabilities and geographic concentration metrics. Capital goods exporters with concentrated buyer books face the steepest compliance burden and are accelerating policy standardization to satisfy audit trails.
Buyer-side risk transfer preferences are rotating toward multiyear frameworks with embedded political risk attachment. Open-account trade terms exceeding one hundred twenty days are becoming standard in China-India-Southeast Asia corridors. This behavioral shift is visible most acutely among automotive component suppliers and capital equipment manufacturers with limited bargaining leverage against anchor buyers.
Credit Insurance Market Segmentation
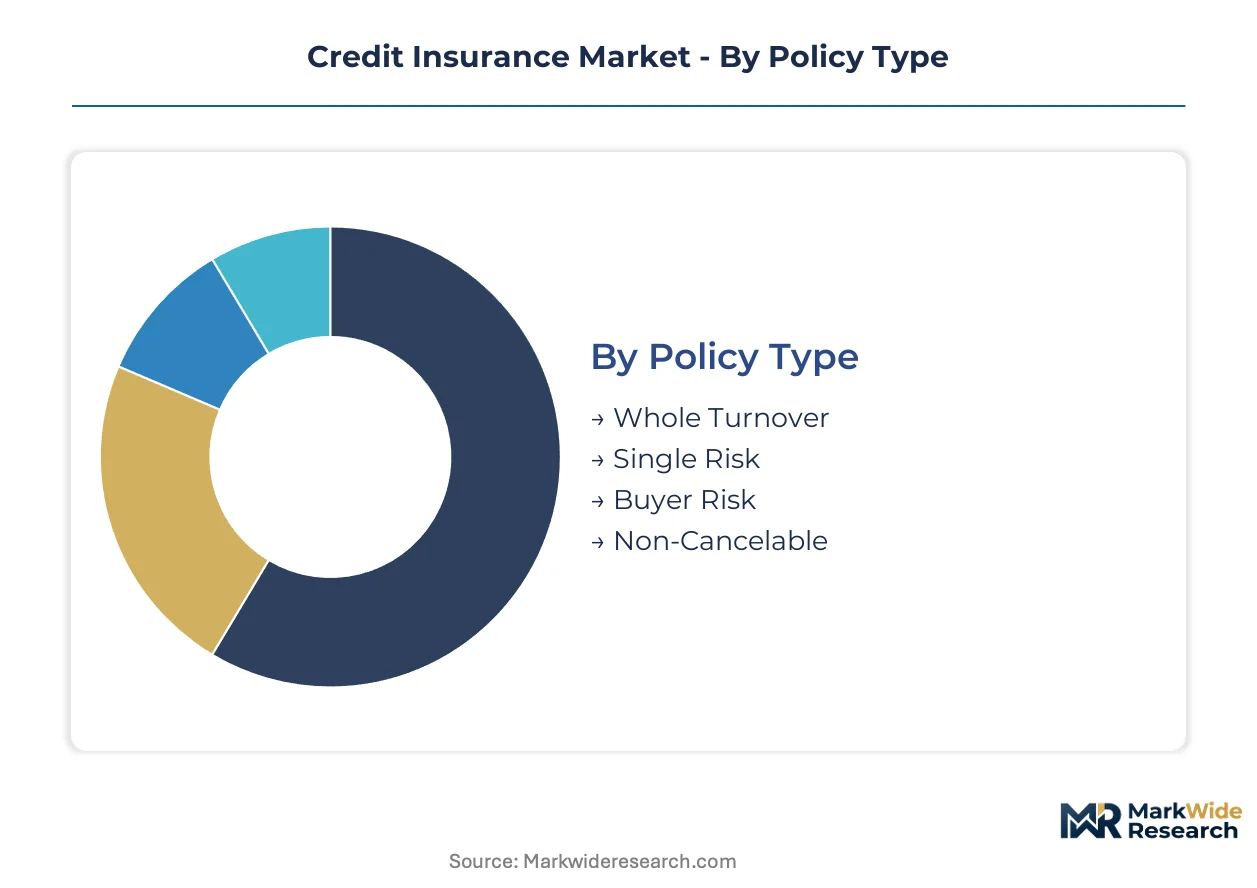
Credit insurance segmentation reveals how risk transfer instruments align with distinct commercial exposures and distribution economics. Policy structures vary dramatically by buyer concentration, trade corridor volatility, and balance sheet capacity of insured parties.
Policy Type:
Whole turnover policies flow through broker networks serving mid-market portfolios, while single risk coverage routes through specialist underwriters handling bespoke capital equipment transactions.
- Whole Turnover:Comprehensive portfolio coverage indemnifying sellers against default across entire receivable books. Demand concentrates among German and French mid-sized exporters with fragmented buyer bases and Solvency II-mandated risk management protocols.
- Single Risk:Bespoke underwriting for concentrated exposures on large capital goods shipments or project finance transactions. Indian and Vietnamese infrastructure equipment manufacturers with limited buyer diversification drive placement volume through direct carrier relationships.
- Buyer Risk:Named-buyer coverage attaching to specific counterparty default events.
- Non-Cancelable:Irrevocable policy terms guaranteeing coverage continuity through credit deterioration cycles.
Whole turnover dominates installed base. Single risk is where expansion concentrates.
Industry Vertical:
Cost tier stratification separates premium-priced manufacturing coverage from commoditized retail programs with standardized terms.
- Manufacturing:Capital goods and automotive component suppliers with extended production cycles and concentrated buyer books. German machine tool exporters and Chinese EV battery suppliers represent the steepest expansion trajectory as open-account terms lengthen in Asia-Europe corridors.
- Wholesale:Commodity traders and distribution intermediaries with high-velocity receivable turnover.
- Retail:Consumer goods importers with seasonal inventory financing needs.
- Services:Professional and technical service exporters with intangible deliverable risks.
Manufacturing commands premium rate tiers. Wholesale delivers volume scale through standardized documentation.
Coverage Type:
Application-specific risk profiles distinguish commercial credit exposure from sovereign and macroeconomic perils requiring separate underwriting expertise.
- Trade Credit:Commercial risk indemnification against buyer insolvency or protracted payment default. Absolute premium generation leader across all coverage dimensions, with particular concentration in China-India-ASEAN manufacturing supply chains.
- Political Risk:Sovereign peril coverage for currency inconvertibility, expropriation, and war risks. Fastest-climbing attachment rate in stressed jurisdictions with elevated sovereign debt levels.
- Credit Default:Pure financial risk transfer without underlying goods or services nexus.
- Business Interruption:Contingent coverage for supply chain disruption cascading from counterparty failure.
Trade credit anchors premium volume. Political risk is gaining share fastest.
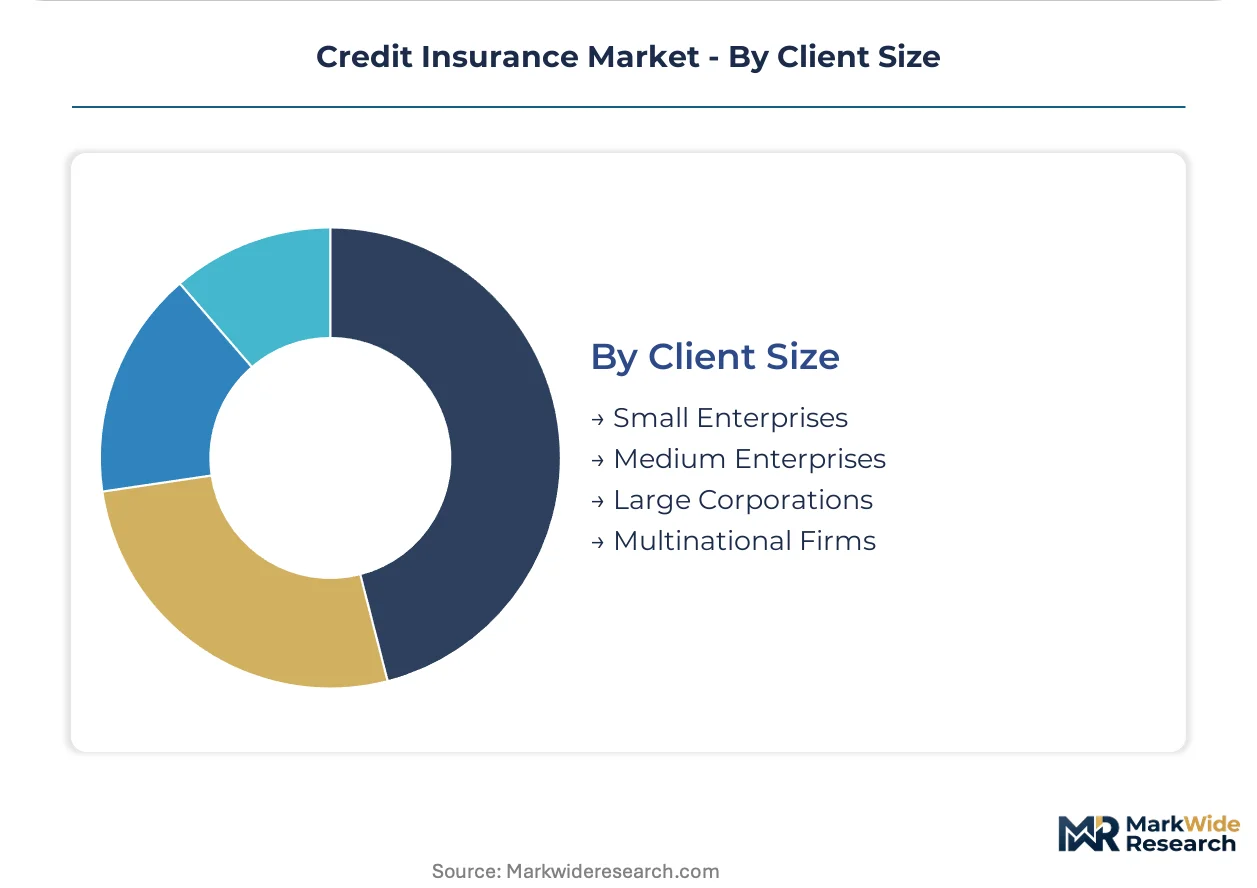
Client Size:
Customer-type segmentation maps policy complexity and service intensity to organizational sophistication and cross-border exposure scale.
- Small Enterprises:Standardized whole turnover programs with automated underwriting and limited policy customization. Indian and Indonesian export-oriented SMEs with first-time cross-border receivables drive digital platform adoption.
- Medium Enterprises:Structured programs combining portfolio coverage with selective single risk attachment. Fastest-expanding segment as supply chain digitization democratizes access to previously enterprise-grade risk analytics.
- Large Corporations:Multiline programs with captive insurance considerations and centralized risk management.
- Multinational Firms:Global master policies with local admitted paper and regulatory compliance across multiple jurisdictions.
Medium enterprises is climbing the fastest. Multinational firms retain deepest policy customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-India-ASEAN manufacturing corridors generate concentrated demand for trade credit coverage as open-account terms extend beyond 120 days. German and French mid-sized exporters anchor European premium volume under Solvency II compliance frameworks. Political risk attachment accelerates fastest across emerging market trade routes with sovereign stress indicators.
Germany
Machine tool exporters in Baden-Württemberg and North Rhine-Westphalia drive whole turnover policy adoption as receivable tenors lengthen with Asian buyers. Solvency II capital requirements from EIOPA standardize risk management protocols across Mittelstand portfolios. Munich and Frankfurt insurance clusters concentrate underwriting expertise for cross-border manufacturing exposures.
China
EV battery suppliers and automotive component manufacturers in Guangdong and Jiangsu provinces expand credit insurance placement as domestic overcapacity pushes exports toward India and Southeast Asia. SAMR insurance regulations and CBIRC capital adequacy frameworks constrain foreign carrier market access. Yangtze River Delta manufacturing hubs generate fastest-growing demand for multiyear political risk attachment.
India
Infrastructure equipment manufacturers in Gujarat and Tamil Nadu rotate toward single risk coverage for concentrated buyer books in ASEAN corridors. RBI prudential norms and IRDAI solvency regulations shape domestic carrier capacity deployment. Chennai and Ahmedabad industrial clusters exhibit steepest mid-market exporter uptake as supply chain finance digitizes.
United States
Commodity traders and energy equipment exporters in Texas and Louisiana expand trade credit placement as open-account terms extend with Latin American buyers. State-level insurance commissioners impose risk-based capital standards that vary by jurisdiction. Houston energy finance corridors concentrate specialist underwriter presence for project-related receivables.
Singapore
Regional trade finance platforms and commodity trading houses anchor Southeast Asian premium generation as China-ASEAN corridor volumes expand. MAS risk-based capital frameworks and trade finance disclosure mandates align with international standards. Marina Bay financial district concentrates captive insurance structuring and multinational program administration expertise.
Credit Insurance Market Key Industry Players
Listed leaders compete with private specialists across capital adequacy and data infrastructure dimensions. The carrier base concentrates around three dominant underwriting groups controlling proprietary buyer risk databases, while regional specialists occupy niche single-risk segments. Strategic archetypes include integrated trade credit-political risk underwriters, data-native digital platforms, and public-private partnership operators. Competitive intensity manifests through API distribution partnerships and real-time risk monitoring capability deployment.
Among integrated credit and political risk underwriters, Allianz Trade, Atradius, and Coface exemplify distinct geographic and product positioning archetypes. Allianz Trade occupies a position emphasizing proprietary database leverage across fragmented supplier bases. Atradius represents specialization in single-risk underwriting for capital goods exporters with concentrated buyer exposure. Coface anchors a public-private partnership model in emerging economy frameworks. These three carriers collectively illustrate how scale, specialization, and government relationship strategies segment competitive terrain.
| Leading Market Players |
|---|
| Allianz Trade |
| Atradius |
| Coface |
| American International Group |
| QBE Insurance Group |
| Chubb |
| Aon |
| Zurich Insurance Group |
| AXA XL |
| Others |
Cost & Logistics Intelligence
API-native distribution platforms displacing traditional broker networks simultaneously compresses commission structures and redistributes underwriting capacity toward carriers with proprietary data infrastructure. This substitution dynamic reshapes supply geography by concentrating risk-bearing capacity in Munich, Paris, and Singapore insurance clusters while pricing economics tilt toward algorithmic portfolio management fees over percentage-of-premium commissions.
Pricing Analysis
Legacy policy administration systems versus cloud-native underwriting engines versus blockchain-enabled smart contract platforms define the technology-generation pricing gap in credit insurance. Three-tier pricing structure across premium, standard, and economy levels separates multinational master policies with captive considerations from mid-market structured programs and automated whole turnover coverage for SMEs. Price differentiation rests on proprietary buyer database depth and real-time risk monitoring capability. Cost compression in the standard tier is intensifying as reinsurance capacity tightening transmits upward pressure from retrocession markets. Small enterprises exhibit highest price sensitivity due to thin margin profiles, while multinational firms prioritize coverage continuity over rate competition.
Supply Chain Analysis
Germany and France anchor primary underwriting capacity for European manufacturing exposures, while Singapore and Hong Kong concentrate trade finance platform administration for Asia-Pacific corridors. Raw material dependencies in this intangible risk transfer market center on proprietary buyer risk databases, actuarial modeling talent, and API distribution infrastructure. Single-source vulnerability in legacy core systems constrains real-time data ingestion capabilities across established carriers. Distribution runs through broker networks for whole turnover portfolios and direct carrier relationships for single risk placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Credit insurance penetration among mid-sized exporters in emerging markets remains below structural potential, creating runway for expansion as supply chain finance digitization accelerates policy standardization.
For Market Incumbents: Secure proprietary data infrastructure advantages by embedding machine learning expertise into underwriting teams before alternative data streams become table stakes. Defend against API-native distribution platforms by consolidating broker relationships through exclusive data-sharing arrangements. Capacity addition in Chennai and Ahmedabad industrial clusters captures mid-market exporter growth as Indian manufacturing corridors expand toward ASEAN hubs. For New Entrants and Emerging Players: Differentiate on real-time risk monitoring capabilities targeting mid-sized exporters with fragmented buyer bases currently underserved by legacy carriers. White-space expansion concentrates in India's Gujarat-Tamil Nadu manufacturing corridors linking to Southeast Asian markets. Digital platform partnerships with ERP system providers offer the most penetrable go-to-market angle for bypassing established broker networks. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors data-native platform acquisitions over traditional indemnity underwriters. Long-term viability across a five-to-ten-year window hinges on proprietary buyer database scale and algorithmic underwriting capability. Acquisition target archetype: regional specialists with concentrated single-risk expertise in infrastructure equipment verticals. Watch reinsurance capacity tightening as the inflection signal for primary rate hardening and carrier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Development | Embedded ERP partnerships with SAP and Oracle compress policy issuance timelines from weeks to hours. |
| Proprietary Database Expansion | Continuous buyer risk monitoring protocols displace static credit limit assignments across mid-market portfolios. |
| Political Risk Module Attachment | Multiyear frameworks with sovereign peril coverage capture expanding demand in China-India-ASEAN corridors. |
| Machine Learning Talent Acquisition | Alternative data operationalization for buyer scoring separates algorithmic carriers from legacy underwriters. |
| Regional Hub Establishment | Chennai and Ahmedabad offices position carriers for Gujarat-Tamil Nadu exporter base expansion. |
Research Approach
Initial hypotheses were tested against primary input from credit risk officers at trade credit carriers, supply chain finance platform executives, and mid-market exporter CFOs and refined through secondary validation against EIOPA solvency reports, IRDAI regulatory filings, and customs trade flow databases. Bottom-up policy placement data triangulated with top-down premium volume estimates from national insurance associations and carrier disclosures. Primary fieldwork encompassed structured interviews across Munich, Paris, Singapore, and Mumbai insurance clusters.
Variance decomposition across policy type, coverage dimension, client size tier, and geographic corridor shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to segment-level baseline estimates, with cross-validation against macroeconomic trade volume projections and regulatory capital adequacy trajectories. Modeled inputs included open-account trade tenor extension rates, Solvency II risk-based capital requirement evolution, and supply chain finance platform penetration curves.
Material uncertainties — sovereign debt stress events, reinsurance market dislocation, and regulatory divergence between EIOPA, IRDAI, and CBIRC frameworks — sit outside the modeled envelope. Forecasts reflect assumptions about trade corridor stability and carrier capital deployment capacity. Recalibration cycles align with material shifts in emerging market exporter credit demand and catastrophe bond spread movements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Term Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
India Life and Non-Life Insurance Market
Insurance
India Dental Insurance Market
Insurance
Solar Panel Warranty Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Dental Insurance Market
Insurance
Africa Microinsurance Market
Insurance
UK Dental Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
AI in Insurance Market
Insurance
Crime Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Djibouti Insurance Market