
 Investment Banking Market | 2026-2036
Investment Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Investment Banking Market Analysis
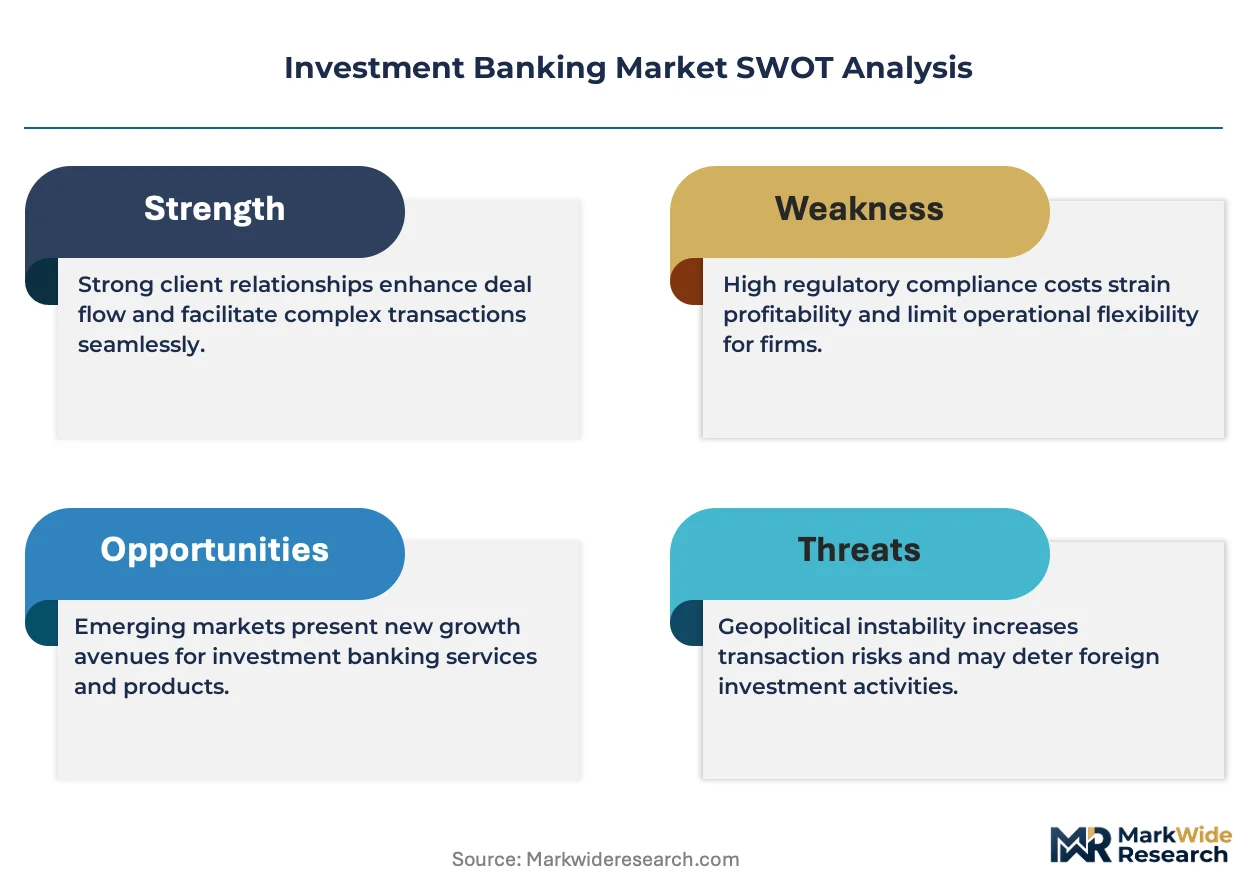
Generative AI deployment across deal execution workflows is tilting due diligence timelines and valuation modeling toward real-time analytics. JPMorgan Chase leverages proprietary machine-learning platforms to compress pitch-to-close cycles across its M&A franchise. Goldman Sachs anchors its competitive edge in debt underwriting through captive distribution networks spanning institutional and sovereign wealth clients. Moelis & Company specializes in activist defense and complex restructuring mandates, occupying a differentiated position against balance-sheet-heavy rivals.
Investment banking encompasses financial advisory, capital-raising, and risk-management services rendered to corporations, governments, and institutional investors, typically structured around fixed fees, success fees, or spreads tied to transaction value and complexity. The practice requires licensed personnel operating under prudential capital requirements and fiduciary standards designed to manage conflicts between issuer interests and market integrity. Mergers & Acquisitions advisory generates the highest fee margins per engagement, particularly in contested or cross-border transactions where regulatory navigation adds complexity. Underwriting of debt and equity issues sustains volume-driven revenue pools, with Large Cap and Mega transactions concentrating among top-tier banks while Mid Cap mandates fragment across regional and boutique competitors.
The SEC enforces disclosure and registration standards that shape issuer behavior and banker liability across U.S.-dominated capital markets, while the Federal Reserve's prudential framework governs capital reserves and risk-weighting for bank-affiliated advisors. FINRA's conduct rules further constrain compensation structures and communications with retail and institutional investors. Stakeholders must monitor how AI-driven execution tools interact with evolving fiduciary interpretations and whether regulatory latency creates compliance gaps for early adopters.
Market Dynamics
Generative AI deployment is compressing diligence timelines and redistributing fee pools from traditional advisory toward technology-augmented execution, forcing incumbents to restructure analyst staffing models and pricing architectures.
Growth Catalysts
- Cross-border M&A mandates:Corporate clients seek advisory on complex international transactions amid evolving SEC disclosure requirements, elevating demand for regulatory navigation expertise.
- Activist defense specialization:Boutique advisors capture premium fees from contested board situations and complex restructuring mandates requiring conflict-free counsel.
- Debt underwriting volume:Institutional and sovereign wealth distribution networks sustain capital-raising activity across rate-sensitive refinancing cycles.
Market Restraints
- Talent concentration in bulge-bracket hubs:New York and London absorb senior bankers, leaving regional markets with execution capacity gaps.
- Fee compression on standardized issuance:Algorithmic pricing for investment-grade debt squeezes spreads on recurring underwriting business.
- Prudential capital requirements:Federal Reserve risk-weighting rules constrain balance-sheet deployment for bank-affiliated advisors against independent boutiques.
Strategic Opportunities
- Healthcare and technology verticals:Specialized mandates in life sciences and software M&A command premium pricing due to technical complexity.
- Real-time analytics integration:Machine-learning platforms enable predictive valuation modeling that compresses pitch-to-close cycles.
- Environmental and social-linked issuance:Sustainability-tied underwriting structures attract institutional capital seeking ESG-aligned deployment.
Industry Challenges
- Generative AI compliance gaps:FINRA conduct rules have not clarified fiduciary standards for algorithm-driven client communications, creating liability exposure for early adopters.
- Legacy system integration:Incumbent banks face friction merging proprietary deal databases with cloud-based collaboration tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Investment Banking Market |
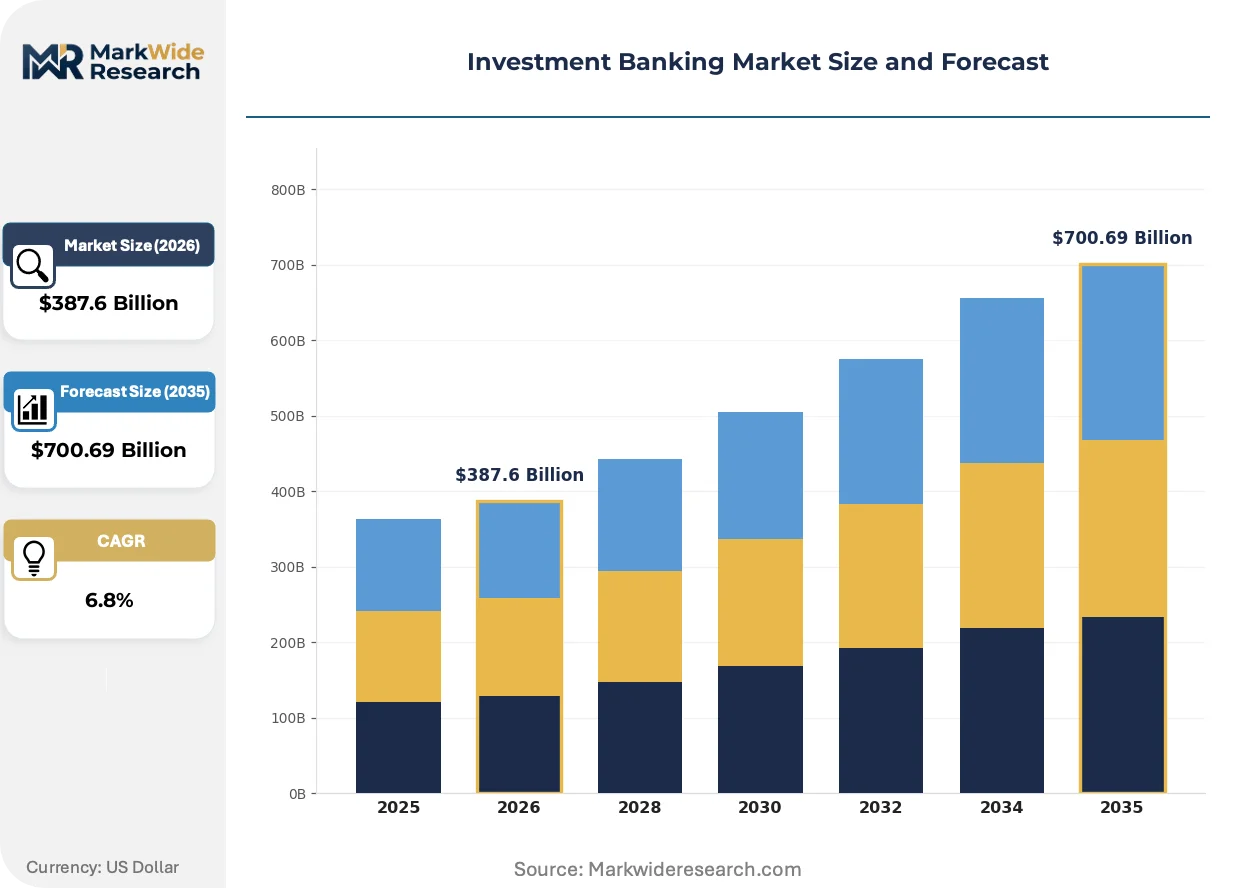
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mergers & Acquisitions, Underwriting, Advisory, Restructuring Client Type: Corporations, Governments, Institutions, Individuals Transaction Size: Small Cap, Mid Cap, Large Cap, Mega Sector Focus: Technology, Healthcare, Consumer, Energy |
| Companies Covered | Bank of America, Evercore, JPMorgan Chase, Centerview Partners, Lazard, Goldman Sachs, Citigroup, Moelis & Company, Morgan Stanley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Investment Banking Market Emerging Trajectories
Advisory workflows are undergoing platform-level transformation as artificial intelligence tools reshape how diligence gets executed, priced, and delivered to corporate issuers.
Natural-language processing engines trained on transaction documents are rendering obsolete manual redaction and clause extraction across M&A due diligence. Mid-market private equity sponsors now demand AI-augmented quality-of-earnings analysis as a baseline deliverable. This compression of manual analyst hours is reallocating fee structures toward technology licensing and specialist interpretation.
SEC disclosure requirements for material cybersecurity incidents are expanding banker liability for target-company technology risks. Underwriters must now verify cyber posture representations in registration statements, adding diligence scope to equity issuance mandates. Technology and healthcare issuers face the steepest compliance burden as digitization deepens across both sectors.
Corporate treasury departments are unbundling advisory relationships, separating M&A counsel from capital-raising representation to optimize fee negotiation leverage. This fragmentation of mandates benefits boutique specialists with narrow expertise over full-service relationships. The pattern is most pronounced among mid-cap industrials seeking to avoid cross-subsidized pricing embedded in bundled service agreements.
Investment Banking Market Segmentation
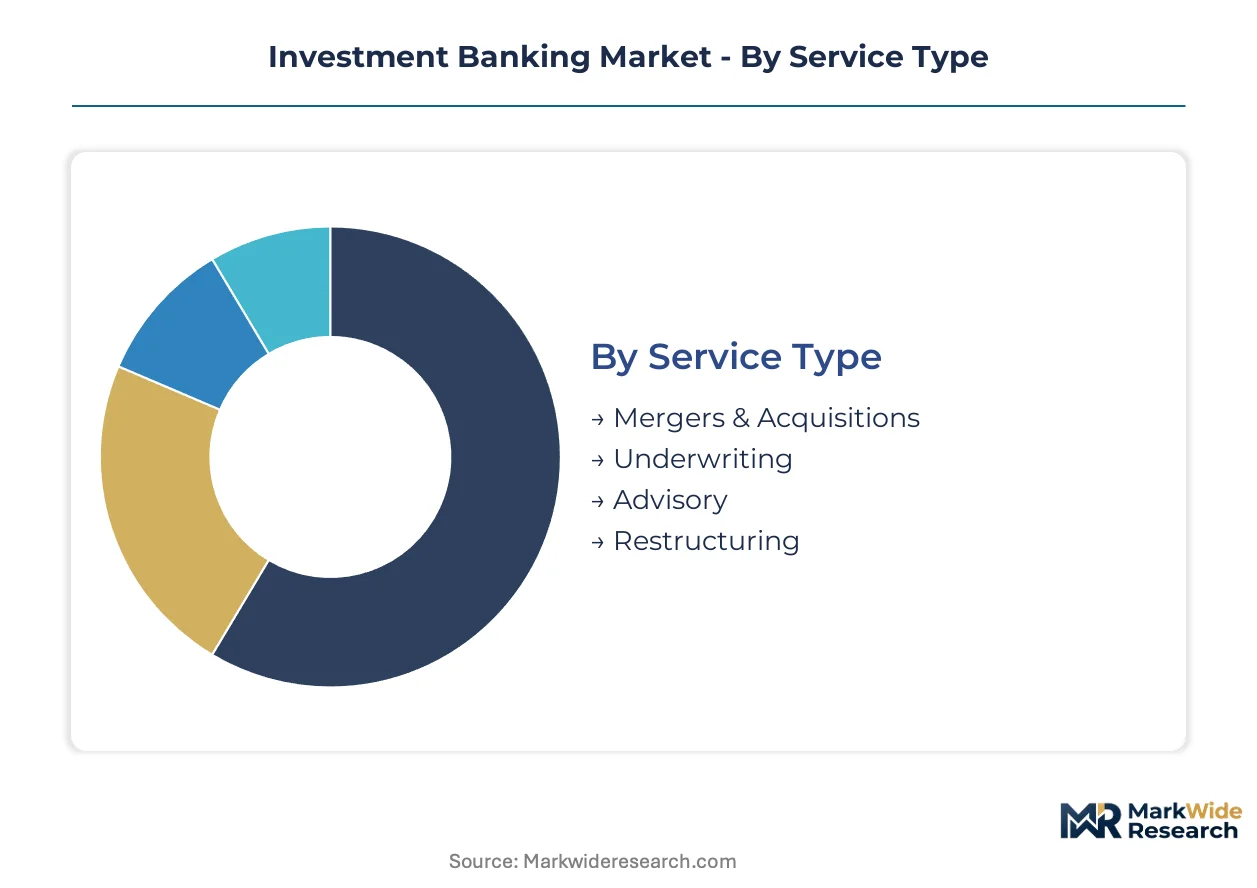
Investment banking services fragment across multiple dimensions that determine pricing power, regulatory exposure, and talent requirements. Service specialization, client sophistication, transaction scale, and sector expertise each create distinct competitive arenas with divergent margin profiles and capital intensity.
Service Type:
After-sales intensity varies sharply across service lines, with ongoing advisory relationships demanding sustained partner attention versus episodic underwriting engagements.
- Mergers & Acquisitions:Contested and cross-border transactions command the highest fee margins due to regulatory navigation complexity and activist defense requirements. Corporate clients in the United States concentrate demand here as SEC disclosure standards tighten for material transactions.
- Underwriting:Debt and equity issuance generates volume-driven revenue pools with spreads tied to distribution network depth and institutional investor relationships. Large Cap and Mega transactions concentrate among bulge-bracket firms with captive sovereign wealth and pension fund access.
- Advisory:Strategic counsel on capital structure and corporate finance decisions operates on retainer or success-fee models depending on mandate scope.
- Restructuring:Distressed advisory and liability management mandates spike during rate-sensitive refinancing cycles.
By volume, Underwriting leads. By growth pace, Mergers & Acquisitions is climbing the fastest.
Client Type:
Cost-to-serve escalates with client complexity, from standardized retail products to bespoke sovereign mandates requiring multi-jurisdictional coordination.
- Corporations:Strategic issuers drive the majority of fee pools across M&A and capital-raising mandates, with mid-cap industrials increasingly unbundling advisory relationships to optimize negotiation leverage.
- Governments:Sovereign and municipal issuance demands regulatory expertise across SEC registration standards and Federal Reserve prudential frameworks.
- Institutions:Pension funds, endowments, and asset managers anchor distribution networks for debt underwriting.
- Individuals:Ultra-high-net-worth clients access private placement and wealth-adjacent services through bank-affiliated platforms.
Corporations dominate absolute fee generation. Governments are expanding most quickly amid infrastructure financing needs.
Transaction Size:
Margin structures invert across size tiers, with complexity premiums attaching to mid-market contests rather than commoditized mega-caps.
- Small Cap:Regional boutiques and specialist advisors capture mandates requiring sector-specific expertise rather than balance-sheet scale.
- Mid Cap:Fragmented competitive landscape pits bulge-bracket coverage teams against independent boutiques, with fee compression most acute on standardized issuance.
- Large Cap:Top-tier banks concentrate share through integrated advisory and underwriting capabilities.
- Mega:A handful of global firms control cross-border mandates requiring multi-currency execution and sovereign wealth distribution.
Mid Cap commands the broadest advisor participation. Mega transactions show the steepest expansion trajectory as cross-border activity accelerates.
Sector Focus:
Technical complexity creates pricing premiums in segments where diligence requires specialized knowledge of regulatory pathways and intellectual property valuation.
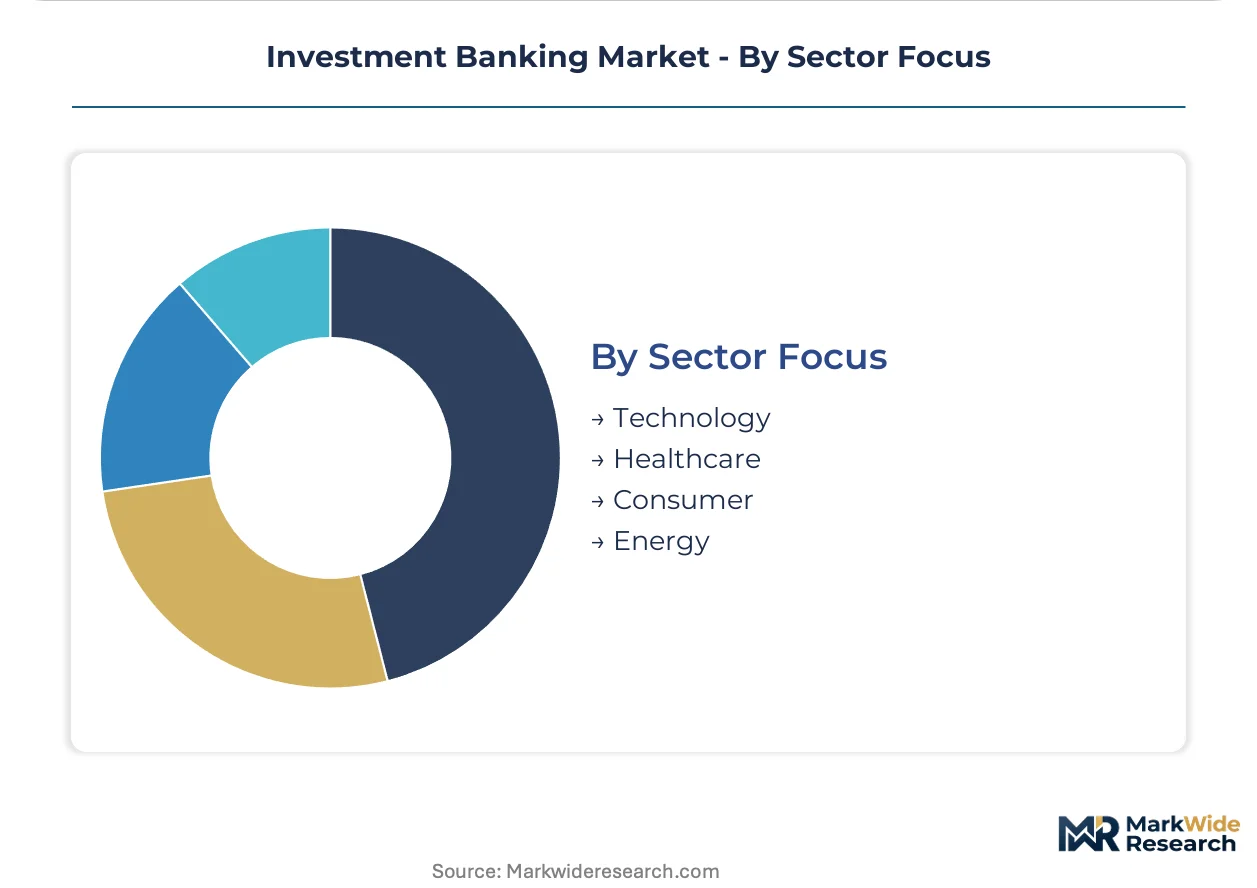
- Technology:Software and digital infrastructure M&A demands cyber posture verification under expanded SEC disclosure requirements for material incidents. Private equity sponsors now require AI-augmented quality-of-earnings analysis as baseline deliverable.
- Healthcare:Life sciences transactions command premium pricing due to FDA regulatory navigation, patent cliff analysis, and reimbursement risk assessment. Biotechnology issuers face the steepest compliance burden as digitization deepens clinical trial documentation.
- Consumer:Brand valuation and channel shift analysis drive advisory needs across retail and consumer packaged goods consolidation.
- Energy:Transition-linked issuance and ESG-tied underwriting structures attract institutional capital seeking sustainability-aligned deployment.
Technology leads by current mandate volume. Healthcare is gaining share fastest as demographic tailwinds sustain deal flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border M&A advisory flows from United States issuers into European and Asian buyer markets dominate fee generation, with bulge-bracket firms capturing mandates requiring multi-jurisdictional regulatory navigation.
United States
Corporate treasury departments unbundle advisory relationships to optimize fee leverage, separating M&A counsel from capital-raising representation. SEC disclosure requirements for material cybersecurity incidents expand banker liability for target-company technology risks. Manhattan and San Francisco financial districts concentrate bulge-bracket headquarters where proprietary machine-learning platforms compress pitch-to-close cycles.
United Kingdom
Sovereign wealth funds and pension managers anchor distribution networks for dollar-denominated debt issuance, sustaining London's position in global capital-raising. The Financial Conduct Authority enforces conduct standards that shape compensation structures and investor communications. The City of London and Canary Wharf clusters host boutiques specializing in activist defense and complex restructuring mandates.
Germany
Mid-cap industrials seek conflict-free counsel for cross-border consolidation, particularly in automotive and industrial machinery verticals. BaFin prudential frameworks govern capital reserves for bank-affiliated advisors competing against independent boutiques. Frankfurt's financial district anchors euro-denominated underwriting activity while Munich and Stuttgart clusters concentrate sector-specialist advisory talent.
Japan
Corporate issuers demand advisory on outbound M&A into Southeast Asian manufacturing and technology assets. METI industrial policy frameworks influence capital structure decisions for strategic sectors including semiconductors and batteries. Tokyo's Marunouchi and Otemachi districts concentrate trust bank advisory arms with captive institutional distribution networks.
Singapore
Wealth management platforms channel ultra-high-net-worth capital into private placement and alternative investment structures. The Monetary Authority of Singapore enforces anti-money-laundering standards that shape client onboarding for cross-border advisory. The Marina Bay financial district hosts regional headquarters for banks competing across ASEAN M&A and infrastructure financing mandates.
Investment Banking Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where balance-sheet scale, distribution network depth, and sector expertise determine mandate access. The market fragments across four competitive tiers: bulge-bracket universal banks with captive institutional distribution, mid-tier nationals with regional coverage depth, independent boutiques with conflict-free positioning, and sector-specialist advisors with technical diligence capabilities. Dominant competitive moves include technology platform investments that compress execution timelines and strategic hiring of senior bankers with established corporate relationships.
Within the bulge-bracket tier, JPMorgan Chase, Goldman Sachs, and Morgan Stanley occupy positions defined by integrated advisory and underwriting capabilities across capital-raising and M&A franchises. These firms exemplify the balance-sheet-heavy archetype where proprietary distribution networks spanning sovereign wealth and institutional clients sustain debt underwriting volume through rate-sensitive refinancing cycles.
| Leading Market Players |
|---|
| Bank of America |
| Evercore |
| JPMorgan Chase |
| Centerview Partners |
| Lazard |
| Goldman Sachs |
| Citigroup |
| Moelis & Company |
| Morgan Stanley |
| Others |
Supply Flow & Price Mechanics
Senior banker talent pools in Manhattan and London concentrate pricing power at bulge-bracket headquarters, compressing margin capture for regional boutiques competing on standardized underwriting mandates. This upstream human capital concentration reshapes where fee premiums accrue across the advisory value chain.
Pricing Analysis
Legacy pitch-to-close workflows versus AI-augmented execution platforms versus next-generation real-time analytics engines define the technology-generation pricing gap in advisory services. Three-tier pricing structure across premium retainer, standard success-fee, and economy commoditized issuance separates contested M&A mandates from routine debt underwriting. Fee compression intensifies in investment-grade debt as algorithmic pricing displaces relationship-based spread negotiation. Mid-cap industrials exhibit acute price sensitivity, while sovereign wealth clients anchor least-sensitive demand through captive distribution relationships.
Supply Chain Analysis
Upstream feedstock for deal execution flows from human capital pipelines at Wharton, LSE, and INSEAD into analyst and associate labor pools. Proprietary machine-learning platforms from JPMorgan Chase, Goldman Sachs, and Morgan Stanley rest on cloud infrastructure dependencies and data vendor subscriptions. Single-source vulnerability concentrates in Bloomberg terminal access and SEC EDGAR filing systems. Distribution runs through partner-led coverage teams into corporate treasury departments and private equity sponsor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI platforms threaten to displace traditional advisory hours, forcing incumbents to defend substitution through technology-augmented execution capabilities that preserve relationship premiums.
For Market Incumbents: Pre-empt boutique encroachment by embedding machine-learning diligence tools into M&A workflows before fee compression spreads from underwriting into advisory. Consolidate activist defense talent pools in London and New York to capture restructuring spikes. Vertical integration into proprietary data assets offsets algorithmic pricing pressure on standardized issuance.
For New Entrants and Emerging Players: Establish a beachhead in healthcare technology M&A where FDA regulatory navigation creates specialist barriers against generalist competitors. Target mid-cap industrials unbundling advisory relationships in Germany and Japan. Lead with AI-augmented quality-of-earnings analysis as a differentiated deliverable to private equity sponsors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech infrastructure plays seeking strategic exits to bank-affiliated platforms. Five-to-ten-year viability hinges on regulatory clarity for algorithm-driven client communications under FINRA conduct rules. Watch SEC enforcement patterns on cybersecurity disclosure liability as an inflection signal for technology sector advisory demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Platform Deployment | JPMorgan Chase's proprietary analytics compress pitch-to-close cycles across contested M&A mandates. |
| Activist Defense Talent Acquisition | Moelis & Company captures premium fees from contested board situations requiring conflict-free counsel. |
| Healthcare Vertical Specialization | Life sciences transactions command pricing premiums due to FDA regulatory navigation complexity. |
| ESG-Linked Underwriting Structure | Sustainability-tied issuance attracts institutional capital from sovereign wealth and pension networks. |
| Cloud-Based Collaboration Integration | Legacy system modernization reduces friction between proprietary deal databases and distributed execution teams. |
Methodological Framework
A spread of perspectives from M&A managing directors, corporate treasury officers, private equity operating partners, and regulatory compliance leads converged on the working assumptions shaping this analysis. Primary fieldwork across bulge-bracket headquarters in Manhattan and boutique clusters in London and Frankfurt was cross-checked against SEC enforcement releases, FINRA disciplinary actions, Federal Reserve prudential filings, and trade publication mandate tracking. Bottom-up transaction database construction was triangulated against top-down fee pool estimates from industry associations.
Demand-supply balance across advisory capacity and corporate issuance activity anchored the forecast framework throughout the projection horizon. Segmentation dimensions modeled include service type, client sophistication tier, transaction size bracket, and sector regulatory intensity. CAGRs were derived from historical fee growth patterns adjusted for technology-driven timeline compression. AI adoption curves and SEC disclosure expansion timelines served as industry-specific forecast inputs.
Stress conditions across rate-sensitive refinancing cycles, geopolitical transaction friction, and generative AI regulatory latency were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against Federal Reserve Senior Loan Officer Opinion Survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Corporate Banking Market
Banking
US Retail Banking Market
Banking
Global Neobanking Market
Banking
Data Analytics in Banking Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Russia Data Analytics in Banking Market
Banking
North America Bank Kiosk Market
Banking
Southeast Asia Commercial Banking Market
Banking
Canada Data Analytics in Banking Market
Banking
Australia Neobanking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Africa Data Analytics in Banking Market
Banking
Embedded Banking Market
Banking
Germany Neobanking Market
Banking
Armenia Banking Market