
 Islamic Finance Market | 2026-2036
Islamic Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Islamic Finance Market Outlook
Buyer concentration across sovereign wealth funds is decoupling from traditional commercial banking channels, fragmenting demand across state-backed institutional pools. Al Rajhi Bank anchors retail penetration through its branch dominance across Saudi Arabia. Kuwait Finance House leverages its transnational footprint to compete in Turkish and European Islamic banking corridors.
Islamic Finance denotes financial services and instruments structured to comply with Shariah law, prohibiting riba (interest), gharar (excessive uncertainty), and haram (forbidden) activities such as alcohol or gambling investments; its primary commercial purpose is to mobilize capital for individuals and institutions seeking ethical, asset-backed returns without conventional interest mechanisms. Sukuk leads product-type issuance volume, with sovereign entities driving benchmark-size deals that set pricing curves for corporate follow-ons. Wealth management services within the service-type dimension attract the fastest-growing fee pools as high-net-worth families across Southeast Asia and the Middle East demand Shariah-compliant portfolio construction.
Malaysia's Securities Commission, Saudi Arabia's Capital Market Authority, and the Accounting and Auditing Organization for Islamic Financial Institutions collectively shape product standards, disclosure requirements, and cross-border recognition protocols that determine market access for new entrants. The EU Green Deal taxonomy and CSRD reporting standards are beginning to intersect with Islamic Finance principles, creating dual-compliance complexity for European-registered Sukuk issuers. Stakeholders must monitor whether regulatory divergence between Gulf-based Shariah boards and Asian standard-setters hardens into incompatible certification regimes.
Market Dynamics
Sovereign wealth funds across the Gulf Cooperation Council are decoupling from conventional banking channels, fragmenting demand across state-backed institutional pools and reshaping how Sukuk issuance reaches end investors.
Growth Catalysts
- Malaysia's Securities Commission streamlined frameworks:Cross-border Shariah-compliant fundraising accelerates as disclosure requirements harmonize with regional standards, reducing issuance friction for multinational entities.
- Retail banking penetration:Branch networks across Saudi Arabia deepen household participation in Islamic investment products, converting previously unbanked populations into active Sukuk and fund subscribers.
- Sovereign Sukuk benchmarks:Government-led issuance curves establish pricing references that enable corporate follow-on deals, expanding the investable universe for institutional portfolios.
Market Restraints
- Shariah board divergence:Gulf-based certification bodies and Asian standard-setters maintain incompatible rulings on permissibility, forcing dual compliance costs for cross-border issuers.
- Scholar scarcity:Qualified Shariah advisors concentrate in Kuala Lumpur and Jeddah, creating bottlenecks for new product approvals in secondary markets.
- Asset-backed complexity:Sukuk structures require tangible collateral documentation that conventional bonds bypass, lengthening transaction timelines and legal spend.
Strategic Opportunities
- EU Green Deal intersection:CSRD reporting standards create dual-compliance frameworks where Islamic asset-backed principles align with European sustainability disclosure, opening new investor bases.
- Wealth management digitization:Robo-advisory platforms in Southeast Asia automate Shariah-compliant portfolio construction for mass-affluent segments previously served only by private banking.
- Turkish corridor expansion:Kuwait Finance House leverages existing European licenses to intermediate between Gulf capital and underbanked Muslim populations in Central Asia.
Industry Challenges
- Scholar training pipelines:Islamic finance jurisprudence programs at Al-Azhar and IIUM produce insufficient graduates to staff expanding Shariah advisory functions at rating agencies and law firms.
- Legacy system integration:Core banking platforms at established institutions require middleware layers to distinguish between conventional and Islamic product ledgers, complicating real-time reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Islamic Finance Market |
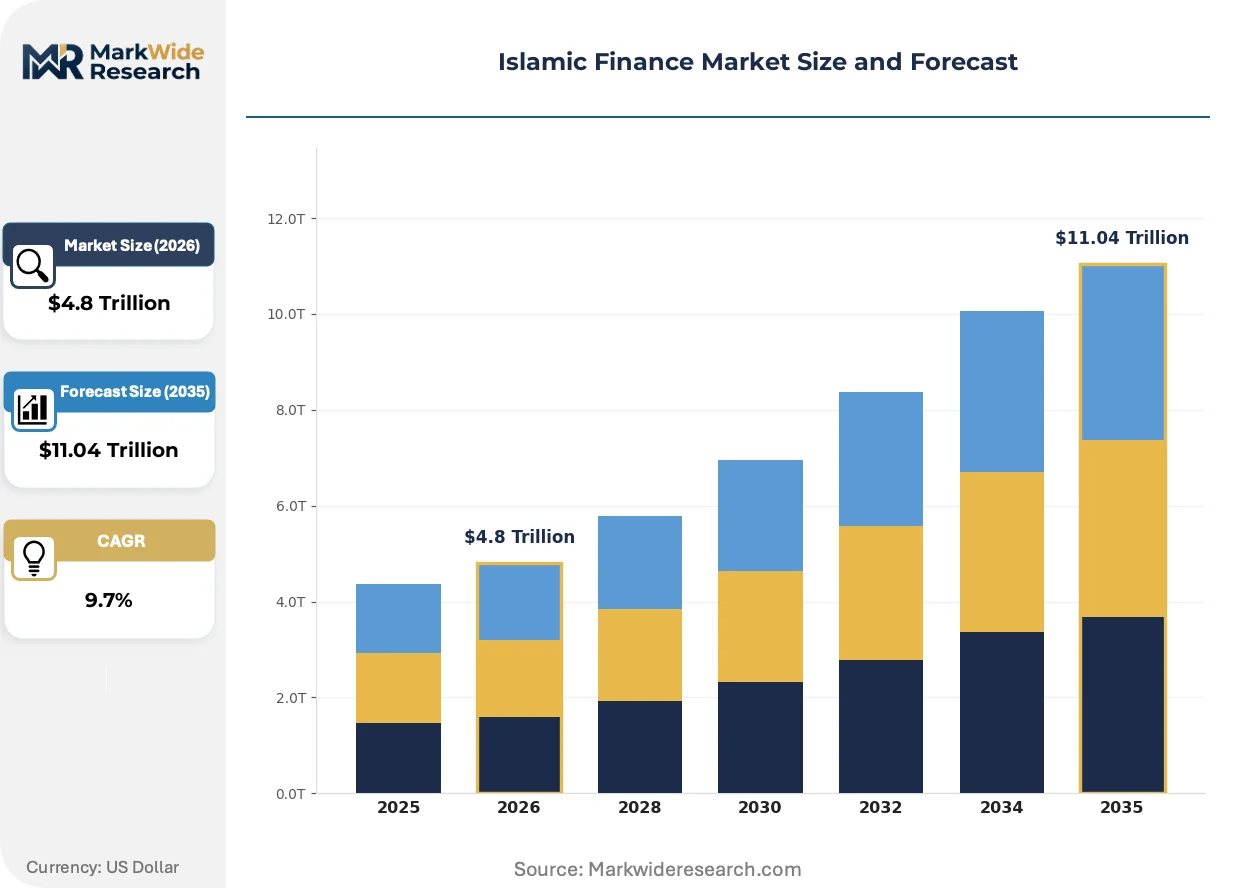
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $11.04 Trillion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murabaha, Ijara, Musharaka, Sukuk End User: Retail Investors, Islamic Banks, Corporations, Sovereign Entities Service Type: Wealth Management, Investment Advisory, Shariah Compliance, Risk Management Delivery Model: Online Platforms, Branch Networks, Collaborative Financing, Direct Investment |
| Companies Covered | Al Rajhi Bank, Kuwait Finance House, Dubai Islamic Bank, Abu Dhabi Islamic Bank, Maybank Islamic, Qatar Islamic Bank, Bank Albilad, Bank Islam Malaysia, Standard Chartered Saadiq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Islamic Finance Market Strategic Shifts
Distributed ledger infrastructure is overtaking paper-based Sukuk registries, compressing settlement cycles and enabling fractional ownership structures that reshape retail access patterns.
Blockchain-based Sukuk issuance is overtaking traditional certificate registries in pilot programs across Bahrain and Abu Dhabi, enabling atomic settlement that eliminates T+2 counterparty exposure. Sovereign issuers in the Gulf Cooperation Council pilot these structures for retail-sized tranches. The technology is overtaking legacy custody arrangements by collapsing registrar, paying agent, and transfer agent functions into smart contract automation.
CSRD disclosure mandates from the European Commission impose sustainability reporting obligations on Sukuk issuers with EU listings, forcing alignment between Shariah compliance and ESG taxonomy classification. Dual-framework documentation now dominates European-registered deals. Asset managers in Luxembourg and Ireland restructure fund mandates to capture both compliant investor pools.
Family offices across Southeast Asia consolidate advisory relationships with single-platform providers, displacing the fragmented bank-and-broker model that historically dominated portfolio construction. Boutique Shariah-compliant wealth advisors in Singapore and Dubai capture these consolidated mandates. Saudi high-net-worth households demonstrate the fastest adoption velocity, driven by generational wealth transfer timing.
Islamic Finance Market Segmentation
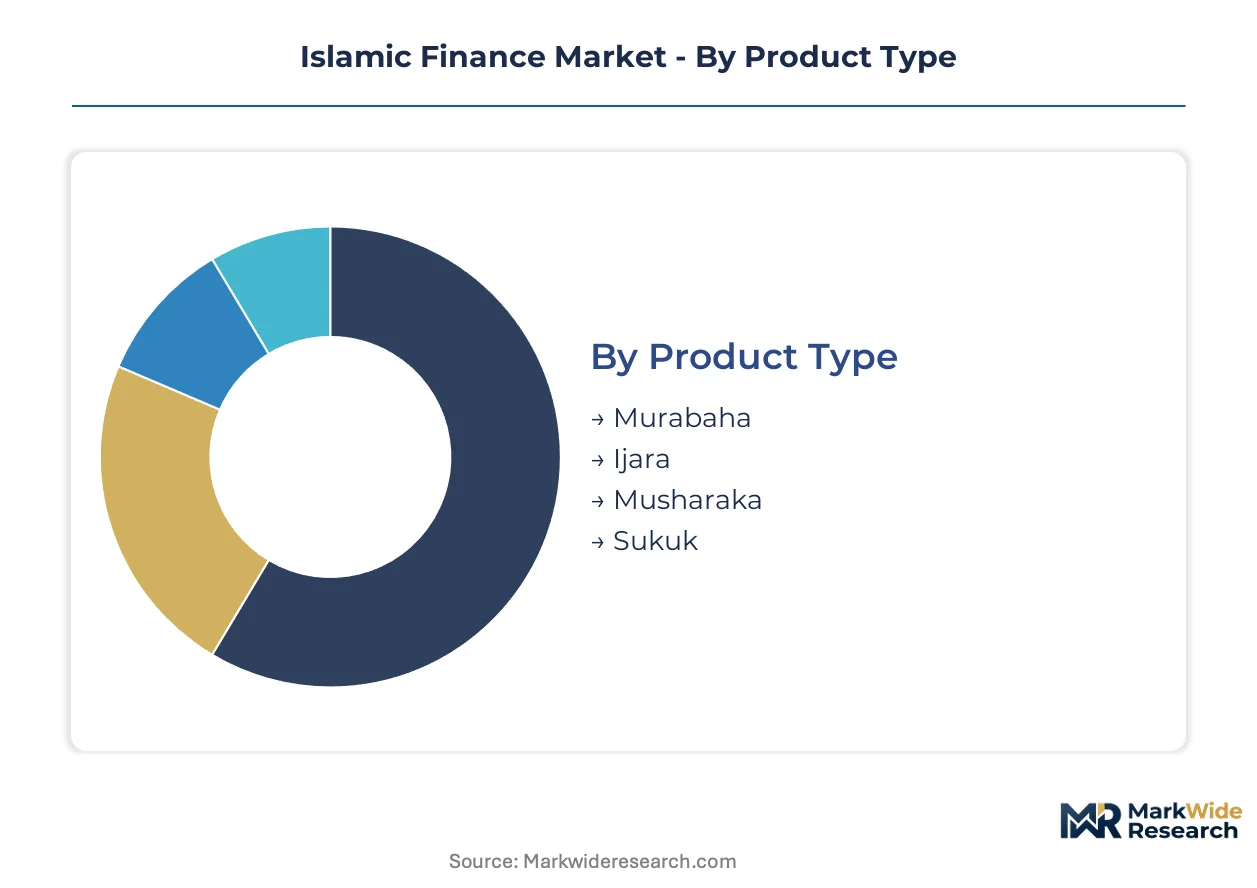
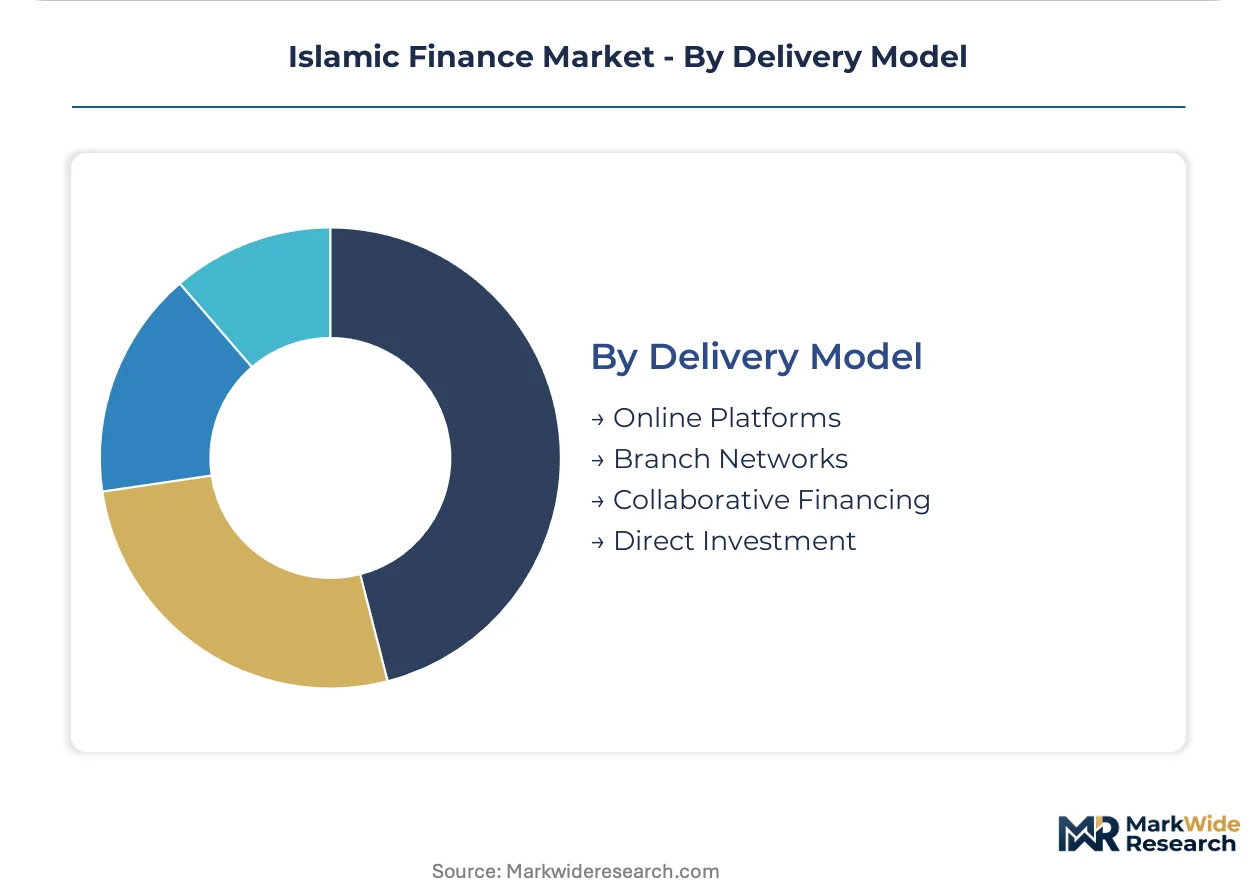
Islamic Finance segments reflect divergent capital deployment timelines and Shariah interpretation strictness. Product structures vary in asset-backing intensity, while delivery models separate digitally native entrants from legacy branch-dependent institutions.
Product Type:
Cost tier distinguishes these instruments, with complex structures commanding premium structuring fees.
- Sukuk:Asset-backed certificates transfer beneficial ownership of tangible assets or usufruct rights, requiring SPV formation and collateral perfection. Demand concentrates among sovereign entities in Saudi Arabia and Malaysia, driven by benchmark pricing curve establishment for corporate follow-on issuance.
- Murabaha:Cost-plus financing structures dominate working capital provision, with disclosed mark-up replacing interest. Retail banking channels across Saudi Arabia absorb the highest volume, converting previously unbanked households into active Islamic finance participants.
- Ijara:Leasing contracts transfer asset use rights without ownership conveyance, prevalent in equipment and vehicle finance.
- Musharaka:Equity participation arrangements distribute profits and losses proportionally, deployed in project finance and joint ventures.
Volume sits with Murabaha; growth tilts toward Sukuk.
End User:
Customer type determines regulatory treatment and disclosure intensity across jurisdictions.
- Sovereign Entities:Central governments and ministries of finance issue benchmark Sukuk to establish yield curves and diversify funding sources. Gulf Cooperation Council sovereigns anchor issuance volume, with Malaysia's government setting regional pricing references.
- Islamic Banks:Licensed institutions deploy customer deposits into Shariah-compliant assets while maintaining regulatory capital ratios. Saudi Arabia's banking sector demonstrates the deepest retail penetration, with branch networks converting deposits into structured products.
- Corporations:Non-financial firms access project finance and working capital through tailored Islamic structures.
- Retail Investors:Individual households participate through mutual funds, deposit products, and retail-sized Sukuk tranches.
Volume sits with Sovereign Entities; expansion concentrates in Retail Investors.
Service Type:
Margin structure separates high-touch advisory from commoditized compliance verification.
- Wealth Management:Portfolio construction and succession planning for high-net-worth families demands Shariah-compliant asset allocation across jurisdictions. Singapore and Dubai boutiques capture consolidated mandates from Southeast Asian family offices.
- Shariah Compliance:Certification and ongoing monitoring by qualified scholars ensures product permissibility. Kuala Lumpur and Jeddah concentrate advisory capacity, creating bottlenecks for new product approvals in secondary markets.
- Investment Advisory:Deal structuring and capital placement services intermediate between issuers and institutional investors.
- Risk Management:Shariah-compliant hedging instruments and takaful alternatives address operational and market exposures.
Volume sits with Shariah Compliance; value expansion favors Wealth Management.
Delivery Model:
Geography of customer acquisition determines infrastructure investment requirements.
- Branch Networks:Physical presence enables relationship-based customer onboarding and complex product explanation. Al Rajhi Bank's Saudi Arabian footprint demonstrates how branch density converts unbanked populations into active subscribers.
- Online Platforms:Digital interfaces automate Shariah screening and portfolio rebalancing for mass-affluent segments. Southeast Asian robo-advisory ventures capture previously private-banking-only customers.
- Collaborative Financing:Multi-bank syndication structures distribute large-ticket exposure across institutional balance sheets.
- Direct Investment:Bilateral arrangements between capital providers and asset originators bypass intermediary layers.
Volume sits with Branch Networks; digitization accelerates fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign wealth fund concentration in the Gulf Cooperation Council is fragmenting demand away from conventional banking channels. Retail banking penetration in Saudi Arabia is converting previously unbanked households into active Islamic investment product subscribers. Malaysia's regulatory streamlining is accelerating cross-border Shariah-compliant fundraising velocity.
Saudi Arabia
Branch network density across Riyadh and Jeddah deepens household participation in Sukuk and fund products. The Capital Market Authority supervises disclosure harmonization for retail-sized tranches. Al Rajhi Bank's nationwide footprint demonstrates how physical presence converts deposit bases into structured Islamic product subscribers.
Malaysia
Kuala Lumpur concentrates qualified Shariah advisory capacity for new product approvals across Southeast Asia. The Securities Commission streamlined cross-border fundraising frameworks to reduce issuance friction for multinational entities. The city's Islamic finance cluster anchors benchmark sovereign Sukuk pricing that enables corporate follow-on deals regionally.
United Arab Emirates
Dubai and Abu Dhabi sovereign issuers pilot blockchain-based Sukuk registries for atomic settlement. The central bank and securities regulator coordinate on smart contract automation standards. Bahrain's adjacent financial hub complements UAE pilot programs with distributed ledger infrastructure testing.
Kuwait
Kuwait Finance House leverages its transnational licensing to intermediate Gulf capital into Turkish and European Islamic banking corridors. The central bank maintains oversight of cross-border expansion into underbanked Muslim populations. The firm's dual-continent footprint exemplifies how regional players capture corridor opportunities between established and emerging markets.
Turkey
Participation banking assets grow as Kuwaiti and Gulf institutions expand licensed operations in Istanbul and Ankara. The Banking Regulation and Supervision Agency governs Shariah-compliant institution licensing. The Bosporus corridor position enables intermediation between Gulf capital pools and Central Asian demand.
Islamic Finance Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital wealth management and robo-advisory platforms. The vendor base concentrates around sovereign-backed institutional pools and state-licensed retail banking networks. Three archetypes dominate: branch-dependent retail banks with nationwide footprints, transnational institutions leveraging multi-jurisdiction licensing, and digital-native platforms automating Shariah screening. Competitive moves center on geographic corridor expansion and technology partnerships for distributed ledger infrastructure.
Within the branch-dependent tier, Al Rajhi Bank and Bank Albilad represent Saudi Arabia's retail penetration model, while Kuwait Finance House exemplifies the transnational licensing archetype. These institutions anchor distinct competitive vectors: physical network density versus cross-border regulatory arbitrage. Maybank Islamic occupies a position within Southeast Asia's streamlined disclosure environment, benefiting from Malaysia's Securities Commission harmonization efforts.
| Leading Market Players |
|---|
| Al Rajhi Bank |
| Kuwait Finance House |
| Dubai Islamic Bank |
| Abu Dhabi Islamic Bank |
| Maybank Islamic |
| Qatar Islamic Bank |
| Bank Albilad |
| Bank Islam Malaysia |
| Standard Chartered Saadiq |
| Others |
Value Chain & Pricing Dynamics
Qualified Shariah advisor concentration in Kuala Lumpur and Jeddah creates labor-cost differentials that widen pricing spreads between premium-certified Sukuk structures and standard Murabaha products. Certification fees from Gulf-based boards command substantial premiums over Malaysian Shariah council approvals, fragmenting price tiers across issuance corridors.
Pricing Analysis
Volume sits with commoditized Murabaha working-capital products; margins concentrate in bespoke Sukuk structuring and wealth management advisory. Price differentiation hinges on Shariah board prestige—GCC sovereign benchmarks versus Asian corporate follow-ons—and asset-backing intensity requiring SPV formation. Pricing pressure stems from scholar scarcity elongating approval timelines and inflating advisory retainers. Retail investors in Saudi Arabia demonstrate highest price sensitivity; sovereign wealth funds accept premium pricing for benchmark-curve establishment.
Supply Chain Analysis
Workforce availability for qualified Shariah scholars concentrates in Malaysia and Saudi Arabia, constraining product-approval capacity in secondary markets like Turkey and Indonesia. Supply chains draw from legal documentation specialists in Dubai, SPV formation agents in Labuan, and trustee services in Luxembourg. Single-source vulnerability sits with scholar concentration—bottlenecks emerge when boards delay rulings. Distribution runs through sovereign issuance pipelines that establish pricing references for corporate follow-on deals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Islamic Finance is transitioning from paper-based Sukuk registries to distributed ledger infrastructure, with blockchain settlement protocols displacing legacy registrar and transfer agent functions across Gulf pilot programs.
For Market Incumbents: Anchor branch network dominance through middleware integration that distinguishes Islamic from conventional product ledgers in real-time reporting. Invest in captive Shariah advisory capacity—training pipelines at Al-Azhar and IIUM partnerships—to mitigate scholar scarcity threatening approval velocity. Defend against digital-native robo-advisory entrants automating mass-affluent portfolio construction. For New Entrants and Emerging Players: Begin with underpenetrated Central Asian corridors where Turkish participation banking licenses enable intermediation between Gulf capital and underbanked Muslim populations. Target European-registered Sukuk issuance where CSRD dual-compliance creates advisory gaps for boutique Shariah-compliant wealth managers. Deploy white-label blockchain infrastructure partnerships to bypass legacy custody buildout costs. For Investors and Strategic Acquirers: The window for entry favors transnational institutions with multi-jurisdiction licensing footprints spanning European and Asian regulatory clusters. Long-term viability rests on capturing consolidated family-office mandates displacing fragmented bank-and-broker models. Watch distributed ledger standardization across GCC central banks as inflection signal for infrastructure-scale platform acquisitions.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Sukuk Registry Deployment | Atomic settlement eliminates T+2 counterparty exposure for Bahrain and Abu Dhabi sovereign issuers. |
| Shariah Scholar Training Pipeline Investment | Partnerships with Al-Azhar and IIUM address certification bottlenecks constraining product approval velocity. |
| Cross-Border Regulatory Licensing Expansion | Kuwait Finance House's Turkish corridor demonstrates Gulf-European-Asian capital intermediation capture. |
| Robo-Advisory Platform Launch | Southeast Asian ventures automate Shariah screening for mass-affluent segments previously private-banking-only. |
| CSRD Dual-Compliance Framework Development | Luxembourg and Ireland fund mandates align Shariah principles with European sustainability disclosure taxonomy. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Islamic Finance market analysis. Primary interviews with Shariah advisory board members, Sukuk structuring lawyers at magic-circle firms, sovereign wealth fund fixed-income officers, and Securities Commission regulatory staff combined with secondary validation from AAOIFI standards documentation, Bursa Malaysia issuance disclosures, and Saudi Capital Market Authority circulars. Bottom-up transaction counting and top-down macroeconomic sizing triangulated market estimates.
Granularity-level modeling distinguished sovereign versus corporate versus retail end-user segments, with product-type splits across Sukuk, Murabaha, Ijara, and Musharaka structures. Service-type dimensions captured wealth management, Shariah compliance, investment advisory, and risk management fee pools. Delivery model differentiation separated branch-dependent institutions from online platform entrants. CAGRs derived from regression analysis against macroeconomic drivers and regulatory event timing across the projection horizon. Sukuk issuance volume curves and scholar approval pipeline data informed forecast inputs.
Underlying measurement precision varies by segment; sovereign Sukuk issuance carries tighter precision than retail robo-advisory penetration estimates. Forecasts reflect assumptions about regulatory harmonization between Gulf and Asian Shariah boards, distributed ledger adoption velocity, and CSRD alignment implementation. Material deviation in scholar training pipeline output or blockchain standardization adoption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Financial Services Software Market
Financial Services
United States Payroll Services Market
Financial Services
Germany E-Brokerage Market
Financial Services
Global Product Cost Management Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Australia Online Gambling Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Credit Rating Software Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Germany Factoring Services Market
Financial Services
Global Temporary Labor Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Europe Factoring Services Market
Financial Services
Virtual Account Management Software Market
Financial Services
Italy Gift Card and Incentive Card Market