
 South America Challenger Banks Market | 2026-2036
South America Challenger Banks Market Size, Share, and Industry Trends Forecast 2026-2036
South America Challenger Banks Market Insights
Market Dynamics
Mobile developer talent scarcity is collapsing across São Paulo and Buenos Aires, unlocking product velocity for digital-native lenders. Nubank leverages its cloud-native core to sustain sub-24-hour account provisioning at continental scale. Banco Inter anchors a hybrid marketplace-banking model that competes on merchant ecosystem density rather than interest margins alone. C6 Bank differentiates through embedded investment and travel rewards, occupying a premium positioning among mass-affluent Brazilians.
Segment Structure
South America challenger banks are licensed digital financial institutions operating without physical branch networks, typically delivering retail and commercial banking services through smartphone applications with real-time transaction processing and API-connected product marketplaces. Mobile Banking and Digital Wallets command the dominant service-type share due to PIX ubiquity in Brazil and similar real-time rails emerging in Colombia and Argentina; Online Loans represents the fastest-expanding margin pool as algorithmic credit scoring displaces traditional collateral requirements. Small Businesses and Freelancers form the most contested customer-type battleground, with Tech Startups showing concentrated growth in Chile and Colombia where venture capital corridors deepen banking integration.
Regulatory Environment
Brazil's Central Bank governs PIX infrastructure and open banking mandates, while Colombia's Superintendencia Financiera supervises Nequi and other digital entrants under evolving fintech licensing frameworks; ANVISA and Banco Central do Brasil jointly shape data privacy and cybersecurity standards affecting cross-border service architecture. Regulation compresses customer acquisition costs by standardizing identity verification and payment interoperability, though compliance intensity rises with each successive open finance phase. Stakeholders must monitor central bank digital currency pilots and interoperability treaty negotiations between Mercosur and Pacific Alliance regulators to anticipate platform consolidation windows.
Market Dynamics
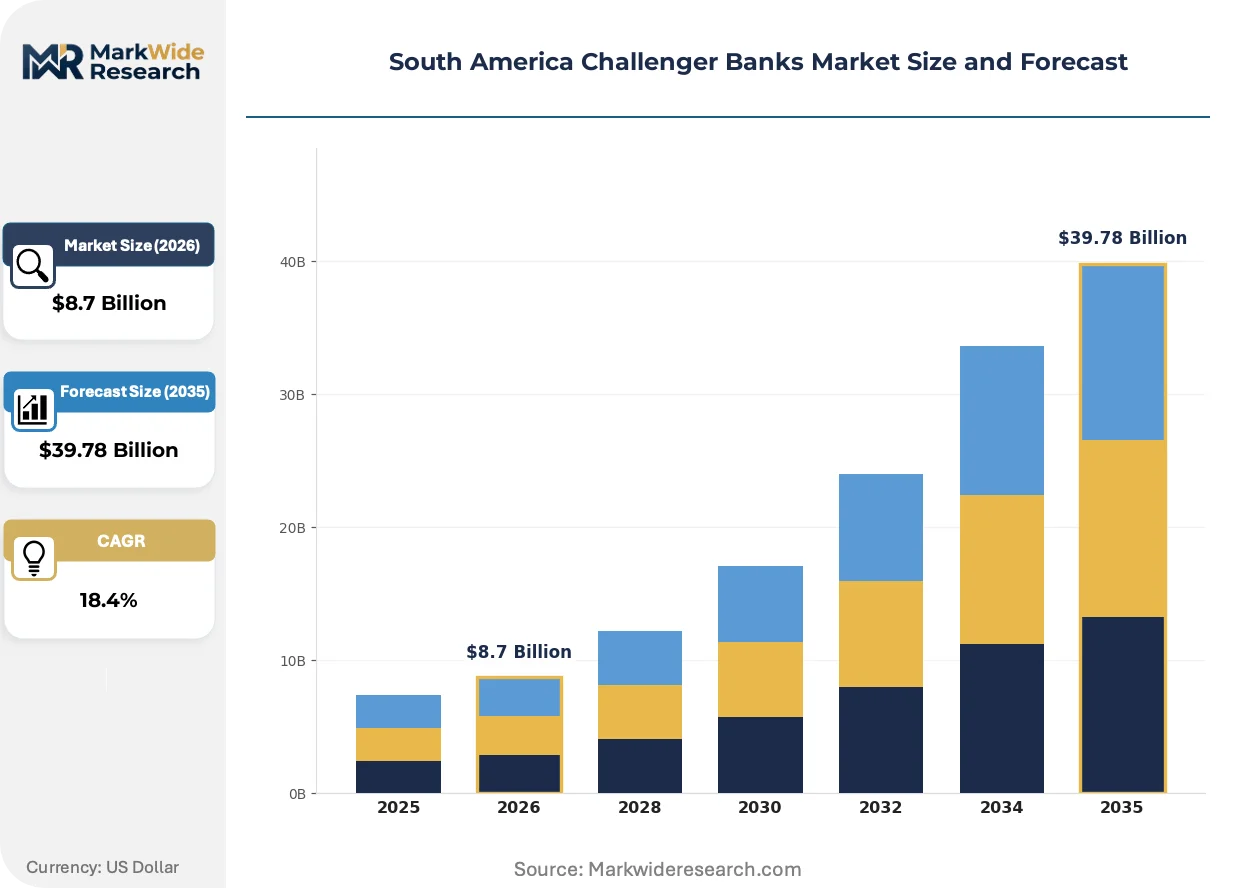
PIX instant payment infrastructure and open banking mandates from Brazil's Central Bank are dismantling the branch-based moats that protected legacy incumbents for decades, forcing a fundamental reconfiguration of how financial services are distributed and monetized across the continent.
Growth Catalysts
- PIX Ubiquity:Brazil's real-time payment rail processes billions of transactions monthly, eliminating friction for digital-native account opening and cross-border remittances.
- Open Banking Phase 3:The Central Bank of Brazil's expanded data-sharing mandates unlock embedded finance partnerships between challenger banks and retail ecosystems.
- Smartphone Penetration:Urban corridors from São Paulo to Buenos Aires have reached critical mass device ownership, collapsing the cost-to-serve for unbanked populations.
Market Restraints
- FX Volatility:Argentine peso instability and Colombian peso depreciation compress net interest margins for dollar-denominated liabilities.
- Credit Bureau Gaps:Thin-file consumers in rural Brazil and Paraguay lack sufficient data for algorithmic underwriting at scale.
- Concentrated Cloud Dependency:AWS and Azure dominance in São Paulo data centers creates single-point-of-failure risk for cloud-native cores.
Strategic Opportunities
- Colombia's Pacific Coast:Underpenetrated micro-enterprise segments in Buenaventura and Cali lack tailored working capital products.
- Cross-Border Wallets:Mercosur-Pacífico Alliance interoperability negotiations could unlock seamless P2P transfers across Andean markets.
- GenAI Convergence:Large language models layered atop open banking APIs enable hyper-personalized financial coaching at marginal cost.
Industry Challenges
- DevOps Talent Scarcity:São Paulo and Medellín face acute shortages of cloud-native engineers capable of maintaining zero-downtime core systems.
- Legacy Core Integration:Partnerships with correspondent banks require expensive middleware to bridge mainframe-era infrastructure with modern APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Challenger Banks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Banking, Digital Wallets, Online Loans, Payment Processing Customer Type: Small Businesses, Freelancers, Tech Startups, Individual Consumers Technology: Blockchain, AI-Driven Analytics, API Integration, Cloud Computing Delivery Model: Direct-to-Consumer, Partnered Retail Networks, Online Platforms, Subscription Services |
| Companies Covered | Nubank, Banco Inter, C6 Bank, Neon, Uala, PicPay, ModalMais, Banco Original, Nequi, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Challenger Banks Market Trends and Innovations
Embedded finance architectures and generative AI are compressing product development cycles from quarters to weeks, while regulatory sandboxes in Chile and Colombia accelerate experimentation with novel credit and insurance bundles.
Cloud-native core banking platforms built on microservices architectures are supplanting monolithic legacy systems that required multi-year implementation timelines. Colombian neobanks and Brazilian digital lenders are adopting these stacks within 90-day windows. The shift is collapsing capital expenditure requirements for market entry and enabling real-time feature deployment that legacy incumbents cannot replicate.
Brazil's Central Bank open finance mandates now require Phase 3 data sharing across insurance, investments, and pension products. This regulatory architecture forces traditional institutions to expose customer data through standardized APIs. Fintech aggregators in São Paulo and Rio de Janeiro are capturing disproportionate value from these pipes, building unified financial dashboards that erode single-product relationships.
Freelancers and gig workers across Argentina and Chile are abandoning traditional payroll-linked accounts for income-smoothing tools that aggregate multiple revenue streams. Digital wallets offering tax automation and invoice factoring are capturing these flows. Buenos Aires and Santiago show the highest concentration of this behavioral pivot, where platform economy participation exceeds formal employment in key demographic cohorts.
South America Challenger Banks Market Segmentation
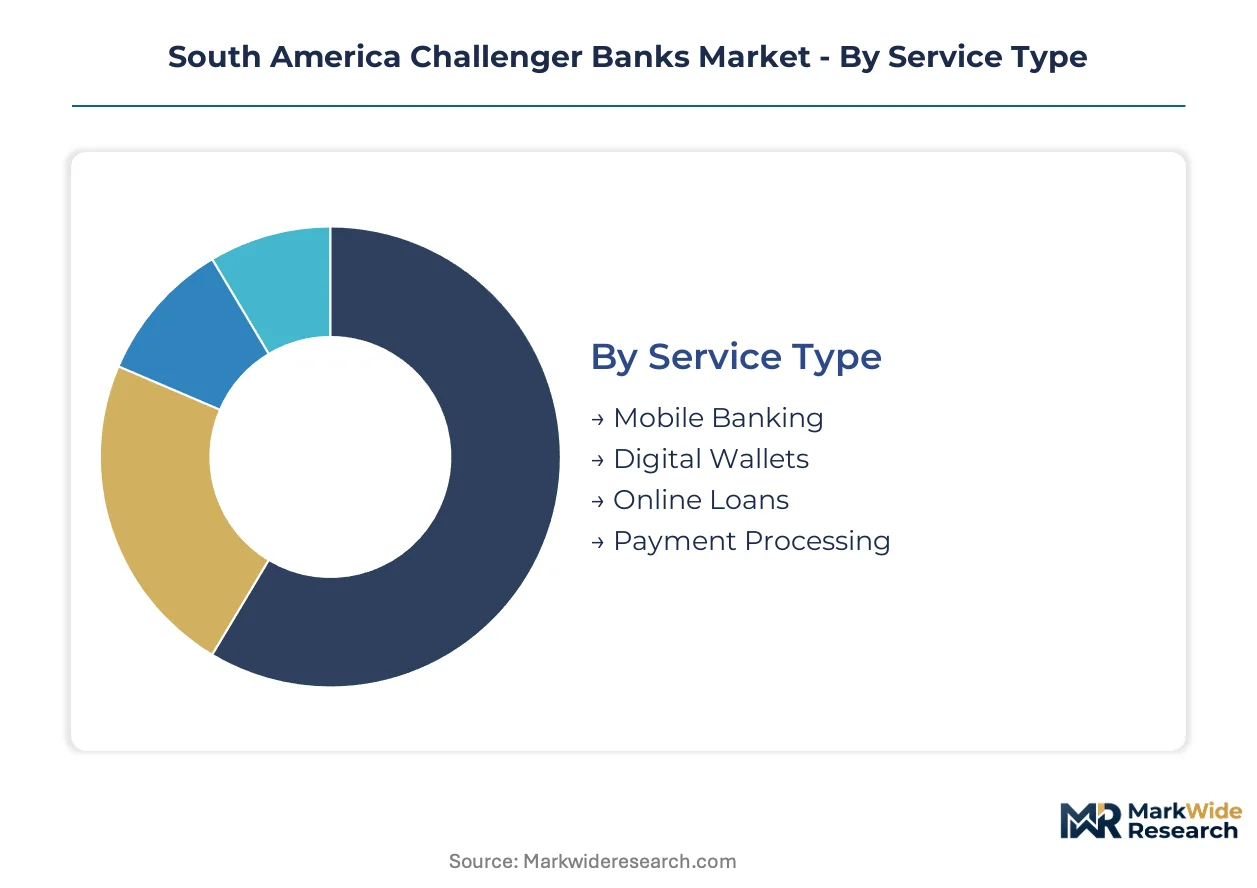
Challenger banks in South America segment across four intersecting dimensions that determine distribution economics and customer lifetime value. Service type and delivery model choices dictate unit economics, while customer type and technology stack selections shape risk-adjusted returns across Brazil, Colombia, and Argentina.
Service Type:
Channel-mix patterns reveal which services flow through PIX rails versus proprietary infrastructure, with mobile-native offerings capturing urban density while loan products require hybrid origination channels.
- Mobile Banking:Smartphone-native interfaces with real-time balance updates and PIX-integrated transfers. Demand clusters in São Paulo and Rio de Janeiro corridors where smartphone penetration and fintech literacy have reached critical mass, with customer acquisition costs collapsing as open banking standardizes identity verification.
- Digital Wallets:Stored-value accounts with merchant payment acceptance and P2P transfer capabilities. Argentina's informal economy and Brazil's gig worker corridors concentrate adoption, with PIX ubiquity eliminating interchange-dependent revenue models.
- Online Loans:Algorithmic credit scoring displaces traditional collateral requirements. Thin-file consumers in rural Brazil and Paraguay constrain scale, though alternative data sources from platform employment are expanding addressable markets.
- Payment Processing:Merchant-acquiring services with instant settlement through real-time payment rails. Small enterprises in Colombia's Pacific Coast cities lack tailored working capital integration, creating whitespace for embedded finance bundles.
Mobile Banking dominates installed base. Online Loans is where expansion concentrates.
Customer Type:
Margin profiles diverge sharply across customer segments, with transaction density and credit sophistication determining cross-sell potential and regulatory capital requirements.
- Small Businesses:Micro-enterprises requiring working capital, invoice factoring, and tax automation. Buenaventura and Cali in Colombia show acute underpenetration for tailored credit products, with platform economy participation exceeding formal banking relationships.
- Freelancers:Gig workers with irregular income streams seeking income-smoothing tools. Buenos Aires and Santiago exhibit the highest concentration of this behavioral pivot, where tax automation and multi-revenue aggregation drive wallet switching.
- Tech Startups:Venture-backed companies requiring treasury management and international wire capabilities. Chile and Colombia corridors deepen banking integration as venture capital deployment accelerates.
- Individual Consumers:Unbanked and underbanked populations adopting digital-first financial services. PIX infrastructure and open banking mandates from Brazil's Central Bank dismantle branch-based acquisition barriers.
Individual Consumers anchor volume scale. Tech Startups is climbing the fastest on a risk-adjusted basis.
Technology:
Technology stack choices determine time-to-market for new products and resilience against regulatory scrutiny on data governance and algorithmic fairness.
- Blockchain:Distributed ledger architectures for cross-border settlements and programmable compliance. Regulatory sandboxes in Chile accelerate experimentation with novel settlement rails.
- AI-Driven Analytics:Machine learning models for credit underwriting, fraud detection, and customer service automation. Large language models layered atop open banking APIs enable hyper-personalized financial coaching at marginal cost.
- API Integration:Standardized data exchange protocols mandated by open finance regulations. São Paulo and Rio de Janeiro aggregators capture disproportionate value from these pipes, building unified financial dashboards.
- Cloud Computing:Microservices architectures enabling 90-day core banking implementations versus multi-year legacy timelines. AWS and Azure dominance in São Paulo data centers creates concentration risk for cloud-native institutions.
API Integration commands the broadest deployment. AI-Driven Analytics is gaining share fastest as GenAI converges with open banking data.
Delivery Model:
Distribution economics vary dramatically by model, with direct acquisition costs compressing under open banking while partnered networks require revenue-sharing but accelerate geographic penetration.
- Direct-to-Consumer:App-based acquisition with digital onboarding and virtual card issuance. Nubank's sub-24-hour account provisioning at continental scale demonstrates cloud-native core advantages.
- Partnered Retail Networks:Embedded finance distribution through merchant ecosystems and payroll platforms. Banco Inter's hybrid marketplace-banking model competes on merchant ecosystem density rather than interest margins alone.
- Online Platforms:Web-first interfaces targeting desktop users in commercial banking segments. Legacy core integration through expensive middleware constrains feature velocity for correspondent bank partnerships.
- Subscription Services:Fee-based premium tiers with investment, travel, and insurance bundles. C6 Bank occupies premium positioning among mass-affluent Brazilians through embedded investment and travel rewards.
Direct-to-Consumer holds the deepest penetration. Partnered Retail Networks is where strategic investment is concentrating as embedded finance architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Central Bank anchors continental momentum through PIX infrastructure and phased open finance mandates that dismantle traditional branch-based distribution economics across South America.
Brazil
São Paulo and Rio de Janeiro corridors concentrate smartphone-native banking adoption where fintech literacy has reached critical mass. Brazil's Central Bank Phase 3 open finance mandates force data sharing across insurance and investment products, eroding single-product relationships. Nubank leverages cloud-native cores to sustain sub-24-hour account provisioning at continental scale from its São Paulo base.
Colombia
Nequi and digital entrants capture underbanked populations in Bogotá and Medellín corridors where platform economy participation exceeds formal banking relationships. Colombia's Superintendencia Financiera supervises evolving fintech licensing frameworks that standardize identity verification and compress customer acquisition costs. Buenaventura and Cali on the Pacific Coast lack tailored working capital products for micro-enterprises, creating whitespace for embedded finance bundles.
Argentina
Buenos Aires exhibits the highest concentration of freelancer behavioral pivots, where gig workers abandon payroll-linked accounts for income-smoothing tools aggregating multiple revenue streams. Argentine peso instability compresses net interest margins for dollar-denominated liabilities, forcing product innovation toward fee-based revenue. Regulatory sandboxes in Buenos Aires accelerate experimentation with novel credit and insurance bundles for platform economy participants.
Chile
Santiago corridors deepen venture capital banking integration as tech startups require treasury management and international wire capabilities. Chile's regulatory sandboxes enable experimentation with blockchain settlement rails and programmable compliance architectures. Alternative data sources from platform employment expand addressable markets for algorithmic underwriting among thin-file consumers in Santiago's urban core.
South America Challenger Banks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud-native scale players commanding premium positioning through embedded marketplace density while niche digital lenders compete on alternative underwriting velocity. The market structure reflects a consolidation gradient: three to four dominant institutions capture metropolitan corridor density, while regional specialists occupy underpenetrated Pacific Coast and Southern Cone segments. Strategic archetypes include hybrid marketplace-banking operators, premium mass-affluent targeting platforms, and API-first infrastructure providers. Competitive moves concentrate on embedded finance partnerships with retail ecosystems and correspondent bank middleware integration to bridge legacy core systems.
Within the integrated leader tier, Nubank and Banco Inter exemplify divergent scale strategies—Nubank occupying the cloud-native provisioning archetype with continental reach, while Banco Inter anchors merchant ecosystem density through hybrid marketplace-banking models. C6 Bank sits within the premium positioning archetype, targeting mass-affluent Brazilians through embedded investment and travel rewards rather than interest margin competition alone.
| Leading Market Players |
|---|
| Nubank |
| Banco Inter |
| C6 Bank |
| Neon |
| Uala |
| PicPay |
| ModalMais |
| Banco Original |
| Nequi |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cloud-native core implementation windows compress capital expenditure requirements for new entrants while simultaneously eroding pricing power for legacy incumbents tethered to multi-year mainframe migrations. This lead-time asymmetry concentrates margin capture among São Paulo-based challengers with microservices architectures, forcing traditional institutions into defensive price positioning across Brazil's urban corridors.
Pricing Analysis
Brazil-to-Argentina spreads on dollar-denominated deposit products widen during peso volatility episodes, compressing net interest margins for cross-border operators. The market runs on a subscription-plus-transaction hybrid model, with fee-based revenue from embedded investment and travel rewards separating C6 Bank's premium tier from mass-market PIX-dependent wallets. Pricing pressure stems from open banking standardization collapsing customer acquisition costs to near-zero in São Paulo corridors. Individual consumers in Argentina's informal economy exhibit acute price sensitivity to foreign exchange spreads, while mass-affluent Brazilians prioritize ecosystem density over rate comparisons.
Supply Chain Analysis
Just-in-time feature deployment through containerized microservices dominates operational preferences, displacing strategic stockpiles of legacy capacity. Cloud computing infrastructure draws from AWS and Azure concentration in São Paulo data centers, with API middleware and biometric identity verification modules as critical component inputs. Single-source vulnerability sits with hyperscaler dominance, where AWS outages cascade through Nubank's continental provisioning systems. Distribution runs through smartphone-native app stores and embedded retail partnerships rather than physical correspondent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among platform economy participants in Buenos Aires and Santiago corridors, where gig workers aggregate across multiple revenue streams and switch wallets based on tax automation features rather than brand loyalty. This fragmentation among freelancers forces providers into feature velocity competition.
For Market Incumbents: Shield core deposit relationships by accelerating cloud-native core migrations before Phase 3 open finance mandates expose customer data to aggregator competitors. Prioritize middleware investments bridging mainframe infrastructure with modern APIs to maintain correspondent bank partnerships against pure-digital challengers. For New Entrants and Emerging Players: Differentiate on alternative data underwriting velocity targeting thin-file consumers in Colombia's Pacific Coast micro-enterprise segments. Capture whitespace in Buenaventura and Cali working capital products through merchant ecosystem density rather than interest rate competition alone. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because open banking standardization rewards scale economics in API infrastructure and algorithmic credit scoring. Target acquisition profiles emphasizing cloud-native core completion and embedded finance partnership networks. Watch central bank digital currency pilots as inflection signals for interoperability treaty windows.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Brazil's Central Bank Phase 3 mandates force legacy institutions into multi-year infrastructure overhauls to remain competitive. |
| Embedded Finance Partnership | Banco Inter's merchant ecosystem density demonstrates alternative revenue models beyond net interest margin compression. |
| Alternative Data Underwriting | Platform employment records from Argentine gig workers expand addressable credit markets beyond traditional bureau coverage. |
| Cross-Border Wallet Integration | Mercosur-Pacific Alliance interoperability negotiations could unlock seamless P2P transfer corridors across Andean markets. |
| GenAI Financial Coaching Layer | Large language models atop open banking APIs enable hyper-personalized services at marginal cost in Santiago corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings from Brazil's Central Bank, Colombia's Superintendencia Financiera, and open finance mandate documentation. Conversations with neobank product executives, cloud infrastructure architects, and correspondent bank integration specialists informed operational assumptions. Secondary validation drew from PIX transaction disclosures, fintech licensing registries, and venture capital deployment databases. Bottom-up service-type demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include service type, customer archetype, technology stack, and delivery model, with geographic clustering across São Paulo-Rio de Janeiro, Bogotá-Medellín, Buenos Aires, and Santiago corridors. CAGRs derive from algorithmic credit penetration curves and smartphone-native banking adoption elasticity. Forecast inputs incorporate PIX infrastructure expansion timelines and open finance phase transition schedules without specific year anchoring.
Material uncertainties — regulatory sandbox outcome variability, central bank digital currency pilot scope, and Mercosur-Pacific Alliance treaty ratification — sit outside the modeled envelope. Forecasts reflect assumptions about PIX ubiquity maintenance and cloud hyperscaler pricing stability. Revision becomes warranted when Argentine peso volatility crosses thresholds that trigger dollarization flight from peso-denominated liabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Letter of Credit Confirmation Market
Banking
Smart Banking Solutions Market
Banking
Retail Banking Market
Banking
Japan Data Analytics in Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Cloud-Based Core Banking Market
Banking
Bank Management Software Market
Banking
Banking Wearable Devices Market
Banking
Performance Bank Guarantee Market
Banking
Africa Data Analytics in Banking Market
Banking
North America Machine Learning in Banking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Italy Data Analytics in Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Blockchain in Retail Banking Market