
 Commercial Banking Market | 2026-2036
Commercial Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Banking Market Analysis
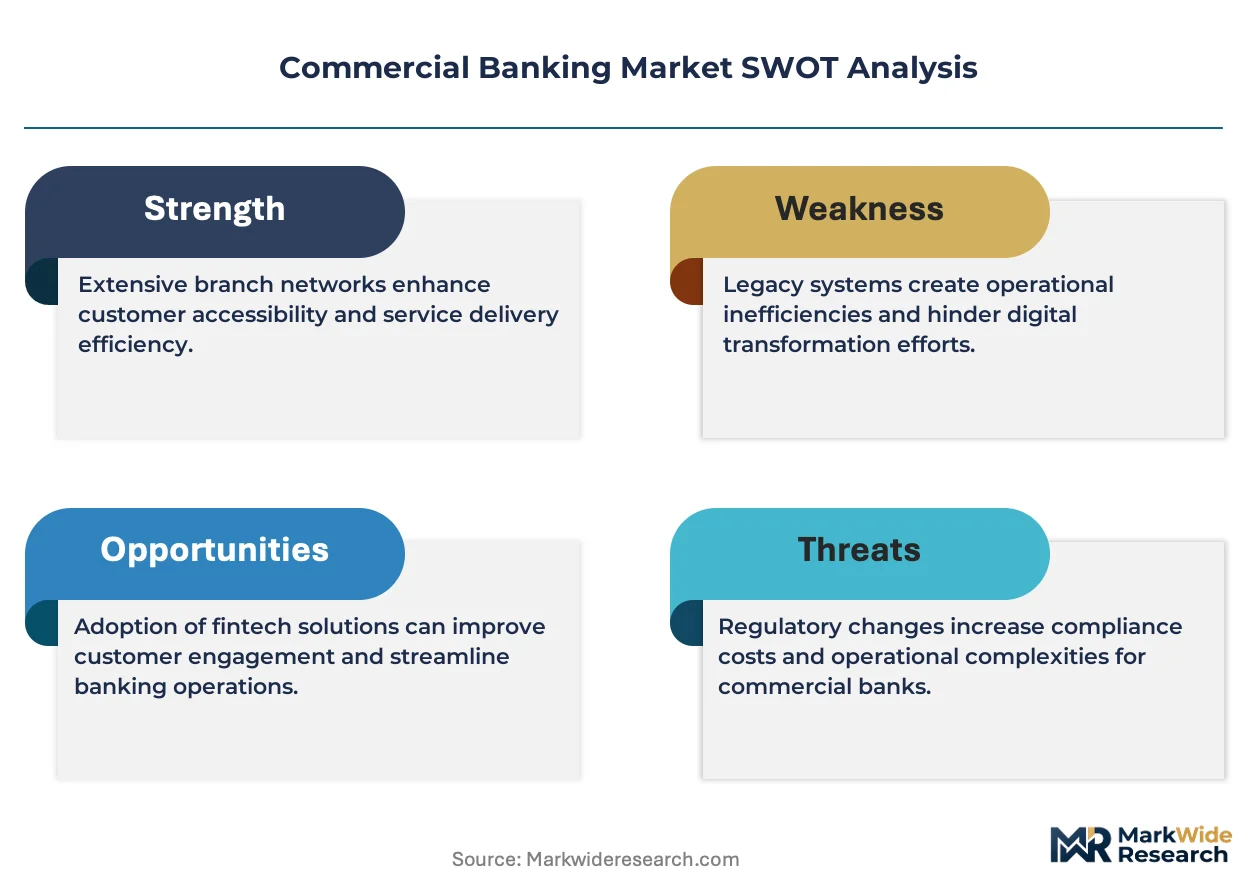
Corporate treasury concentration among mid-market enterprises is shifting toward relationship-heavy institutions that bundle cash management with advisory services. JPMorgan Chase & Co. leverages its balance sheet depth to anchor complex cross-border liquidity structures for Fortune 500 clients. Industrial and Commercial Bank of China dominates renminbi-denominated trade finance corridors through its state-backed network density. HSBC competes on correspondent banking reach, sustaining advantage in Asia-Europe transactional flows.
Commercial banking encompasses deposit-taking institutions that intermediate credit, manage payment systems, and provide treasury services to non-consumer entities, with core operations governed by risk-weighted asset frameworks and net interest margin mechanics. Corporate banking and investment banking segments concentrate fee income from capital markets activity, while wealth management captures recurring advisory revenue from high-net-worth pools. API banking and blockchain infrastructure segments are expanding fastest, though loans and deposit accounts still occupy the bulk of balance sheet allocation and regulatory scrutiny.
Basel Committee capital standards, national banking regulators including the Federal Reserve and the People's Bank of China, and jurisdiction-specific data frameworks such as GDPR in Europe shape product design, cross-border data flows, and market entry thresholds for new entrants. Compliance cost escalation favors incumbents with existing risk infrastructure over fintech challengers. Stakeholders must monitor divergence between Basel implementation timelines across the United States, European Union, and China, as asynchronous rulemaking fragments capital deployment strategies.
Market Dynamics
Open banking API proliferation is redistributing competitive advantage from balance-sheet scale toward data-interoperability infrastructure, forcing incumbents to rebuild core systems around real-time information exchange rather than proprietary silos.
Growth Catalysts
- Basel III Finalization:The Federal Reserve's implementation of enhanced risk-weighted capital standards is compressing regional bank leverage capacity, creating acquisition opportunities for well-capitalized money-center institutions with advanced stress-testing infrastructure.
- SME Credit Digitization:India's RBI-mandated account aggregator framework is enabling cash-flow-based lending algorithms that bypass traditional collateral requirements for small enterprises in tier-2 and tier-3 cities.
- Renminbi Internationalization:Cross-border settlement corridors through China's CIPS network are expanding renminbi-denominated trade finance volumes, requiring correspondent banks to upgrade clearing infrastructure.
Market Restraints
- Core System Modernization Costs:Legacy mainframe architectures at mid-tier institutions require capital deployment exceeding typical annual technology budgets, constraining competitive response speed.
- Regulatory Divergence:Asynchronous GDPR, CCPA, and China's PIPL implementation timelines fragment data architecture standardization, multiplying compliance engineering overhead for cross-border operators.
- Fintech Deposit Competition:Neobank yield offerings on insured sweep accounts are compressing funding cost advantages that traditional branch networks previously maintained through geographic density.
Strategic Opportunities
- Embedded Finance Convergence:Banking-as-a-Service platforms integrating with vertical SaaS providers in construction and logistics are capturing origination volume outside traditional branch footprints.
- Carbon Accounting Services:The EU CSRD's Scope 3 disclosure requirements are creating advisory revenue pools as corporate clients demand supply-chain emissions tracking bundled with treasury management.
- Sub-Saharan Africa Trade Finance:Underpenetrated correspondent banking networks in Nigeria and Kenya present first-mover advantages for institutions building local currency settlement capabilities ahead of AfCFTA implementation.
Industry Challenges
- Quantitative Risk Talent Scarcity:Competitive compensation from technology firms and hedge funds is constraining recruitment of machine-learning engineers capable of deploying real-time credit decisioning models.
- API Security Architecture:Open banking endpoints expand attack surfaces requiring continuous penetration testing and zero-trust network redesign, stretching information security team capacity.
- Interoperability Standardization Delays:Fragmented technical specifications across ISO 20022 implementation phases are forcing parallel system maintenance, increasing operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Banking Market |
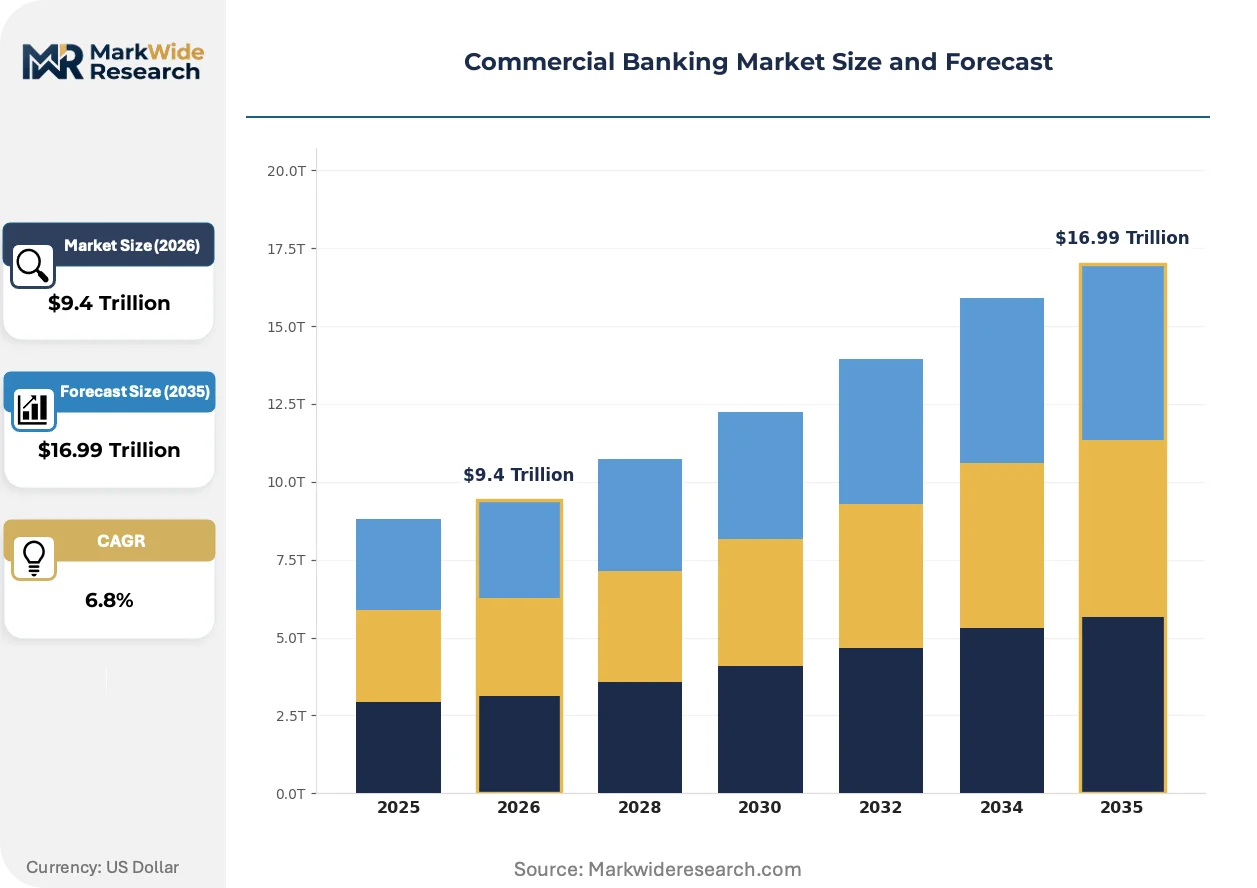
| Market Size in 2026 | $9.4 Trillion |
| Market Size in 2035 | $16.99 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Banking, Corporate Banking, Investment Banking, Wealth Management Client Type: Individual Customers, Small Enterprises, Corporates, Non-Profit Organizations Product Type: Loans, Mortgages, Credit Cards, Deposit Accounts Technology: Online Banking, Mobile Banking, API Banking, Blockchain |
| Companies Covered | JPMorgan Chase & Co., Bank of America Corp., Wells Fargo & Co., Citigroup Inc., Industrial and Commercial Bank of China, Agricultural Bank of China, China Construction Bank, HSBC, U.S. Bancorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Banking Market Emerging Trajectories
Commercial banking infrastructure is bifurcating between cloud-native challengers and incumbent core system renovation, with competitive differentiation migrating toward real-time data orchestration capabilities rather than physical distribution presence.
Real-time payment settlement infrastructure is absorbing correspondent banking volume as ISO 20022 message formats enable richer data attachment alongside fund transfers. Mid-market corporate treasurers in Germany and the Netherlands are migrating liquidity operations from traditional batch-based systems toward instant settlement rails. This compression of clearing cycles is absorbing float-based revenue models that previously subsidized account maintenance pricing.
China's SAMR antitrust enforcement against platform financial services is redirecting technology investment toward state-affiliated joint ventures and licensed banking subsidiaries rather than direct Big Tech competition. The structural consequence favors Industrial and Commercial Bank of China and Bank of China in capturing SME lending volume that Alibaba and Tencent previously dominated through ecosystem data advantages. Domestic institutions are responding by accelerating proprietary supply-chain finance platform deployment.
Corporate treasury centralization is consolidating banking relationships among multinationals seeking consolidated cash visibility across Asian manufacturing subsidiaries and European distribution entities. Relationship managers at HSBC and Standard Chartered are displacing fragmented local bank arrangements with regional liquidity structures spanning Singapore, Hong Kong, and London. This concentration pattern is most visible among consumer goods and industrial equipment manufacturers with complex multi-currency working capital requirements.
Commercial Banking Market Segmentation
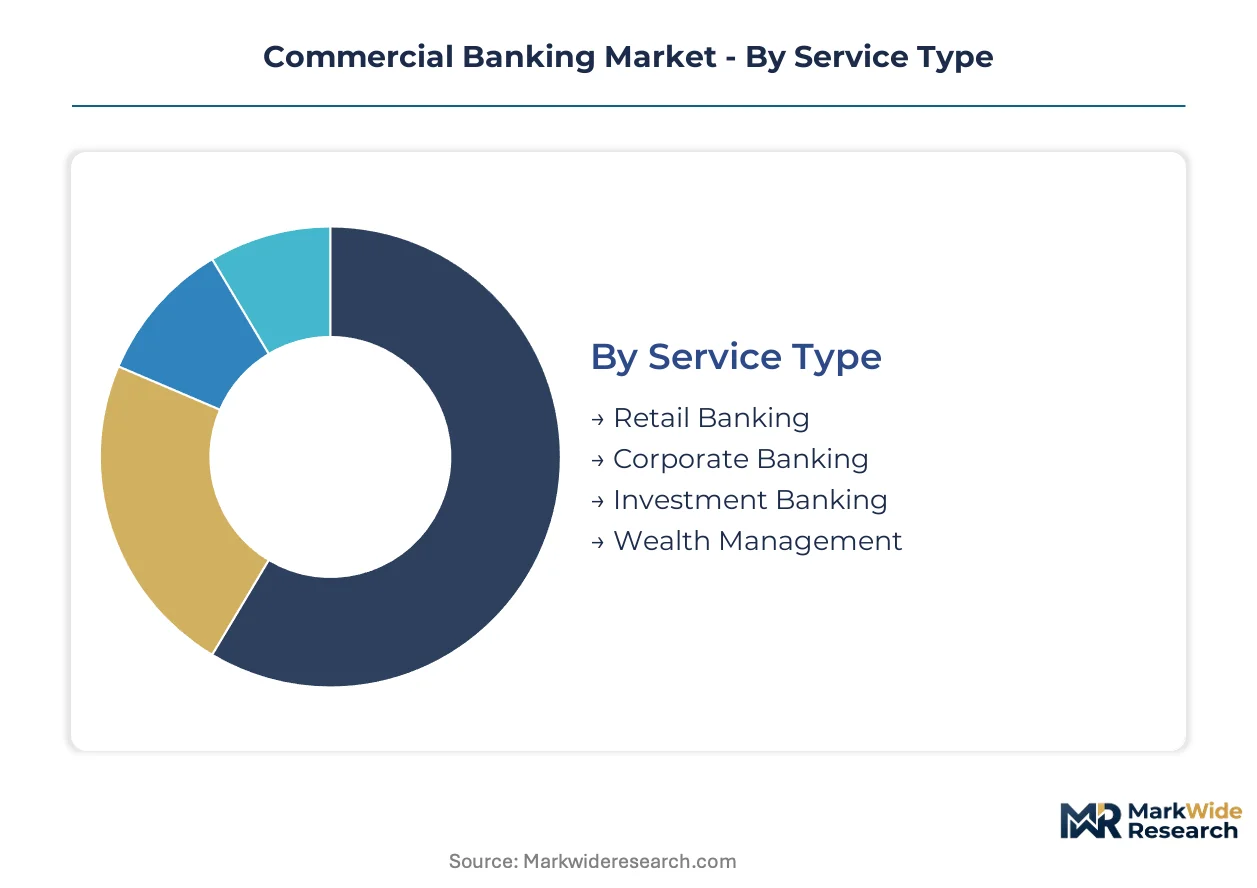
Segmentation in commercial banking reveals how revenue pools fragment across service models, client sophistication levels, and technology infrastructure investments. Understanding these divides exposes where capital allocation decisions concentrate and where margin compression threatens incumbent positioning.
Service Type:
Standalone service delivery dominates relationship-heavy segments, while embedded finance convergence is reshaping transactional and advisory offerings through platform integration.
- Retail Banking:Deposit-taking and consumer lending operations serving mass-market households through branch networks and digital channels. Demand concentrates in India's tier-2 cities where Jan Dhan-Aadhaar-Mobile infrastructure enables last-mile financial inclusion. Regulatory pressure from RBI on interest rate transparency compresses net interest margin predictability.
- Corporate Banking:Working capital facilities, trade finance, and treasury management for mid-market and large enterprises. German automotive suppliers and Dutch commodity traders are consolidating banking relationships around institutions offering real-time liquidity visibility across multi-currency operations. Basel III finalization favors money-center banks with advanced stress-testing infrastructure.
- Investment Banking:Capital markets underwriting, M&A advisory, and structured finance execution. Advisory revenue pools concentrate among Fortune 500 cross-border transactions requiring balance sheet depth for risk warehousing.
- Wealth Management:Investment advisory, trust services, and portfolio management for high-net-worth individuals. Singapore and Hong Kong private banking centers capture recurring fee income from Asia-Pacific family office migration.
Corporate Banking leads volumes today; API-enabled Retail Banking platforms are gaining share fastest.
Client Type:
Client sophistication tiers determine pricing power, with relationship depth and data availability creating divergent origination economics across the customer base.
- Individual Customers:Mass-market and affluent personal banking clients seeking transaction convenience and credit access. India's account aggregator framework is redirecting data ownership toward consumers, enabling cash-flow-based lending algorithms that bypass traditional collateral requirements.
- Small Enterprises:Micro-businesses and SME borrowers with limited financial statement history. Nigeria's underpenetrated correspondent banking networks present first-mover advantages for institutions building local currency settlement capabilities ahead of AfCFTA implementation.
- Corporates:Mid-market and large enterprises with complex treasury and capital markets needs. Multinationals are centralizing cash visibility across Asian manufacturing subsidiaries and European distribution entities, consolidating relationships around regional liquidity structures.
- Non-Profit Organizations:Charitable foundations, educational institutions, and NGOs requiring specialized fiduciary and grant management services. Compliance with EU CSRD Scope 3 disclosure requirements is creating advisory demand for supply-chain emissions tracking bundled with treasury management.
Corporates anchor fee income concentration; Small Enterprises show the steepest expansion trajectory as digitization unlocks previously unbanked segments.
Product Type:
Product architecture separates balance-sheet-intensive offerings from fee-generating services, with regulatory capital treatment driving strategic prioritization decisions.
- Loans:Term lending, revolving credit facilities, and asset-based finance requiring risk-weighted capital allocation. SME credit digitization in India's tier-3 cities is enabling algorithmic origination that compresses decision timelines from weeks to hours.
- Mortgages:Residential and commercial real estate secured lending with long-duration asset-liability management requirements. Rate volatility has compressed origination margins across developed markets.
- Credit Cards:Revolving consumer credit and commercial card programs generating interchange and interest income. Neobank yield competition on insured sweep accounts is pressuring funding cost structures.
- Deposit Accounts:Transactional and savings products forming the core funding base for lending operations. ISO 20022 message format adoption is enabling richer data attachment alongside fund transfers, absorbing float-based revenue models.
Loans occupy the largest balance sheet allocation; API-integrated Deposit Accounts are climbing the fastest as Banking-as-a-Service platforms capture origination volume outside traditional branch footprints.
Technology:
Technology infrastructure bifurcates between renovation of legacy core systems and greenfield cloud-native deployment, with interoperability standards determining competitive mobility.
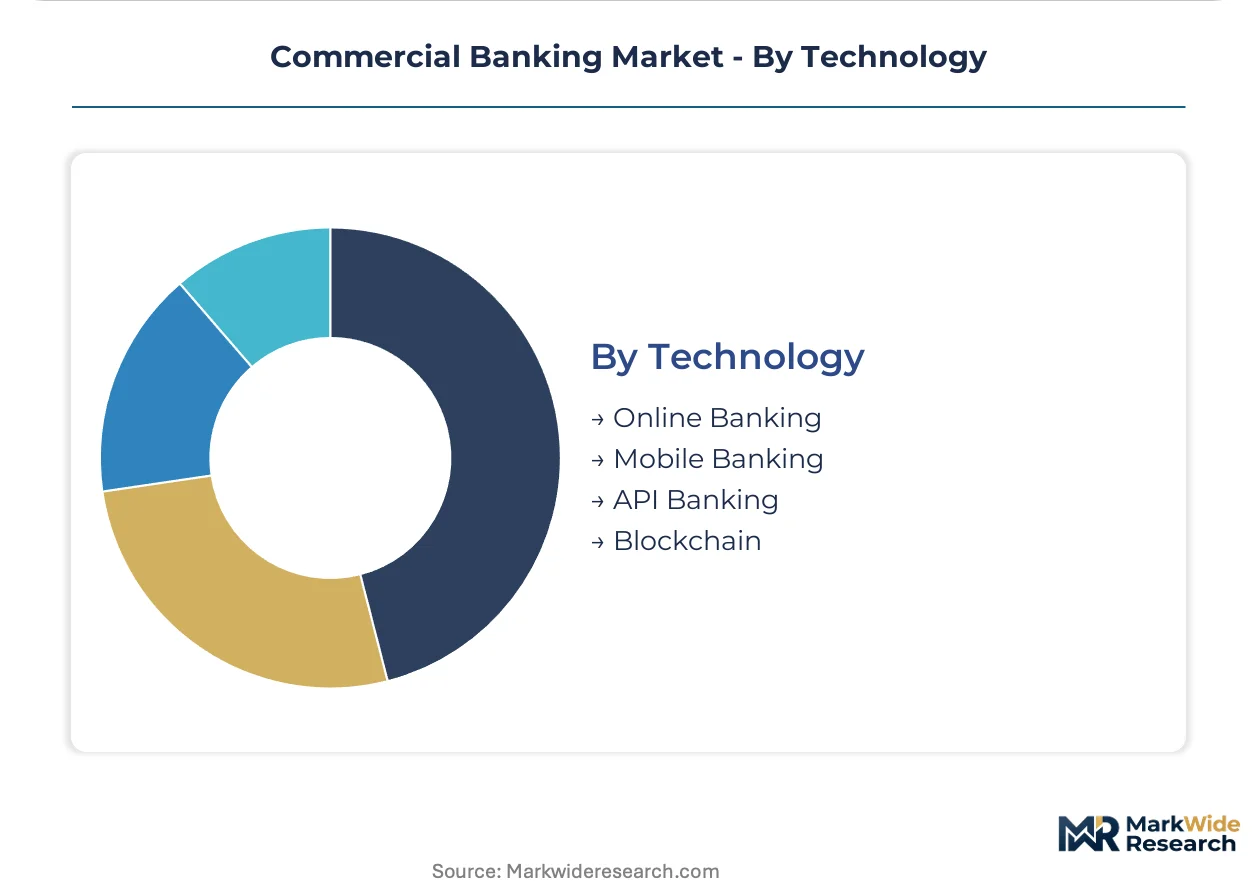
- Online Banking:Web-based transaction platforms and corporate treasury portals. Batch-based systems in Germany and the Netherlands are migrating toward instant settlement rails, compressing clearing cycle revenue.
- Mobile Banking:Smartphone-native applications for consumer and small business banking. China's SAMR antitrust enforcement against platform financial services is redirecting investment toward state-affiliated joint ventures and licensed banking subsidiaries.
- API Banking:Open banking interfaces enabling third-party data exchange and embedded finance integration. Regulatory divergence across GDPR, CCPA, and China's PIPL implementation timelines fragments data architecture standardization, multiplying compliance engineering overhead.
- Blockchain:Distributed ledger infrastructure for trade finance, cross-border settlement, and digital asset custody. Correspondent banks are upgrading clearing infrastructure to capture renminbi-denominated trade finance volumes through China's CIPS network.
Online Banking retains the largest user base; API Banking shows the most rapid adoption curve as real-time data orchestration displaces proprietary silo advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quantitative risk specialists and compliance engineers cluster in financial centers where regulatory complexity demands advanced technical infrastructure. Talent density in these hubs determines which institutions can deploy real-time credit decisioning and cross-border treasury platforms.
United States
Mid-market corporate treasurers demand consolidated cash visibility across multi-currency operations. The Federal Reserve's Basel III finalization compresses regional bank leverage capacity, favoring money-center institutions with advanced stress-testing infrastructure. New York and Chicago anchor the largest concentration of relationship-heavy banking operations bundling advisory with liquidity management.
China
Renminbi-denominated trade finance volumes expand through CIPS network corridors requiring correspondent bank infrastructure upgrades. SAMR antitrust enforcement redirects technology investment toward state-affiliated joint ventures and licensed banking subsidiaries. Shanghai and Shenzhen dominate renminbi clearing operations as Industrial and Commercial Bank of China captures SME lending volume previously held by platform financial services.
Germany
Automotive suppliers and commodity traders consolidate banking relationships around real-time liquidity visibility. EU CSRD Scope 3 disclosure requirements create advisory revenue pools for supply-chain emissions tracking bundled with treasury management. Frankfurt anchors the largest concentration of corporate banking operations serving cross-border manufacturing subsidiaries.
India
Tier-2 and tier-3 city small enterprises expand credit utilization through cash-flow-based lending algorithms. RBI-mandated account aggregator frameworks enable data ownership redirection toward consumers, bypassing traditional collateral requirements. Mumbai and Bangalore cluster the technical talent deploying API-enabled origination platforms.
Singapore
Asia-Pacific family office migration concentrates private banking and wealth management fee income. Multinationals centralize treasury operations spanning Asian manufacturing subsidiaries and European distribution entities. The city-state anchors regional liquidity structures displacing fragmented local bank arrangements across consumer goods and industrial equipment sectors.
Commercial Banking Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across relationship-heavy and technology-enabled segments. The market structure concentrates among institutions with balance sheet depth sufficient for cross-border risk warehousing and complex liquidity structures. Three archetypes dominate: universal banks bundling corporate and investment banking, state-backed institutions leveraging network density for trade finance, and technology-forward specialists capturing API-enabled origination. Competitive moves center on M&A to acquire stress-testing infrastructure and strategic partnerships embedding banking services into vertical SaaS platforms.
Among universal banking groups, JPMorgan Chase & Co. and Bank of America Corp. occupy positions exemplifying balance-sheet scale deployment for Fortune 500 cross-border structures. Industrial and Commercial Bank of China represents the state-backed archetype leveraging renminbi corridor dominance. HSBC sits within the correspondent banking tier where Asia-Europe transactional flow concentration sustains competitive positioning.
| Leading Market Players |
|---|
| JPMorgan Chase & Co. |
| Bank of America Corp. |
| Wells Fargo & Co. |
| Citigroup Inc. |
| Industrial and Commercial Bank of China |
| Agricultural Bank of China |
| China Construction Bank |
| HSBC |
| U.S. Bancorp |
| Others |
Supply Flow & Price Mechanics
EU CSRD Scope 3 disclosure mandates gate access to premium-tier corporate advisory bundles, forcing institutions to restructure supply chains around carbon-accounting competency and certified data lineage before pricing power materializes.
Pricing Analysis
The bundled-vs-unbundled service split separates relationship-heavy treasury management from transactional commodity offerings. Pricing stratifies across premium advisory tiers, standard relationship packages, and economy self-service portals, with differentiation driven by real-time data integration depth and cross-border coverage density. Cost compression in the economy tier is intensifying because neobank yield competition erodes deposit-funded margin structures. Small enterprises exhibit highest price sensitivity, while Fortune 500 treasurers prioritize liquidity visibility over rate spreads.
Supply Chain Analysis
India's RBI-mandated account aggregator rules and China's SAMR licensing requirements are reshaping sourcing toward domestic data infrastructure and state-affiliated joint ventures. Technology supply draws from the United States, India, and China, with core banking platforms, API middleware, and cloud infrastructure forming critical dependencies. Single-source vulnerability concentrates in legacy mainframe maintenance pools. Distribution runs through correspondent banking networks and embedded finance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where corporate treasury centralization favors institutions bundling carbon-accounting compliance with liquidity management.
For Market Incumbents: Anticipate margin compression in transactional deposit products by accelerating proprietary supply-chain finance platform deployment. Defensive consolidation through stress-testing infrastructure acquisition counters fintech challengers exploiting open banking endpoints. Vertical integration into carbon-accounting advisory services captures EU CSRD-driven fee pools. For New Entrants and Emerging Players: The premium-economy pricing gap in SME cash-flow-based lending creates white-space opportunity in India's tier-3 cities and Nigeria's underpenetrated trade finance corridors. Embedded finance partnerships with vertical SaaS providers in logistics and construction bypass branch network requirements. API-first origination platforms targeting unbanked small enterprises offer the most penetrable entry vector. For Investors and Strategic Acquirers: Roll-up economics work for regional banks with advanced stress-testing infrastructure because Basel III finalization compresses leverage capacity and creates distressed acquisition targets. Long-term viability centers on institutions capturing relationship-heavy advisory revenue rather than commodity transactional flows. Watch for divergence in Basel implementation timelines across the United States, European Union, and China as the signal for capital deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API Banking Platform Integration | Open banking infrastructure enables real-time data exchange displacing proprietary silo advantages. |
| Carbon Accounting Service Launch | EU CSRD Scope 3 compliance creates advisory revenue bundled with treasury management. |
| Stress-Testing Infrastructure Acquisition | Basel III finalization favors institutions with advanced risk-weighted capital modeling. |
| Embedded Finance Partnership | Banking-as-a-Service platforms capture origination outside traditional branch footprints. |
| Renminbi Clearing Capability Buildout | CIPS network expansion requires correspondent bank infrastructure upgrades. |
Methodological Framework
Multiple input streams — primary interviews with corporate treasurers and relationship managers, secondary validation through regulatory filings and trade finance databases, and proprietary balance-sheet analytics — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed chief risk officers at money-center institutions, API platform engineers, SME lending specialists, and compliance officers navigating GDPR-CCPA-PIPL divergence. Secondary sources included Federal Reserve stress-testing disclosures, RBI circulars on account aggregators, Basel Committee implementation timelines, and ISO 20022 migration status reports.
Data-stream reconciliation anchored volume projections across service type, client sophistication tier, technology infrastructure, and regional regulatory cluster dimensions. CAGRs were derived from segment-level origination trajectories and net interest margin compression curves. Forecast inputs incorporated open banking API adoption velocity, renminbi internationalization corridor expansion, and SME credit digitization penetration rates.
The model assumes a particular technology adoption path; alternative pathways for blockchain-based trade finance settlement would alter the outlook. Forecasts reflect assumptions around regulatory harmonization timelines and capital standard implementation sequencing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
France Data Analytics in Banking Market
Banking
US Banking-As-A-Service Market
Banking
Global Big Data Analytics in Banking Market
Banking
Italy Data Analytics in Banking Market
Banking
Retail Banking IT Spending Market
Banking
Data Analytics in Banking Market
Banking
Bank Management Software Market
Banking
US Retail Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Australia Neobanking Market
Banking
Video Banking Service Market
Banking
Germany Banking As a Service Market
Banking
Third-Party Banking Software Market
Banking
Investment Banking and Trading Services Market
Banking
Banking Maintenance Support and Services Market
Banking
Singapore Data Analytics in Banking Market