
 Germany Data Analytics in Banking Market | 2026-2036
Germany Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Analytics in Banking Market Insights
Retail banking is consolidating its position as the dominant end-user vertical, displacing slower-moving credit unions in analytics procurement. SAP leverages deep ERP integration to anchor enterprise-wide data platforms across Sparkassen and Volksbanken networks. Oracle competes through specialized database architectures optimized for real-time transaction processing, while IBM sustains credibility in regulatory compliance modules through longstanding relationships with Bundesbank-supervised institutions.
Germany Data Analytics in Banking encompasses the systematic extraction, processing, and modeling of structured and unstructured financial data to generate actionable intelligence, typically operating across sub-100-millisecond latency thresholds for real-time decisioning. Its primary purpose spans credit risk quantification, anti-money laundering surveillance, and personalized product recommendation engines. Predictive analytics leads current deployment value as mature statistical methods outperform experimental AI in Basel IV capital calculations, though machine learning is accelerating fastest among neobanks seeking alternative credit scoring. Fraud detection applications occupy entrenched positions with stable margins, whereas customer insights segments show expanding margin pools as institutions monetize behavioral data for cross-selling.
BaFin's MaRisk circulars and the EU AI Act's risk-based classification framework collectively mandate explainable algorithms for credit and insurance decisions, directly shaping vendor product roadmaps and procurement specifications. GDPR constraints on profiling further restrict how banks deploy customer insights solutions, creating compliance-driven demand for privacy-preserving analytics architectures. Stakeholders must monitor how the European Banking Authority's forthcoming technical standards on AI governance reshape competitive requirements for algorithmic transparency and model documentation.
Market Dynamics
BaFin's algorithmic transparency mandates and the EU AI Act's risk-based classification framework are forcing German banks to rebuild procurement specifications around explainable decisioning systems, compressing vendor selection cycles and elevating compliance architecture to a primary competitive differentiator.
Growth Catalysts
- BaFin MaRisk Circulars:Mandatory explainable algorithms for credit decisions are creating procurement pull for transparent analytics platforms across Sparkassen and cooperative banking networks.
- Cloud Migration:Fintech companies and neobanks in Frankfurt and Munich are accelerating adoption of cloud-native analytics to bypass legacy infrastructure constraints.
- Basel IV Capital Calculations:Predictive analytics deployment is deepening as mature statistical methods prove superior for regulatory capital quantification.
Market Restraints
- GDPR Profiling Constraints:Customer insights monetization faces hard operational limits from privacy regulations restricting behavioral data deployment.
- Legacy System Integration:Cooperative banks struggle with technical debt from decades-old core banking architectures that resist real-time analytics overlay.
- Specialized Talent Scarcity:Explainable AI development requires rare combinations of regulatory knowledge and machine learning engineering concentrated in Berlin and Munich.
Strategic Opportunities
- Privacy-Preserving Architectures:Federated learning and differential privacy techniques are opening compliant pathways for cross-institutional data collaboration.
- Real-Time Transaction Processing:Sub-100-millisecond decisioning infrastructure is creating new margin pools in instant payment verification and dynamic credit limits.
- European Banking Authority Standards:Forthcoming AI governance technical standards will reshape competitive requirements for model documentation and audit trails.
Industry Challenges
- Model Documentation Burden:Regulatory audit trails demand exhaustive algorithmic provenance records that extend development cycles and inflate compliance staffing.
- Cross-Functional Talent Gaps:Banks struggle to recruit professionals fluent in both statistical modeling and BaFin supervisory expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Analytics in Banking Market |
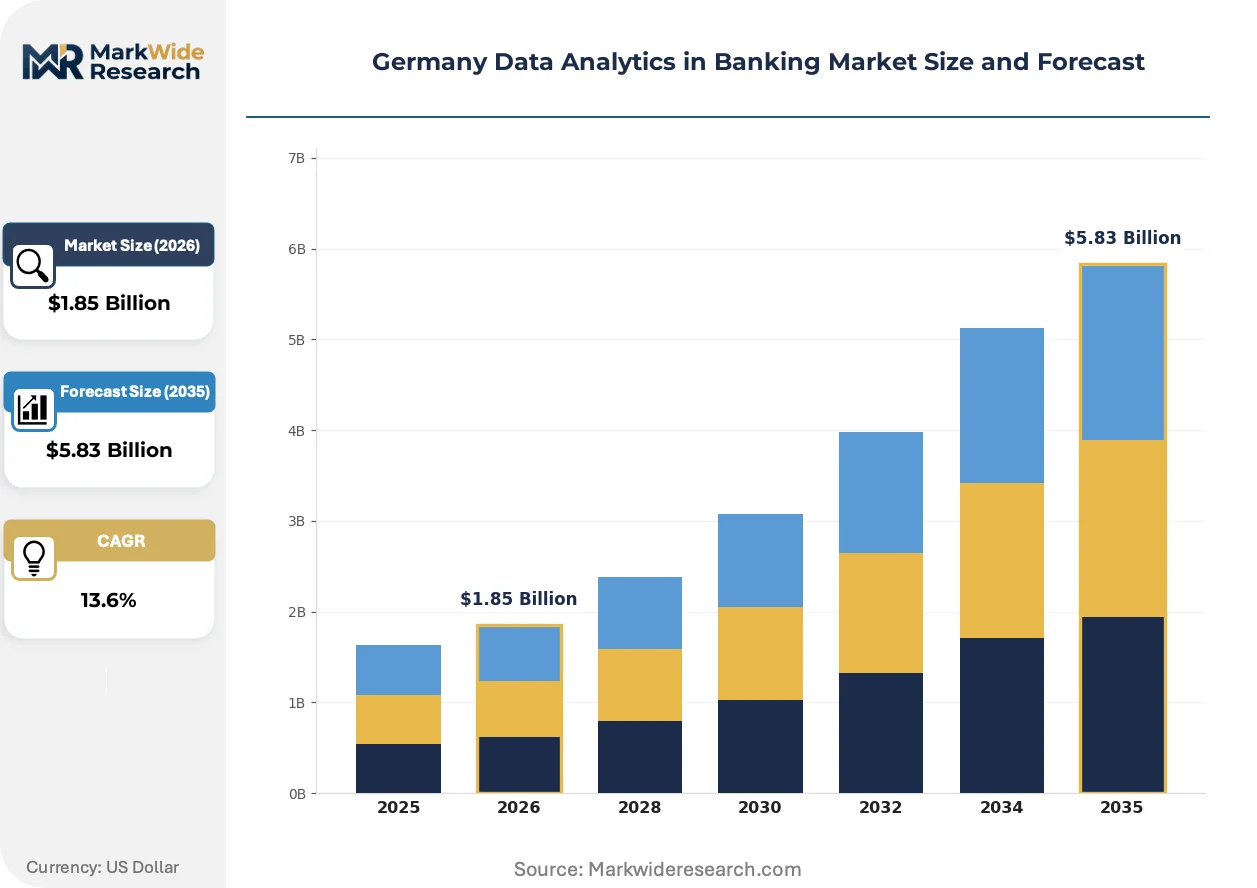
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.83 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Artificial Intelligence, Big Data, Predictive Analytics Application: Risk Management, Customer Insights, Fraud Detection, Regulatory Compliance End User: Retail Banks, Investment Banks, Credit Unions, Fintech Companies Solution: Cloud-Based Solutions, On-Premise Solutions, Real-Time Analytics, Reporting Tools |
| Companies Covered | SAP, FIS, Temenos, Oracle, Finastra, Avaloq, Sopra Banking Software, IBM, Microsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Analytics in Banking Market Trends and Innovations
Three distinct vectors are compressing competitive timelines in German banking analytics: infrastructure convergence around unified data platforms, regulatory pressure accelerating explainable AI deployment, and procurement rationalization favoring outcome-aligned vendor relationships over perpetual licensing.
Data fabric architecture is unifying previously siloed transaction records, customer profiles, and risk models into queryable layers accessible to both business analysts and automated decision engines. Sparkassen networks are piloting these platforms fastest, driven by centralized IT procurement through their regional associations. This unifying infrastructure is collapsing the traditional separation between operational and analytical data stores, enabling real-time risk recalculation that was previously batch-processed overnight.
The EU AI Act's high-risk system classification is mandating human oversight interfaces and algorithmic impact assessments for credit scoring and insurance pricing modules. German institutions supervised by BaFin must now maintain model cards documenting training data provenance, performance benchmarks, and failure mode analyses. Retail banking product teams are responding by embedding compliance checkpoints earlier in development pipelines, often at the cost of extended time-to-market for experimental features.
Cooperative banks are consolidating vendor relationships around outcome-based performance contracts that tie analytics platform fees to measurable improvements in fraud detection accuracy or cross-sell conversion rates. This displaces traditional seat-based SaaS pricing that ignored actual business impact. Procurement centralization through DZ Bank and Bundesverband der Deutschen Volksbanken is most visible in this shift, with regional institutions pooling negotiating leverage to demand guaranteed ROI thresholds.
Germany Data Analytics in Banking Market Segmentation
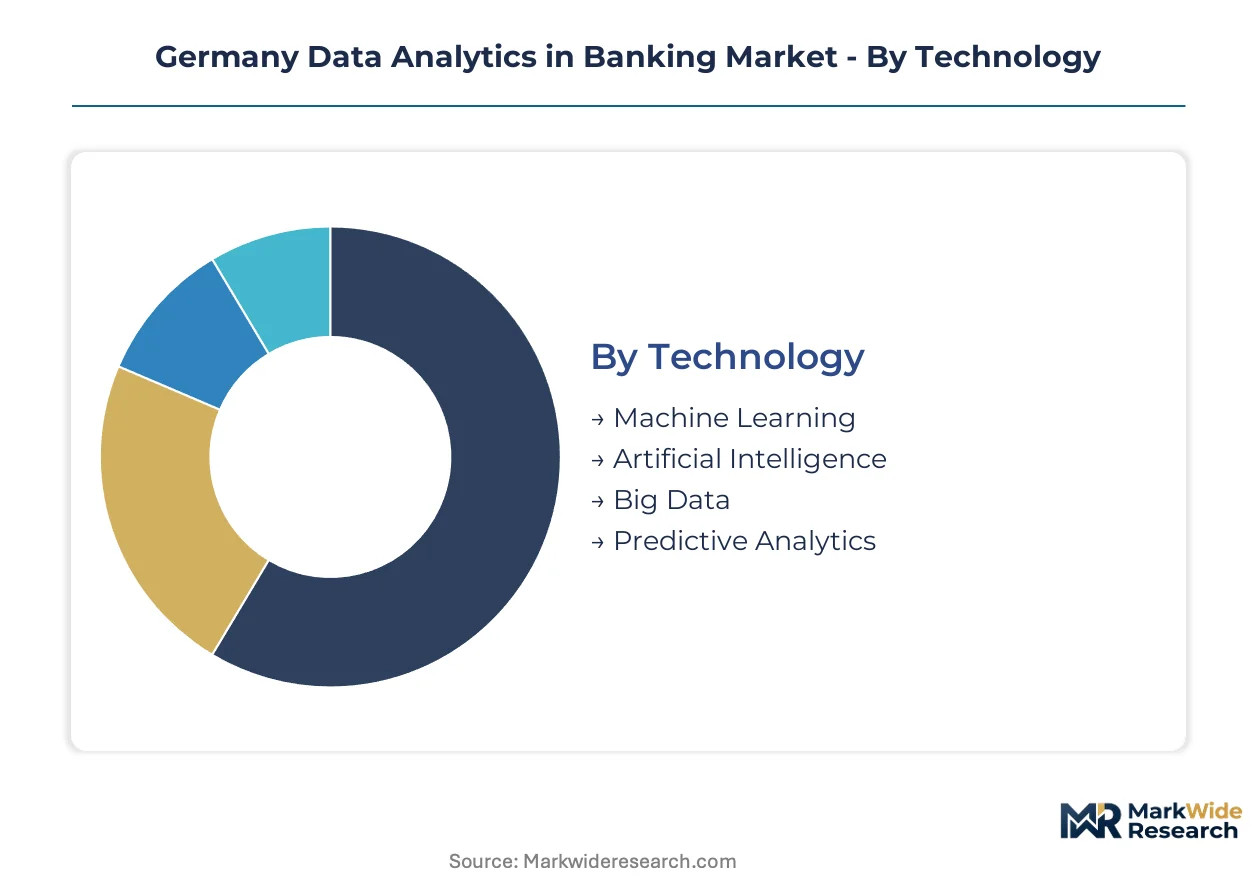
Segmentation in German banking analytics reveals how procurement priorities diverge across technology maturity, regulatory exposure, and infrastructure legacy. Institutions select capabilities based on BaFin supervision intensity and core system constraints rather than generic feature comparisons.
Technology:
Technology upgrade cycles in German banking are compressing as BaFin mandates force replacement of black-box algorithms with explainable alternatives.
- Predictive Analytics:Mature statistical methods dominate Basel IV capital calculations across Sparkassen networks, with proven reliability in credit risk quantification. Demand concentrates in Frankfurt's wholesale banking cluster where regulatory audit requirements favor transparent regression models over opaque neural architectures.
- Machine Learning:Neobanks and fintech companies deploy gradient-boosted frameworks for alternative credit scoring, bypassing traditional bureau dependencies. Munich-based digital lenders drive fastest adoption as they build proprietary risk engines from customer transaction histories.
- Artificial Intelligence:Natural language processing applications extract entity relationships from unstructured loan documentation.
- Big Data:Distributed storage architectures aggregate decades of transactional archives for behavioral pattern mining.
Volume placements concentrate in Predictive Analytics; the faster expansion belongs to Machine Learning.
Application:
Application demand patterns track directly to EU AI Act risk classifications and corresponding supervisory scrutiny levels.
- Risk Management:Credit scoring and portfolio stress-testing modules absorb the largest procurement budgets across Landesbanken, driven by ECB supervisory expectations for model risk governance. Frankfurt-based institutions centralize these investments through shared service centers serving multiple regional entities.
- Fraud Detection:Real-time transaction monitoring systems with sub-100-millisecond latency thresholds protect instant payment rails. Cooperative banks in Bavaria prioritize these deployments following targeted phishing campaigns against rural customer bases.
- Customer Insights:Behavioral segmentation tools face GDPR profiling constraints that limit deployment scope.
- Regulatory Compliance:Automated reporting pipelines streamline BaFin submission workflows for smaller institutions.
Procurement intensity peaks in Risk Management; Customer Insights encounters the steepest regulatory headwinds.
End User:
End-user economics diverge sharply between legacy institutions carrying technical debt and digital-native competitors building analytics-first architectures.
- Retail Banks:Sparkassen and Volksbanken networks consolidate procurement through regional IT associations, achieving scale advantages in platform licensing. Their branch-dense operations generate rich transaction datasets that fuel cross-selling algorithm development.
- Fintech Companies:Cloud-native stacks enable rapid experimentation with alternative data sources for credit decisions. Berlin and Munich clusters attract venture funding specifically for explainable AI capabilities that satisfy upcoming EBA technical standards.
- Investment Banks:Wholesale trading operations demand ultra-low-latency analytics for market risk calculations.
- Credit Unions:Smaller asset bases restrict in-house development, forcing reliance on cooperative data center consortia.
Platform spending concentrates in Retail Banks; Fintech Companies are gaining share fastest in headcount-adjusted terms.
Solution:
Solution architecture choices reflect infrastructure ownership patterns and data sovereignty requirements under German banking law.
- Cloud-Based Solutions:Frankfurt-based fintech companies and neobanks bypass legacy constraints through API-first analytics platforms. Regulatory comfort with EU-sovereign cloud regions accelerates migration timelines for mid-tier institutions previously committed to on-premise stacks.
- Real-Time Analytics:Sub-100-millisecond decisioning infrastructure enables dynamic credit limits and instant payment verification. Munich's digital banking cluster leads deployment as customer expectations shift from batch to continuous risk recalculation.
- On-Premise Solutions:Bundesbank-supervised institutions maintain captive data centers for core risk systems.
- Reporting Tools:Standardized visualization layers satisfy BaFin documentation requirements with minimal customization.
Deployment scale favors Cloud-Based Solutions; Real-Time Analytics demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Mainhattan financial district operates as Germany's primary data analytics concentration zone, with BaFin-supervised institutions clustering procurement decisions within the city's regulatory orbit. Tax incentives for fintech headquarters in Hesse accelerate vendor co-location alongside Landesbanken and cooperative banking networks.
Bavaria
Munich anchors southern Germany's neobank density, with digital lenders deploying cloud-native risk engines for alternative credit scoring. The Bavarian Ministry of Economic Affairs funds AI competency centers through its High-Tech Agenda. Munich's cluster hosts machine learning engineering talent concentrated in Schwabing and Garching research parks.
North Rhine-Westphalia
Düsseldorf and Cologne house insurance-banking hybrids demanding real-time analytics for bancassurance product bundles. The state's Digital Hub Initiative channels grants toward explainable AI development for credit decisions. Cologne's media-banking convergence generates unique behavioral data assets for cross-selling algorithms.
Baden-Württemberg
Stuttgart's manufacturing finance specialists apply predictive analytics to supply chain lending and equipment leasing portfolios. The state's Mittelstand-focused economic programs subsidize SME credit risk modeling tools. Karlsruhe's IT security cluster feeds fraud detection engineering pipelines for cooperative banks.
Berlin-Brandenburg
Berlin's fintech ecosystem drives fastest machine learning adoption among digital-native challengers unburdened by legacy core systems. The federal government's AI strategy funds regulatory sandbox programs through BaFin collaboration. Potsdam's University of Applied Sciences pipelines explainable AI talent toward compliance-heavy banking roles.
Hamburg
Hamburg's trade finance specialists deploy analytics for commodity-backed lending and shipping risk quantification. The city's port-centric economic development zones incentivize maritime banking technology clusters. HafenCity's fintech incubators concentrate alternative data sourcing for international trade credit decisions.
Germany Data Analytics in Banking Market Competitive Landscape
Top-tier vendors anchor enterprise-wide platform contracts across Sparkassen and Volksbanken networks, while mid-tier specialists compete for modular point solutions in fraud detection and regulatory reporting. The vendor structure stratifies between ERP-integrated incumbents with decades-long banking relationships and cloud-native challengers targeting neobank greenfield deployments. Three archetypes dominate: core banking platform extenders, standalone analytics specialists, and hyperscale cloud providers with financial services certifications. Competitive dynamics center on procurement centralization through cooperative IT associations and outcome-based pricing models displacing perpetual licenses.
Within the ERP-integrated tier, SAP and Oracle occupy positions as archetypal platform anchors, with SAP leveraging deep Sparkassen network penetration and Oracle competing through database architecture specialization. IBM sits within the regulatory compliance module segment, sustained by longstanding Bundesbank-supervised institutional relationships. These three exemplify how vendor selection in German banking analytics increasingly hinges on BaFin-aligned documentation capabilities and pre-certified algorithmic transparency frameworks rather than raw processing performance.
| Leading Market Players |
|---|
| SAP |
| FIS |
| Temenos |
| Oracle |
| Finastra |
| Avaloq |
| Sopra Banking Software |
| IBM |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between BaFin-compliant explainable AI platforms and non-compliant legacy systems manifests in both pricing premiums and supply chain consolidation. Tier-one vendors command sustained margins through pre-certified algorithmic transparency frameworks, while mid-tier suppliers face cost compression from cooperative banks pooling procurement through DZ Bank and regional Sparkassen IT associations.
Pricing Analysis
Short lead-time premiums for EU AI Act-compliant deployments run 15-25% above standard SaaS tiers, reflecting scarce explainable AI engineering capacity concentrated in Berlin and Munich. The dominant pricing structure stratifies across outcome-based performance contracts, seat-based SaaS licensing, and project-based implementation fees. Price differentiation hinges on BaFin certification status and real-time processing latency guarantees below 100 milliseconds. Cost compression in the mid-tier intensifies because cooperative banks demand guaranteed ROI thresholds tied to fraud detection accuracy improvements. Fintech companies in Frankfurt exhibit the highest price sensitivity, while Bundesbank-supervised Landesbanken prioritize compliance architecture over unit economics.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale providers with EU-sovereign data center certifications in Germany, Ireland, and the Netherlands. Specialized compute hardware for real-time analytics draws from Taiwanese semiconductor foundries and German precision engineering clusters. Raw material dependencies span advanced GPUs, high-bandwidth memory modules, and optical interconnects. Single-source vulnerability concentrates in NVIDIA's dominance of training-grade accelerators, compounded by export restriction exposure on cutting-edge AI chips. Distribution runs through systems integrators with deep Sparkassen network relationships, anchored by SAP and Oracle's entrenched platform positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
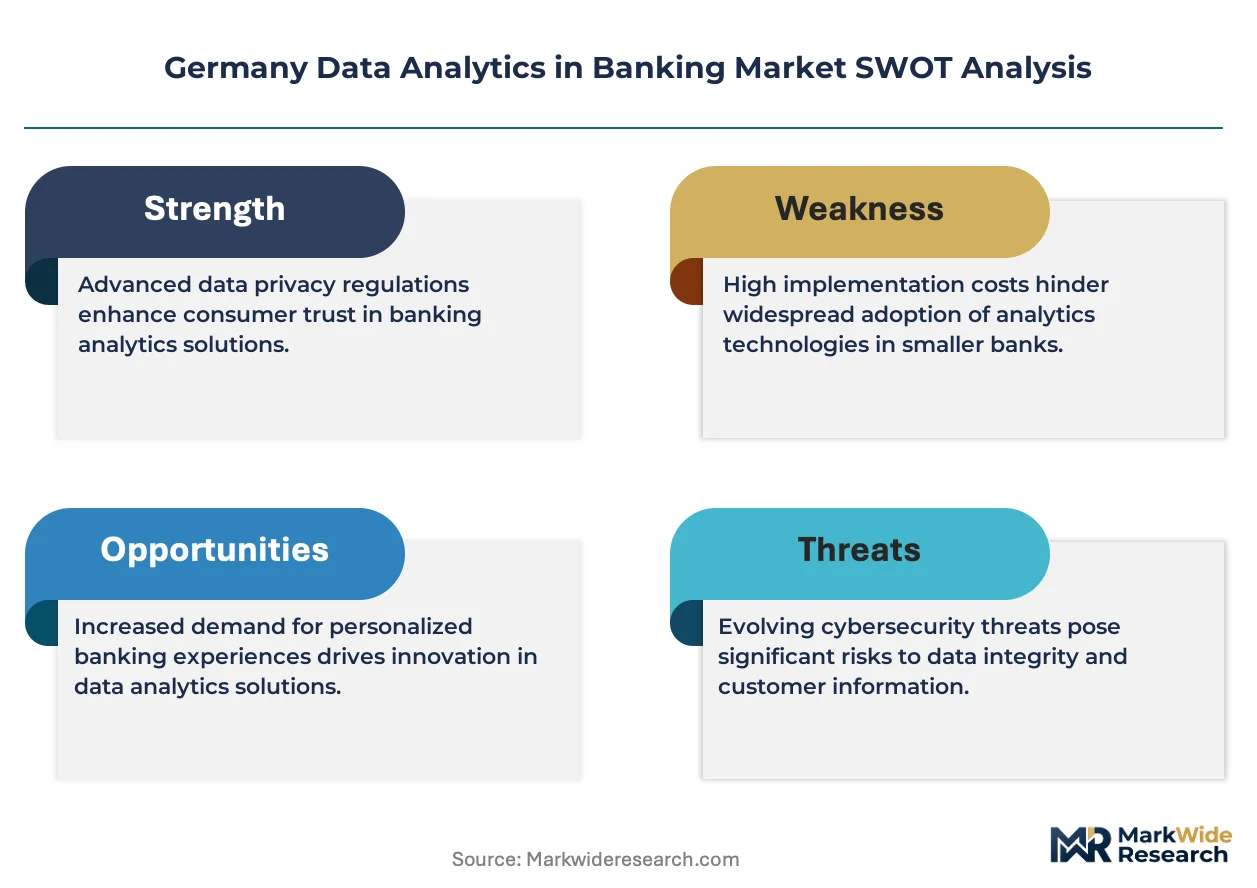
This market operates as a supply-constrained environment where explainable AI engineering capacity bottlenecks prop pricing power for certified vendors. Procurement centralization through cooperative banking associations is compressing vendor selection cycles and elevating compliance architecture as the primary competitive moat.
For Market Incumbents: Acquire specialized explainable AI engineering teams in Berlin and Munich to defend against cloud-native challengers. Consolidate platform positions through backward integration into data fabric architecture, capturing the unifying infrastructure layer that Sparkassen networks are piloting fastest. Deepen regulatory compliance module investments to exploit BaFin's algorithmic transparency mandates as a barrier to non-certified entrants.
For New Entrants and Emerging Players: Capture white-space opportunities in privacy-preserving analytics architectures for cross-institutional data collaboration under GDPR constraints. Target Bavaria's neobank density with cloud-native risk engines optimized for alternative credit scoring from transaction histories. Penetrate through API-first deployment models that bypass legacy core banking integration burdens.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists possessing BaFin-aligned documentation capabilities given the EU AI Act's high-risk system classification timeline. Long-term viability over a 5-10 year window favors vendors with outcome-based pricing traction and cooperative banking network penetration. Monitor the European Banking Authority's forthcoming AI governance technical standards as the critical inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies siloed transaction records and risk models into queryable data fabric layers accessible to Sparkassen networks. |
| Acquisition of Specialist Firm | Captures scarce explainable AI engineering capacity concentrated in Berlin and Munich research parks. |
| Strategic Partnership | Aligns vendor roadmaps with DZ Bank procurement centralization for cooperative banking network scale. |
| Product Launch | Deploys sub-100-millisecond real-time decisioning infrastructure for dynamic credit limits in Munich's digital banking cluster. |
| Geographic Expansion | Establishes EU-sovereign cloud regions satisfying Bundesbank data sovereignty requirements for core risk systems. |
Research Methodology
Multi-period observation of BaFin regulatory circulars, vendor procurement patterns, and cooperative banking IT centralization trends anchored the trend analysis, supplemented by interviews with chief technology officers at Landesbanken, data platform engineers at Sparkassen regional associations, compliance officers at neobanks, and procurement leads at DZ Bank. Secondary validation drew from BaFin MaRisk circulars, EU AI Act implementation guidance, European Banking Authority consultation papers, and Bundesbank supervisory reports. Bottom-up triangulation across fintech deployment velocities and top-down assessment of regulatory capital calculation requirements converged on segment-level demand estimates.
An input-output matrix mapped technology adoption curves against BaFin supervision intensity and core banking legacy constraints across the projection horizon. Segmentation dimensions modeled encompassed deployment model, institution size tier, regulatory exposure level, and regional banking cluster density. CAGRs were derived from slope analysis of technology substitution rates and procurement cycle compression patterns. Industry-specific forecast inputs incorporated Basel IV capital calculation timelines and EBA technical standards development trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EBA AI governance standard finalization and hyperscaler EU-sovereign cloud certification timelines. Forecasts reflect documented assumptions on regulatory implementation pace and cooperative banking consolidation continuity. A small set of triggers—EBA technical standards publication, major Sparkassen network platform consolidation decisions, and export restriction evolution on AI accelerators—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Automated Teller Machine (ATM) Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Cybersecurity in Banking Market
Banking
Global Neobanking Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Video Banking Service Market
Banking
Russia Data Analytics in Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Banking Wearable Market
Banking
Germany Banking As a Service Market
Banking
Blockchain in Banking Market
Banking
Investment Banking and Trading Services Market
Banking
Open Banking Market
Banking
Commercial Banking Market
Banking
Data Analytics in Banking Market
Banking
US Investment Banking Market