
 Spain Data Analytics in Banking Market | 2026-2036
Spain Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Analytics in Banking Market Insights
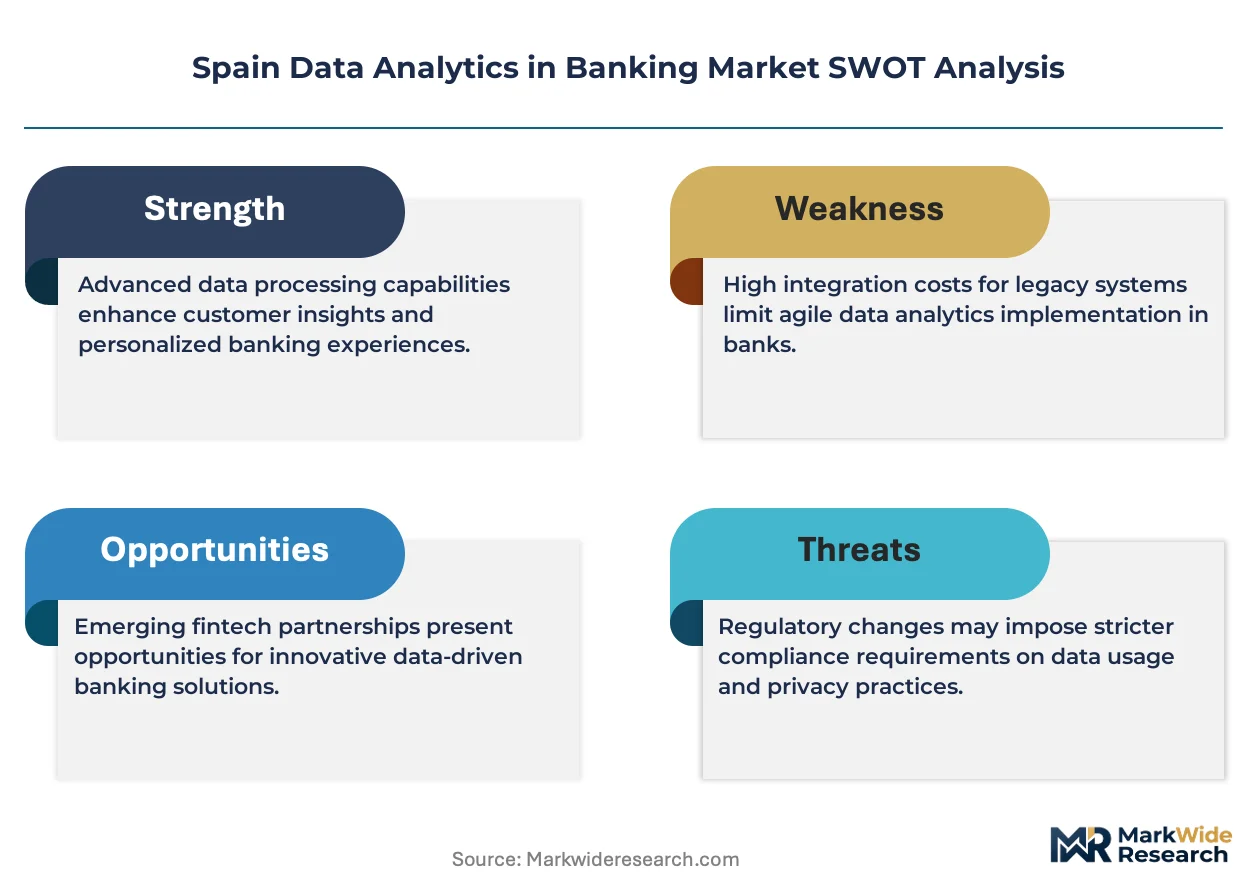
Subscription-based access to real-time fraud scoring APIs is expanding the addressable base beyond tier-one institutions. Banco Santander leverages its proprietary data infrastructure to sustain cross-border analytics standardization across European subsidiaries. BBVA anchors its competitive stance through specialized prescriptive analytics for SME lending portfolios. CaixaBank differentiates via embedded machine-learning modules within mobile banking channels.
Data analytics in banking encompasses the systematic extraction, processing, and statistical modeling of transactional, behavioral, and external datasets to generate actionable intelligence for credit decisions, operational optimization, and regulatory compliance. Core technical architectures integrate distributed computing frameworks with sub-second latency requirements for real-time payment screening. Predictive analytics commands the largest revenue share as Spanish institutions prioritize default probability modeling under Basel III frameworks. Cloud-based deployment exhibits the steepest growth trajectory, driven by elastic compute needs for stress-testing simulations and regulatory reporting. Fraud detection applications retain entrenched budget allocation, though marketing analytics is gaining share as neobanks weaponize granular customer segmentation.
The Bank of Spain enforces stringent data governance protocols under PSD2 open-banking mandates, compelling institutions to maintain audit trails for algorithmic credit decisions. The Spanish Data Protection Agency applies GDPR-derived accountability standards to customer profiling engines, shaping vendor selection toward privacy-preserving architectures. The National Securities Market Commission extends MiFID II suitability requirements into digital advisory channels, tightening analytics validation protocols. Stakeholders must weigh sovereign cloud mandates against the interoperability demands of pan-European banking unions.
Market Dynamics
The transposition of the EU AI Act into Spanish banking supervision is compressing procurement cycles for explainable analytics platforms, forcing institutions to replace black-box models with auditable decision systems before enforcement deadlines.
Growth Catalysts
- Basel III default probability mandates:Spanish retail banks are expanding predictive analytics budgets to meet capital adequacy requirements for forward-looking credit risk assessment.
- Madrid financial district clustering:Geographic concentration of data science operations in the capital creates network effects and accelerates talent acquisition for analytics vendors.
- PSD2 open-banking infrastructure:Standardized data sharing protocols under the EU directive are expanding the addressable dataset for fraud detection algorithms.
Market Restraints
- Sovereign cloud mandates:Spain's data localization preferences under national security frameworks limit vendor options and inflate infrastructure costs for cross-border analytics standardization.
- GDPR-derived accountability standards:The Spanish Data Protection Agency's algorithmic audit requirements extend deployment timelines and increase compliance overhead for customer profiling engines.
- Legacy core banking integration:Mainframe architectures at established institutions resist API-based analytics insertion, forcing expensive middleware development.
Strategic Opportunities
- Catalonia and Basque Country SME corridors:Regional banking subsidiaries outside Madrid show underpenetrated prescriptive analytics adoption for small-business lending portfolios.
- Real-time payment screening convergence:The intersection of distributed computing frameworks with sub-second latency requirements is opening new vendor categories for elastic fraud detection infrastructure.
- MiFID II digital advisory extension:The National Securities Market Commission's suitability validation protocols are creating procurement pull for analytics platforms with embedded compliance documentation.
Industry Challenges
- Quantitative risk modeler scarcity:Spanish universities produce insufficient graduates combining statistical modeling expertise with banking domain knowledge, inflating compensation for hybrid profiles.
- Algorithmic decision audit trail engineering:Institutions must reconstruct technical documentation for legacy credit scoring systems to satisfy the Bank of Spain's governance protocols.
- Cross-border data governance fragmentation:Pan-European banking unions face interoperability friction when Spanish sovereign cloud requirements conflict with subsidiary analytics standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Analytics in Banking Market |
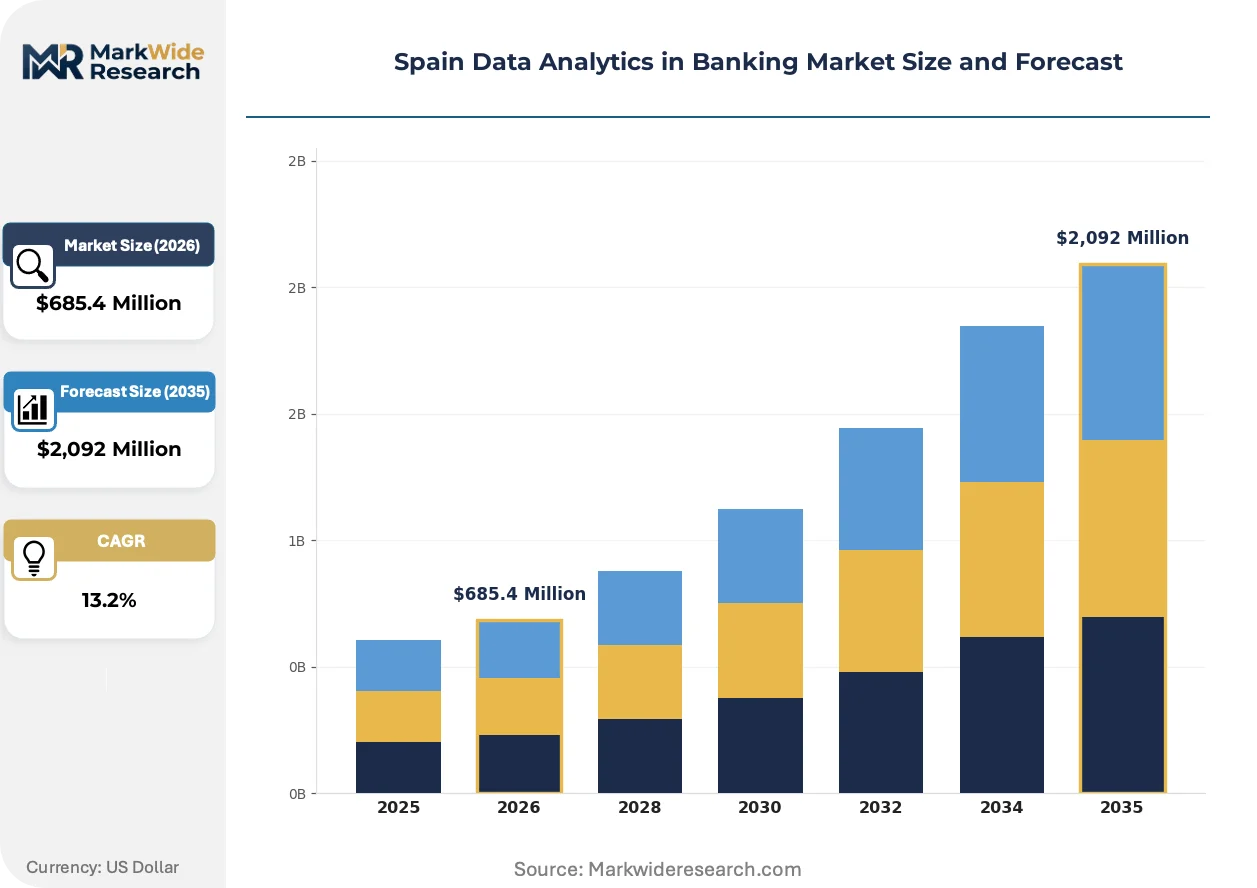
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,092 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Fraud Detection, Customer Segmentation, Risk Analysis, Marketing Analytics Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Customer Type: Retail Banks, Investment Firms, Credit Unions, Insurance Companies Analytics Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Text Analytics |
| Companies Covered | Banco Santander, BBVA, CaixaBank, ING Spain, Banco Sabadell, Openbank, Bankinter, Revolut, N26, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Analytics in Banking Market Trends and Innovations
Federated learning architectures and explainable AI modules are displacing centralized model training, while regulatory pressure accelerates the shift from descriptive to prescriptive analytics across Spanish retail and commercial banking segments.
Differential privacy techniques are converging with customer behavioral datasets to enable granular segmentation without individual re-identification risk. Neobanks and digital-first subsidiaries are adopting these methods fastest, lapping incumbent deployment cycles by twelve to eighteen months. The structural result is compressing competitive advantage for institutions with proprietary data moats alone.
The EU AI Act's risk-based classification system is forcing Spanish institutions to reclassify credit scoring algorithms as high-risk applications. This designation triggers mandatory human oversight interfaces and conformity assessment procedures. Medium-sized regional banks with limited compliance infrastructure face the steepest adaptation costs.
Subscription-based API access to fraud scoring engines is displacing perpetual license models for tier-two and tier-three institutions. Channel partners and core banking vendors are bundling these analytics as embedded modules rather than standalone procurement. This pattern concentrates in Barcelona and Valencia, where mid-market banks dominate the competitive landscape.
Spain Data Analytics in Banking Market Segmentation
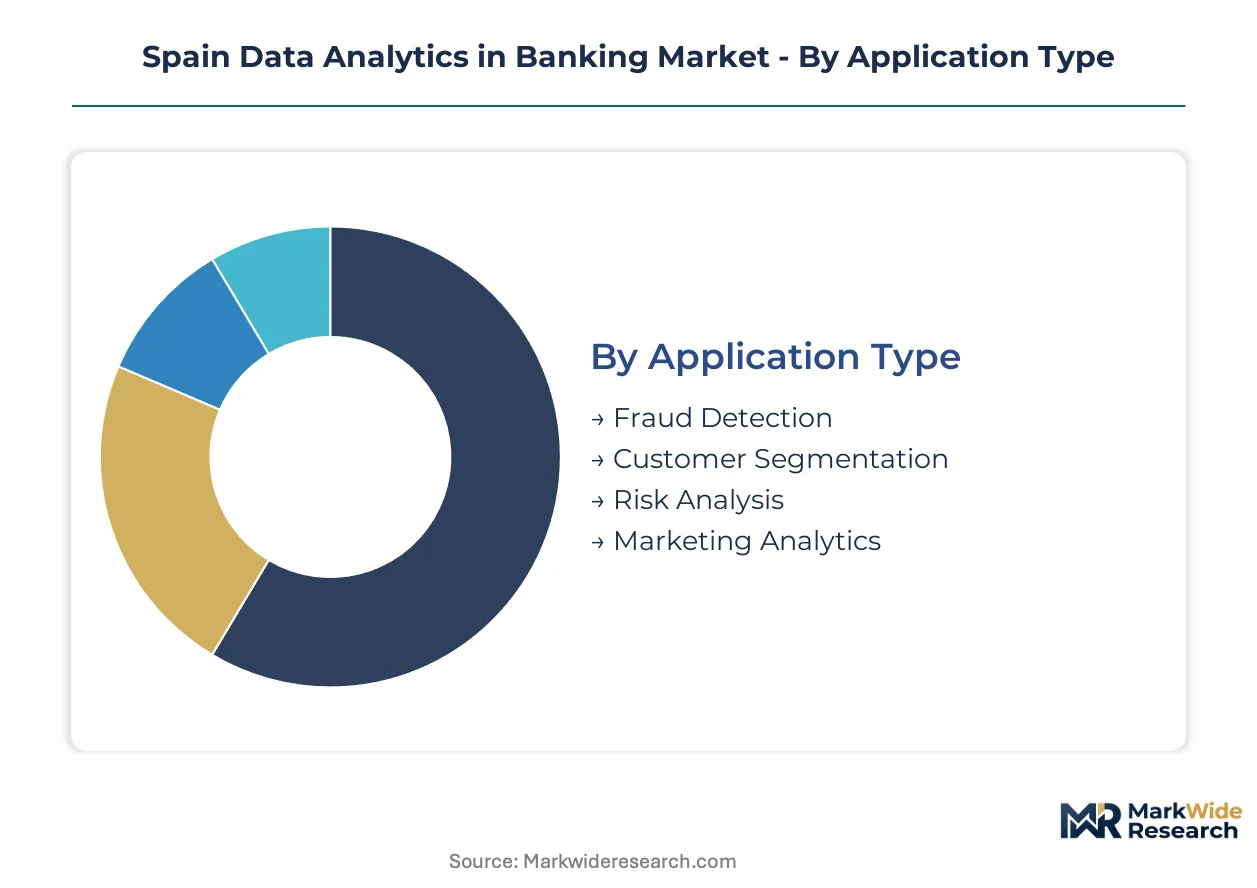
Spanish banking institutions deploy analytics across divergent technical and commercial dimensions, with procurement patterns shaped by regulatory mandates, infrastructure legacy, and competitive positioning. Understanding segment boundaries clarifies where vendor solutions concentrate and where white-space opportunities persist.
Application Type:
Supply concentration in fraud detection infrastructure dominates vendor revenue, though emerging use cases are redistributing development resources across the application stack.
- Fraud Detection:Real-time transaction screening engines process payment flows through distributed computing architectures with sub-second latency requirements. Madrid-based retail banks allocate entrenched budgets here under PSD2 open-banking mandates that expand the addressable dataset for algorithmic anomaly detection.
- Risk Analysis:Default probability modeling consumes the largest predictive analytics expenditure as institutions comply with Basel III capital adequacy frameworks for forward-looking credit assessment. The Bank of Spain's governance protocols compel audit trails for algorithmic decisions, shaping procurement toward explainable platforms.
- Customer Segmentation:Granular behavioral clustering enables neobanks to weaponize personalization against incumbent deposit bases.
- Marketing Analytics:Campaign attribution engines gain share as digital channels displace branch-centric acquisition strategies.
Today's leader: Fraud Detection. Tomorrow's challenger: Marketing Analytics.
Deployment Model:
Cost tier differentiation separates elastic cloud consumption from capital-intensive on-premise installations, with hybrid architectures emerging as the compromise pathway for regulated institutions.
- Cloud-Based:Elastic compute provisioning supports stress-testing simulations and regulatory reporting with variable cost structures. Spain's sovereign cloud preferences under national security frameworks limit vendor options and inflate infrastructure costs for cross-border analytics standardization.
- Hybrid:Split architectures maintain sensitive data on-premise while bursting analytical workloads to external infrastructure. Regional banks in Barcelona and Valencia favor this model to balance GDPR-derived accountability standards against scalability demands.
- On-Premise:Legacy mainframe environments at established institutions resist API-based insertion, forcing expensive middleware development.
- Edge Computing:Latency-sensitive inference at branch or ATM locations remains nascent outside pilot deployments.
Today's leader: Hybrid. Tomorrow's challenger: Cloud-Based.
Customer Type:
Volume concentration in retail banking masks margin differentiation across institutional categories, with investment firms commanding premium pricing for specialized risk infrastructure.
- Retail Banks:Deposit-taking institutions generate the largest absolute demand for analytics platforms, with Banco Santander and BBVA driving standardization across European subsidiaries. Geographic clustering of data science operations in Madrid's financial district creates network effects for vendor sales cycles.
- Investment Firms:Asset managers and broker-dealers require MiFID II-compliant suitability validation with embedded compliance documentation, tightening analytics validation protocols beyond retail requirements.
- Credit Unions:Cooperative structures show underpenetrated adoption in Catalonia and Basque Country SME corridors.
- Insurance Companies:Bancassurance integrations create procurement overlap with banking analytics vendors.
Today's leader: Retail Banks. Tomorrow's challenger: Investment Firms.
Analytics Type:
Maturity gradients separate established descriptive capabilities from emerging prescriptive architectures, with the EU AI Act compressing procurement cycles for explainable systems.
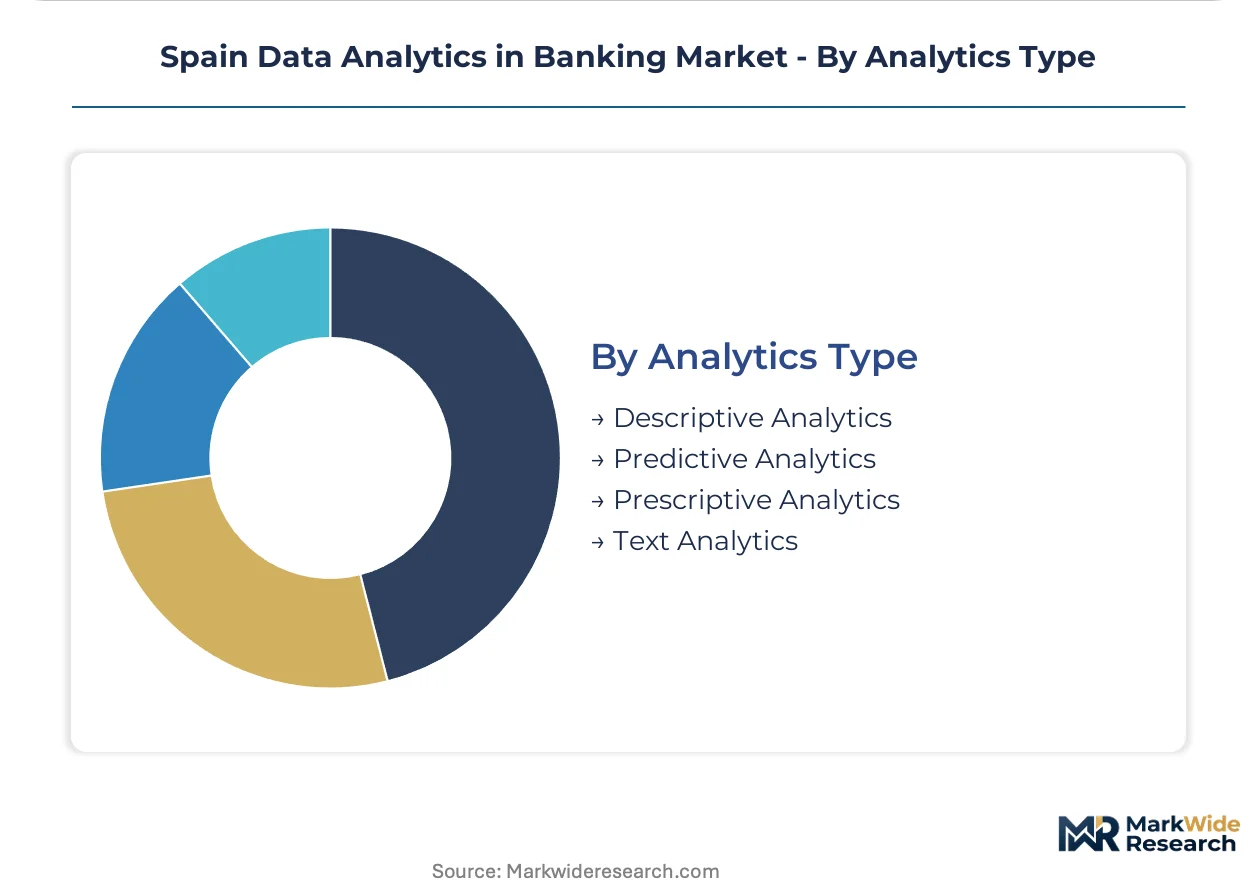
- Predictive Analytics:Statistical modeling of future outcomes commands the largest revenue share as Spanish institutions prioritize default probability modeling under Basel III frameworks. The Spanish Data Protection Agency's algorithmic audit requirements extend deployment timelines and increase compliance overhead for customer profiling engines.
- Prescriptive Analytics:Optimization engines recommending specific actions anchor BBVA's competitive stance through specialized deployment for SME lending portfolios. Federated learning architectures are displacing centralized model training in this category.
- Descriptive Analytics:Historical reporting and dashboarding retains baseline budget allocation but loses share to forward-looking capabilities.
- Text Analytics:Natural language processing of unstructured documents accelerates in regulatory reporting and customer service automation.
Today's leader: Predictive Analytics. Tomorrow's challenger: Prescriptive Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment patterns as Spanish institutions weigh sovereign cloud mandates against pan-European standardization imperatives. Madrid's financial district concentrates procurement authority, while regional banking subsidiaries outside the capital face steeper compliance cost burdens.
Madrid
Banco Santander and BBVA anchor data science operations in the capital's financial district, creating network effects for vendor sales cycles. The Bank of Spain's governance protocols under PSD2 open-banking mandates compel institutions to maintain audit trails for algorithmic credit decisions. Madrid's clustering of predictive analytics talent accelerates procurement timelines for explainable AI platforms ahead of EU AI Act enforcement deadlines.
Catalonia
Regional banking subsidiaries in Barcelona show underpenetrated prescriptive analytics adoption for SME lending portfolios. The Spanish Data Protection Agency applies GDPR-derived accountability standards to customer profiling engines, shaping vendor selection toward privacy-preserving architectures. Barcelona and Valencia host mid-market banks where subscription-based API access to fraud scoring engines displaces perpetual license models.
Basque Country
Cooperative credit structures in Bilbao and San Sebastián exhibit lagging deployment of specialized analytics for small-business lending. Spain's transposition of the EU AI Act into national banking supervision compresses procurement cycles for explainable platforms at regional institutions with limited compliance infrastructure. The Basque SME corridor presents white-space opportunities for prescriptive analytics vendors targeting underpenetrated portfolios.
Andalusia
Seville and Málaga host emerging fintech clusters where neobanks weaponize granular customer segmentation against incumbent deposit bases. The National Securities Market Commission extends MiFID II suitability requirements into digital advisory channels, tightening analytics validation protocols for emerging players. Federated learning architectures gain traction among digital-first subsidiaries seeking to compress deployment cycles.
Valencia
Mid-market banks in Valencia favor hybrid deployment architectures to balance GDPR accountability standards against scalability demands. Channel partners and core banking vendors bundle analytics as embedded modules rather than standalone procurement. The city's positioning between Madrid's regulatory gravity and Barcelona's tech ecosystem creates distinctive vendor access patterns.
Spain Data Analytics in Banking Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one institutions consolidating procurement around proprietary infrastructure while mid-market players fragment across subscription-based API providers. The vendor base organizes around three strategic archetypes: universal banks with captive analytics capabilities, pure-play fintech disruptors, and technology vendors supplying modular platforms. M&A activity concentrates on explainable AI capabilities ahead of regulatory deadlines, while capacity expansion focuses on elastic cloud infrastructure for stress-testing simulations.
Among Spain-based universal banks, Banco Santander, BBVA, and CaixaBank occupy positions as anchors for competitive dynamics. Santander exemplifies the proprietary infrastructure archetype through cross-border analytics standardization across European subsidiaries. BBVA sits within the specialized deployment tier, anchoring competitive stance through prescriptive analytics for SME lending. CaixaBank represents the embedded-module approach, differentiating via machine-learning integration within mobile banking channels.
| Leading Market Players |
|---|
| Banco Santander |
| BBVA |
| CaixaBank |
| ING Spain |
| Banco Sabadell |
| Openbank |
| Bankinter |
| Revolut |
| N26 |
| Others |
Pricing and Supply Chain Analysis
Tier-two and tier-three Spanish retail banks concentrate procurement authority for analytics platforms, driving subscription-based API access to fraud scoring engines as the dominant pricing model across the mid-market segment.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for elastic compute provisioning, compressing margins for on-premise deployments. Three-tier pricing structure across premium, standard, and economy levels separates explainable AI platforms with embedded compliance documentation from black-box legacy systems. Cost compression in the standard tier is intensifying because channel partners bundle analytics as embedded modules rather than standalone procurement. Regional banks in Barcelona and Valencia exhibit highest price sensitivity, while Madrid-based tier-one institutions prioritize audit-trail capabilities over unit cost.
Supply Chain Analysis
Specialized GPU and TPU hardware supply rests on Taiwanese semiconductor foundries and American chip designers, with European cloud infrastructure providers serving as intermediaries for Spanish deployment. Raw material dependencies span advanced silicon wafers, high-bandwidth memory modules, and specialized networking equipment for distributed computing frameworks. Single-source vulnerability concentrates in EU sovereign cloud providers eligible under Spain's data localization preferences. Distribution runs through core banking vendors and systems integrators with established relationships at Banco Santander, BBVA, and CaixaBank.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Spanish institutions shift procurement toward explainable analytics platforms with embedded EU AI Act compliance documentation, elevating premium specifications over cost-minimized alternatives.
For Market Incumbents: Deploy federated learning architectures to defend proprietary data moats against neobank competitors weaponizing differential privacy techniques. Consolidate around cross-border analytics standardization capabilities to neutralize the threat of pan-European banking unions fragmenting procurement authority. Prioritize human oversight interface development ahead of enforcement deadlines for high-risk algorithm classification. For New Entrants and Emerging Players: API-first distribution partnerships with core banking vendors unlock the fastest route to scale within tier-two institutions in Barcelona and Valencia. White-space concentrates in prescriptive analytics for SME lending portfolios across Catalonia and Basque Country cooperative structures. Target compliance documentation automation as the most penetrable feature gap at regional banks with limited infrastructure. For Investors and Strategic Acquirers: Universal banks with captive analytics capabilities are the most active acquirer in this space, seeking explainable AI specialists to internalize before regulatory deadlines compress. Long-term viability favors vendors with privacy-preserving architectures and elastic cloud infrastructure for stress-testing simulations. Watch the EU AI Act transposition timeline as the critical inflection signal for accelerated procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Platform Development | Addresses EU AI Act high-risk classification mandates for credit scoring algorithms. |
| Federated Learning Architecture Deployment | Enables cross-border analytics standardization without centralized data pooling. |
| API-First Distribution Partnership | Accelerates penetration of tier-two and tier-three institutions through embedded modules. |
| Human Oversight Interface Investment | Satisfies Bank of Spain governance protocols for algorithmic decision audit trails. |
| Privacy-Preserving Technology Acquisition | Aligns vendor capabilities with Spanish Data Protection Agency accountability standards. |
Research Methodology
Coverage spans Madrid's financial district, Barcelona and Valencia mid-market banking clusters, and Basque Country cooperative structures, with primary inputs from each. Chief data officers, risk analytics directors, regulatory compliance leads, and procurement managers at Banco Santander, BBVA, CaixaBank, and regional institutions provided structured interviews. Secondary validation drew from Bank of Spain supervisory reports, Spanish Data Protection Agency guidance documents, EU AI Act implementation texts, and National Securities Market Commission circulars. Bottom-up vendor revenue triangulation against top-down banking IT expenditure estimates anchored market sizing.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include application type, deployment model, customer tier, and analytics maturity level, with regulatory compliance tier as a banking-specific overlay. CAGRs derive from elasticity-adjusted adoption curves for explainable platforms and stress-testing compute demand. Forecast inputs incorporate Basel III capital adequacy implementation timelines and PSD2 open-banking data availability expansion.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures would alter the outlook. Forecasts reflect assumptions around EU AI Act enforcement sequencing and sovereign cloud eligibility criteria. Regulatory delay, talent scarcity in quantitative risk modeling, or cross-border data governance fragmentation could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
North America Machine Learning in Banking Market
Banking
Payment Bank Solutions Market
Banking
Latin America Neo Banking Services Market
Banking
Predictive Analytics in Banking Market
Banking
China Retail Banking System Market
Banking
UK Banking as a Service Market
Banking
Global AI in Banking Market
Banking
Smart ATM Market
Banking
Global Neo and Challenger Bank Market
Banking
Global Chatbot for Banking Market
Banking
Open Banking Market
Banking
Credit Intermediation Market
Banking
Latin America Data Analytics in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
APAC Banking-As-A-Service Market
Banking
Banking Tax Management Software Market