
 Asia-Pacific Data Analytics in Banking Market | 2026-2036
Asia-Pacific Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Analytics in Banking Market Analytics
Singapore's fintech corridor is rewriting how banks deploy predictive analytics across ASEAN trade corridors. IBM leverages its Watson platform to anchor enterprise-grade fraud detection for tier-one lenders across Southeast Asia. Microsoft sustains cloud-native analytics infrastructure that competes directly with Oracle Corporation's on-premises banking installations in Tokyo and Sydney.
Data analytics in banking encompasses the systematic extraction, processing, and modeling of structured and unstructured financial data to generate actionable intelligence for credit decisions, operational optimization, and regulatory compliance. Machine learning algorithms process transaction velocities exceeding ten thousand per second to flag anomalous patterns in real-time payment networks. Cloud-based deployment architectures now dominate new installations, while artificial intelligence applications within risk management command the deepest margin pools due to Basel III compliance complexity. Fintech companies represent the fastest-growing end-user category as neobanks bypass legacy core systems entirely.
India's RBI mandates granular data localization standards that reshape how foreign vendors architect banking platforms for the subcontinent. Australia's Consumer Data Right, enforced by the ACCC, compels incumbent banks to share transaction histories with accredited fintech competitors, accelerating third-party analytics demand. China's SAMR and PBOC impose algorithmic governance rules on credit scoring models. Stakeholders must weigh sovereign data requirements against cloud economies of scale when selecting deployment architectures for multi-jurisdiction portfolios.
Market Dynamics
Real-time payment network modernization across Southeast Asian corridors is compressing decision windows for credit risk engines, forcing banks to rebuild core infrastructure around sub-100 millisecond latency requirements rather than batch-processing architectures.
Growth Catalysts
- India's RBI data localization mandates:Foreign cloud providers must establish domestic infrastructure, creating captive demand for localized analytics platforms that process transaction histories within national boundaries.
- Machine learning inference at network edge:Tier-one commercial banks deploy federated learning models that train on distributed device data without centralizing sensitive customer records.
- Australia's Consumer Data Right:ACCC enforcement compels incumbent banks to expose standardized APIs, accelerating third-party analytics demand from accredited fintech competitors.
Market Restraints
- Specialized talent scarcity:Quantitative risk modelers with Basel III compliance expertise command premium compensation that mid-tier banks struggle to match.
- Cross-border data friction:Divergent sovereignty requirements between Singapore, Australia, and India fragment cloud economies of scale for regional portfolios.
- Legacy core system entanglement:COBOL-based transaction engines in Tokyo and Sydney resist API-native analytics integration without multimillion-dollar middleware layers.
Strategic Opportunities
- Vietnam's underpenetrated neobank sector:Digital-first lenders bypass legacy infrastructure entirely, creating greenfield demand for cloud-native risk analytics stacks.
- Convergence of graph analytics and real-time payments:Relationship mapping across ASEAN trade corridors enables dynamic counterparty risk scoring for correspondent banking networks.
- China's algorithmic governance rules:SAMR and PBOC credit scoring transparency requirements create advisory service demand for model documentation and bias auditing.
Industry Challenges
- Model risk management talent gaps:Banks lack sufficient validation engineers to independently audit machine learning credit decisions for regulatory defensibility.
- Hybrid cloud orchestration complexity:Workload portability between on-premise Tokyo data centers and Sydney hyperscale regions demands specialized platform engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Analytics in Banking Market |
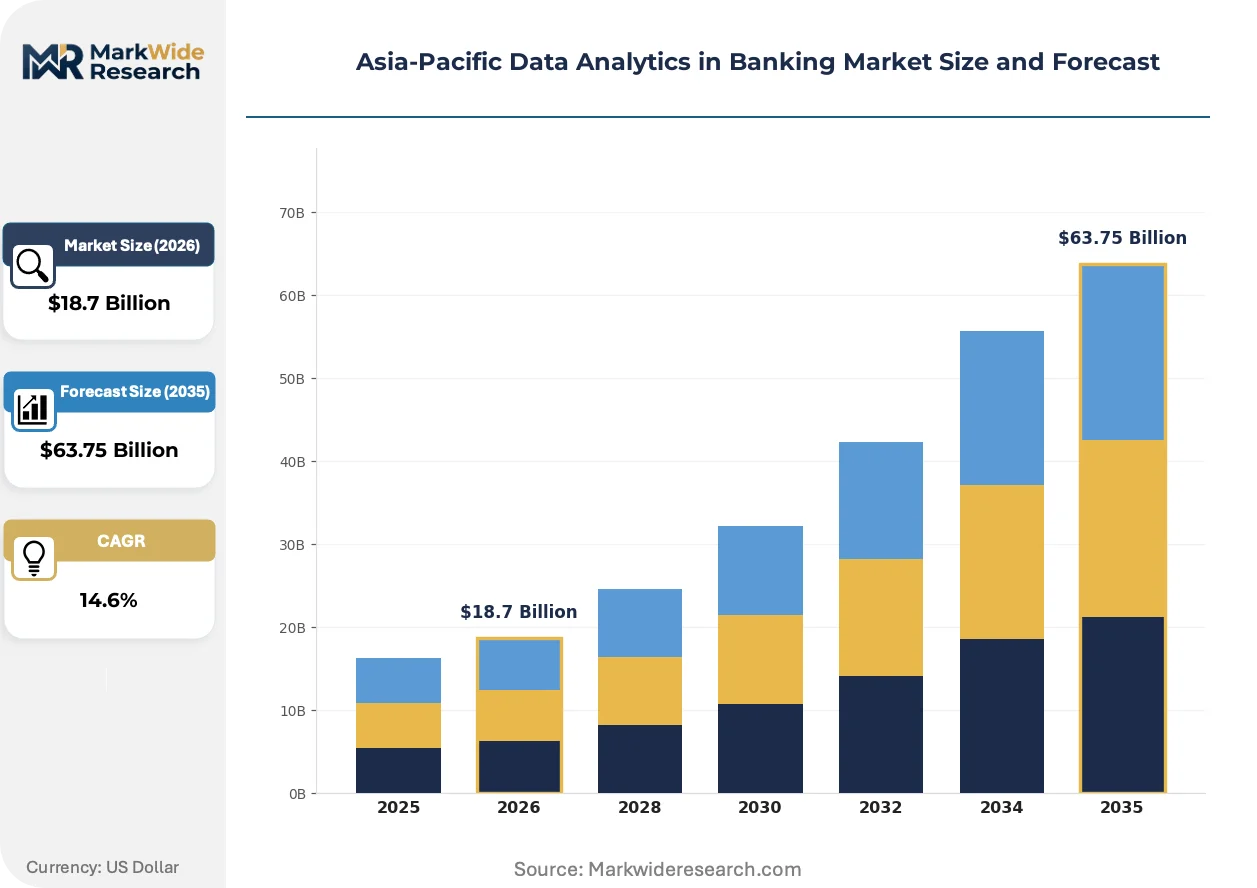
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Segmentation, Predictive Analytics End User: Commercial Banks, Investment Banks, Credit Unions, Fintech Companies Technology: Artificial Intelligence, Machine Learning, Big Data, Cloud Computing Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | IBM, Microsoft, Google, SAP SE, Oracle Corporation, DBS Bank, HSBC, Standard Chartered, Baidu, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Analytics in Banking Market Evolving Landscape
Analytics deployment architectures across Asia-Pacific banking are pivoting from centralized data lakes toward federated computation models that preserve jurisdictional boundaries while enabling cross-border risk visibility.
Real-time feature engineering pipelines are migrating from batch overnight processing to continuous stream computation. Tier-one lenders in Singapore and Hong Kong now ingest transaction velocities exceeding ten thousand per second for instant credit decisioning. This compression is migrating from proof-of-concept sandboxes into production payment networks, collapsing the latency gap between data generation and actionable risk signals.
China's SAMR algorithmic governance framework now mandates explainability documentation for credit scoring models deployed by licensed financial institutions. The industrial consequence is a structural shift toward simpler, interpretable model architectures that sacrifice marginal predictive power for regulatory auditability. Domestic banks and joint-venture fintechs are responding by embedding model risk management functions earlier in product development cycles.
Neobank procurement patterns favor modular, API-first analytics vendors over integrated enterprise suites. Australia's Consumer Data Right accelerates this unbundling as accredited data recipients demand granular, best-of-breed components for specific use cases. This fragmentation is most visible in Sydney's fintech corridor, where specialist providers for fraud detection, credit scoring, and customer lifetime value prediction operate as interchangeable infrastructure layers.
Asia-Pacific Data Analytics in Banking Market Segmentation
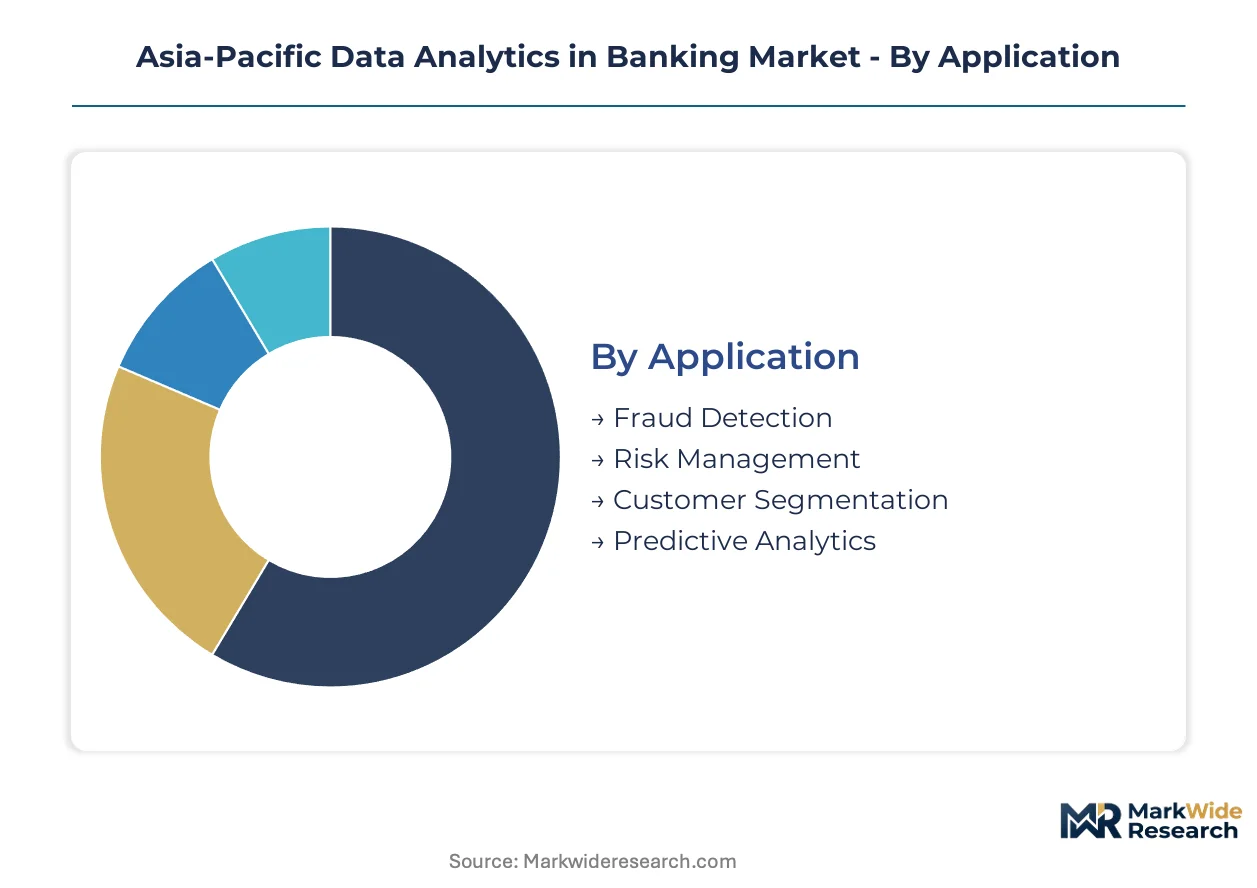
Segmentation reveals how banking institutions across Asia-Pacific prioritize analytics investments by operational priority, infrastructure maturity, and regulatory exposure. Each dimension carries distinct procurement patterns and vendor selection criteria that reshape competitive dynamics.
Application:
After-sales service intensity varies sharply across use cases, with fraud detection demanding 24/7 model retraining support while customer segmentation operates on quarterly refresh cycles.
- Fraud Detection:Real-time transaction monitoring systems process velocities exceeding ten thousand per second across Singapore's payment networks. Demand concentrates in ASEAN trade corridors where cross-border correspondent banking amplifies synthetic identity exposure.
- Risk Management:Credit decisioning engines integrate Basel III capital adequacy calculations with machine learning probability of default estimates. Australia's major banks deploy these systems for mortgage portfolio stress testing under APRA supervision.
- Customer Segmentation:Behavioral clustering models identify micro-segments for personalized product recommendations.
- Predictive Analytics:Forecasting tools project cash flow patterns and churn propensity for relationship managers.
Fraud detection holds the largest share; momentum sits with risk management as Basel III implementation deadlines approach.
End User:
Cost tier stratification separates enterprise-grade deployments from modular cloud subscriptions, with annual analytics spend ranging across three orders of magnitude between tier-one commercial banks and emerging neobanks.
- Commercial Banks:Full-stack analytics platforms integrate core banking systems with regulatory reporting infrastructure. Tokyo and Sydney institutions dominate procurement volume for on-premise installations.
- Fintech Companies:API-native vendors supply point solutions for credit scoring and fraud detection without legacy middleware. These firms expand most quickly across Vietnam's underpenetrated digital lending market.
- Investment Banks:Trading desk analytics require sub-millisecond latency for algorithmic execution strategies.
- Credit Unions:Smaller institutions favor managed service arrangements over captive data science teams.
Commercial banks hold the largest share; momentum sits with fintech companies as neobank licensing accelerates across Southeast Asia.
Technology:
Volume concentration favors machine learning inference workloads, which consume disproportionate compute resources compared to traditional business intelligence reporting.
- Machine Learning:Supervised and unsupervised algorithms train on historical transaction patterns for anomaly detection. Federated learning architectures gain traction in India to satisfy RBI data localization without centralizing sensitive records.
- Artificial Intelligence:Natural language processing extracts sentiment from customer service interactions and regulatory filings. China's SAMR mandates explainability documentation for AI credit decisions, favoring simpler model architectures.
- Big Data:Distributed storage and processing frameworks handle petabyte-scale transaction histories.
- Cloud Computing:Hyperscale infrastructure enables elastic capacity for seasonal credit demand spikes.
Machine learning holds the largest share; artificial intelligence gains share fastest as generative models enter customer service automation.
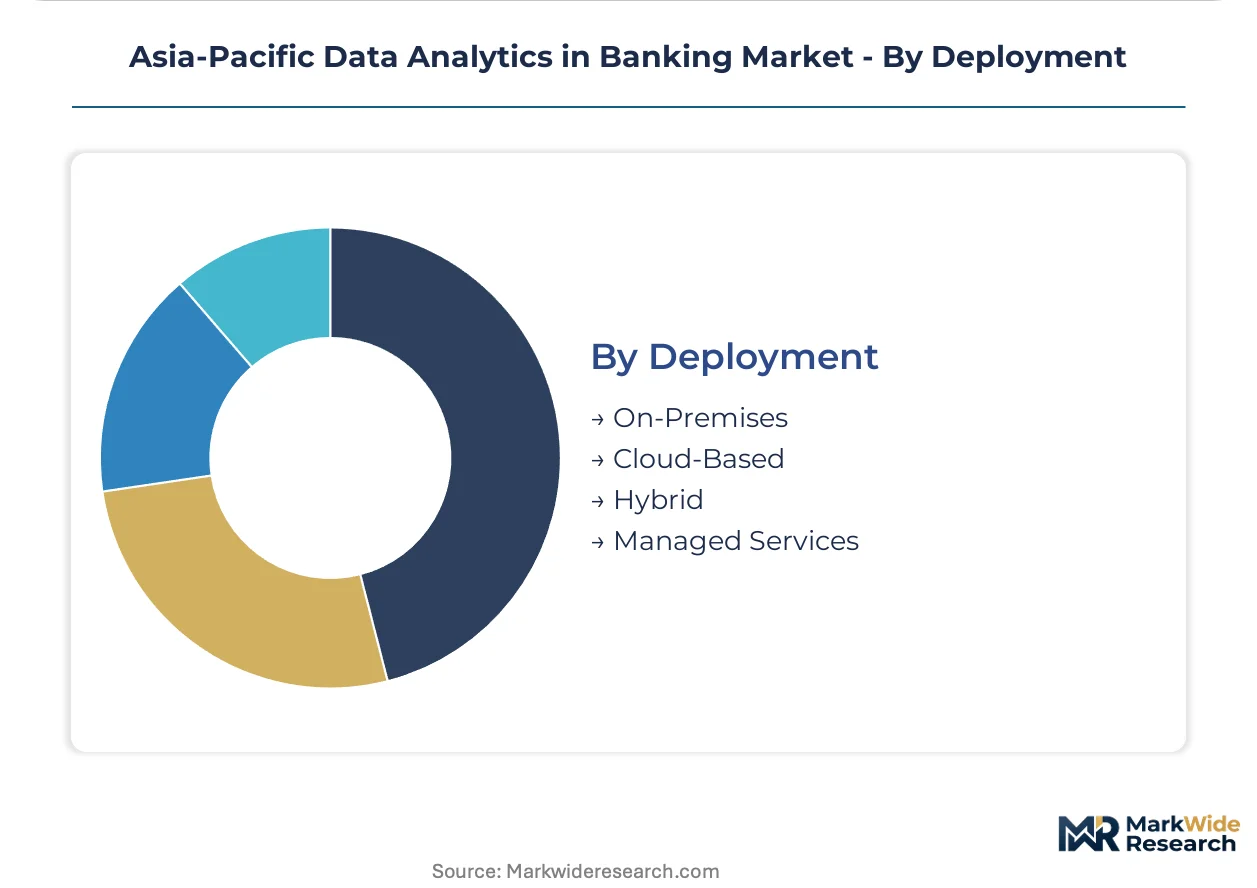
Deployment:
Margin structure diverges sharply, with managed services commanding recurring revenue premiums while on-premise installations carry heavy upfront professional services dependency.
- Cloud-Based:Scalable infrastructure eliminates capital expenditure for hardware refresh cycles. Singapore's fintech corridor favors this model for rapid product iteration without data center construction delays.
- Hybrid:Sensitive risk data remains on-premise while customer-facing analytics leverage public cloud elasticity. Australia's Consumer Data Right compliance drives this architecture for data sharing with accredited recipients.
- On-Premises:Legacy core system entanglement in Tokyo and Sydney preserves installed base despite higher total cost of ownership.
- Managed Services:Third-party operations of analytics infrastructure reduce talent recruitment burdens for mid-tier institutions.
Cloud-based deployment holds the largest share; hybrid architectures gain share fastest as sovereignty requirements fragment regional cloud strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment clusters in financial centers where regulatory mandates intersect with fintech density. Singapore, Sydney, and Mumbai anchor procurement volume for real-time analytics platforms.
Singapore
ASEAN trade corridor concentration drives demand for cross-border fraud detection systems. The Monetary Authority of Singapore enforces technology risk management guidelines that mandate operational resilience for digital payment networks. The fintech corridor hosts tier-one bank innovation labs deploying sub-100 millisecond credit decisioning engines.
Australia
Open banking data sharing accelerates third-party analytics procurement from accredited fintech competitors. The Australian Competition and Consumer Commission enforces Consumer Data Right compliance deadlines that expose standardized transaction APIs. Sydney's fintech cluster specializes in modular fraud detection components for neobank integration.
India
Domestic data localization requirements reshape foreign vendor cloud architectures for the subcontinent. The Reserve Bank of India mandates granular storage standards that process transaction histories within national boundaries. Mumbai's financial district anchors captive infrastructure investments by hyperscale providers.
China
Algorithmic governance rules on credit scoring models create advisory demand for documentation and bias auditing. The State Administration for Market Regulation and People's Bank of China impose explainability requirements on licensed financial institutions. Shanghai's fintech zone concentrates model risk management specialists serving joint-venture banks.
Japan
Legacy core system entanglement in Tokyo preserves on-premise analytics installations despite higher ownership costs. The Financial Services Agency supervises Basel III implementation timelines that drive machine learning credit decisioning adoption. Tokyo's banking district maintains multimillion-dollar middleware layers connecting COBOL engines to API-native platforms.
Asia-Pacific Data Analytics in Banking Market Competitive Landscape
Hyperscale cloud providers and enterprise software incumbents split the market between infrastructure-as-a-service and integrated analytics suites. The vendor landscape exhibits tiered concentration: global technology conglomerates anchor enterprise contracts, while specialized fintech infrastructure vendors capture neobank segments. Three archetypes dominate: cloud-native platform operators, legacy enterprise software vendors with banking vertical expertise, and financial institutions developing proprietary analytics capabilities. Competitive intensity centers on strategic partnerships with tier-one commercial banks and regulatory compliance advisory services.
Among global technology conglomerates, IBM and Microsoft exemplify divergent architectural approaches for regional banking clients. IBM occupies a position representing enterprise-grade fraud detection platforms with established presence in Southeast Asian corridors. Microsoft anchors cloud-native infrastructure deployments competing directly with Oracle Corporation's installed base across Tokyo and Sydney banking centers. These three entities collectively represent the strategic tension between hybrid cloud orchestration and on-premise legacy preservation that defines procurement decisions.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| SAP SE |
| Oracle Corporation |
| DBS Bank |
| HSBC |
| Standard Chartered |
| Baidu |
| Others |
Value Network & Pricing Analysis
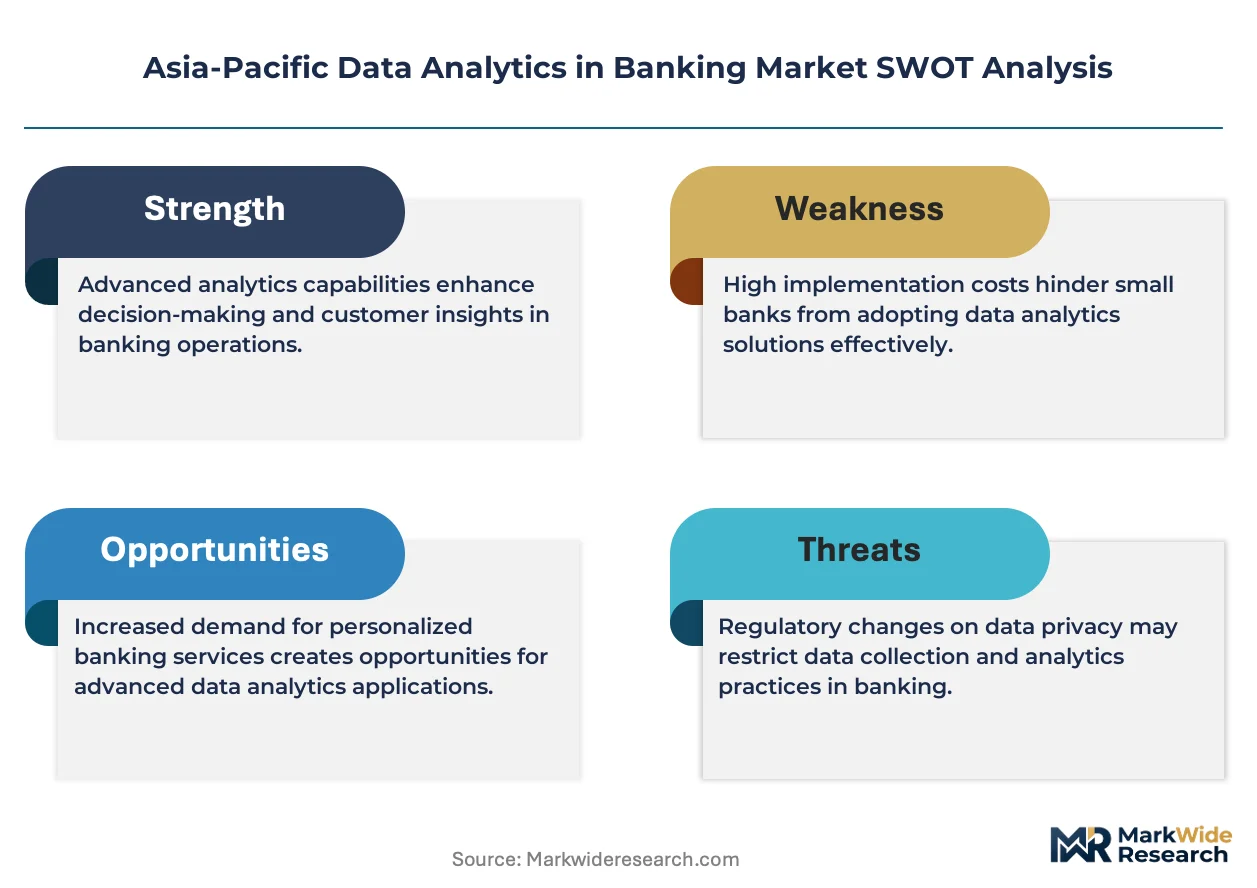
Undercapacity in India's domestic cloud infrastructure is driving hyperscale providers toward captive data center construction, simultaneously inflating professional services premiums and compressing SaaS margins as localization mandates reshape vendor economics across the subcontinent.
Pricing Analysis
RBI data localization mandates dictate the pricing tier structure across deployment models. Cloud-native subscriptions stratify across premium, standard, and economy tiers based on latency guarantees and sovereign data residency certification. Price differentiation hinges on API throughput volume and after-sales model retraining intensity. Pricing pressure stems from fintech procurement teams demanding modular point solutions over bundled enterprise suites. Neobanks exhibit highest price sensitivity; tier-one commercial banks absorb premium tiers for regulatory defensibility.
Supply Chain Analysis
Export controls on advanced GPU clusters and AI training silicon limit hardware flows into Chinese banking technology procurement channels. Supply concentrates in Taiwan for semiconductor fabrication, the United States for specialized AI accelerators, and Singapore for regional cloud infrastructure assembly. Raw material dependencies span high-bandwidth memory modules, liquid cooling systems, and sovereign-certified encryption hardware. Single-source vulnerability sits with NVIDIA's dominance in training-grade silicon. Distribution runs through hyperscale provider direct sales teams and systems integrator partnerships for legacy bank modernization projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among neobank procurement consortia across Southeast Asia, fragmenting demand into specialized vendor ecosystems that displace integrated enterprise suites.
For Market Incumbents: Harden API-native platform architectures against modular disintermediation by embedding compliance automation directly into core risk engines. Acquire specialized model risk management boutiques in Shanghai and Sydney to capture advisory revenue from SAMR and APRA documentation requirements. Defend against hyperscale encroachment through vertical integration into edge inference hardware for sub-100 millisecond latency guarantees. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated digital lending sector where legacy core entanglement is minimal and greenfield procurement favors API-first vendors. Target Australia's Consumer Data Right compliance tooling as accredited data recipients proliferate. Pursue partnerships with Singapore's MAS-licensed fintech sandboxes for rapid proof-of-concept validation before enterprise sales cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers operating hybrid cloud orchestration layers for mid-tier Japanese banks. Long-term viability favors vendors with captive infrastructure in India and model interpretability expertise for China's algorithmic governance enforcement. Monitor RBI enforcement intensity on data localization as the signal indicating capacity expansion timing for hyperscale providers.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Platform Launch | Enables RBI-compliant credit scoring without centralizing sensitive customer records across Indian portfolios. |
| Model Risk Management Acquisition | Captures advisory demand from SAMR explainability mandates affecting Shanghai joint-venture banks. |
| Edge Inference Infrastructure Partnership | Delivers sub-100 millisecond latency for Singapore's real-time payment network modernization. |
| Consumer Data Right Compliance Tooling | Addresses ACCC-mandated API standardization for Australia's accredited fintech recipients. |
| Hybrid Cloud Orchestration Service | Resolves workload portability between Tokyo on-premise data centers and Sydney hyperscale regions. |
Research Methodology
Operator-level perspectives from chief risk officers, model validation engineers, cloud procurement leads, and regulatory compliance heads anchored the qualitative base. Primary interviews combined with secondary validation against RBI circulars, MAS technology risk guidelines, ACCC Consumer Data Right determinations, and SAMR algorithmic governance notices. Bottom-up triangulation across deployment architecture costs and top-down reconciliation against aggregate banking IT expenditure estimates shaped the analytical foundation.
Scenario-bracketing framed the quantitative approach across the analysis window. Segmentation dimensions modeled encompass deployment model, end-user tier, application priority, and jurisdictional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating Basel III implementation timelines and neobank licensing velocity. Forecast inputs included real-time payment network transaction velocity growth and hyperscale provider capex allocation to sovereign cloud regions.
Stress conditions across RBI enforcement intensity, SAMR algorithmic governance expansion, and ASEAN cross-border payment integration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory deadline adherence and legacy system replacement rates. Material shifts in data sovereignty jurisprudence or GPU export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Performance Bank Guarantee Market
Banking
Southeast Asia Commercial Banking Market
Banking
Brazil Retail Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Canada Data Analytics in Banking Market
Banking
Global Neo and Challenger Bank Market
Banking
Europe Machine Learning in Banking Market
Banking
UK Banking as a Service Market
Banking
Digital Banking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Data Analytics in Banking Market
Banking
China Retail Banking System Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
US Investment Banking Market
Banking
Bank Management Software Market