
 Case and Box Handling Robots Market | 2026-2036
Case and Box Handling Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Case and Box Handling Robots Market Outlook
OSHA's updated machine guarding standards is recalibrating the cost-of-entry calculus for collaborative box handling installations in US warehouses. FANUC America leverages its Rochester Hills manufacturing base to sustain rapid domestic delivery cycles for articulated palletizing cells. ABB anchors European demand through its Västerås engineering center, which specializes in force-controlled packaging lines for food producers. KUKA competes in high-payload segments where automotive tier-one suppliers require repeatable case placement above fifty kilograms.
Case and box handling robots are programmable manipulators equipped with vacuum or mechanical end-effectors designed to lift, transfer, orient, and place rigid containers at throughputs exceeding twenty cycles per minute; these systems integrate with conveyor networks and warehouse management software to automate the movement of goods from production lines to shipping docks. Articulated robots dominate heavy-palletizing applications where six-axis flexibility accommodates mixed-SKU loads, while delta robots occupy high-speed sorting stations in pharmaceutical distribution centers requiring sub-millimeter placement accuracy. Vision guidance technology leads technology adoption as e-commerce warehouses deploy camera-guided pick-and-place systems to handle variable box dimensions without manual teach programming.
The EU Machinery Directive and ISO 10218 safety standards constrain collaborative robot deployments by mandating force-limiting verification and protective stop testing before operational certification. The US Food and Drug Administration's Current Good Manufacturing Practice regulations shape pharmaceutical end-user demand by requiring traceable material handling records and washdown-compatible robot designs. Stakeholders must monitor evolving cybersecurity frameworks for IoT-integrated warehouse fleets as connected palletizing networks expand attack surfaces beyond traditional factory perimeters.
Market Dynamics
E-commerce fulfillment centers are compressing robot deployment cycles as parcel volumes strain manual handling capacity, forcing warehouse operators to prioritize throughput-per-square-foot over capital recovery timelines.
Growth Catalysts
- EU Machinery Directive force-limiting mandates:Collaborative palletizing systems gain operational certification faster under harmonized safety standards, accelerating deployment timelines for human-robot workcells.
- Pharmaceutical cold-chain expansion:Temperature-controlled distribution centers deploy articulated robots to maintain product integrity during high-throughput case handling.
- Vision-guided pick-and-place:Camera-based box dimension recognition eliminates manual teach programming, reducing SKU changeover downtime in multi-tenant fulfillment facilities.
Market Restraints
- Servo motor and reducer supply concentration:Japanese and German precision component suppliers control critical motion control supply, creating lead time vulnerability for robot OEMs.
- ISO 10218 protective stop testing:Force-limiting verification protocols extend pre-operational certification timelines, delaying revenue recognition for system integrators.
- Conveyor-based fixed automation:Traditional material handling infrastructure in established distribution centers competes for capital allocation against flexible robotic cells.
Strategic Opportunities
- India PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive sectors drive greenfield warehouse automation investments in Pune and Chennai industrial corridors.
- 5G-enabled fleet coordination:Low-latency wireless connectivity converges with edge AI to enable synchronized multi-robot palletizing without wired network infrastructure.
- Secondary packaging for direct-to-consumer:Emerging demand for mixed-SKU case consolidation creates white space for delta robots in high-speed pharmaceutical distribution.
Industry Challenges
- Robot programming specialist scarcity:Shortage of technicians proficient in force-controlled collaborative applications limits deployment velocity for mid-sized logistics operators.
- Warehouse management system integration complexity:Legacy WMS platforms require custom middleware development to synchronize robot work orders with existing inventory databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case and Box Handling Robots Market |
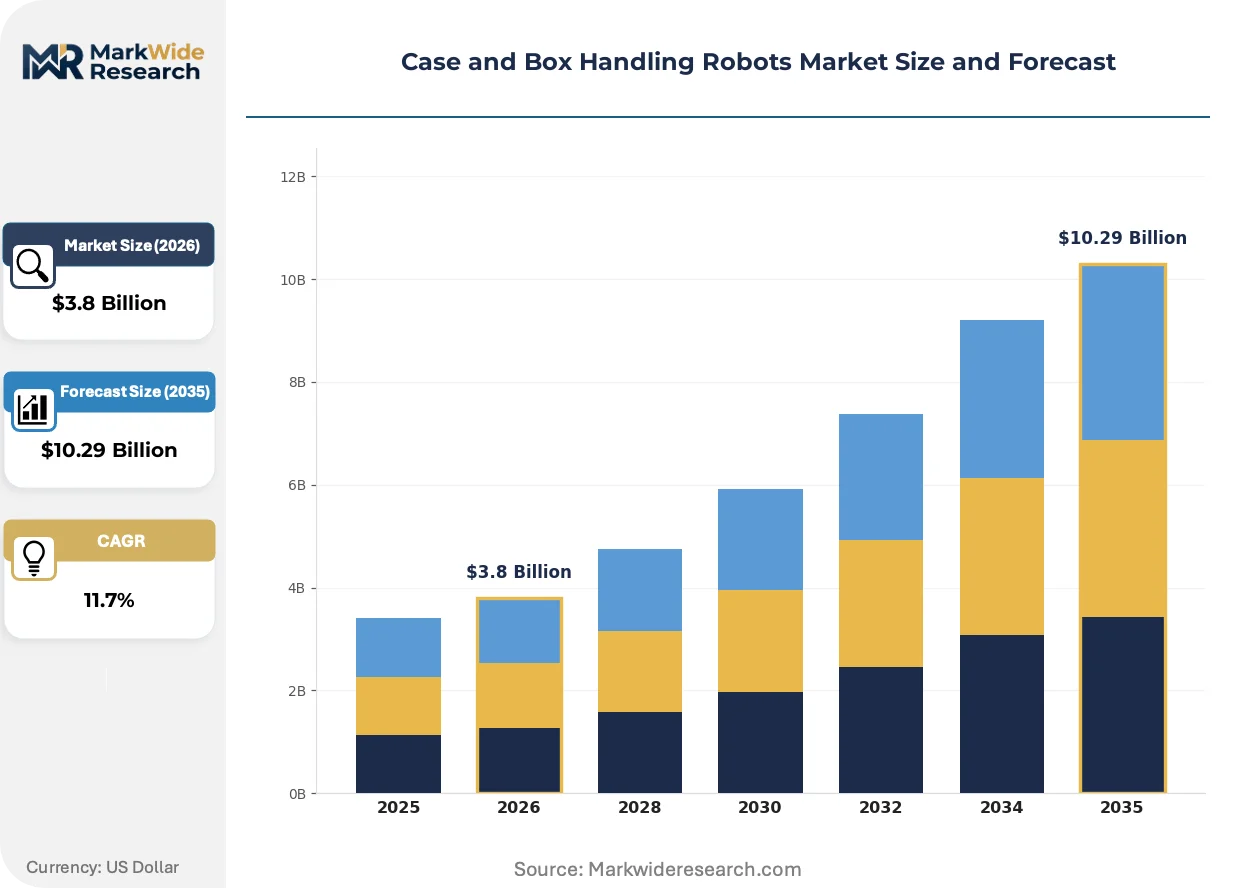
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Cartesian Robots, SCARA Robots, Delta Robots Technology: Vision Guidance, Force Control, Machine Learning, IoT Integration End User: E-Commerce, Food & Beverage, Pharmaceuticals, Consumer Goods Application: Packaging, Palletizing, Sorting, Pick and Place |
| Companies Covered | FANUC America, Yaskawa America, Brenton, Bastian Solutions, Teradyne, ABB, KUKA, Kawasaki Heavy Industries, Dematic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case and Box Handling Robots Market Strategic Shifts
Active perception systems are compressing the gap between fixed automation flexibility and robotic precision, enabling case handling deployments in facilities previously served by manual labor or rigid conveyor infrastructure.
Adaptive vacuum end-effectors with multi-zone suction arrays are automating the handling of damaged or irregularly sealed boxes that previously required manual sorting. Third-party logistics providers in the Benelux region are deploying these systems at throughput rates matching conventional mechanical grippers. The technology is automating quality-control handoffs between inbound receiving and outbound shipping lanes, reducing labor touchpoints in high-velocity cross-dock operations.
OSHA's updated machine guarding standards for collaborative systems are recalibrating safety zone calculations and force-threshold documentation requirements. US warehouse operators must now maintain detailed risk assessment records for each human-robot workcell configuration. Food and beverage distribution centers in California and Texas are responding by consolidating vendor relationships with integrators holding pre-validated safety certification packages.
Subscription-based robot-as-a-service contracts are displacing capital purchase models among mid-market e-commerce fulfillment operators. Equipment financing firms are underwriting deployment costs in exchange for per-pallet handling fees, transferring obsolescence risk from end-users to OEM balance sheets. This arrangement is most visible in German automotive supplier parks, where tier-one logistics providers prefer operational expenditure treatment for seasonal volume spikes.
Case and Box Handling Robots Market Segmentation
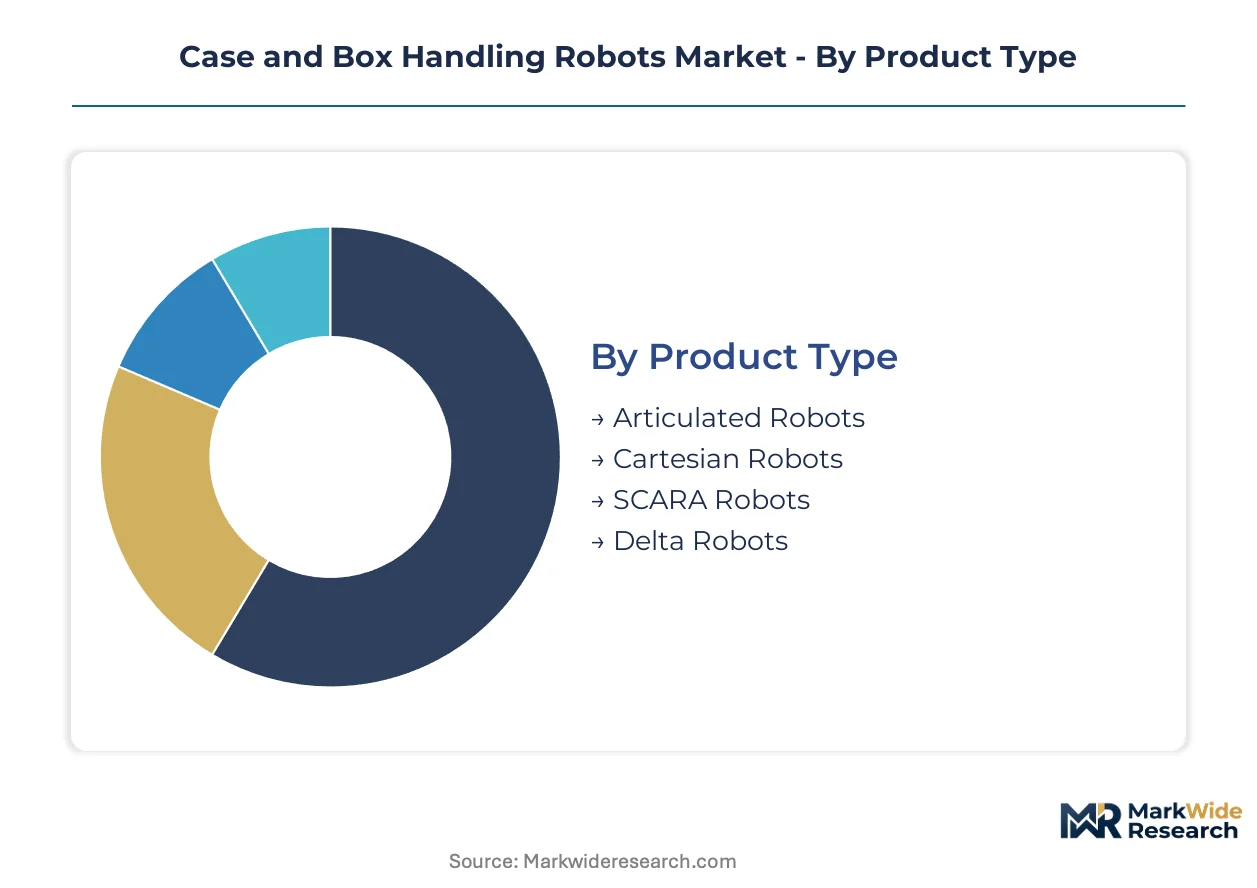
Robot architecture determines payload capacity, workspace envelope, and cycle speed for case handling operations. Technology integration governs adaptability to variable box dimensions and safety compliance in collaborative environments.
Product Type:
Six-axis kinematics versus linear or parallel architectures define deployment suitability across weight classes and facility footprints.
- Articulated Robots:Six-revolute-joint configurations deliver multi-directional flexibility for heavy-case palletizing above fifty kilograms. Automotive tier-one suppliers in Germany specify these systems for mixed-SKU automotive parts containers where reach extension and wrist dexterity prevent product damage during high-speed placement.
- Delta Robots:Parallel-link mechanisms achieve sub-millimeter placement accuracy at throughputs exceeding thirty cycles per minute through lightweight carbon-fiber arms and fixed base mounting. Pharmaceutical distribution centers in the Benelux region deploy delta configurations for high-speed sorting of temperature-sensitive biologics where vibration minimization protects product integrity.
- Cartesian Robots:Linear actuator assemblies on orthogonal gantries provide cost-effective solutions for single-plane palletizing with predictable box geometries.
- SCARA Robots:Selective compliance articulated arms excel in planar pick-and-place operations with cylindrical work envelopes and rigid vertical axis control.
Mature deployment sits with articulated systems in automotive logistics. Newer deployment is concentrated in delta configurations for pharmaceutical cold-chain expansion.
Technology:
Perception and control layers determine programming burden, changeover speed, and human-robot collaboration safety certification timelines.
- Vision Guidance:Camera-based box dimension recognition eliminates manual teach programming by generating pick coordinates from real-time point cloud analysis. E-commerce fulfillment centers in California deploy these systems to handle variable inbound parcel dimensions without SKU-specific programming, compressing changeover intervals from hours to minutes during promotional volume spikes.
- Force Control:Torque-sensing joints enable collaborative operation by limiting contact forces to ISO 10218 thresholds during human proximity. Food packaging lines in Texas integrate force-controlled arms for hand-guided programming of seasonal product variations, reducing specialist technician dependency.
- Machine Learning:Neural network-based grasp planning improves success rates for damaged or irregularly sealed boxes through iterative failure recovery.
- IoT Integration:Connected sensor networks enable predictive maintenance and fleet coordination across distributed warehouse operations.
Vision guidance dominates new installations for e-commerce flexibility. Force control is gaining share fastest in food and beverage collaborative cells.
End User:
Industry-specific handling requirements shape end-effector selection, environmental protection ratings, and traceability system integration.
- E-Commerce:High-velocity fulfillment centers demand adaptive handling of variable parcel weights and dimensions with minimal manual intervention. German logistics clusters deploy articulated and delta configurations in multi-tenant facilities where rapid SKU turnover exceeds fixed automation flexibility.
- Pharmaceuticals:Temperature-controlled distribution requires stainless steel construction and washdown compatibility to maintain FDA Current Good Manufacturing Practice compliance. Cold-chain expansion in the EU drives articulated robot installations for case handling within validated environmental envelopes.
- Food & Beverage:Hygienic design priorities and allergen segregation protocols influence robot selection and cleaning procedure integration.
- Consumer Goods:Seasonal demand volatility favors flexible robotic cells over dedicated conveyor infrastructure for secondary packaging operations.
E-commerce represents the largest installed base by unit volume. Pharmaceutical applications are expanding most quickly through cold-chain infrastructure investment.
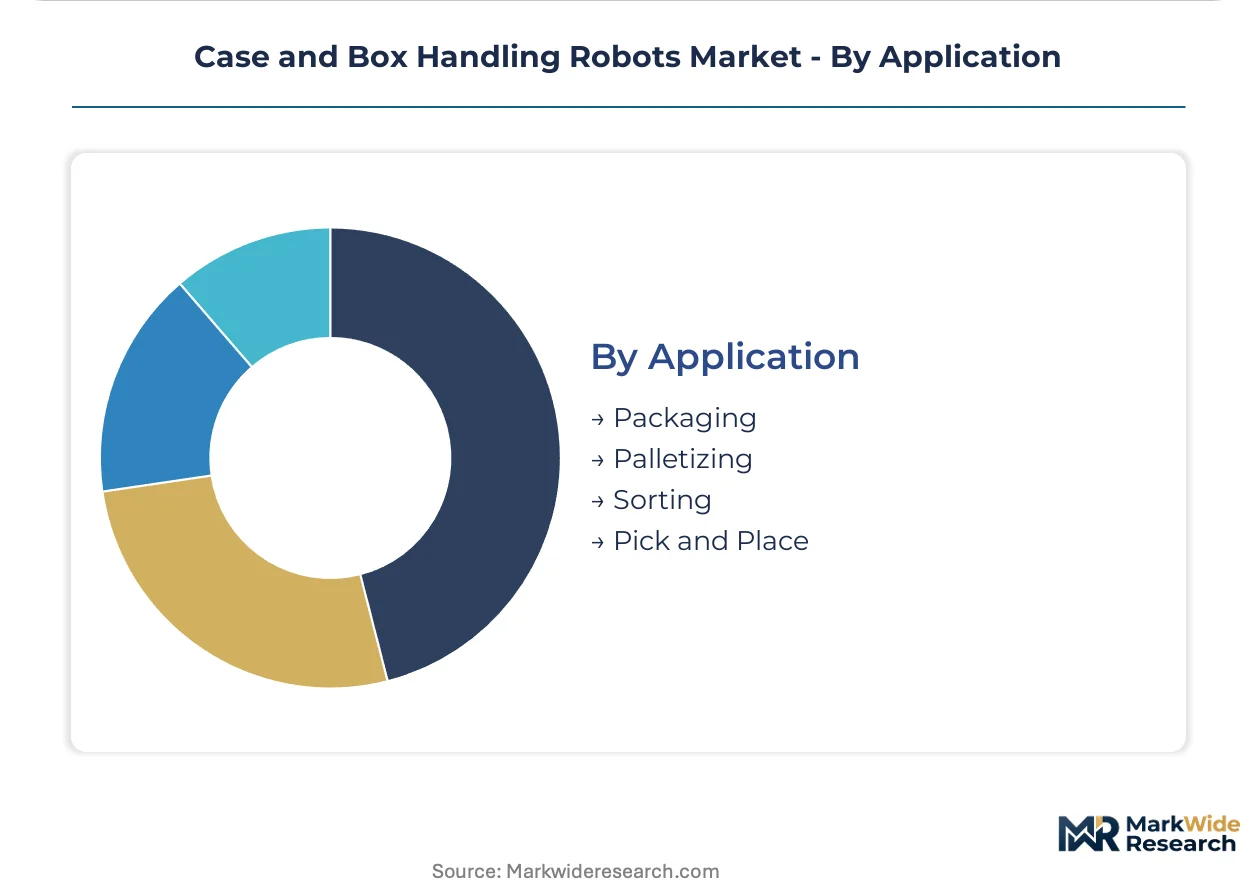
Application:
Process stage determines throughput requirements, placement precision, and integration complexity with upstream and downstream material handling equipment.
- Palletizing:Layer-forming and slip-sheet insertion operations require payload capacity and reach extension for mixed-SKU load stability. Automotive supplier parks in Germany specify heavy-payload articulated systems for tier-one parts consolidation where load pattern optimization reduces shipping damage claims.
- Sorting:High-speed diverting by destination code demands sub-second cycle times and vision-based barcode reading. Pharmaceutical distribution centers deploy delta robots for prescription fulfillment sorting where placement accuracy prevents medication errors.
- Packaging:Case erecting, loading, and sealing integration requires synchronization with form-fill-seal equipment and conveyor pacing.
- Pick and Place:General material transfer between conveyors and workstations spans lightweight to medium-payload requirements across end-user industries.
Palletizing commands the longest deployment history in automotive logistics. Sorting applications are climbing the fastest through e-commerce parcel volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Pune and Chennai concentrate India's emerging warehouse automation investments through production-linked incentive schemes for electronics and automotive manufacturing.
United States
OSHA's updated machine guarding standards recalibrate safety zone calculations for collaborative palletizing installations in California and Texas distribution centers. Food and beverage operators consolidate vendor relationships with integrators holding pre-validated certification packages. The Midwest automotive supplier corridor sustains demand for heavy-payload articulated systems.
Germany
The EU Machinery Directive's force-limiting mandates accelerate operational certification timelines for human-robot workcells in automotive logistics clusters. Västerås-based engineering centers specialize in force-controlled packaging lines for food producers. Bavaria and Baden-Württemberg anchor European demand through tier-one supplier parks requiring repeatable case placement above fifty kilograms.
China
E-commerce fulfillment volume expansion strains manual handling capacity in Yangtze River Delta distribution hubs. National standards for collaborative robot safety shape certification requirements for domestic system integrators. Shenzhen and Shanghai industrial zones deploy camera-guided pick-and-place systems to handle variable parcel dimensions during promotional volume spikes.
India
The PLI scheme for advanced manufacturing drives greenfield warehouse automation investments in Pune and Chennai corridors. Central electricity authority regulations influence power infrastructure planning for robotic fleet deployments. Karnataka's electronics manufacturing clusters adopt articulated configurations for secondary packaging operations serving export markets.
Japan
METI industrial automation policies support precision component supply chains for servo motor and reducer manufacturing. Pharmaceutical distribution centers in the Kanto region deploy delta robots for high-speed sorting of temperature-sensitive biologics. Osaka-based precision engineering maintains critical supply positions for motion control systems.
Case and Box Handling Robots Market Competitive Environment
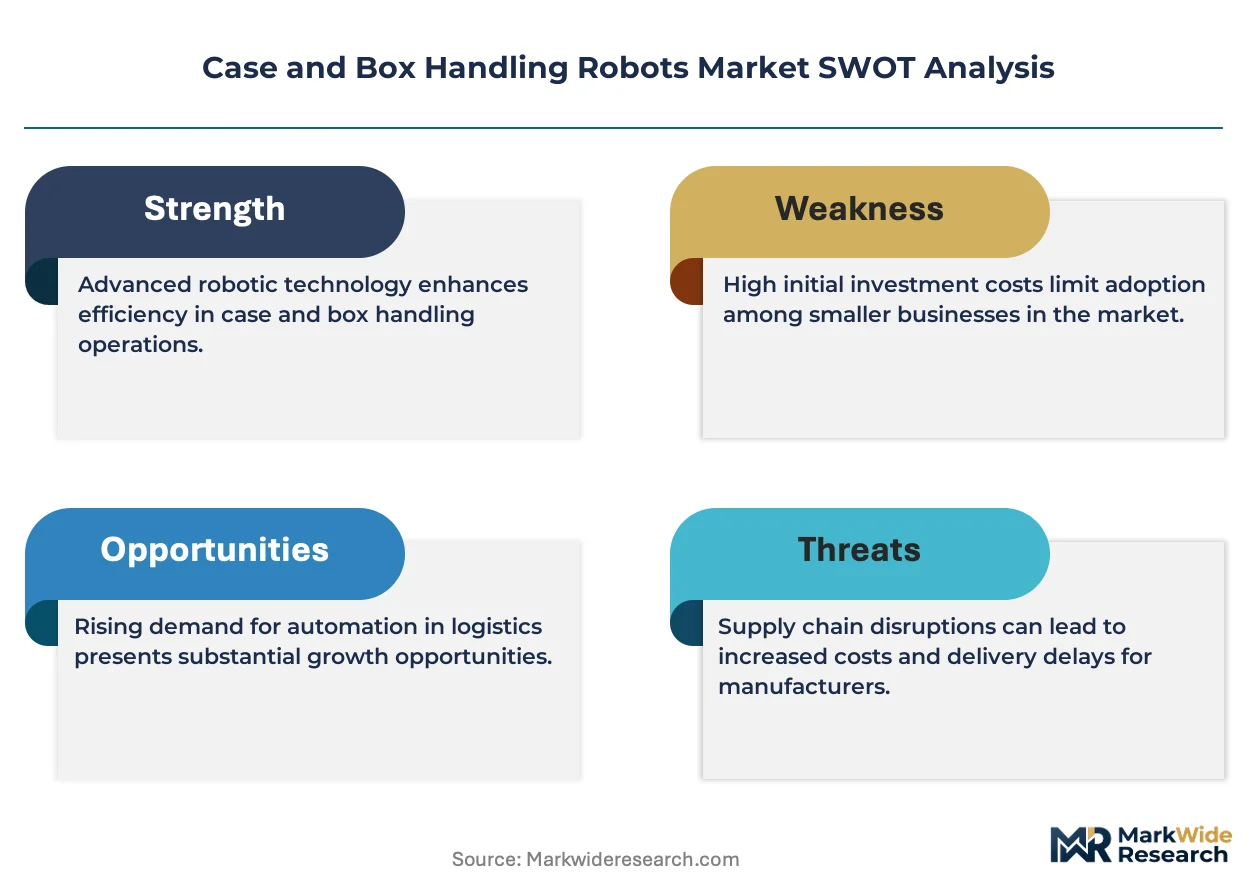
German and Japanese producers anchor one tier; American specialists hold integration and regional service advantages. The vendor structure concentrates around precision motion control supply chains with limited alternative sourcing for high-torque reducers. Three archetypes dominate: diversified industrial automation conglomerates, regional system integration specialists, and precision component captive suppliers. Competitive moves center on safety certification pre-validation and robot-as-a-service financing structures.
Within the diversified industrial tier, FANUC America and ABB exemplify geographic anchoring strategies that compress delivery cycles through localized manufacturing. Yaskawa America occupies a position representing Japanese precision motion control integration into North American warehouse networks. KUKA sits within the European heavy-payload specialization archetype serving automotive tier-one consolidation requirements.
| Leading Market Players |
|---|
| FANUC America |
| Yaskawa America |
| Brenton |
| Bastian Solutions |
| Teradyne |
| ABB |
| KUKA |
| Kawasaki Heavy Industries |
| Dematic |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 10218-validated collaborative systems and non-certified commodity alternatives manifests in pricing premiums exceeding thirty percent for force-controlled palletizing cells, while supply chain configurations cluster around Japanese and German precision component corridors that feed tiered manufacturing footprints in the United States and Europe.
Pricing Analysis
Lead-time-driven pricing stratification rewards domestic manufacturing proximity with premium positioning for rapid deployment cycles, while spot inventory from Asian assembly lines trades at discounted rates for non-urgent fulfillment. Robot-as-a-service subscription models now command twenty to thirty-five percent of mid-market transactions, compressing upfront capital barriers but extending lifetime revenue capture. Price differentiation hinges on force-limiting certification tier and after-sales service bundling, with California e-commerce operators showing highest sensitivity to per-pallet operational expenditure treatment. Pricing pressure stems from servo motor supply constraints that elongate delivery windows for non-priority customers.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive tier-one suppliers, while distributor networks serve fragmented mid-market logistics operators with standardized palletizing configurations. Geographic supply concentration centers on Japan and Germany for precision reducers and servo motors, with China expanding final assembly capacity for cost-optimized delta configurations. Critical component dependencies include harmonic drive reducers from Osaka-based suppliers and high-torque servo motors from Bavarian engineering centers. Single-source vulnerability in precision motion control creates lead time volatility that propagates through system integrator order books. Distribution runs through certified integrator partnerships that pre-validate safety documentation for end-user compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component supply scarcity and certification complexity are forcing consolidation among mid-sized system integrators unable to secure preferential reducer allocation or pre-validated safety packages.
For Market Incumbents: Deploy backward integration into precision reducer manufacturing or captive supply agreements with Japanese component houses to secure allocation priority during supply crunches. Fortify position by acquiring regional integrators holding pre-validated OSHA and EU Machinery Directive certification portfolios, neutralizing emerging competitors who lack compliance velocity. For New Entrants and Emerging Players: Enter via India PLI scheme corridors in Pune and Chennai, where greenfield warehouse automation investments lack incumbent service density. Target pharmaceutical cold-chain expansion with stainless steel articulated configurations serving FDA-validated distribution centers, leveraging regulatory compliance as differentiation against commodity Asian suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial automation conglomerates seeking regional service footprint expansion. Long-term viability favors targets with captive force-control algorithm IP and established integrator certification relationships. Watch for inflection when Japanese reducer suppliers announce capacity expansion timelines that decompress supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Force-Control Certification Pre-Validation | Compresses EU Machinery Directive compliance timelines for collaborative palletizing deployments. |
| Robot-as-a-Service Financing Structure | Transfers obsolescence risk from German automotive logistics operators to OEM balance sheets. |
| Vision-Guided Pick-and-Place Integration | Eliminates manual teach programming for California e-commerce fulfillment centers handling variable parcel dimensions. |
| Precision Reducer Supply Agreement | Secures allocation priority from Osaka-based suppliers during motion component supply crunches. |
| Pharmaceutical Cold-Chain Specialization | Captures FDA washdown-compatible demand from temperature-controlled biologics distribution expansion. |
Study Parameters
Trade association filings, customs import records, and SEC equipment manufacturer disclosures formed the secondary backbone, supplemented by primary interviews with warehouse automation directors, system integration engineers, and OEM procurement managers across automotive and pharmaceutical verticals. Bottom-up unit deployment estimates triangulated against top-down capital expenditure analysis from logistics operator financial statements.
Historical trendline analysis of articulated and delta robot shipments established baseline penetration rates across end-use industries, with projection modeling incorporating technology adoption curves for vision guidance and force control segments. CAGRs derived from segmented growth rate blending across e-commerce fulfillment, pharmaceutical distribution, and automotive supplier park applications, with cross-validation against precision component supplier order backlogs.
Revisions become necessary when Japanese reducer supply constraints materially exceed current lead time assumptions or when EU Machinery Directive enforcement intensity shifts collaborative certification timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Underwater Exploration Robots Market