
 Inspection Robots Market | 2026-2036
Inspection Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Inspection Robots Market Analysis
Robot-as-a-service leasing is reshaping capital deployment for mid-sized facility operators. ANYbotics leverages autonomous navigation software to compete in hazardous environment deployments. Gecko Robotics anchors structural inspection workflows with magnetic crawler systems for industrial assets. Waygate Technologies extends ultrasonic testing expertise into robotic platforms for power generation clients.
Inspection robots encompass mobile platforms equipped with sensors, cameras, and non-destructive testing instruments to evaluate asset condition without human entry into confined or hazardous spaces. These systems typically integrate lidar, thermal imaging, and ultrasonic probes to detect corrosion, cracks, or leaks in pipelines, tanks, and infrastructure. Ground robots and crawlers dominate current deployment volumes due to payload capacity for heavy NDT equipment. Machine learning and vision systems represent the fastest-expanding technology dimension as operators demand automated defect classification. The energy sector captures the largest end-user share, while safety compliance applications generate premium pricing for certified hazardous-area configurations.
OSHA confined-space regulations in the United States mandate atmospheric monitoring and rescue readiness, directly stimulating robotic substitution for human entry. The EU Machinery Directive and ATEX standards govern robot deployment in potentially explosive European environments, creating certification barriers that filter supplier participation. Stakeholders must evaluate whether autonomous navigation algorithms or regulatory compliance capabilities will determine vendor selection as facility operators consolidate maintenance contracts.
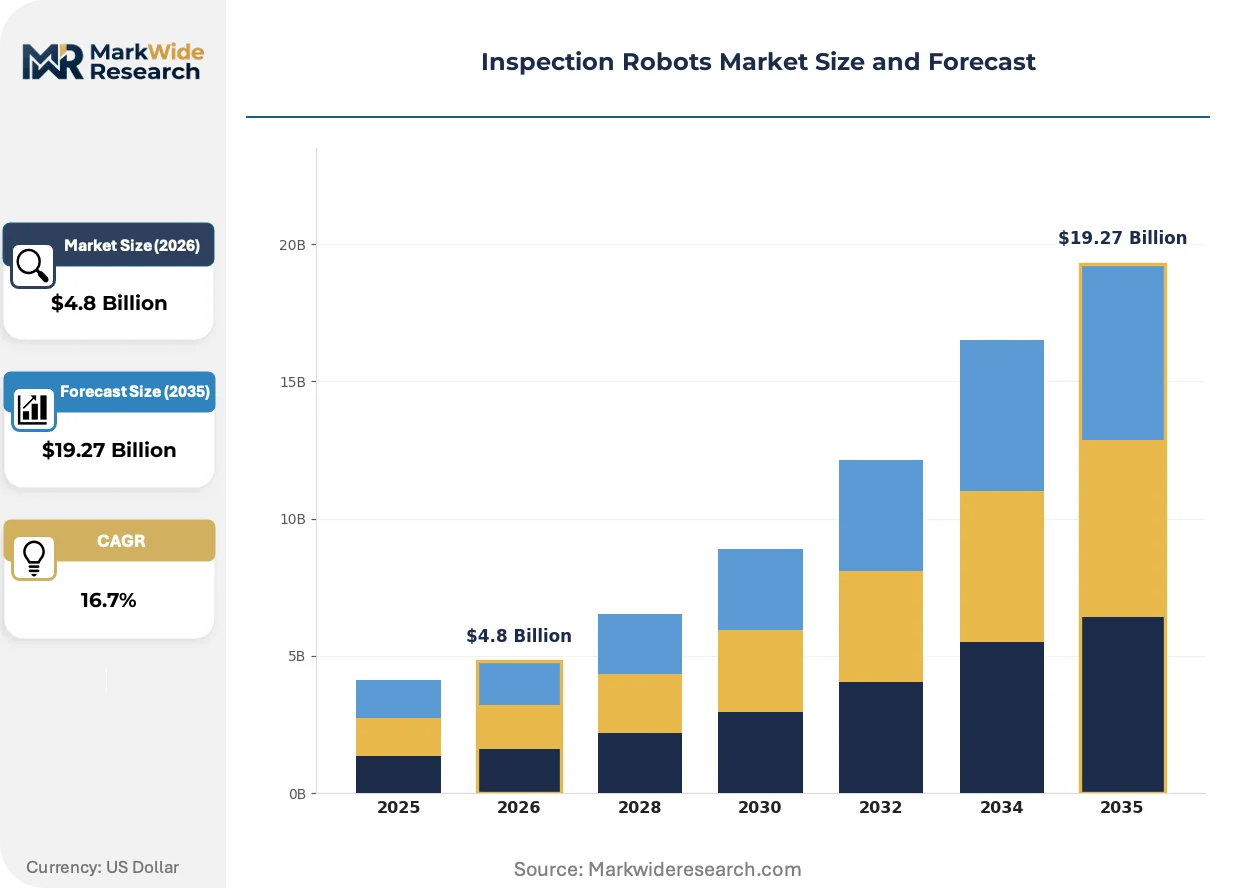
Market Dynamics
Machine learning integration in autonomous navigation systems is compressing inspection cycle times while PHMSA pipeline mandates and OSHA confined-space rules accelerate substitution of human entry with robotic platforms across energy infrastructure.
Growth Catalysts
- PHMSA Integrity Management:US pipeline operators face mandatory hydrostatic testing and direct assessment schedules that ground robots execute faster than manual crews, particularly in remote terrain.
- Ultrasonic phased-array sensors:Non-destructive testing payloads now detect sub-millimeter cracks in storage tanks, expanding addressable asset classes beyond visual inspection limits.
- German chemical cluster density:ECHA continuous emissions monitoring requirements at BASF, Bayer, and Lanxess facilities generate recurring demand for autonomous gas-sniffing crawlers.
Market Restraints
- Lithium-ion battery supply:Cell chemistry constraints limit runtime for magnetic crawlers on extended pressure vessel inspections, forcing tethered configurations that reduce mobility.
- ATEX certification timelines:EU notified body backlogs stretch hazardous-area robot approvals to 14-18 months, filtering out smaller vendors lacking dedicated compliance teams.
- Manual rope-access substitution:Low-cost inspection contractors in Southeast Asian shipyards underbid robotic deployment on straightforward visual surveys of hull structures.
Strategic Opportunities
- Offshore wind foundation inspection:Monopile and jacket structures below the splash zone lack established robotic protocols, creating first-mover advantage for subsea crawler developers.
- US Inflation Reduction Act:Clean energy tax credits for utility-scale solar and storage pair with accelerated depreciation for automated maintenance equipment.
- 5G private networks:Ultra-reliable low-latency communication enables real-time teleoperation of inspection robots in GPS-denied environments like underground mining tunnels.
Industry Challenges
- Multi-physics simulation talent:Vendors struggle to hire engineers capable of modeling magnetic adhesion, thermal drift, and vibration damping simultaneously for crawler chassis design.
- Legacy SCADA integration:Industrial facilities running 1990s-era control systems require costly protocol gateways to ingest robotic inspection data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inspection Robots Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Robots, Aerial Drones, Underwater Robots, Crawlers Technology: Telepresence, Autonomous Navigation, Machine Learning, Vision Systems End User: Energy Sector, Manufacturing, Infrastructure, Agriculture Application: Structural Inspection, Environmental Monitoring, Safety Compliance, Surveillance |
| Companies Covered | ANYbotics, Energy Robotics GmbH, SuperDroid Robots, Taurob, ExRobotics, Robotnik, Gecko Robotics, Waygate Technologies, NUCTECH COMPANY LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inspection Robots Market Emerging Trajectories
Edge computing architectures are relocating defect classification algorithms from cloud servers to onboard processors, eliminating latency for real-time go/no-go decisions in hazardous environments.
Digital twin synchronization is collapsing the boundary between physical inspection and predictive maintenance workflows. Robotic platforms now stream geometric and thermal data directly into Bentley Systems or Aveva asset models, allowing operators to simulate remaining useful life without manual model updates. Energy majors in the North Sea deploy this convergence to schedule turnaround intervals based on actual crack propagation rates rather than conservative calendar assumptions.
The EU AI Act's risk classification framework for autonomous systems imposes documentation burdens on inspection robot vendors deploying machine learning for defect recognition. High-risk categorization for infrastructure safety applications triggers conformity assessment procedures that extend time-to-market by 8-12 months. German and French facility operators now require algorithmic transparency reports as standard procurement addenda, favoring vendors with pre-established technical documentation.
Asset owners are unbundling inspection service contracts from traditional maintenance agreements, creating standalone robotic procurement vehicles with discrete performance metrics. US refineries and chemical plants issue request-for-proposals specifying defect detection rates and false-positive thresholds rather than hourly equipment rental. This shift concentrates purchasing authority with reliability engineering departments rather than general maintenance contractors, altering vendor sales engagement protocols.
Inspection Robots Market Segmentation
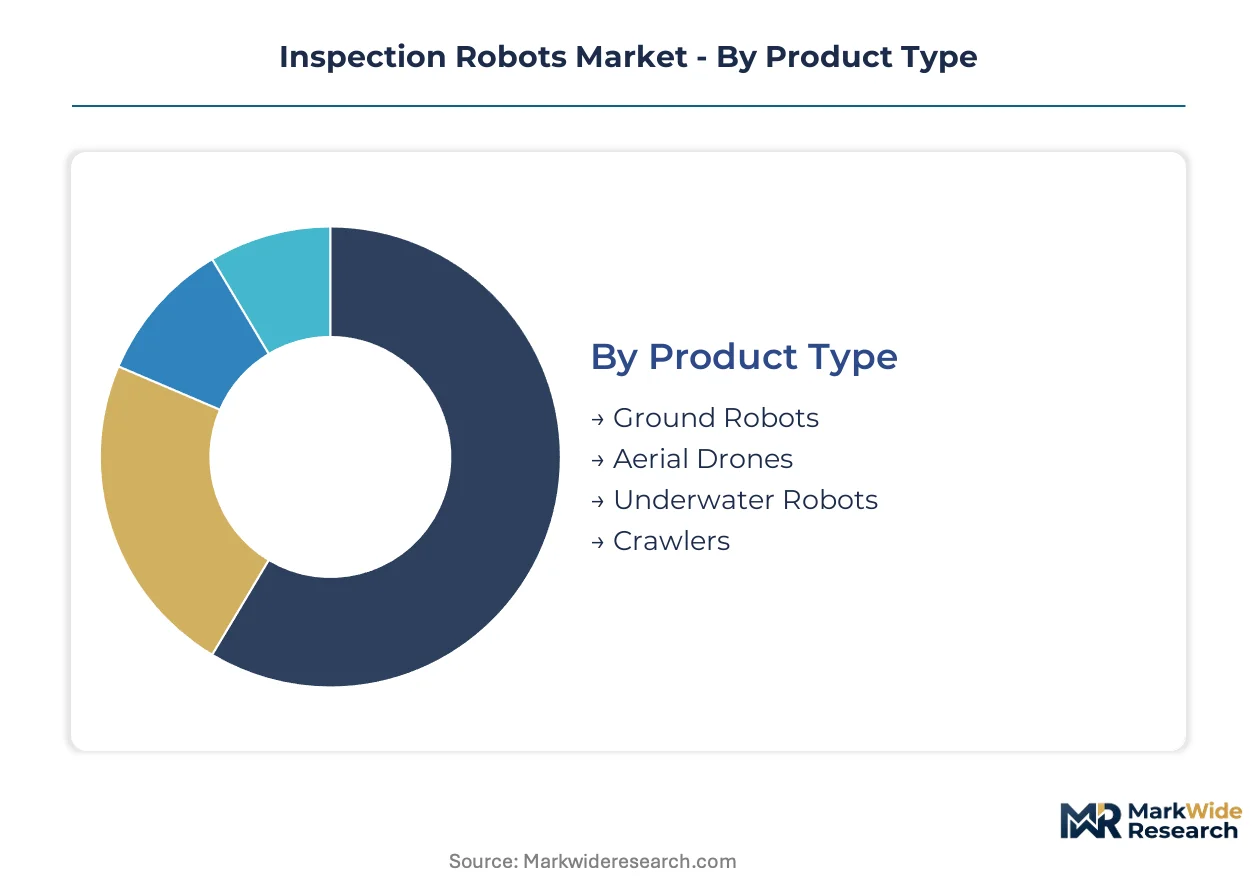
Segmentation in inspection robots reveals how payload constraints, autonomy levels, and regulatory exposure shape procurement decisions across asset-intensive industries. Operators select platforms based on whether the mission demands vertical mobility, subsea pressure tolerance, or magnetic adhesion on ferrous surfaces.
Product Type:
Cost tier separates inspection robot categories, with capital intensity and operational complexity driving distinct deployment economics across facility types.
- Ground Robots:Wheeled or tracked platforms carry heavy NDT payloads including ultrasonic phased-array sensors and thermal cameras across refinery floors and pipeline rights-of-way. PHMSA-mandated integrity assessments in Texas and North Dakota favor these units for remote terrain coverage where manual crews face mobilization delays.
- Crawlers:Magnetic adhesion systems scale vertical storage tanks and pressure vessels, transmitting real-time thickness data to corrosion engineers. German chemical clusters at Ludwigshafen and Leverkusen deploy these for continuous emissions monitoring under ECHA requirements.
- Aerial Drones:Rotorcraft with lidar and visual sensors access flare stacks and transmission towers without scaffolding.
- Underwater Robots:ROVs and autonomous subsea crawlers inspect cooling water intakes and offshore monopile foundations.
Ground robots command the established base. The steepest expansion runs through crawlers.
Technology:
Application maturity distinguishes technology tiers, with proven telepresence systems facing displacement from learning-enabled autonomy in hazardous environments.
- Autonomous Navigation:SLAM-based path planning eliminates GPS dependency for indoor refinery and underground mining deployments. German operators under EU AI Act documentation requirements favor vendors with pre-established algorithmic transparency reports for high-risk infrastructure classifications.
- Machine Learning:Edge-deployed defect classification models process thermal and ultrasonic data locally, enabling real-time go/no-go decisions without cloud latency. Energy majors in the North Sea leverage these systems to synchronize inspection streams directly into predictive maintenance digital twins.
- Vision Systems:Stereo cameras and structured light sensors generate 3D point clouds for crack detection.
- Telepresence:Operator-controlled platforms persist in straightforward visual surveys where autonomy premiums exceed value capture.
Telepresence retains legacy share in low-complexity missions. Autonomous navigation gains share fastest in regulated hazardous environments.
End User:
Volume concentration centers on asset operators with the highest regulatory exposure and cost of human entry.
- Energy Sector:Pipeline operators, refineries, and power generators deploy the full platform spectrum from aerial drones for transmission corridors to magnetic crawlers for storage tanks. OSHA confined-space regulations and PHMSA integrity mandates in the United States directly substitute robotic entry for human atmospheric monitoring.
- Infrastructure:Bridge, tunnel, and dam authorities adopt ground robots and crawlers for structural health monitoring.
- Manufacturing:Automotive and aerospace facilities use vision-guided systems for quality assurance on production lines.
- Agriculture:Crop monitoring and irrigation infrastructure inspection represent emerging demand with lower current platform specialization.
Energy sector deployments anchor current revenue. Infrastructure applications expand most quickly as transportation agencies consolidate inspection contracts.
Application:
Customer type and procurement authority vary by application, with safety compliance commanding premium pricing and standalone contracting vehicles.
- Structural Inspection:Non-destructive testing of pressure vessels, pipelines, and storage tanks demands platforms with magnetic adhesion, ultrasonic payloads, and sub-millimeter crack resolution. US refineries now specify defect detection rates and false-positive thresholds in RFPs rather than hourly equipment rental.
- Safety Compliance:Confined-space atmospheric monitoring and hazardous area certification generate premium configurations. ATEX approval timelines of 14-18 months filter vendor participation to established players with dedicated compliance teams.
- Environmental Monitoring:Emissions sniffing and leak detection concentrate in chemical clusters with continuous monitoring mandates.
- Surveillance:Perimeter and facility security applications favor lower-cost aerial and ground platforms.
Structural inspection holds the largest installed base. Safety compliance climbs the fastest as reliability engineering departments consolidate maintenance authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing economies supplying hazardous-environment platforms to emerging inspection markets. Germany and the United States dominate outbound shipments of ATEX-certified crawlers and autonomous navigation systems. Import demand concentrates in industrializing regions modernizing pipeline and refinery infrastructure.
United States
PHMSA integrity management mandates drive crawler deployment across Permian Basin pipeline networks. OSHA confined-space regulations at Texas and Louisiana refineries substitute robotic entry for human atmospheric monitoring. Houston anchors the largest concentration of inspection robot leasing operations serving Gulf Coast petrochemical complexes.
Germany
ECHA continuous emissions monitoring requirements at BASF and Bayer facilities generate recurring demand for gas-sniffing magnetic crawlers. EU AI Act documentation burdens favor vendors with pre-established algorithmic transparency reports for high-risk infrastructure classifications. The Ludwigshafen chemical cluster operates the densest deployment of autonomous crawlers in European process industries.
China
Dual carbon goals accelerate robotic substitution in coal-fired power plant boiler inspections. GB standards for pressure vessel safety tighten manual entry restrictions at Sinopec and PetroChina refineries. The Yangtze River Delta manufacturing belt hosts expanding domestic production of magnetic adhesion crawlers for tank farm applications.
Japan
METI funding for decommissioning robotics at Fukushima Daiichi sustains specialized crawler development. JIS standards for nuclear containment inspection mandate sub-millimeter crack resolution capabilities. The Chubu region around Nagoya concentrates precision engineering suppliers for ultrasonic phased-array sensor integration.
United Kingdom
North Sea offshore operators deploy subsea crawlers for monopile foundation assessments under Health and Safety Executive guidelines. The UK's national pharmaceutical regulator enforces containment integrity standards that drive robotic substitution in sterile manufacturing environments. Aberdeen anchors subsea inspection robotics development tied to offshore wind expansion timelines.
Inspection Robots Market Vendor Landscape
On the supply side, the industry is bifurcated between established industrial automation conglomerates and specialized hazardous-environment robotics firms. Tier-one positions concentrate around vendors with ATEX certification capabilities and dedicated compliance teams. Three strategic archetypes dominate: autonomous navigation software specialists, magnetic crawler hardware fabricators, and non-destructive testing integrators. Competitive moves center on technology licensing partnerships and vertical integration into sensor payload manufacturing.
Within the autonomous navigation tier, ANYbotics and Energy Robotics GmbH exemplify software-centric positioning. Gecko Robotics anchors the magnetic crawler hardware segment with vertically integrated payload development. Waygate Technologies occupies a position bridging ultrasonic testing expertise with robotic platform deployment. These three represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| ANYbotics |
| Energy Robotics GmbH |
| SuperDroid Robots |
| Taurob |
| ExRobotics |
| Robotnik |
| Gecko Robotics |
| Waygate Technologies |
| NUCTECH COMPANY LTD |
| Others |
Supply Flow & Price Mechanics
LiDAR sensor and high-torque motor fabrication in Germany and Japan concentrates upstream margin capture for precision navigation hardware, while downstream pricing power clusters with vendors bundling ATEX certification and predictive maintenance software for North American energy majors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the inspection robots market. Premium tiers command spreads based on SIL-rated safety certification and integrated digital twin synchronization, while standard configurations compete on ultrasonic payload density. Pricing pressure stems from Chinese domestic crawler manufacturers expanding into Southeast Asian tank farm markets. Mid-sized facility operators exhibit highest price sensitivity, whereas integrated energy majors prioritize total cost of ownership metrics over unit acquisition cost.
Supply Chain Analysis
Magnetic adhesion substrates and subsea pressure-rated housings draw from specialized metalworking clusters in Germany, Japan, and the United Kingdom. Lithium-ion battery cell supply rests on South Korean and Chinese cathode chemistry production, with solid-state alternatives emerging from Japanese pilot lines. Single-source vulnerability concentrates in precision ultrasonic transducer fabrication, where three European suppliers control phased-array probe manufacturing. Distribution runs through authorized system integrators and robot-as-a-service leasing platforms serving Gulf Coast petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inspection robots represent a high-growth disruption propelled by OSHA confined-space substitution mandates and EU AI Act documentation requirements that filter vendor participation toward compliance-capable incumbents.
For Market Incumbents: Build regulatory certification moats through dedicated ATEX notified body relationships and pre-positioned algorithmic transparency documentation. Expand in-house production of magnetic adhesion substrates to reduce exposure to German steel processor bottlenecks. Acquire edge computing specialists to defend against software-centric autonomous navigation entrants. For New Entrants and Emerging Players: Build out offshore wind foundation inspection protocols where established robotic workflows remain undefined, targeting Aberdeen and Hamburg marine engineering clusters. Penetrate the subsea crawler segment through partnerships with North Sea diving contractors seeking to displace saturation diving crews. Pursue 5G private network integration as a differentiated go-to-market angle for underground mining applications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed magnetic crawler manufacturers holding BASF and Bayer framework contracts but lacking autonomous navigation software stacks. Five-to-ten year viability hinges on successful digital twin integration and recurring software revenue attachment. Monitor EU notified body approval velocity as the critical inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ATEX Certification Fast-Track | Accelerates market access for autonomous crawlers under EU Machinery Directive enforcement. |
| Digital Twin Platform Integration | Enables direct data streaming from robotic platforms into Bentley Systems asset models. |
| Robot-as-a-Service Leasing Expansion | Reduces capital barriers for mid-sized refineries adopting PHMSA-mandated inspection protocols. |
| Subsea Crawler Protocol Development | Captures first-mover position in offshore wind monopile inspection workflows. |
| Edge Computing Architecture Migration | Eliminates cloud latency for real-time defect classification in GPS-denied environments. |
Methodological Framework
Cross-validation between primary interviews with reliability engineering directors and secondary validation through PHMSA enforcement data anchors the qualitative findings. Conversations with plant managers at Texas and Louisiana refineries, aftermarket service heads at crawler OEMs, and procurement leads at North Sea offshore operators informed operational deployment patterns. Secondary sources include OSHA incident databases, EU ATEX certification registries, and SEC filings from industrial automation conglomerates. Bottom-up unit deployment estimates triangulate against top-down energy sector maintenance expenditure allocations.
Calibration against historical integrity management spending patterns and announced refinery turnaround schedules shapes the projection framework. Segmentation dimensions span product type, autonomy level, end-use sector, and regional regulatory cluster. CAGRs derive from regression analysis of robotic substitution rates against manual rope-access contractor pricing. Forecast inputs incorporate lithium-ion battery cost curves and EU notified body approval queue lengths.
Stress conditions across ATEX certification timeline extensions, battery chemistry supply disruptions, and offshore wind installation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OSHA enforcement continuity and EU AI Act implementation sequencing. Cross-checking against EIA refinery maintenance expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Telepresence Robot Market