
 Underwater Data Center Market | 2026-2036
Underwater Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Data Center Market Insights
Subscription-based connectivity services is repositioning vendor economics away from one-time hardware sales toward recurring revenue streams. Microsoft anchors its strategy through sustained R&D intensity in pressure-resistant vessel engineering. Huawei leverages its integrated telecom infrastructure to dominate coastal deployment sites across East Asia. Subsea Cloud specializes in turnkey subsea leasing models that reduce capital barriers for research institutions.
An underwater data center consists of sealed pressure vessels housing standard server racks, operating at depths between 20 and 1,000 meters where ambient seawater temperature remains between 2°C and 15°C, eliminating mechanical refrigeration demand. These facilities primarily serve latency-sensitive computing workloads for populations concentrated along coastlines. Liquid cooling and immersion cooling configurations command the deepest margin pools due to their compatibility with high-density GPU clusters. Colocation and hybrid deployment models are gaining traction fastest among cloud providers seeking to diversify geographic risk without full capital ownership.
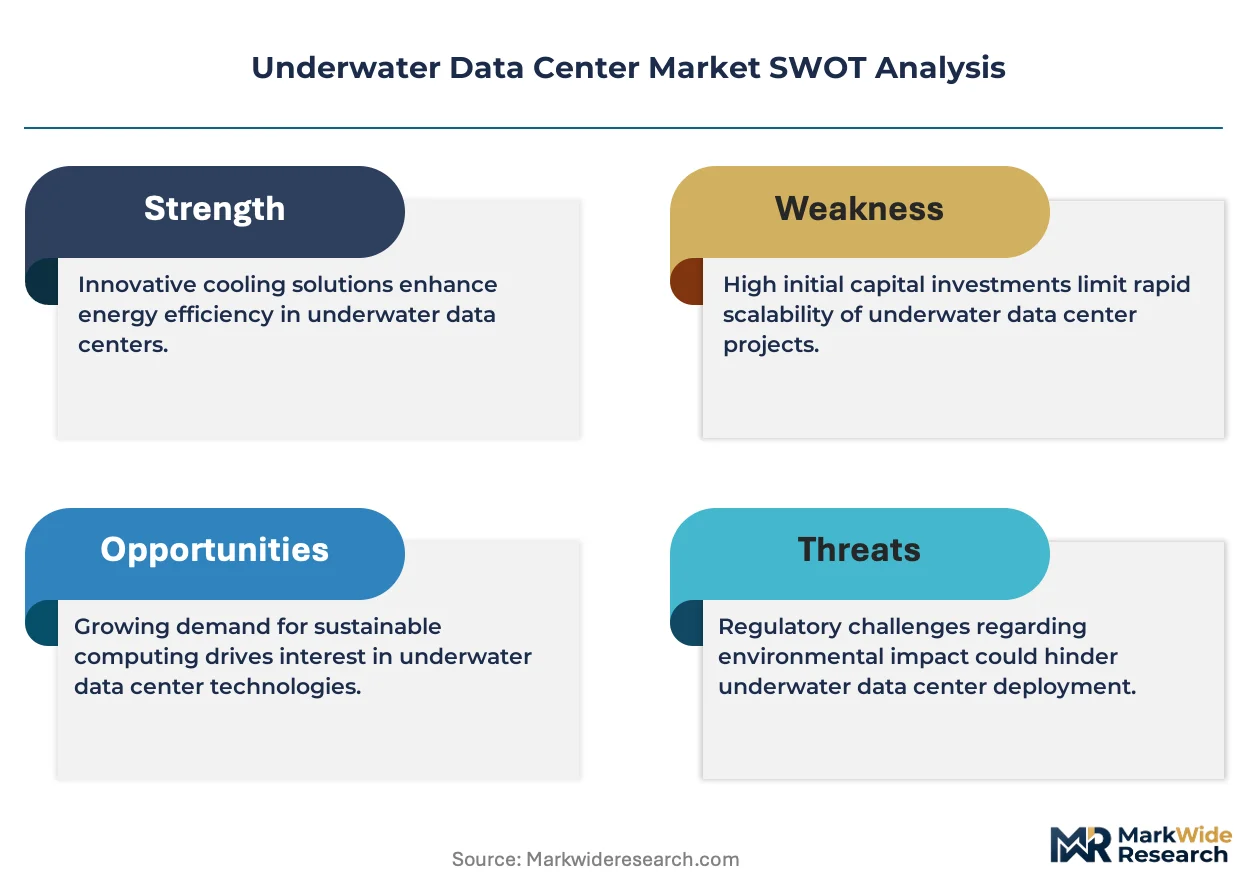
China's MIIT and SAMR enforce GB standards for subsea telecommunications infrastructure, while the EU F-Gas Regulation and REACH framework restrict synthetic refrigerants that conventional data centers depend upon, indirectly advantaging seawater-cooled alternatives. The US Coast Guard and FCC coordinate on submarine cable corridor permitting, which constrains site selection but protects operational integrity. Stakeholders must weigh regulatory fragmentation against thermal efficiency gains when sequencing international expansion priorities.
Market Dynamics
Pressure-resistant vessel engineering is compressing deployment timelines while ambient seawater cooling eliminates mechanical refrigeration infrastructure entirely. Coastal cloud providers now sequence expansion around submarine cable landing points rather than terrestrial power grid capacity.
Growth Catalysts
- Liquid cooling compatibility:Immersion configurations align with high-density GPU cluster thermal profiles. Hyperscale operators prioritize subsea sites for AI training workloads.
- EU F-Gas Regulation:Synthetic refrigerant phase-downs indirectly advantage seawater-cooled alternatives over conventional mechanical cooling. Data center operators face compliance cost escalations onshore.
- East Asian coastal concentration:Population density along Pacific Rim shorelines creates natural latency-sensitive compute demand clusters. Submarine cable density supports low-latency connectivity.
Market Restraints
- Specialized steel alloy supply:Pressure hull manufacturing depends on narrow supplier bases in Japan and South Korea. Input cost volatility tracks naval shipbuilding cycles.
- Submarine cable corridor permitting:US Coast Guard and FCC coordination constrains site selection to pre-cleared corridors. Alternative locations face multi-year approval timelines.
- Tidal zone maintenance access:Retrieval operations require weather-dependent surface vessel availability. Downtime risk exceeds terrestrial facility service level agreements.
Strategic Opportunities
- Nordic territorial waters:Norway and Scotland offer deep fjord proximities to European population centers with minimal fishing conflict. Cold water temperatures maximize thermal efficiency.
- Turnkey leasing models:Research institutions and mid-tier cloud providers seek capital-light access without vessel ownership. Subscription structures reduce balance sheet barriers.
- Hybrid deployment architectures:Colocation arrangements let operators diversify geographic risk across submerged and terrestrial assets. Load balancing optimizes latency and redundancy.
Industry Challenges
- Pressure vessel welding certification:ASME and DNV standards require specialized underwater construction expertise. Qualified technician pools remain shallow relative to deployment targets.
- Biological fouling management:Marine organism accumulation on external heat exchangers degrades thermal performance. Cleaning protocols must balance efficacy against environmental permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Data Center Market |
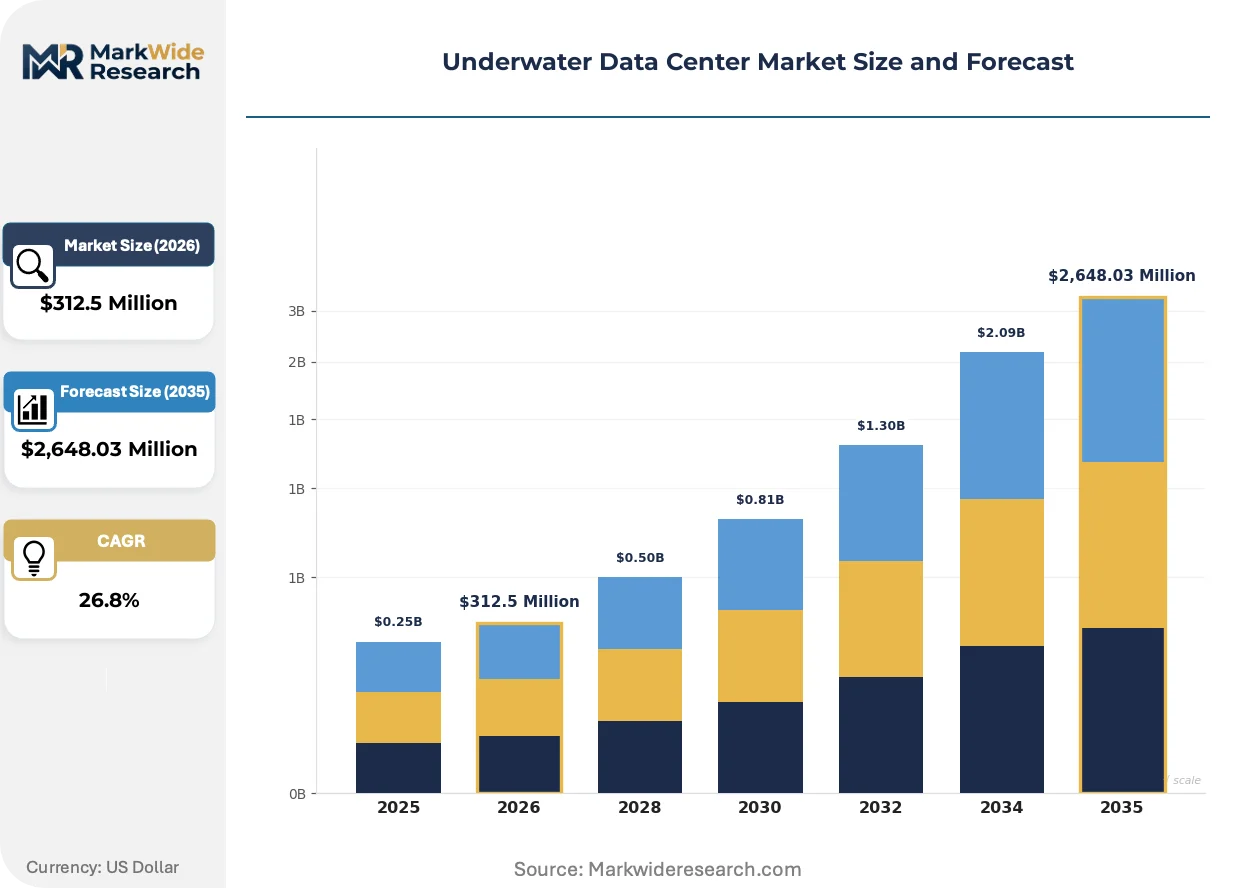
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,648.03 Million |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Colocation, Cloud, Hybrid Cooling Technology: Liquid Cooling, Direct-to-Chip, Immersion Cooling, Evaporative Cooling Service Type: Data Storage, Data Processing, Connectivity Services, Disaster Recovery End User: Financial Services, Research Institutions, Cloud Providers, Media Companies |
| Companies Covered | Subsea Cloud, Huawei, Microsoft, NetworkOcean, Naval Group, Nautilus Data Technologies, HiCloud, EcoDataCenter Marine, Highlander Digital Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Data Center Market Trends and Innovations
Subsea infrastructure economics are pivoting from experimental validation toward repeatable deployment templates. Standardized pressure vessel specifications and modular power distribution are compressing project development cycles.
Direct liquid cooling is overtaking air-side heat rejection in subsea enclosure designs. The technology circulates dielectric fluid through server cold plates before transferring waste heat to ambient seawater. Hyperscale operators are adopting it for AI inference clusters. Conventional chilled-water mechanical systems are overtaking legacy air-cooled architectures in new vessel specifications.
China's MIIT enforcement of GB standards for subsea telecommunications infrastructure is harmonizing vessel construction protocols with terrestrial data center reliability tiers. The framework mandates redundant power distribution and pressure monitoring systems. Domestic operators are aligning procurement specifications to these standards ahead of international expansion.
Cloud providers are unbundling long-term capacity commitments from hardware ownership obligations. Research institutions and regional telecoms now access submerged compute through short-term leasing without capital deployment. Norway and Scotland host the most active leasing arrangements. Subscription pricing is displacing traditional colocation contracts in coastal European markets.
Underwater Data Center Market Segmentation
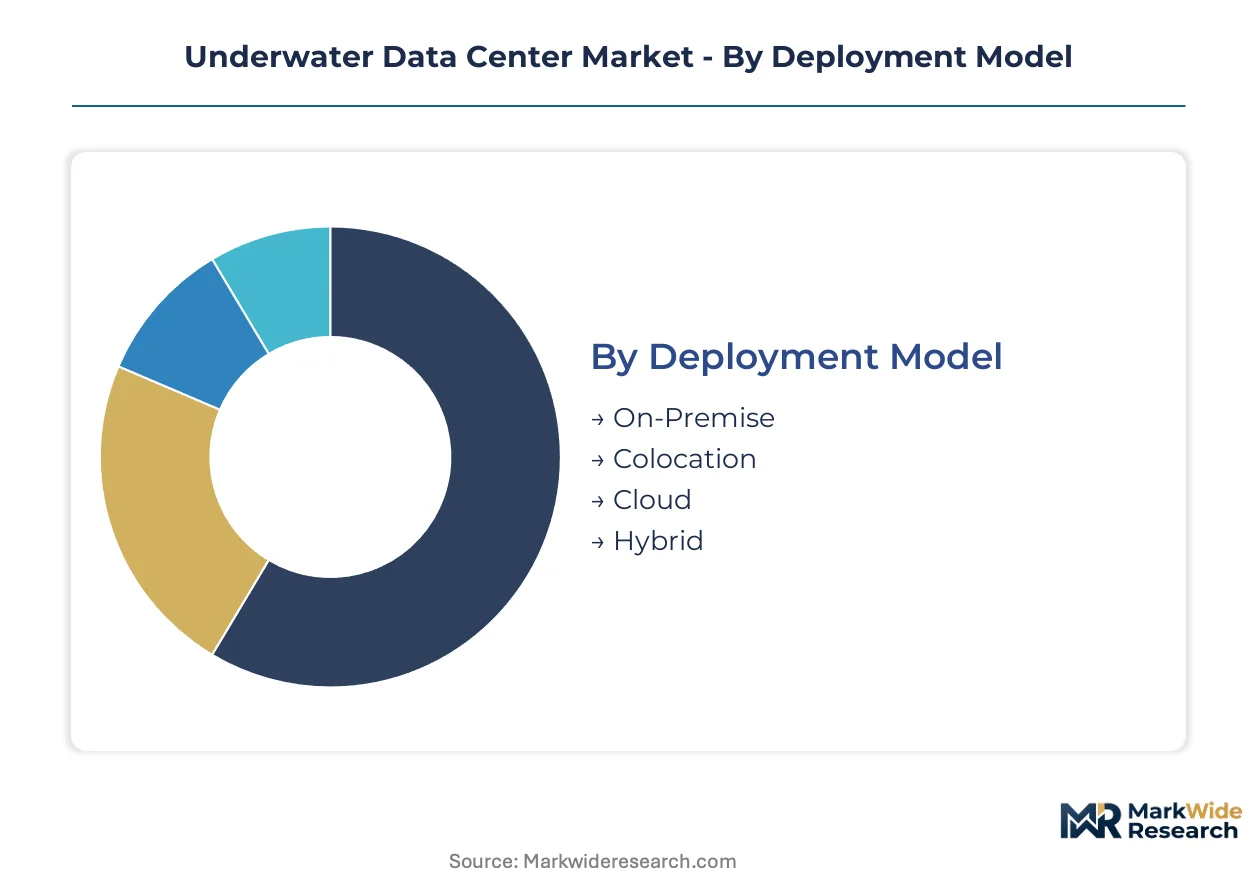
Segmentation reveals how buyer priorities diverge across capital intensity, thermal architecture, workload sensitivity, and regulatory exposure. Each dimension carries distinct margin profiles and vendor selection criteria that reshape competitive positioning.
Deployment Model:
Capital commitment thresholds determine deployment model selection, with ownership structures directly governing balance sheet treatment and operational flexibility.
- Colocation:Shared vessel infrastructure lets multiple tenants partition sealed pressure hulls through independent rack allocations. Research institutions and regional telecoms in Norway and Scotland favor this model to bypass ASME-certified welding requirements and specialized steel procurement. Growth tilts toward this segment as subscription pricing displaces traditional hardware ownership.
- Hybrid:Split workloads across submerged and terrestrial assets enable geographic risk diversification without full capital lock-in. Cloud providers sequence expansion around submarine cable landing points while retaining onshore failover capacity. Load balancing optimizes latency for Pacific Rim coastal populations.
- On-Premise:Single-tenant vessel ownership demands full pressure hull engineering investment and direct biological fouling management.
- Cloud:Hyperscale operators deploy captive subsea capacity for AI training clusters with direct liquid cooling integration.
Volume sits with Colocation; growth tilts toward Hybrid.
Cooling Technology:
Thermal density tolerance separates viable architectures, with GPU cluster compatibility now dictating technology selection.
- Liquid Cooling:Dielectric fluid circulation through server cold plates transfers waste heat directly to ambient seawater without mechanical refrigeration. EU F-Gas Regulation phase-downs indirectly advantage this configuration over synthetic refrigerant-dependent alternatives. Hyperscale operators prioritize subsea sites for AI inference workloads.
- Immersion Cooling:Fully submerged server boards in non-conductive fluid eliminate air-side heat rejection entirely. High-density GPU cluster thermal profiles align with this architecture's heat dissipation capacity. China's MIIT GB standards harmonize vessel construction protocols with terrestrial reliability tiers.
- Direct-to-Chip:Targeted cold plate attachment at processor level minimizes fluid volume and pumping energy.
- Evaporative Cooling:Seawater evaporation through external heat exchangers suits lower-density storage workloads with minimal GPU concentration.
Volume concentrates with Liquid Cooling; Immersion Cooling climbs the fastest on AI training demand.
Service Type:
Latency sensitivity and data sovereignty requirements segment service demand across workload types.
- Data Processing:Real-time computation for coastal populations demands sub-20 millisecond round-trip latency that submarine cable density enables. Pacific Rim deployment clusters concentrate here.
- Connectivity Services:Submarine cable landing point integration positions subsea facilities as network interconnection hubs.
- Data Storage:Cold archival workloads exploit thermal efficiency without mechanical refrigeration infrastructure.
- Disaster Recovery:Geographic separation from terrestrial seismic and weather risks drives replication topology design.
Volume sits with Data Processing; growth tilts toward Connectivity Services.
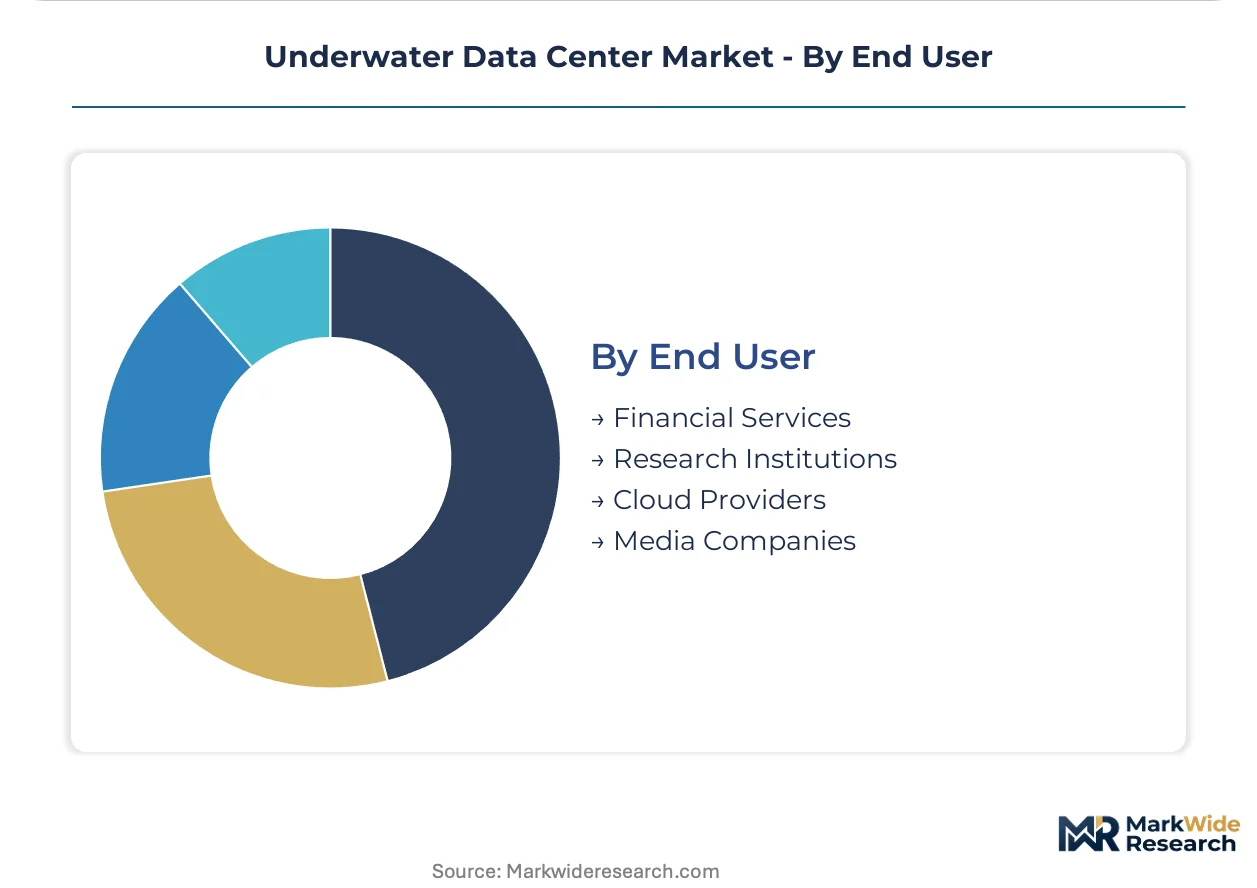
End User:
Workload characteristics and regulatory exposure separate buyer segments with distinct procurement patterns.
- Cloud Providers:Hyperscale operators drive standardization through repeatable deployment templates and modular power distribution specifications. Microsoft anchors sustained R&D intensity in pressure-resistant vessel engineering.
- Research Institutions:Capital constraints and intermittent compute demand favor turnkey leasing models without vessel ownership obligations. Subsea Cloud specializes in subscription structures that reduce balance sheet barriers.
- Financial Services:Latency arbitrage and regulatory data residency requirements shape site selection near major financial centers.
- Media Companies:Content delivery network edge positioning drives coastal deployment for streaming latency reduction.
Volume sits with Cloud Providers; growth tilts toward Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of deployed subsea capacity while vessel engineering concentrates in Japan and South Korea. Coastal latency demand and submarine cable density determine site selection across Pacific Rim markets.
China
MIIT and SAMR enforcement of GB standards for subsea telecommunications infrastructure harmonizes vessel construction with terrestrial reliability tiers. The dual carbon goals accelerate seawater-cooled alternatives over mechanical refrigeration. Huawei and Highlander Digital Technology operate multiple units along coastal provinces.
United States
Hyperscale operators sequence expansion around submarine cable landing points for AI training workloads. The Coast Guard and FCC coordinate on corridor permitting that constrains site selection to pre-cleared zones. Microsoft's sustained R&D intensity in pressure-resistant vessel engineering anchors Pacific Northwest development.
Norway
Deep fjord proximities to European population centers maximize thermal efficiency with minimal fishing conflict. The EU F-Gas Regulation indirectly advantages seawater-cooled alternatives over synthetic refrigerant-dependent onshore facilities. Turnkey leasing arrangements concentrate along western coastal municipalities.
United Kingdom
Scotland's coastal waters host active leasing arrangements for research institutions seeking capital-light access. The EU F-Gas Regulation phase-downs escalate compliance costs for conventional mechanical cooling onshore. Subsea Cloud specializes in subscription structures that reduce balance sheet barriers for regional telecoms.
Japan
METI oversight of industrial standards shapes pressure vessel welding certification requirements that track naval shipbuilding cycles. Specialized steel alloy supply from domestic fabricators supports pressure hull manufacturing. Coastal deployment clusters concentrate near Tokyo and Osaka submarine cable landing points.
Underwater Data Center Market Competitive Landscape
Capital-heavy vessel fabricators compete with asset-light platform operators for margin capture. The vendor base separates into three tiers: hyperscale cloud operators with captive R&D programs, integrated telecom infrastructure providers with coastal site control, and specialized leasing firms with turnkey subscription models. Dominant competitive moves include strategic partnerships with submarine cable consortiums and geographic expansion into Nordic territorial waters.
Among China-based integrated providers, Huawei occupies a position within the telecom infrastructure tier, leveraging coastal deployment site control across East Asia. Microsoft represents the hyperscale operator archetype, anchoring sustained engineering intensity in pressure-resistant vessel development. Subsea Cloud exemplifies the asset-light leasing model, sitting within the specialized services tier with turnkey structures for research institutions.
| Leading Market Players |
|---|
| Subsea Cloud |
| Huawei |
| Microsoft |
| NetworkOcean |
| Naval Group |
| Nautilus Data Technologies |
| HiCloud |
| EcoDataCenter Marine |
| Highlander Digital Technology |
| Others |
Pricing and Supply Chain Analysis
Direct liquid cooling adoption across subsea vessel specifications simultaneously compresses operational energy economics and concentrates procurement leverage among certified pressure hull fabricators. Japan and South Korea's naval shipbuilding cycles now govern input cost volatility for specialized steel alloys, while EU F-Gas Regulation compliance costs onshore accelerate buyer migration toward seawater-cooled alternatives.
Pricing Analysis
Cost-down pressure on colocation tiers accelerates because subscription pricing models displace traditional hardware ownership across Nordic leasing arrangements. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified vessel allocations from uncertified alternatives, with certification grade and volume scale as primary price differentiation drivers. Margin tightening in on-premise ownership traces to biological fouling management obligations and retrieval operation weather dependencies. Research institutions exhibit highest price sensitivity; hyperscale cloud providers demonstrate lowest sensitivity due to captive R&D amortization.
Supply Chain Analysis
Pressure vessel welding certification pools remain shallow relative to deployment targets across Japan, South Korea, and China's coastal manufacturing clusters. The supply chain draws from specialized steel alloy suppliers, dielectric fluid formulators, and submarine cable consortiums. Single-source vulnerability concentrates in ASME and DNV-qualified technician availability. Distribution runs through turnkey platform operators and direct hyperscale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation synthetic refrigerant phase-downs erect a compliance moat that seawater-cooled alternatives exploit, while terrestrial operators face escalating mechanical refrigeration cost burdens.
For Market Incumbents: Cement dominance in pressure-resistant vessel engineering through sustained R&D intensity and ASME-certified welding capacity expansion. Vertical integration into specialized steel alloy procurement hedges against naval shipbuilding cycle volatility. Biological fouling management protocols and retrieval operation service level agreements represent critical defensive levers against emerging turnkey leasing competitors. For New Entrants and Emerging Players: The premium-economy price-point gap in hybrid deployment architectures offers white-space access without full capital ownership obligations. Target research institutions in Scotland and Norway seeking capital-light subscription structures. Go-to-market positioning through submarine cable landing point proximity and direct liquid cooling compatibility for AI inference workloads accelerates penetration. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale cloud operator acquisition of turnkey leasing platforms with established Nordic site control. Long-term viability hinges on regulatory fragmentation arbitrage and thermal efficiency gains across the projection horizon. Watch for MIIT GB standards harmonization signals as inflection indicators for China-based integrated providers' international expansion readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Vessel Standardization | ASME and DNV certification alignment compresses deployment timelines for hyperscale operators. |
| Submarine Cable Consortium Partnership | Coastal site control near landing points locks in latency-sensitive compute demand clusters. |
| Turnkey Leasing Platform Launch | Subscription structures reduce balance sheet barriers for research institutions and regional telecoms. |
| Direct Liquid Cooling Integration | Dielectric fluid compatibility with GPU thermal profiles captures AI training workload migration. |
| Nordic Territorial Waters Expansion | Norway and Scotland fjord proximities maximize thermal efficiency with minimal fishing conflict. |
Research Methodology
Independent corroboration across hyperscale cloud procurement officers, pressure vessel engineering directors, submarine cable consortium managers, and regulatory affairs leads at MIIT and SAMR underwrites the qualitative findings. Secondary validation draws from SEC capex disclosures, EU F-Gas Regulation implementation reports, GB standards documentation, and naval shipbuilding cycle data. Bottom-up deployment unit tracking and top-down coastal latency demand modeling complete the triangulation.
Comparable-period anchoring to historical subsea facility commissioning rates and terrestrial data center construction cost indices shaped the forecast window. Segmentation across deployment model, cooling technology, service type, and end user dimensions was modeled throughout the forecast period. CAGRs were derived from deployment pipeline visibility and submarine cable landing point density correlations. Pressure hull manufacturing capacity constraints and biological fouling protocol efficacy served as industry-specific forecast inputs.
Inputs from hyperscale operator procurement disclosures and regulatory filing databases were available through the study window; gaps in proprietary vessel cost structures and retrieval operation downtime records introduce uncertainty bands. Forecasts reflect documented assumptions regarding F-Gas Regulation enforcement trajectory and ASME certification pipeline expansion. Material deviation in submarine cable corridor permitting timelines or specialized steel alloy supply shocks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
India Data Center Rack Market