
 Asia Pacific Hyperloop Technology Market | 2026-2036
Asia Pacific Hyperloop Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hyperloop Technology Market Intelligence
The shift towards public-private partnership (PPP) financing models for large-scale infrastructure is tilting the competitive landscape toward consortiums with deep sovereign and institutional backing. Hyperloop Transportation Technologies leverages a crowd-collaboration approach to de-risk its capital structure. Virgin Hyperloop positions itself as a technology partner within larger infrastructure bids. Transpod Inc. competes by focusing on freight-first applications to secure initial commercial contracts in countries like Australia.
Hyperloop technology involves propelling passenger or cargo pods through a low-pressure tube to minimize air resistance. These systems utilize magnetic levitation and linear electric motors to achieve speeds exceeding 1,000 km/h, aiming to drastically reduce inter-city travel times. The Propulsion System and Levitation System components represent the core intellectual property and highest value-add segments. While Passenger Transport remains the long-term vision, Freight Transit applications are gaining near-term traction with logistics companies in markets like China and India.
Regulatory frameworks for this nascent technology are still in development across the Asia Pacific region. National transport ministries in India and South Korea are establishing safety and certification protocols, while frameworks like China's GB standards will govern component manufacturing and interoperability. Stakeholder success now depends on navigating the complex interface between technological readiness and the formation of national-level regulatory approval pathways.
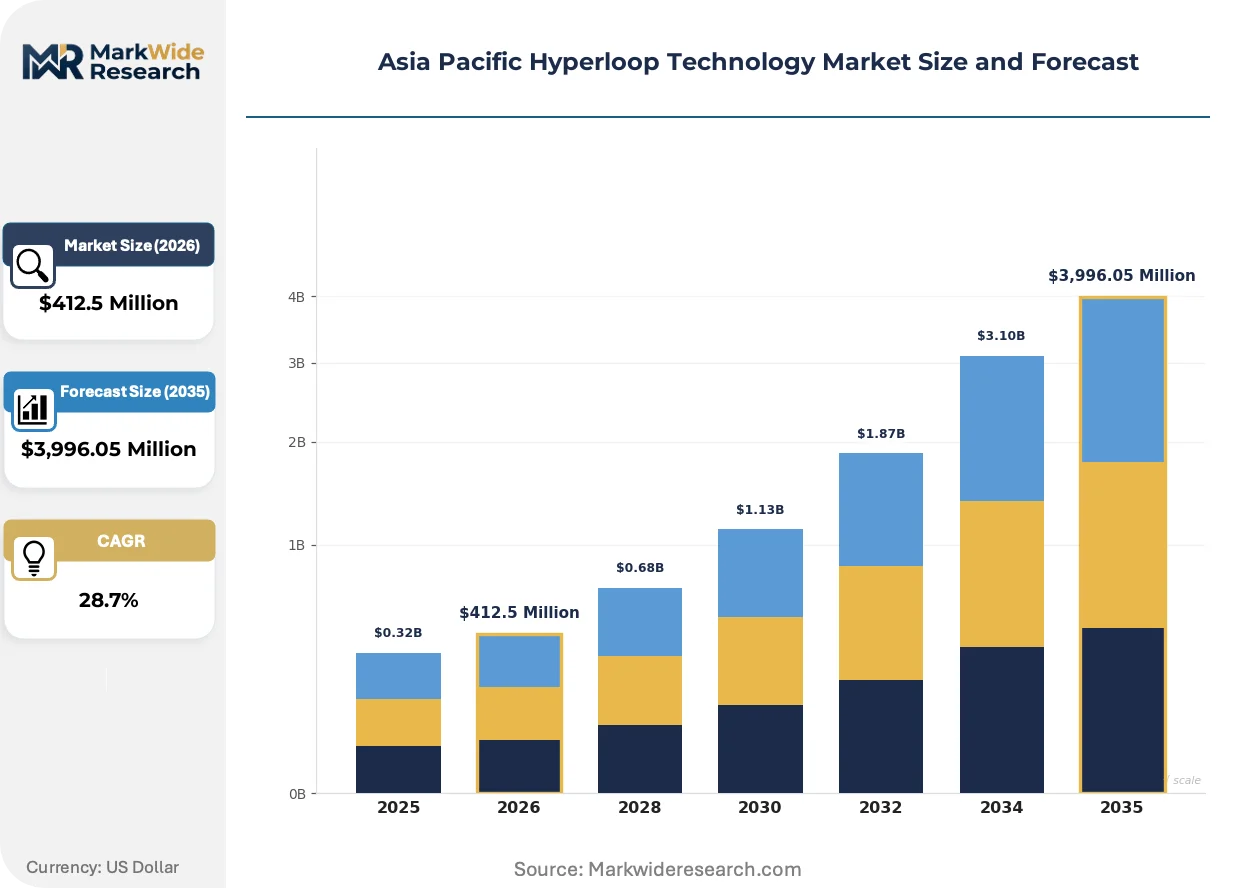
Market Dynamics
The central dynamic in the Asia Pacific hyperloop market is the alignment of government-led infrastructure ambitions with technological maturation. National policies, including India’s infrastructure pipeline and China’s dual carbon goals, are providing the top-down impetus for project development.
Growth Catalysts
- Policy Support:India's national infrastructure pipeline creates a direct funding pathway for large-scale transport projects, de-risking early-stage hyperloop development.
- Freight Demand:Intense pressure to resolve supply chain bottlenecks is driving logistics firms in China to explore hyperloop for high-speed cargo transport.
- Advanced Feasibility Studies:Concentrated project development and detailed assessments in South Korea are building investor confidence and clarifying the path to commercialization.
Market Restraints
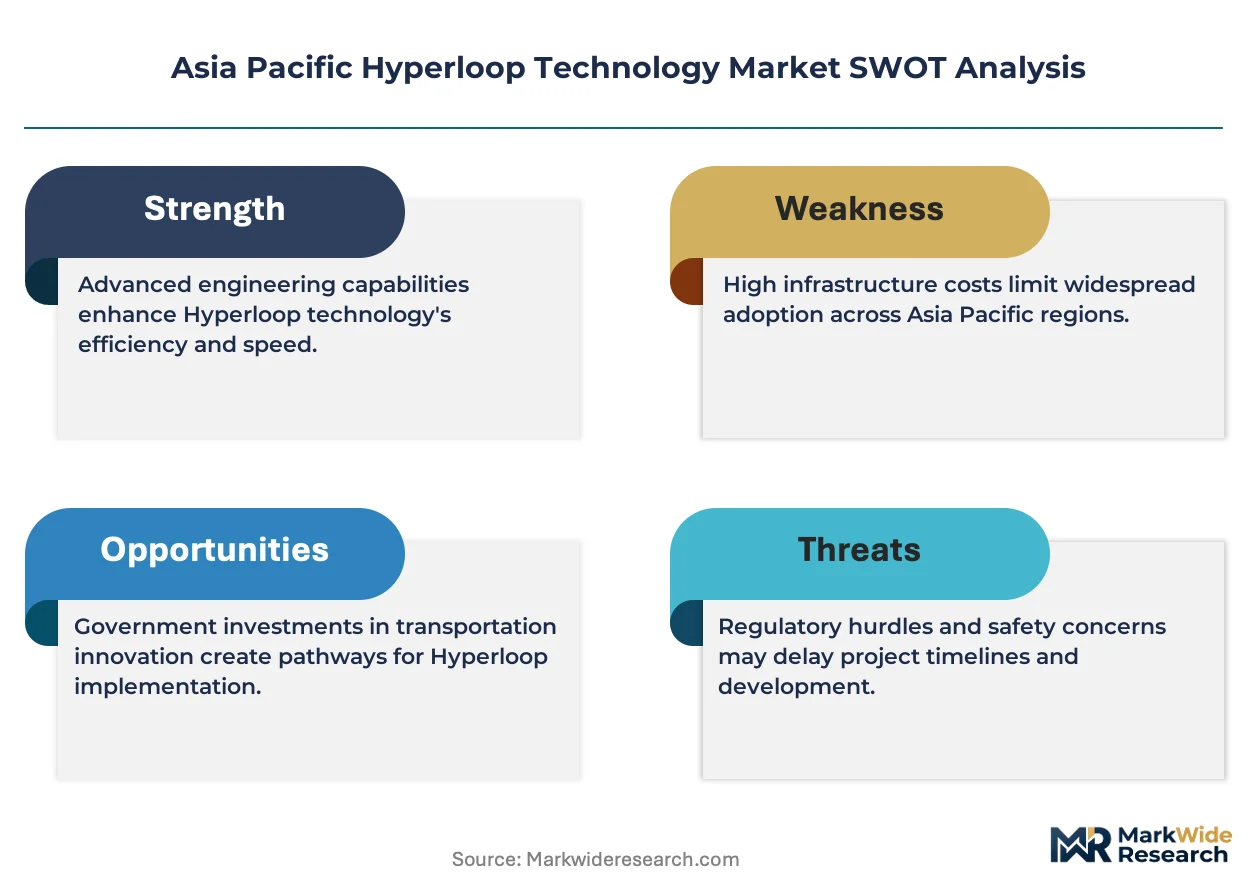
- Extreme Capital Costs:The immense upfront investment for tube and station infrastructure presents a formidable barrier for financing models without sovereign backing.
- Regulatory Gaps:A lack of harmonized safety and certification standards across the Asia Pacific region creates significant uncertainty for investors and developers.
- Vacuum Integrity:Maintaining a stable vacuum across vast tube networks remains a primary engineering and operational risk that impacts system reliability.
Strategic Opportunities
- Freight-First Commercialization:Focusing on freight applications in markets like Australia offers a path to earlier revenue before deploying complex passenger systems.
- Southeast Asia Expansion:Growing megacities in Indonesia and Vietnam present future opportunities for inter-city hyperloop links to alleviate severe traffic congestion.
- Smart City Integration:Converging hyperloop with smart city platforms and 5G networks enables the creation of seamless, data-driven multimodal transit systems.
Industry Challenges
- Interoperability Standards:The lack of common component standards, governed by bodies like China's GB standards, risks creating fragmented and incompatible national networks.
- Land Acquisition:Securing contiguous land rights for long-distance corridors is a major political and logistical hurdle, particularly in densely populated countries.
- Public Perception:Overcoming public skepticism about the safety and economic viability of this new transport mode is critical for securing political support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hyperloop Technology Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,996.05 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Levitation System, Propulsion System, Vacuum Technology, Control System, Infrastructure Components Application: Passenger Transport, Freight Transit, Emergency Services, Tourism, Logistics End User: Transportation Authorities, Logistics Companies, Emergency Responders, Travel Agencies, Infrastructure Developers Deployment Model: Public Sector Projects, Private Sector Initiatives, Public-Private Partnerships, Research & Development Facilities |
| Companies Covered | Virgin Hyperloop, Hyperloop Transportation Technologies, Tesla's Boring Company, Dinclix Groundworks, Hyperloop India, Transpod Inc., Space Exploration Technologies Corp, Zeleros Hyperloop, Hardt Global Mobility, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hyperloop Technology Market Strategic Shifts & Innovations
The evolution of hyperloop technology in Asia Pacific is defined by the concurrent development of core systems and the regulatory frameworks needed to govern them. Innovation is concentrating on component-level intellectual property for propulsion and levitation systems.
Next-generation passive magnetic levitation systems reduce the energy consumption and complexity of active control systems. Project consortiums in India and South Korea are incorporating these designs into feasibility studies. This focus on energy-efficient propulsion is rendering obsolete earlier, more power-intensive active maglev designs and lowering projected operational costs.
National transport ministries in India and South Korea are establishing dedicated safety and certification protocols for hyperloop systems. This proactive regulatory development provides a clearer pathway for developers to move from pilot to commercial deployment. Propulsion and Levitation System components face the highest scrutiny under new manufacturing frameworks like China's GB standards.
A definitive shift toward public-private partnership (PPP) financing models defines how new hyperloop projects are structured. This approach replaces purely venture-capital-backed models, favoring consortiums with deep sovereign and institutional financial support. This trend is most visible in India, where projects integrate into the national infrastructure pipeline, attracting long-term investors.
Asia Pacific Hyperloop Technology Market Segmentation
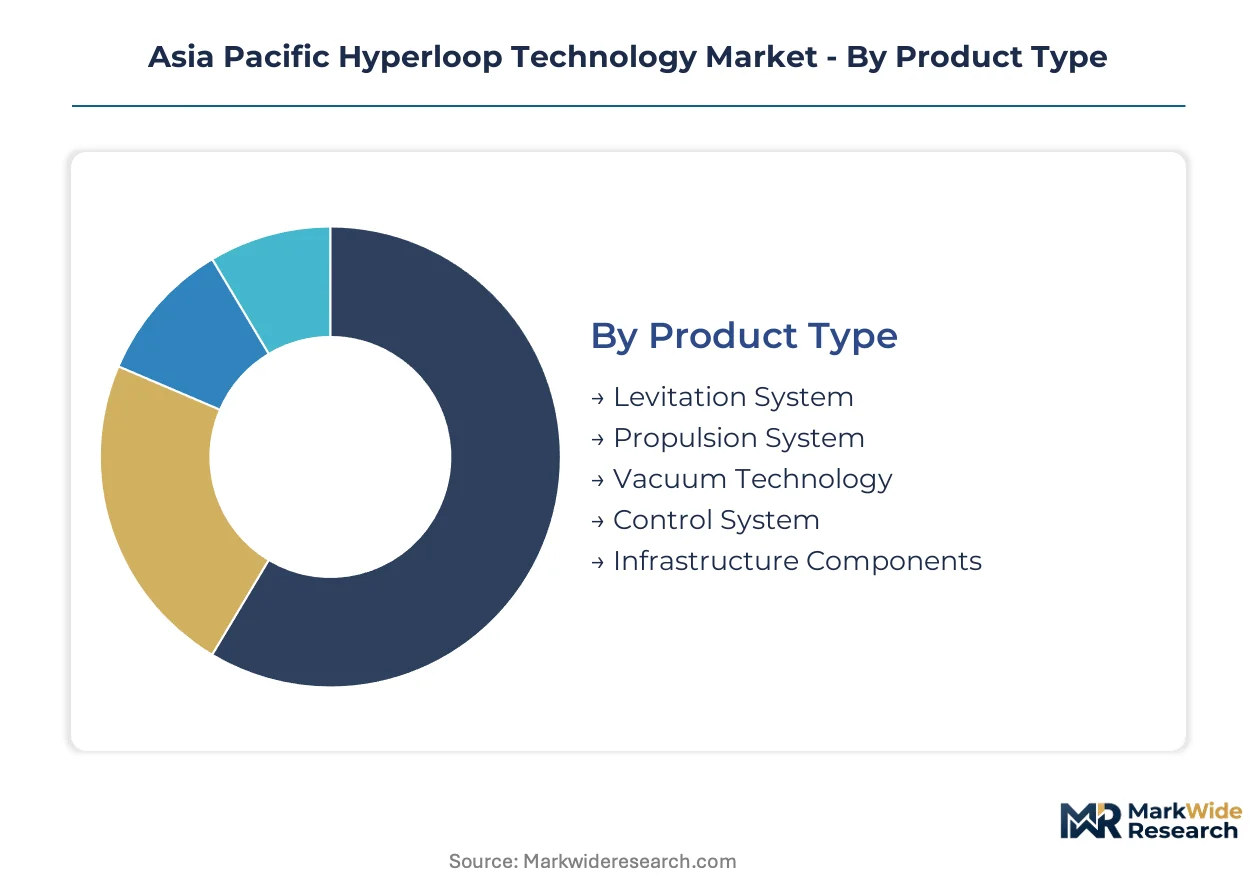
The Asia Pacific hyperloop technology market is segmented to provide a granular understanding of its diverse components and adoption patterns. This detailed breakdown helps identify specific areas of investment, technological focus, and end-user demand across the region.
Product Type:
The use-case spectrum for hyperloop technology encompasses a range of specialized product types, each critical for system functionality and performance.
- Propulsion System:These systems, often linear electric motors, generate the thrust required to accelerate and decelerate hyperloop pods within the low-pressure tubes, achieving speeds exceeding 1,000 km/h. Demand concentrates in India and China, where efficient, high-speed movement of goods and people is a primary objective.
- Levitation System:Utilizing magnetic forces, these systems suspend the pods above the track, eliminating friction and enabling ultra-high speeds with minimal energy consumption. Project consortiums in India and South Korea are incorporating advanced passive magnetic levitation designs into their feasibility studies, seeking to lower operational costs.
- Vacuum Technology:This segment includes the pumps and seals necessary to maintain the near-vacuum environment within the hyperloop tubes, significantly reducing air resistance.
- Control System:This comprises the sophisticated software and hardware managing pod movement, safety protocols, and overall system operations across the network.
- Infrastructure Components:This category covers the physical structures such as tubes, stations, and guideways that form the backbone of any hyperloop network.
Established volume favors Infrastructure Components; emerging adoption favors Levitation System.
Application:
Application focus within the Asia Pacific hyperloop market highlights how the technology is being adapted to address various transportation needs.
- Freight Transit:This application involves dedicated pods for high-speed cargo movement, designed to alleviate supply chain bottlenecks and expedite goods delivery across long distances. Logistics firms in China and India are exploring hyperloop for high-speed cargo transport, driven by intense pressure to resolve supply chain inefficiencies.
- Passenger Transport:Envisioned as a future mode of inter-city travel, this application aims to drastically reduce journey times between major urban centers using passenger-carrying pods. South Korea and India are conducting advanced feasibility studies, focusing on the potential for reduced inter-city travel times.
- Emergency Services:Hyperloop systems could facilitate rapid deployment of emergency personnel and critical supplies, particularly in disaster relief scenarios or urgent medical transfers.
- Tourism:This application explores hyperloop's potential to create unique travel experiences and connect tourist destinations with unprecedented speed.
- Logistics:Encompassing the broader movement and management of goods, this application leverages hyperloop for efficient, time-sensitive deliveries within complex supply chains.
The Freight Transit application is gaining significant near-term traction, while Passenger Transport represents the long-term strategic vision for hyperloop developers.
End User:
The customer type for hyperloop technology varies significantly, reflecting the diverse stakeholders involved in its development and deployment across Asia Pacific.
- Transportation Authorities:These government bodies are responsible for planning, regulating, and overseeing the development of national transportation infrastructure, including hyperloop projects. National transport ministries in India and South Korea are establishing dedicated safety and certification protocols, indicating their direct involvement.
- Logistics Companies:These firms operate supply chains and cargo networks, seeking hyperloop solutions to optimize delivery times and reduce operational costs for goods movement. Logistics companies in China are actively exploring hyperloop as a solution for high-speed cargo transport.
- Emergency Responders:Organizations involved in public safety and disaster management could utilize hyperloop for rapid transit of personnel and equipment during crises.
- Travel Agencies:These businesses could integrate hyperloop services into their offerings, providing faster and more novel travel options for tourists and business travelers.
- Infrastructure Developers:Companies specializing in the construction and management of large-scale infrastructure projects are key partners in building hyperloop networks.
Government-led infrastructure ambitions are largely driven by Transportation Authorities, while Logistics Companies are providing commercial impetus for freight applications.
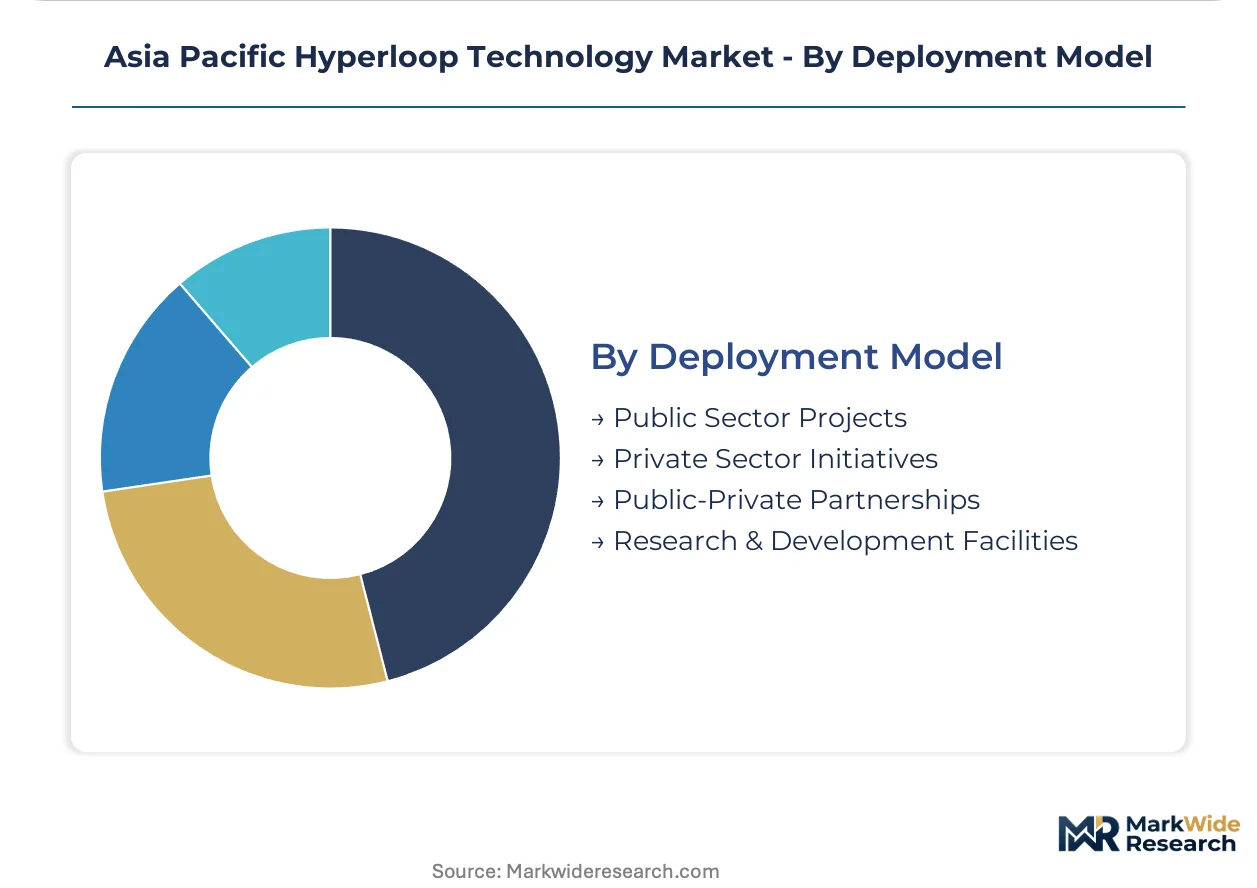
Deployment Model:
The financing structure of hyperloop projects reflects the significant capital requirements and strategic importance of this emerging technology.
- Public-Private Partnerships:These models combine government funding and oversight with private sector investment and operational expertise, sharing risks and rewards for large-scale infrastructure projects. This definitive shift toward PPP financing is most visible in India, where projects integrate into the national infrastructure pipeline.
- Public Sector Projects:These initiatives are primarily funded and managed by government entities, often driven by national strategic goals such as economic development or carbon reduction targets. China's dual carbon goals provide top-down impetus for project development under public sector initiatives.
- Private Sector Initiatives:These projects are financed and developed predominantly by private companies, often seeking to establish commercial viability and technological leadership.
- Research & Development Facilities:These entities focus on advancing hyperloop technology through testing, prototyping, and innovation, often supported by a mix of public and private funding.
Public-Private Partnerships are becoming the dominant model for new hyperloop projects, while Research & Development Facilities drive foundational technological maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transportation Authorities and Logistics Companies are driving hyperloop development in the Asia Pacific region. Their interest stems from national infrastructure ambitions and critical supply chain pressures. This dual focus defines regional investment patterns and project prioritization.
India
India's demand for hyperloop technology centers on its national infrastructure pipeline, aiming to drastically reduce inter-city travel times. The country's national transport ministries are actively establishing dedicated safety and certification protocols. Projects in India integrate into the national infrastructure pipeline, attracting long-term investors for large-scale transport initiatives.
China
China's hyperloop demand is driven by intense pressure to resolve supply chain bottlenecks, exploring high-speed cargo transport. The nation's dual carbon goals provide top-down impetus for project development. Logistics firms in China are actively exploring hyperloop as a solution for high-speed cargo movement, aligning with national standards like GB standards for component manufacturing.
South Korea
South Korea exhibits strong demand for hyperloop to enable reduced inter-city travel times, supported by advanced feasibility studies. National transport ministries are establishing comprehensive safety and certification protocols for hyperloop systems. Project consortiums in South Korea are incorporating advanced passive magnetic levitation designs into their feasibility studies, focusing on operational efficiency.
Australia
Australia presents demand for freight-first hyperloop applications, offering a path to earlier revenue generation. National transport authorities are evaluating commercial contracts for these initial freight systems. Transpod Inc. focuses on freight-first applications in countries like Australia to secure initial commercial contracts, demonstrating a pragmatic market entry strategy.
Indonesia
Indonesia's growing megacities drive demand for inter-city hyperloop links to alleviate severe traffic congestion. National urban planning initiatives consider high-speed transit solutions for future infrastructure. Megacities like Jakarta present future opportunities for hyperloop links, addressing critical urban mobility challenges within the region.
Asia Pacific Hyperloop Technology Market Key Industry Players
Channel-controlling players compete with product-specialist players across the Asia Pacific hyperloop technology market. The market structure exhibits fragmentation, with diverse entities pursuing distinct strategic archetypes. Consortiums with deep sovereign and institutional backing represent one key archetype, alongside technology partners and freight-first specialists. Dominant competitive moves include forming strategic public-private partnerships and expanding geographic reach into nascent markets.
Companies representing specific strategic archetypes include Virgin Hyperloop, which positions itself as a technology partner within larger infrastructure bids. Hyperloop Transportation Technologies leverages a crowd-collaboration approach, de-risking its capital structure through collective innovation. Transpod Inc. exemplifies a freight-first specialist, focusing on securing initial commercial contracts for cargo applications in target countries.
| Leading Market Players |
|---|
| Virgin Hyperloop |
| Hyperloop Transportation Technologies |
| Tesla's Boring Company |
| Dinclix Groundworks |
| Hyperloop India |
| Transpod Inc. |
| Space Exploration Technologies Corp |
| Zeleros Hyperloop |
| Hardt Global Mobility |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly around safety and certification, determine both pricing tier spreads and the supply chain shape for hyperloop components. This nascent market navigates high capital expenditure requirements alongside evolving technical standards.
Pricing Analysis
Cost-plus contract models, often indexed to sovereign infrastructure project budgets, define hyperloop system pricing. Price differentiation stems from the technological sophistication of Propulsion and Levitation Systems and the project's customization level. Pricing softness affects foundational infrastructure components due to the immense upfront capital costs required for tube networks. Logistics companies exhibit higher price sensitivity compared to national transportation authorities, who prioritize long-term strategic value over immediate cost savings.
Supply Chain Analysis
Component contract manufacturing largely concentrates in China, India, and South Korea, reflecting existing industrial bases and emerging hyperloop development. The supply chain draws from advanced materials for vacuum tubes and precision electronics for control systems. A lack of harmonized safety and certification standards across the Asia Pacific region presents a structural supply chain risk. Distribution typically runs through direct engagement with government-backed consortiums and infrastructure development firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific hyperloop market stands at a platform-economics inflection, driven by the imperative for seamless smart city integration and robust interoperability standards.
For Market Incumbents: Entrench core intellectual property in Propulsion and Levitation Systems through continuous R&D, particularly in passive magnetic levitation. Prioritize certification investment within key regulatory frameworks like India's and South Korea's national transport ministries. Leverage deep sovereign backing by forming strategic public-private partnerships, mitigating the threat of extreme capital costs and regulatory uncertainty.
For New Entrants and Emerging Players: Southeast Asia's underpenetration in high-speed inter-city links offers a significant white-space opportunity. Target freight-first applications in countries like Australia to secure initial commercial contracts and establish a revenue base. Focus on developing modular, cost-efficient component solutions that can integrate with existing smart city platforms, offering a clear value proposition for urban mobility challenges.
For Investors and Strategic Acquirers: The establishment of national safety and certification protocols reshapes the acquisition landscape, signaling long-term market viability. Focus on acquiring technology specialists possessing proprietary intellectual property in core hyperloop systems or companies with demonstrated success in navigating complex regulatory approval pathways. Monitor government funding allocations and successful pilot project commercialization as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Core Components | Scaling production lowers unit costs for Propulsion and Levitation Systems, driving broader market adoption. |
| Joint Venture with Infrastructure Developers | Partnerships with infrastructure developers de-risk project financing and accelerate network deployment. |
| Technology Licensing for Vacuum Systems | Sharing vacuum technology IP fosters standardization and reduces engineering complexity across projects. |
| Geographic Expansion into Southeast Asia | Entering new markets like Indonesia addresses critical urban congestion and unlocks future growth. |
| Regulatory Approval Pathway Acceleration | Expediting certification processes in India and South Korea ensures faster market entry and commercialization. |
Research Approach
A standing panel of transportation authorities, logistics company executives, infrastructure developers, and hyperloop technology developers provided ongoing calibration and validation for market estimates. This approach combined primary interviews with industry stakeholders and secondary validation from national transport ministry reports, China's GB standards documents, and feasibility study reports. Bottom-up data from project announcements and top-down policy analysis informed the market sizing.
Scenario-bracketing frames the forecast framework, modeling market evolution across the analysis window. The analytical framework incorporates segmentation dimensions including Product Type, Application, End User, Deployment Model, and regional policy support. Compound annual growth rates were derived from projected adoption rates and investment trends, with government infrastructure spending and technological readiness levels serving as key forecast inputs.
Practitioners should monitor regulatory harmonization progress, capital cost fluctuations, and engineering breakthroughs in vacuum integrity for early signals of market shifts. Forecasts reflect assumptions regarding sustained government backing and continued technological maturation. Quarterly review of pilot project success rates and government funding allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
GCC Electronic Toll Collection Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
E-Scooter Sharing Market