
 Global Sorghum Seed Market | 2026-2036
Global Sorghum Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sorghum Seed Market Foresight
ISO 17025 accreditation for seed quality testing is unwinding competitive access across export corridors. Bayer CropScience leverages its trait pipeline to dominate drought-tolerant hybrid development. Corteva Agriscience anchors North American distribution through its Pioneer seed network. Syngenta AG differentiates via integrated crop protection bundles tied to proprietary genetics.
Sorghum seed comprises the reproductive propagule of Sorghum bicolor, a C4 grass species bred for grain, forage, or sweet-stalk biochemistry with germination standards typically requiring 80% minimum viability and varietal purity thresholds exceeding 98%. Hybrid seeds command premium positioning due to proprietary cytoplasmic male-sterile systems and controlled pollination infrastructure that locks in farmer repurchase cycles. Open pollininated varieties retain structural relevance across Sub-Saharan African smallholder systems where saved-seed practices and lower input costs sustain acreage. Trait architecture clusters around drought tolerance and pest resistance where molecular marker stacking accelerates breeding cycles and compresses development timelines.
FDA feed ingredient guidelines, EU REACH frameworks for novel trait registration, and Brazil's MAPA cultivar release protocols collectively shape product commercialization pathways and cross-border seed movement. Australia's OGTR governs genetically modified sorghum field trials while India's PPVFRA establishes farmer rights over traditional landraces that constrain proprietary germplasm claims. Stakeholders must monitor evolving gene-editing regulatory classifications that could recategorize CRISPR-derived drought traits outside GMO frameworks in key export destinations.
Market Dynamics
Climate volatility across major grain belts is compressing breeding timelines and forcing seed companies to prioritize drought-escape physiology over yield maximization in their trait pipelines.
Growth Catalysts
- Safrinha Crop Expansion:Brazilian livestock producers in Mato Grosso and Goiás are displacing failed second-crop corn with short-cycle sorghum varieties, creating dedicated seed demand corridors.
- EU REACH Framework Adaptation:Streamlined novel trait registration pathways for gene-edited drought tolerance are accelerating product commercialization timelines for export-oriented breeding programs.
- CrispR-Accelerated Breeding:Molecular marker stacking is compressing development cycles from eight years to four, enabling faster trait deployment against emerging pest pressures.
Market Restraints
- Phosphorus Input Volatility:Fertilizer cost spikes in Australian production zones are squeezing margins for open-pollinated variety multiplication.
- Proprietary Germplasm Concentration:Three breeding houses control cytoplasmic male-sterile systems, locking independent seed companies into licensing dependencies.
- Maize Substitution Elasticity:Feed compounders in temperate zones revert to corn when moisture conditions normalize, destabilizing sorghum seed offtake forecasts.
Strategic Opportunities
- Sub-Saharan African Smallholder Systems:Kenya and Ethiopia present white space for dual-purpose grain-forage varieties that reduce input costs through saved-seed practices.
- India's PPVFRA Flexibility:Farmer rights frameworks over traditional landraces create partnership pathways for public-private germplasm exchange models.
- Biogas Feedstock Certification:EU renewable energy mandates for agricultural biomass are opening dedicated contract production channels for sweet-stalk biochemistry lines.
Industry Challenges
- Field Trial Containment Protocols:Australia's OGTR requirements for genetically modified sorghum isolation distances are extending development timelines and inflating site costs.
- Phenotyping Talent Scarcity:Drought physiology expertise shortages in Brazil's Cerrado breeding stations are bottlenecking trait validation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sorghum Seed Market |
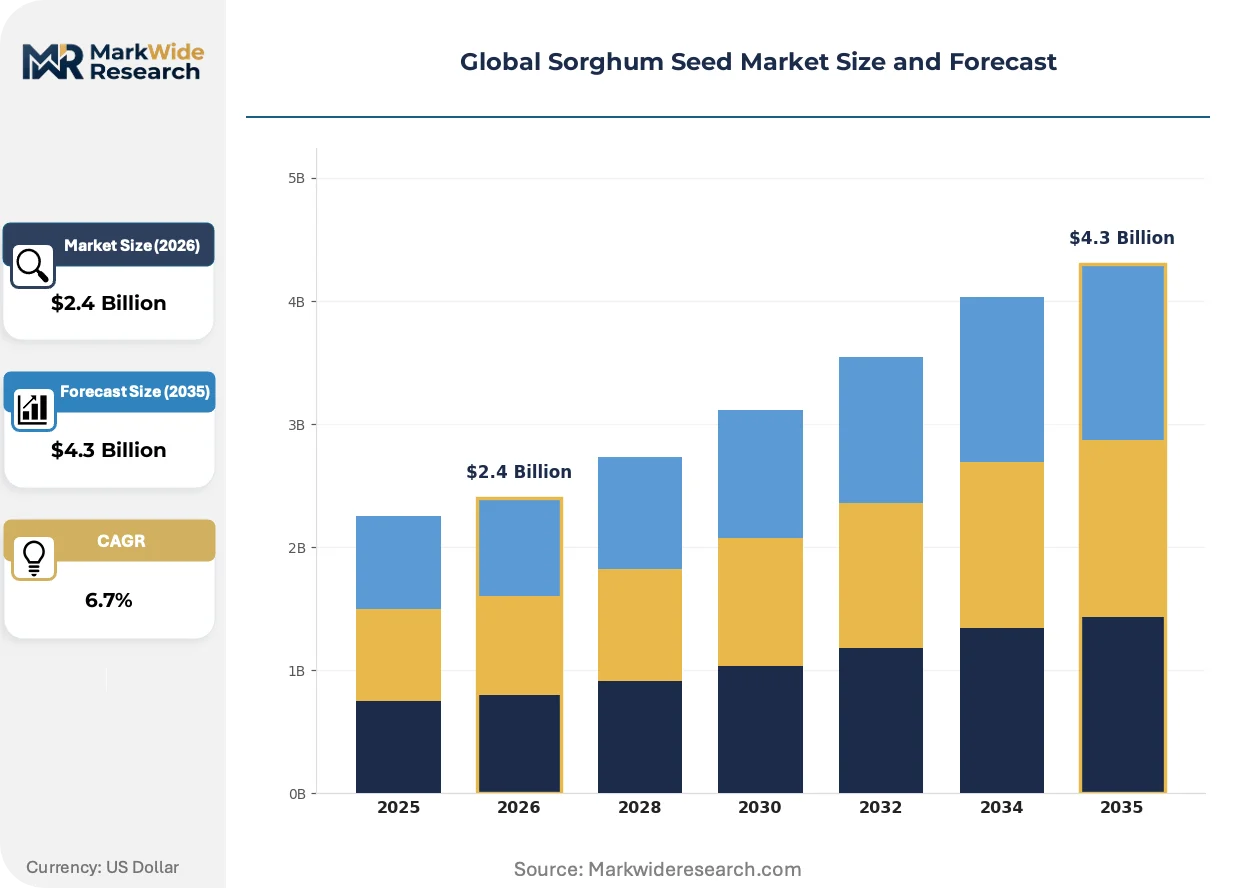
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.3 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open Pollinated Seeds, Organic Seeds, Genetically Modified Seeds Trait: Drought Tolerance, Pest Resistance, High Yield, Early Maturity, Nutritional Enhancement Application: Food Processing, Animal Feed Production, Biofuel Manufacturing, Alcohol Distillation End User: Seed Companies, Agricultural Cooperatives, Contract Farmers, Research Institutions |
| Companies Covered | KWS, Dyna-Gro Seed, Corteva Agriscience, Syngenta AG, Nufarm, Bayer CropScience, S&W Seed Co, Seed Co Limited, Advanta Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sorghum Seed Market Shifts & Advancements
Gene-editing platforms are rewriting competitive boundaries between proprietary hybrid developers and public breeding programs, while digital phenotyping infrastructure is compressing the gap between field observation and genomic selection.
Speed-breeding protocols using controlled-environment chambers and rapid generation advance are fragmenting the traditional regional breeding station model. Australian and Brazilian programs are adopting these systems to compress selection cycles. This acceleration is fragmenting competitive advantage away from germplasm depth toward bioinformatics and automation capability.
REACH framework revisions in Europe are recategorizing CRISPR-derived drought traits outside GMO classification for import purposes. This regulatory recalibration is redirecting breeding investment toward gene-editing platforms rather than transgenic approaches. Seed exporters targeting EU feed markets are restructuring product portfolios to exploit this pathway.
Livestock integrators in Brazil are consolidating procurement through direct contract arrangements with seed multipliers, bypassing traditional distribution cooperatives. This channel compression is concentrating volume commitments among fewer breeding relationships. The pattern is most pronounced in Mato Grosso's integrated poultry and beef production zones.
Global Sorghum Seed Market Segmentation
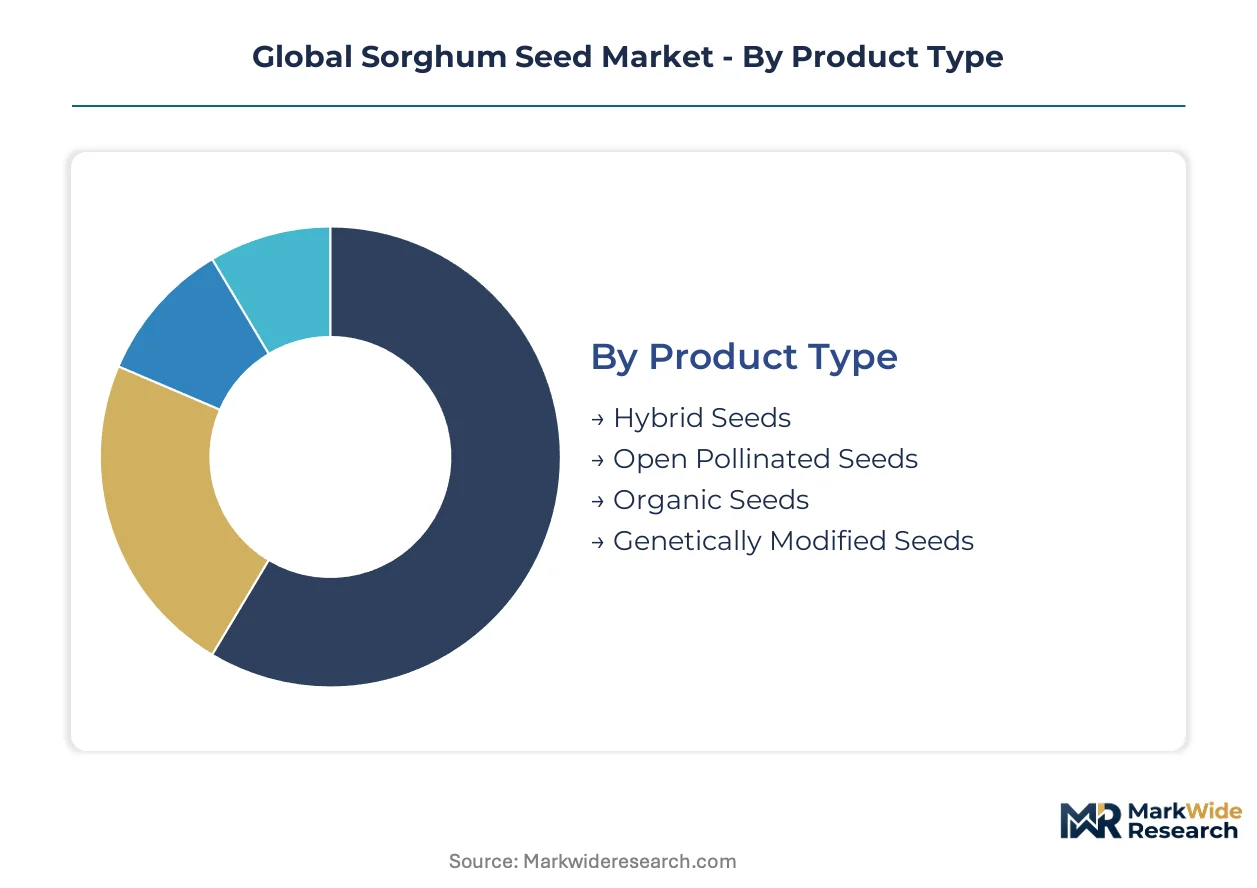
Sorghum seed segmentation reflects divergent regulatory pathways for proprietary versus saved-seed systems. Trait architecture and distribution channels reshape competitive positioning across drought-prone production belts.
Product Type:
EU REACH frameworks and Australia's OGTR create divergent commercialization corridors for proprietary versus conventional genetics.
- Hybrid Seeds:Cytoplasmic male-sterile systems enable controlled pollination with germination standards exceeding 80% viability. Bayer CropScience and Corteva Agriscience dominate Brazilian Cerrado and North American distribution through locked-in farmer repurchase cycles driven by drought-escape physiology priorities.
- Open Pollinated Seeds:Farmer-saved propagation sustains structural relevance across Sub-Saharan African smallholder systems where input cost minimization overrides yield maximization. Kenya and Ethiopia retain acreage through varietal purity thresholds exceeding 98% without licensing dependencies.
- Organic Seeds:Certification under EU organic farming standards restricts synthetic input use during multiplication phases.
- Genetically Modified Seeds:Brazil's MAPA cultivar release protocols and India's PPVFRA farmer rights constraints limit proprietary germplasm claims across key export destinations.
Hybrid seeds handle the majority of throughput; organic seeds are expanding most quickly on share.
Trait:
Cost tiers stratify between molecular marker-stacked premium hybrids and conventional selection programs.
- Drought Tolerance:CRISPR-accelerated breeding compresses development timelines from eight years to four through rapid generation advance protocols. Australian breeding stations prioritize drought-escape physiology as climate volatility forces trait pipeline reallocation across the Cerrado and Sub-Saharan zones.
- Pest Resistance:Stacked molecular markers target emerging biotype pressures in Brazilian safrinha production corridors. Speed-breeding infrastructure fragments competitive advantage toward bioinformatics capability away from germplasm depth alone.
- High Yield:Selection indices prioritize grain output under irrigated conditions in temperate feed markets.
- Early Maturity:Short-cycle varieties displace failed second-crop corn in Mato Grosso and Goiás livestock integration zones.
- Nutritional Enhancement:Sweet-stalk biochemistry lines access EU renewable energy mandates for biogas feedstock certification channels.
Drought tolerance commands the dominant R&D allocation; nutritional enhancement is climbing the fastest on commercial priority.
Application:
Volume concentration follows livestock integrator procurement consolidation in Brazil's integrated poultry and beef zones.
- Animal Feed Production:Compounders in temperate zones revert to corn when moisture normalizes, creating demand elasticity that destabilizes sorghum seed offtake forecasts. Brazilian integrators in Mato Grosso now contract directly with seed multipliers, bypassing traditional distribution cooperatives.
- Food Processing:White sorghum varieties for gluten-free product lines concentrate in Ethiopian and Sudanese export corridors.
- Biofuel Manufacturing:EU renewable energy directives for agricultural biomass open dedicated contract production for high-brix stalk chemistry.
- Alcohol Distillation:Chinese baijiu producers and Nigerian traditional fermentation systems sustain demand for specific endosperm texture profiles.
Animal feed production absorbs the largest volume share; biofuel manufacturing is gaining share fastest on policy mandate expansion.
End User:
Customer type determines margin capture through licensing structures versus saved-seed cost avoidance.
- Seed Companies:Three breeding houses control cytoplasmic male-sterile systems, locking independent multipliers into licensing dependencies. ISO 17025 accreditation requirements for quality testing unwind competitive access across export corridors.
- Agricultural Cooperatives:Brazilian distribution cooperatives face channel compression as livestock integrators consolidate procurement relationships directly with breeding programs.
- Contract Farmers:Sweet-stalk biochemistry lines for EU biogas certification require dedicated production agreements with specified isolation distances.
- Research Institutions:Australia's OGTR field trial containment protocols extend development timelines for genetically modified trait validation.
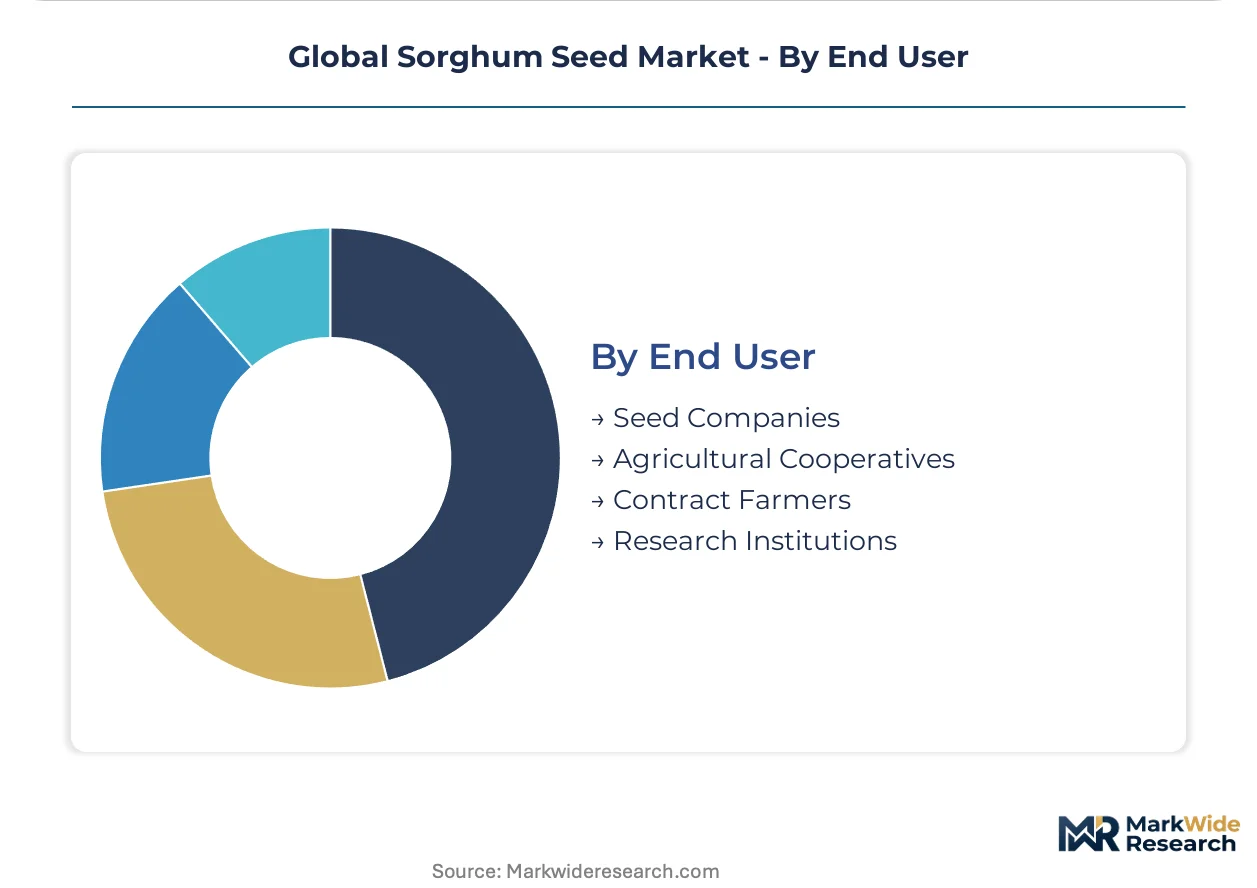
Seed companies retain the dominant procurement volume; contract farmers are expanding most quickly on dedicated channel formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed biofuel mandates and drought-resilience incentives are redirecting breeding investment toward specific national production corridors. National regulators are recalibrating gene-editing classifications to accelerate trait commercialization timelines. Seed procurement patterns concentrate in livestock integration zones and expanding safrinha production belts.
Brazil
Safrinha sorghum displaces failed second-crop corn across Mato Grosso and Goiás as livestock integrators consolidate direct procurement relationships. ANVISA and MAPA cultivar release protocols govern proprietary germplasm commercialization pathways. The Cerrado expansion zones anchor dedicated seed demand corridors for short-cycle varieties.
United States
Livestock producers in the Southern Plains seek drought-resilient grain alternatives as irrigation constraints intensify. FDA feed ingredient guidelines shape product registration requirements for export-oriented breeding programs. Texas and Kansas breeding stations prioritize drought-escape physiology in hybrid development pipelines.
Australia
Climate volatility across grain belts compresses breeding timelines toward rapid generation advance protocols. The OGTR governs genetically modified sorghum field trial containment requirements and isolation distances. Queensland production zones face phosphorus input cost volatility squeezing open-pollinated variety multiplication margins.
India
Smallholder systems in Maharashtra and Karnataka sustain acreage through saved-seed practices and lower input costs. The PPVFRA establishes farmer rights over traditional landraces that constrain proprietary germplasm claims. Public-private germplasm exchange models create partnership pathways for dual-purpose grain-forage varieties.
Ethiopia
White sorghum varieties for gluten-free export corridors concentrate demand in highland production systems. National agricultural research institutes coordinate varietal release protocols without restrictive licensing frameworks. The Rift Valley and Oromia regions present white space for open-pollinated seed systems reducing input dependency.
Global Sorghum Seed Market Competitive Landscape
Player mix skews toward integrated agriscience conglomerates with captive trait pipelines and distribution infrastructure. Three breeding houses control cytoplasmic male-sterile systems, locking independent multipliers into licensing dependencies. Strategic archetypes include proprietary hybrid developers, open-pollinated variety specialists, and regional distribution integrators. Competitive moves center on gene-editing platform licensing and direct livestock integrator contracting.
Among the integrated agriscience tier, Bayer CropScience, Corteva Agriscience, and Syngenta AG exemplify the proprietary hybrid development archetype. These entities occupy positions defined by controlled pollination infrastructure and locked-in farmer repurchase cycles. KWS and Advanta Seeds represent the mid-scale breeding house category with regional distribution anchoring. S&W Seed Co sits within the specialized multiplier segment focused on contract production relationships. Each archetype faces pressure from speed-breeding protocol adoption and digital phenotyping capability gaps.
| Leading Market Players |
|---|
| KWS |
| Dyna-Gro Seed |
| Corteva Agriscience |
| Syngenta AG |
| Nufarm |
| Bayer CropScience |
| S&W Seed Co |
| Seed Co Limited |
| Advanta Seeds |
| Others |
Supply & Pricing Matrix
Capacity utilization at Australian and Brazilian breeding stations shapes supply concentration and establishes price floors for hybrid seed multiplication. Scale economies in controlled-environment infrastructure compress per-unit costs for major breeding houses while marginalizing independent multipliers lacking rapid generation advance capability.
Pricing Analysis
Certification level creates the primary spread between ISO 17025-accredited premium hybrids and uncertified open-pollinated varieties. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm licensing depth, trait stacking complexity, and after-sales agronomic support bundling. Cost compression in standard-tier hybrids is intensifying because phosphorus input volatility squeezes margins for open-pollinated variety multiplication. Smallholder systems in Sub-Saharan Africa exhibit highest price sensitivity, while Brazilian livestock integrators demonstrate lowest sensitivity due to direct contract arrangements that lock in volume commitments.
Supply Chain Analysis
Just-in-time inventory preferences dominate Brazilian safrinha corridors where short-cycle variety demand surges unpredictably after corn failure assessments. Geographic supply concentrates in Australia, Brazil, and India where breeding infrastructure clusters around drought-prone production belts. Raw material dependencies center on cytoplasmic male-sterile seed parent lines, molecular marker reagents, and phosphorus-based fertilizers. Single-source vulnerability in proprietary germplasm licensing creates structural risk as three breeding houses control essential pollination systems. Distribution runs through direct livestock integrator contracting in Mato Grosso and traditional agricultural cooperative networks in North American temperate zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene-editing regulatory recalibration across EU REACH frameworks and Australia's OGTR creates a high-growth disruption window as CRISPR-derived drought traits accelerate commercialization timelines outside GMO classification.
For Market Incumbents: Fortify proprietary germplasm control by deepening backward integration into rapid generation advance infrastructure and securing ISO 17025 accreditation for quality testing protocols. Emerging biotype pressures in Brazilian safrinha corridors threaten trait obsolescence cycles; capacity addition in Queensland breeding stations anchors drought-escape physiology pipelines against climate volatility compression. For New Entrants and Emerging Players: Differentiate on public-private germplasm exchange models leveraging India's PPVFRA farmer rights frameworks to access traditional landraces without licensing dependencies. White space concentrates in Sub-Saharan African smallholder systems for dual-purpose grain-forage varieties and EU biogas feedstock certification channels for sweet-stalk biochemistry lines. Go-to-market execution should prioritize direct contract production arrangements with livestock integrators bypassing cooperative intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among breeding houses with locked-in farmer repurchase cycles through cytoplasmic male-sterile system control. Long-term viability over the projection horizon favors acquisition targets with speed-breeding protocol adoption and digital phenotyping capability. Watch for regulatory recategorization of gene-edited traits in additional export destinations as the primary inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Platform Licensing | REACH framework revisions outside GMO classification redirect R&D investment toward CRISPR-derived drought traits. |
| Direct Livestock Integrator Contracting | Brazilian poultry and beef production zones in Mato Grosso bypass traditional distribution cooperatives for volume consolidation. |
| Speed-Breeding Infrastructure Deployment | Controlled-environment chambers fragment competitive advantage toward bioinformatics capability away from germplasm depth alone. |
| ISO 17025 Quality Accreditation | Seed quality testing certification unwinds competitive access across export corridors for uncertified multipliers. |
| Public-Private Germplasm Exchange | India's PPVFRA farmer rights frameworks create partnership pathways constraining proprietary claims over traditional landraces. |
Research Methodology
Operator-level perspectives from breeding program directors, seed multiplication contractors, livestock procurement managers, and regulatory affairs specialists anchored the qualitative base. Primary interview data combined with secondary validation from MAPA cultivar release filings, OGTR field trial registers, EU REACH substance databases, and FAO production statistics. Bottom-up acreage estimates and top-down value chain assessments underwent triangulation against trade flow records and breeding house capacity disclosures.
Sensitivity analysis tested forecast robustness across alternative regulatory scenarios for gene-edited trait classification. The analytical framework modeled segmentation dimensions including product type, trait architecture, application end-use, and customer archetype across the projection horizon. CAGRs derived from trend extrapolation of historical adoption curves adjusted for policy mandate expansion and climate volatility intensification. Industry-specific inputs incorporated safrinha crop displacement elasticity and biogas feedstock certification pipeline formation.
The analysis sits within stated boundaries; outcomes outside sustained EU renewable energy mandate expansion or accelerated OGTR approval timelines would require recalibration. Forecasts reflect assumptions regarding regulatory stability for cross-border seed movement and phosphorus input cost normalization. Revision becomes warranted when gene-editing classification thresholds in major export destinations cross policy inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Cannabis Seeds Market
Seeds
Garden Seeds Market
Seeds
North America Chia Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
Europe Quinoa Seed Market
Seeds
North America Tomato Seed Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Global Sports Turf Seed Market
Seeds
Uganda Seeds Market
Seeds
Poppy Seed Market
Seeds
Ghana Seed Extract Market
Seeds
Asia-Pacific Seed Market
Seeds
North America Seeds Market
Seeds
Commercial Seed Market
Seeds
Thailand Seed Market
Seeds
Global Vegetable Seed Market