
 North America Managed Services Market | 2026-2036
North America Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Managed Services Market Analytics
The shift from in-house IT operations toward fully outsourced managed infrastructure is realigning how enterprises procure technology capabilities across North America. IBM anchors substantial presence through its hybrid cloud management portfolio and decades of enterprise relationships. Microsoft competes aggressively via Azure Arc and endpoint management tools that unify multi-cloud environments. Cisco Systems dominates network-centric managed security with integrated SASE offerings that reduce vendor sprawl for distributed workforces.
North America Managed Services encompasses the ongoing administration, monitoring, and optimization of enterprise IT infrastructure, applications, and security environments by third-party specialists operating under contractual service-level agreements with defined uptime, response-time, and compliance parameters. These arrangements deliver continuous operational oversight without requiring clients to maintain equivalent internal technical depth or around-the-clock staffing. Cloud Services within the Service Type dimension is expanding fastest as organizations repatriate selective workloads while retaining cloud-native architectures. Hybrid deployment models command premium pricing due to orchestration complexity and the scarcity of engineers credentialed across both legacy on-premises stacks and containerized cloud platforms. Large Enterprises within the End User category currently generate the deepest margin pools, though SME adoption is accelerating through standardized, pre-configured service tiers.
FCC guidelines on telecommunications reliability, HIPAA security rule enforcement by the Department of Health and Human Services, and SEC cybersecurity disclosure requirements collectively elevate compliance-driven demand for audited, certified managed services providers. NIST frameworks and state-level data privacy statutes in California and New York further fragment the regulatory landscape, compelling providers to maintain jurisdiction-specific compliance architectures. Stakeholders must evaluate whether their current provider portfolios can absorb emerging AI governance obligations and quantum-resistant encryption mandates without service disruption or cost pass-through.
Market Dynamics
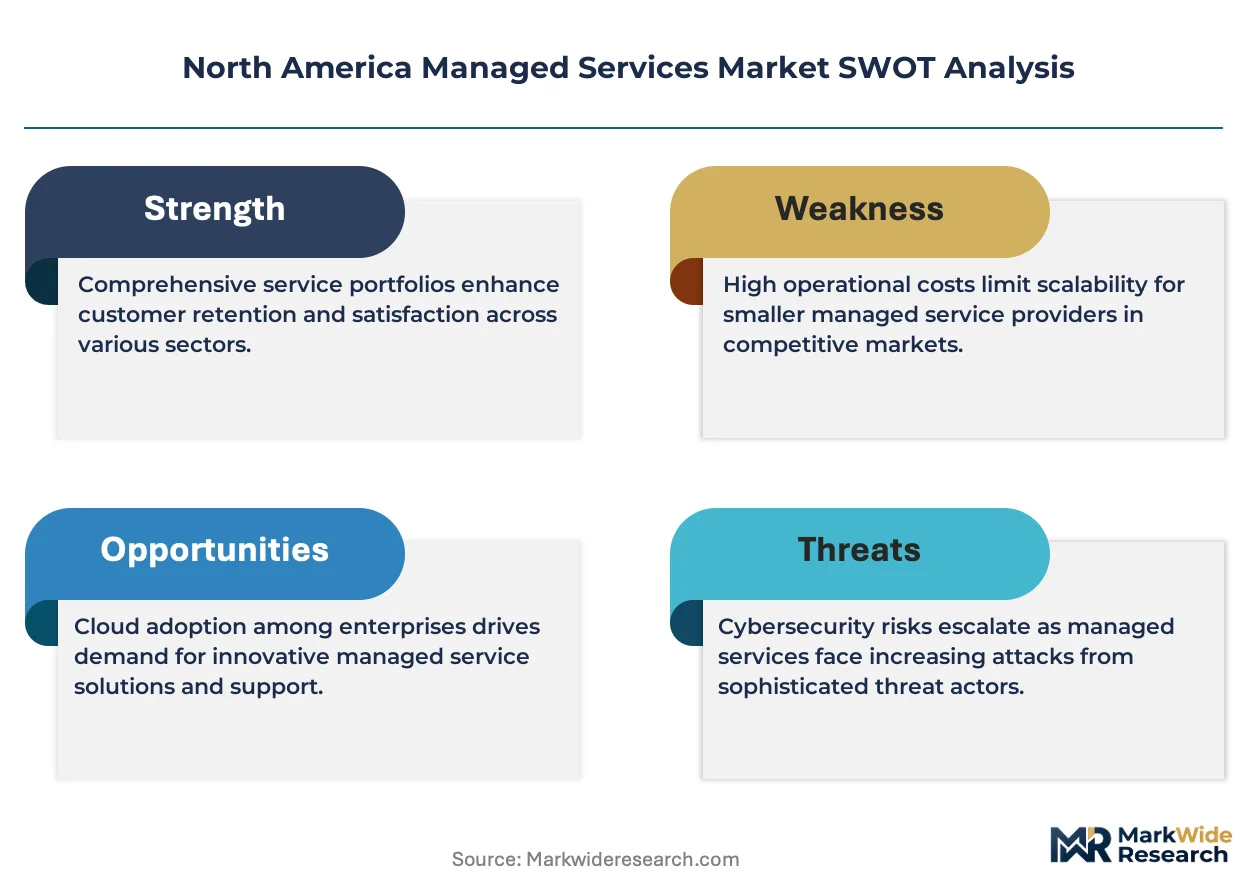
Healthcare providers across the United States are outsourcing IT infrastructure management to navigate escalating HIPAA compliance complexity, compressing procurement cycles and elevating certified managed services providers above uncredentialed competitors.
Growth Catalysts
- HIPAA Security Rule enforcement:The Department of Health and Human Services has intensified audit frequency, compelling healthcare systems to engage audited MSPs with documented security architectures rather than maintaining equivalent internal capabilities.
- Zero-trust security mandates:Mid-market enterprises are accelerating procurement of integrated SASE offerings to secure distributed workforces, displacing fragmented point-solution stacks.
- Cloud migration imperatives:Financial services corridors spanning New York, Chicago, and Charlotte are repatriating selective workloads while retaining cloud-native architectures, generating demand for hybrid orchestration specialists.
Market Restraints
- Engineer scarcity:The shortage of professionals credentialed across both legacy on-premises stacks and containerized cloud platforms commands premium compensation, compressing provider margins.
- Regulatory fragmentation:NIST frameworks and state-level data privacy statutes in California and New York force providers to maintain jurisdiction-specific compliance architectures, elevating operational overhead.
- Input cost volatility:Specialized cybersecurity tooling and threat intelligence subscriptions face renewal pricing pressure, complicating multi-year contract structuring.
Strategic Opportunities
- AI governance preparation:Emerging algorithmic accountability obligations create first-mover advantage for MSPs building audit-ready AI operations centers before mandates crystallize.
- Quantum-resistant encryption migration:Post-quantum cryptographic standards adoption by NIST opens service lines for cryptographic inventory and transition management.
- SME standardization:Pre-configured service tiers targeting mid-market enterprises currently underserved by customized enterprise offerings represent expansion white space.
Industry Challenges
- Multi-cloud orchestration complexity:Engineers must simultaneously manage Azure Arc, native AWS tooling, and Google Cloud Platform environments, stretching training pipelines and certification timelines.
- Legacy system integration friction:Mainframe and AS/400 environments in financial services require specialized bridging expertise that conflicts with cloud-native hiring profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Managed Services Market |
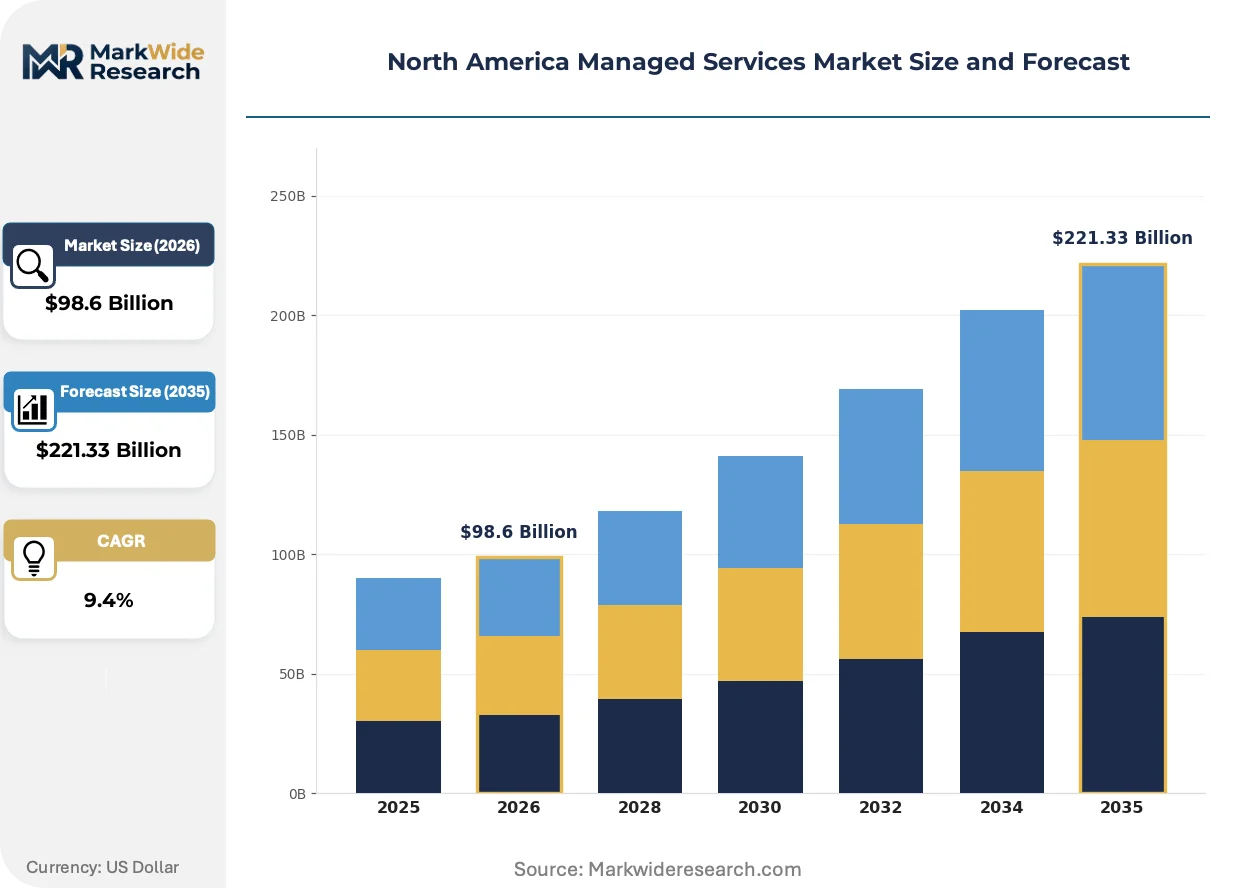
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Management, Network Security, Cloud Services, Data Backup Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote Management End User: SMEs, Large Enterprises, Government, Non-Profit Organizations Industry Vertical: Healthcare, Finance, Retail, Education |
| Companies Covered | Cisco Systems, Fujitsu, Accenture, DXC Technology, HCL Technologies, IBM, Hewlett Packard Enterprise, Microsoft, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Managed Services Market Evolving Landscape
Service delivery architectures are fragmenting from centralized data center models toward distributed edge-to-cloud fabrics, rewiring how providers architect uptime guarantees and security perimeters.
Edge computing infrastructure is decentralizing workload placement decisions. Manufacturing facilities and retail distribution centers are deploying micro-data centers locally to process latency-sensitive telemetry, reducing backhaul dependence on hyperscale regions. This topology is decentralizing managed services delivery models toward hub-and-spoke architectures with localized response capabilities.
SEC cybersecurity disclosure requirements are mandating incident reporting timelines that compress breach notification windows. Publicly traded enterprises must now document material cybersecurity events within four business days, elevating 24/7 security operations center retention from optional to essential. Financial services issuers are restructuring vendor agreements to embed guaranteed response-time clauses with penalty structures.
Consumption-based pricing models are displacing fixed-fee arrangements in mid-market procurement. Buyers are negotiating metered billing tied to actual endpoint counts and ticket volumes rather than contracted seat minimums. This behavioral shift is most visible in technology and professional services verticals where CFOs demand cost elasticity aligned with headcount fluctuations.
North America Managed Services Market Segmentation
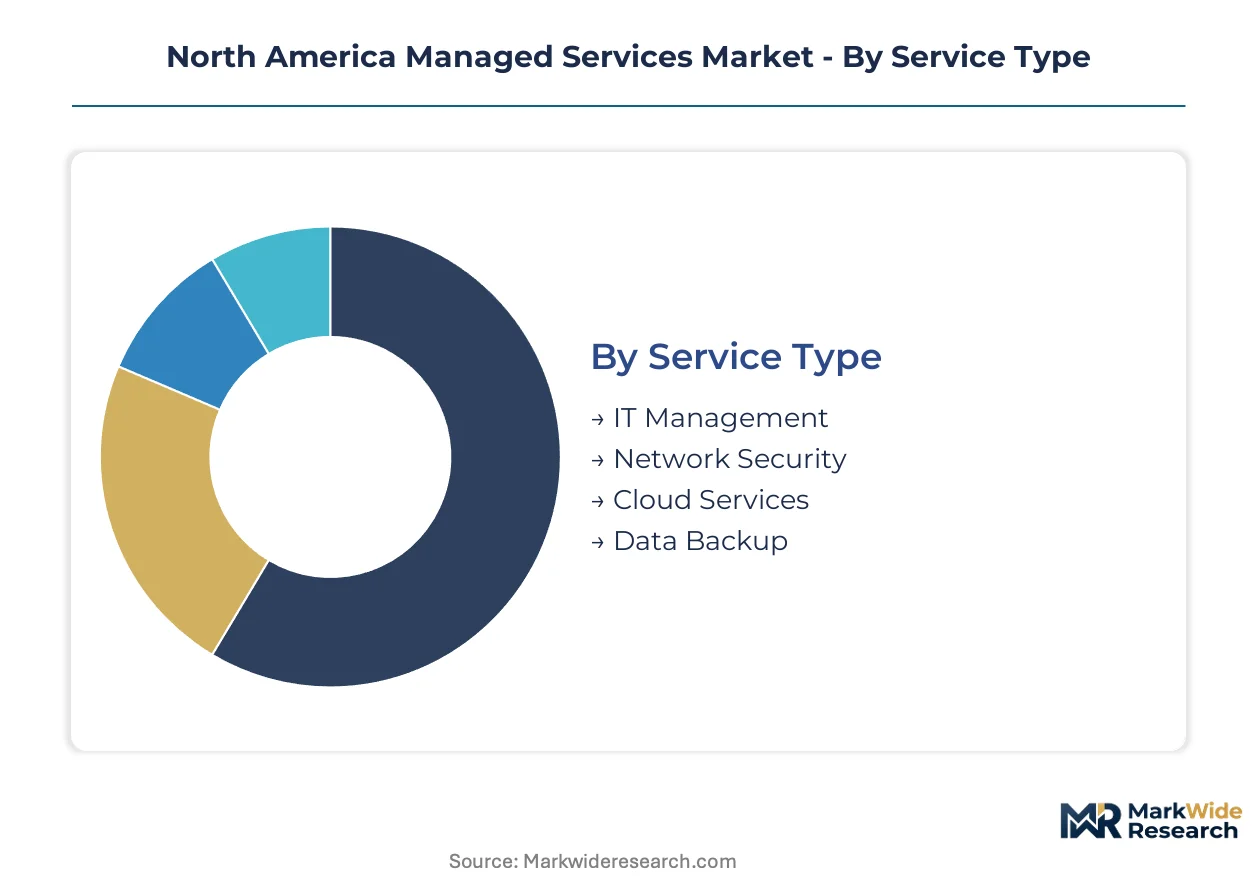
Managed services procurement patterns diverge sharply across integration architectures. Organizations embedding services within hybrid infrastructure stacks prioritize orchestration capabilities over standalone tool deployment.
Service Type:
Integration depth separates embedded security fabrics from standalone administrative functions in current procurement patterns.
- IT Management:Comprehensive infrastructure monitoring, patch management, and endpoint administration delivered through unified platforms. Demand concentrates in U.S. financial services corridors where operational continuity requirements compress response-time thresholds. HIPAA audit intensity elevates certified providers above uncredentialed competitors in healthcare systems.
- Cloud Services:Multi-cloud orchestration spanning Azure Arc, native AWS tooling, and containerized platforms with workload optimization. New York, Chicago, and Charlotte financial services clusters drive procurement as institutions repatriate selective workloads while retaining cloud-native architectures. Engineer scarcity across hybrid credentialing compresses provider margins.
- Network Security:Integrated SASE offerings securing distributed workforces through converged networking and security stacks.
- Data Backup:Immutable storage architectures and ransomware-resistant recovery orchestration with defined recovery-time objectives.
IT Management leads volumes today; Cloud Services is gaining share fastest.
Deployment Model:
Cost tier stratification reflects infrastructure sunk costs versus elasticity premiums in procurement decisions.
- Hybrid:Orchestration of legacy on-premises stacks alongside containerized cloud platforms requiring dual-credentialed engineering teams. Mid-market enterprises across the U.S. Southeast absorb premium pricing for workload portability between private data centers and hyperscale regions. NIST framework compliance obligations fragment architecture standardization.
- Cloud-Based:Fully outsourced infrastructure with consumption-based billing tied to actual compute and storage utilization. Technology and professional services verticals in California and New York negotiate metered arrangements replacing fixed-fee seat minimums.
- On-Premises:Managed administration of client-controlled hardware with remote monitoring overlays.
- Remote Management:Distributed workforce endpoint administration without physical infrastructure presence.
Hybrid deployments command the highest margins; Cloud-Based adoption is expanding most quickly.
End User:
Customer type determines service tier standardization versus customization depth in provider engagements.
- Large Enterprises:Customized service-level agreements with dedicated engineering pods and defined uptime guarantees. U.S. healthcare systems generate deep margin pools through 24/7 security operations center retention mandated by SEC cybersecurity disclosure timelines.
- SMEs:Pre-configured service tiers with standardized pricing and limited customization scope. Procurement acceleration through standardized offerings targets mid-market enterprises currently underserved by enterprise-customized portfolios.
- Government:FedRAMP-authorized and state-certified compliance architectures with audit documentation requirements.
- Non-Profit Organizations:Constrained budget procurement prioritizing essential uptime guarantees over advanced security orchestration.
Large Enterprises anchor revenue concentration today; SME penetration is climbing the fastest.
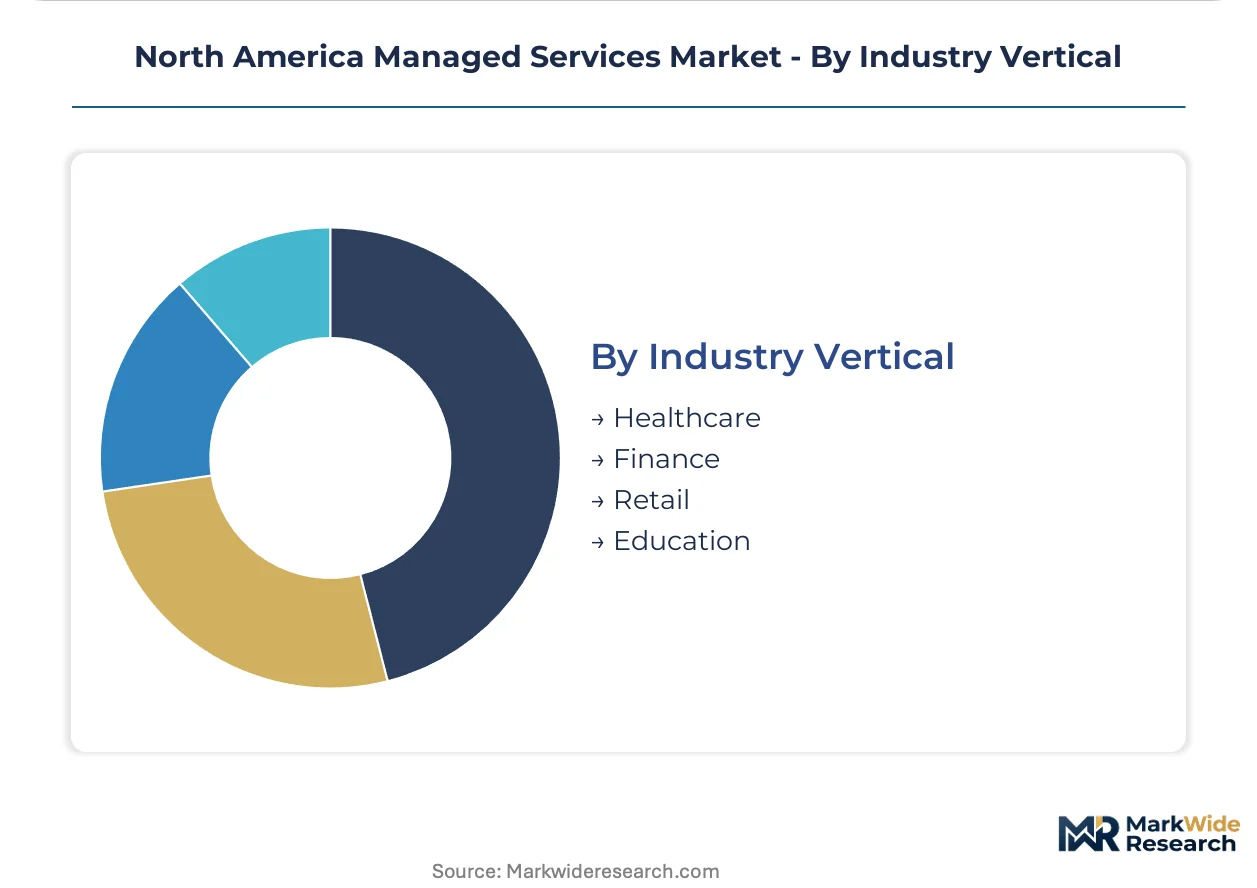
Industry Vertical:
Maturity stage differentiation separates regulated compliance-heavy procurement from elasticity-driven adoption.
- Healthcare:HIPAA Security Rule enforcement by the Department of Health and Human Services compels audited MSP engagement with documented security architectures. United States hospital systems compress procurement cycles toward certified providers.
- Finance:SEC cybersecurity disclosure requirements mandate four-business-day incident reporting, restructuring vendor agreements with guaranteed response-time penalties. Financial services issuers span New York, Chicago, and Charlotte corridors.
- Retail:Edge computing deployment for latency-sensitive inventory telemetry at distribution centers.
- Education:Constrained capital budgets favor remote management overlays over infrastructure replacement.
Healthcare leads compliance-driven procurement today; Finance is expanding most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York-Chicago-Charlotte financial services corridor anchors North American demand for managed infrastructure services, with HIPAA enforcement and SEC disclosure mandates compressing procurement timelines across healthcare and finance verticals.
United States
Hospital systems and financial services issuers dominate procurement volumes, with the Department of Health and Human Services intensifying HIPAA Security Rule audits. SEC cybersecurity disclosure requirements mandate four-business-day incident reporting, restructuring vendor agreements with guaranteed response-time penalties. The Southeast region absorbs premium pricing for hybrid workload portability between private data centers and hyperscale regions.
Canada
FedRAMP-authorized compliance architectures and provincial data residency requirements shape procurement decisions for government and healthcare entities. Health Canada regulations on digital health record security elevate certified providers above uncredentialed competitors. Toronto and Vancouver clusters concentrate financial services and technology vertical demand for multi-cloud orchestration.
Mexico
Nearshoring manufacturing expansion drives edge computing deployment for latency-sensitive production telemetry at Monterrey and Bajío Region facilities. The central bank's cybersecurity guidelines for financial institutions elevate audited MSP engagement. Mexico City Metro anchors professional services and fintech vertical adoption of consumption-based pricing models.
North America Managed Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance certifications and AI governance service lines. The vendor base stratifies across three tiers: hyperscale cloud platforms with managed service overlays, legacy infrastructure providers pivoting toward hybrid orchestration, and boutique specialists targeting HIPAA or FedRAMP compliance niches. Dominant competitive moves include strategic partnerships bridging legacy mainframe expertise with containerized platforms, and portfolio diversification into quantum-resistant encryption migration services.
Within the hybrid cloud orchestration tier, IBM and Microsoft exemplify divergent architectural approaches—IBM anchoring enterprise relationships through decades of mainframe integration, Microsoft competing via Azure Arc's multi-environment unification. Cisco Systems occupies a network-centric security position with converged SASE offerings. These three entities represent distinct archetypes: legacy infrastructure incumbents extending managed service capabilities, hyperscale platforms embedding management tooling, and networking specialists integrating security stacks.
| Leading Market Players |
|---|
| Cisco Systems |
| Fujitsu |
| Accenture |
| DXC Technology |
| HCL Technologies |
| IBM |
| Hewlett Packard Enterprise |
| Microsoft |
| AT&T |
| Others |
Value Network & Pricing Analysis
Hybrid cloud orchestration complexity simultaneously escalates cost economics and concentrates supply among dual-credentialed engineering specialists. The scarcity of professionals spanning legacy on-premises stacks and containerized platforms compresses margins while elevating premium pricing for workload portability services.
Pricing Analysis
Input-cost pass-through from specialized cybersecurity tooling and threat intelligence subscriptions intensifies pricing pressure across multi-year contract structures. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-certified healthcare offerings from uncredentialed administrative tiers. Cost compression in mid-market segments stems from consumption-based billing displacing fixed-fee arrangements. SME buyers exhibit highest price sensitivity; large financial services issuers absorb premium guarantees for four-business-day SEC-mandated incident response.
Supply Chain Analysis
Regional distribution centers in Dallas, Toronto, and Mexico City anchor hub-and-spoke delivery architectures for edge computing deployments. Engineering talent concentrates in the United States, Canada, and India, with Hyderabad and Bangalore feeding remote monitoring capabilities. Specialized credentialing dependencies rest on NIST framework compliance and state-level privacy statutes. Single-source vulnerability runs through FedRAMP-authorized certification pipelines. Distribution runs through hyperscale cloud regions with localized micro-data center partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America Managed Services operates as a geographic-arbitrage play where Canadian provincial data residency requirements and U.S. SEC disclosure mandates create divergent compliance cost structures across otherwise integrated markets.
For Market Incumbents: Anticipate quantum-resistant encryption migration demands by building cryptographic inventory capabilities before NIST standards crystallize. Consolidate position through backward integration into AI governance audit tooling to counter boutique specialists. Channel control over legacy mainframe bridging expertise defends against hyperscale platform encroachment.
For New Entrants and Emerging Players: Cloud-native partner marketplaces offer lowest-friction customer acquisition for pre-configured SME service tiers. Target mid-market enterprises in the U.S. Southeast currently underserved by customized enterprise portfolios. White-space penetration runs through consumption-based pricing models with metered endpoint billing.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-orchestration boutiques holding dual Azure-AWS certifications without dedicated healthcare vertical focus. Long-term viability hinges on absorbing AI operations center mandates before regulatory crystallization. Watch FedRAMP authorization timelines as inflection signal for government vertical expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Service Line Development | Positions providers for emerging algorithmic accountability obligations before HIPAA and SEC mandates expand. |
| Quantum-Resistant Encryption Migration | Opens cryptographic inventory and transition management revenue streams as NIST standards finalize. |
| Hybrid Cloud Orchestration Partnership | Bridges legacy mainframe expertise with containerized platforms for financial services corridor clients. |
| SME Pre-Configured Tier Launch | Captures mid-market demand elasticity through standardized pricing replacing customized enterprise engagements. |
| Edge Computing Micro-Data Center Deployment | Reduces latency for manufacturing telemetry while decentralizing managed services delivery architectures. |
Research Methodology
Multiple input streams — executive interviews with managed services providers, procurement officers at healthcare systems and financial issuers, and engineering directors at hyperscale platforms — were reconciled against secondary validation. Primary fieldwork engaged CTOs, HIPAA compliance officers, security operations center managers, and channel partners across the New York-Chicago-Charlotte corridor. Secondary sources encompassed SEC cybersecurity disclosure filings, HHS audit documentation, NIST framework publications, and hyperscaler capex disclosures. Bottom-up service-line revenue estimates and top-down addressable market calculations were triangulated.
Data-stream reconciliation across deployment model, end-user organization size, industry vertical, and regional regulatory cluster generated segment-level projections. CAGRs were derived from elasticity modeling of cloud migration velocity and compliance mandate intensity. Forecast inputs incorporated engineer credentialing pipeline constraints, FedRAMP authorization backlogs, and edge computing infrastructure deployment curves across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for post-quantum cryptographic migration would alter the outlook. Forecasts reflect stated assumptions around HIPAA audit frequency and SEC enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Europe Managed Services Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
United States Managed Services Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market