
 Indonesia Managed Services Market | 2026-2036
Indonesia Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Managed Services Market Insights
Mid-sized enterprises is unwinding from large enterprise dominance as the fastest-growing buyer archetype in Indonesian managed services. Telkomsigma leverages its state-linked heritage to anchor government and banking contracts nationwide. PT Aplikanusa Lintasarta competes through fiber backhaul density that sustains low-latency connectivity promises. Amazon Web Services Indonesia differentiates via compliance-ready cloud regions that position it for regulated sector uptake.
Managed services encompass the ongoing administration, monitoring, and optimization of IT infrastructure, applications, and security environments through third-party specialists operating under defined service-level agreements with uptime thresholds typically exceeding 99.9%. These arrangements transfer operational risk from client to provider while embedding automation tooling and predictive analytics into routine maintenance workflows. Security Management commands premium pricing as BIS mandates and breach disclosure rules harden accountability standards across finance and healthcare verticals. Cloud-Based deployment is expanding fastest among SMEs seeking to bypass capital-intensive on-premises builds, though Hybrid architectures retain dominance among large enterprises with legacy core systems.
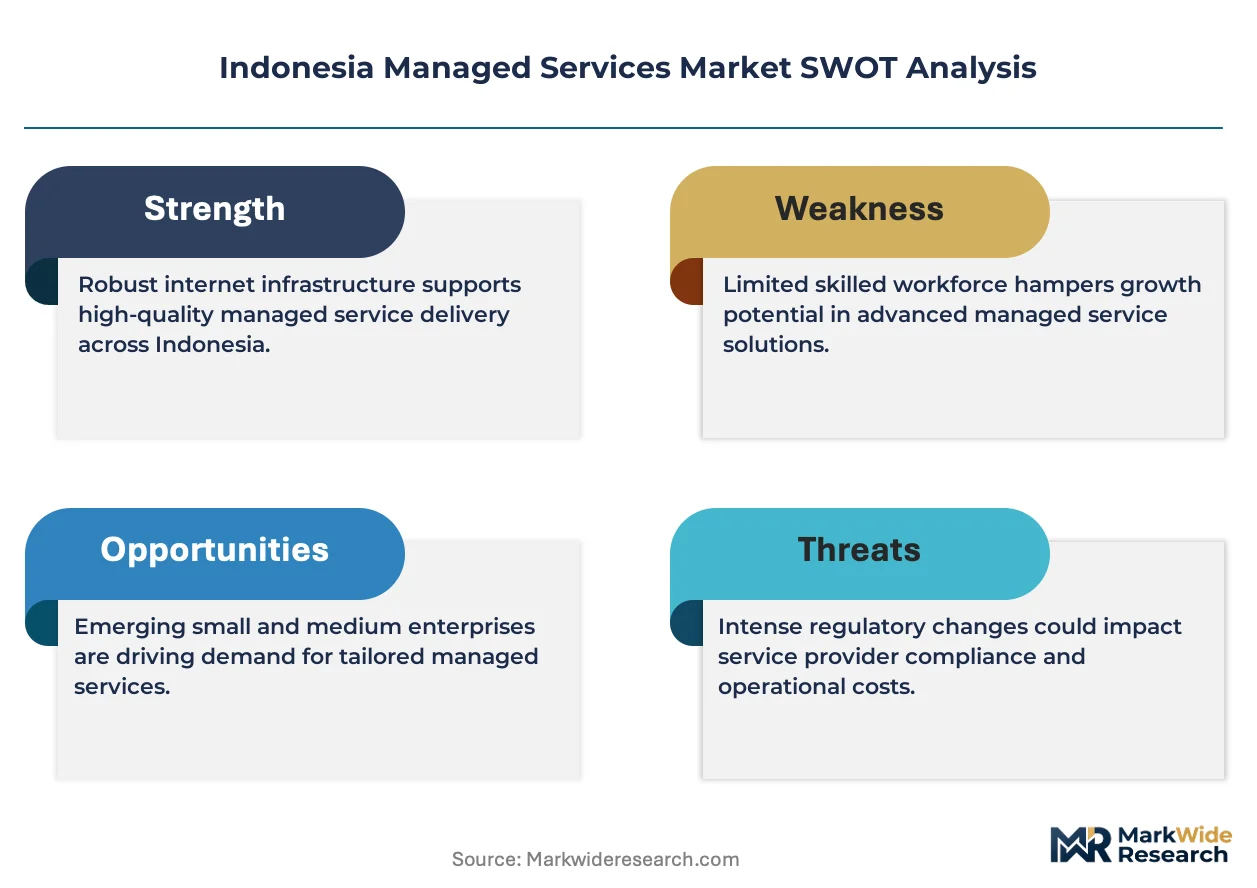
BIS cybersecurity frameworks and OJK banking technology regulations shape procurement specifications and vendor qualification criteria for Indonesian managed services buyers. The country's national data sovereignty requirements, enforced through Ministry of Communication and Informatics directives, restrict cross-border data flows and elevate local hosting compliance burdens. Stakeholders must monitor evolving localization mandates and decide between building captive delivery centers or deepening partnerships with domestically certified operators.
Market Dynamics
Cloud migration among Indonesian state-owned enterprises is compressing procurement cycles and forcing legacy infrastructure providers to restructure service delivery models around hybrid architectures.
Growth Catalysts
- OJK banking technology regulations:Indonesian banks face mandatory cybersecurity audits that expand managed security service contracts across Jakarta's financial district.
- Ministry of Communication and Informatics directives:Data sovereignty requirements restrict cross-border flows and elevate demand for locally hosted managed infrastructure.
- Mid-sized enterprises:This buyer segment is accelerating cloud adoption to bypass capital-intensive on-premises builds, creating new service tier demand.
Market Restraints
- Fiber backhaul concentration:Connectivity quality depends on limited infrastructure density outside Java, raising latency risks for remote deployments.
- Certified talent scarcity:BIS cybersecurity framework compliance requires specialized engineers whose supply trails demand in secondary cities.
- Legacy core system entrenchment:Large enterprises maintain hybrid architectures that slow full cloud migration and extend payback periods.
Strategic Opportunities
- Eastern Indonesia expansion:Underpenetrated markets beyond Java present first-mover advantages for providers establishing local delivery presence.
- Healthcare vertical penetration:Breach disclosure rules hardening accountability standards create new managed security demand from hospitals and clinics.
- Automation tooling convergence:Predictive analytics embedded into routine maintenance workflows enable premium service tier differentiation.
Industry Challenges
- Localization mandate compliance:Evolving domestic certification requirements force foreign providers to deepen partnerships with locally certified operators.
- Integration complexity:Hybrid cloud deployments demand specialized engineering to bridge legacy on-premises systems with modern cloud infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Managed Services Market |
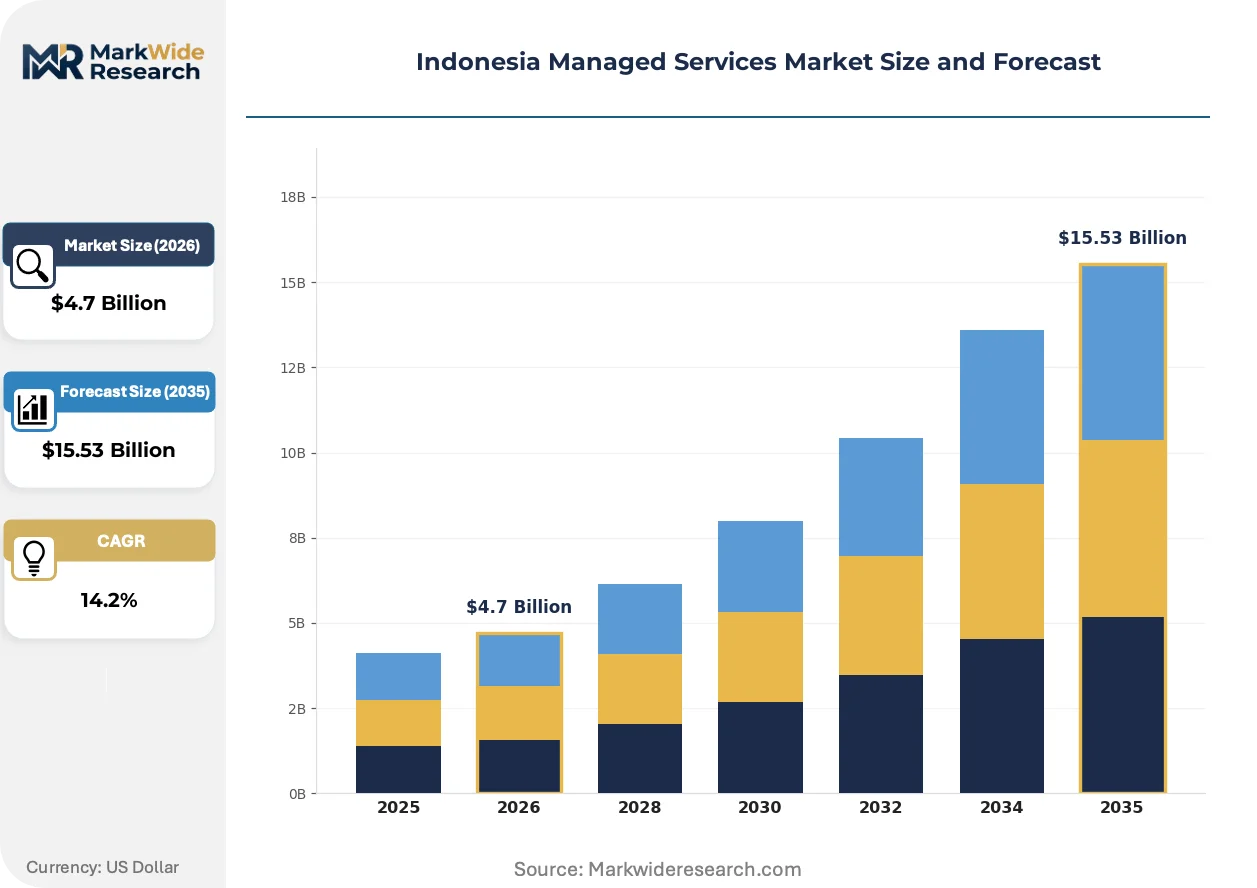
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure Management, Application Management, Network Management, Security Management End User: SMEs, Large Enterprises, Government, Healthcare Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Hosting Industry Vertical: Finance, Retail, Manufacturing, Education |
| Companies Covered | PT Cyberindo Mega Persada, PT Aplikanusa Lintasarta, Telkomsigma, PT Biznet Gio Nusantara, Amazon Web Services Indonesia, Zettagrid Indonesia, Eranyacloud, PT XL Axiata, PT VADS Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Managed Services Market Trends and Innovations
Managed service delivery in Indonesia is pivoting from reactive break-fix models toward predictive, automation-heavy operations that embed compliance by design.
AI-driven security operations centers are supplanting rule-based monitoring systems that required manual threshold configuration. Indonesian banks and state-owned enterprises are adopting these platforms within eighteen-month refresh cycles. The shift is compressing incident response times from hours to minutes while reducing headcount-dependent service margins.
BIS cybersecurity frameworks now mandate breach notification timelines and third-party audit trails for financial institutions. These rules reshape procurement specifications to favor providers with pre-certified compliance architectures. Jakarta-based banks are responding by bundling security management into broader infrastructure contracts rather than sourcing point solutions.
Mid-sized enterprises are unbundling after-sales support from hardware procurement and contracting specialized managed service providers directly. This behavior fragments the traditional vendor-captive service model that dominated Indonesian IT spending. The pattern is most visible among manufacturing firms in Surabaya and Bandung seeking predictable operational expenditure structures.
Indonesia Managed Services Market Segmentation
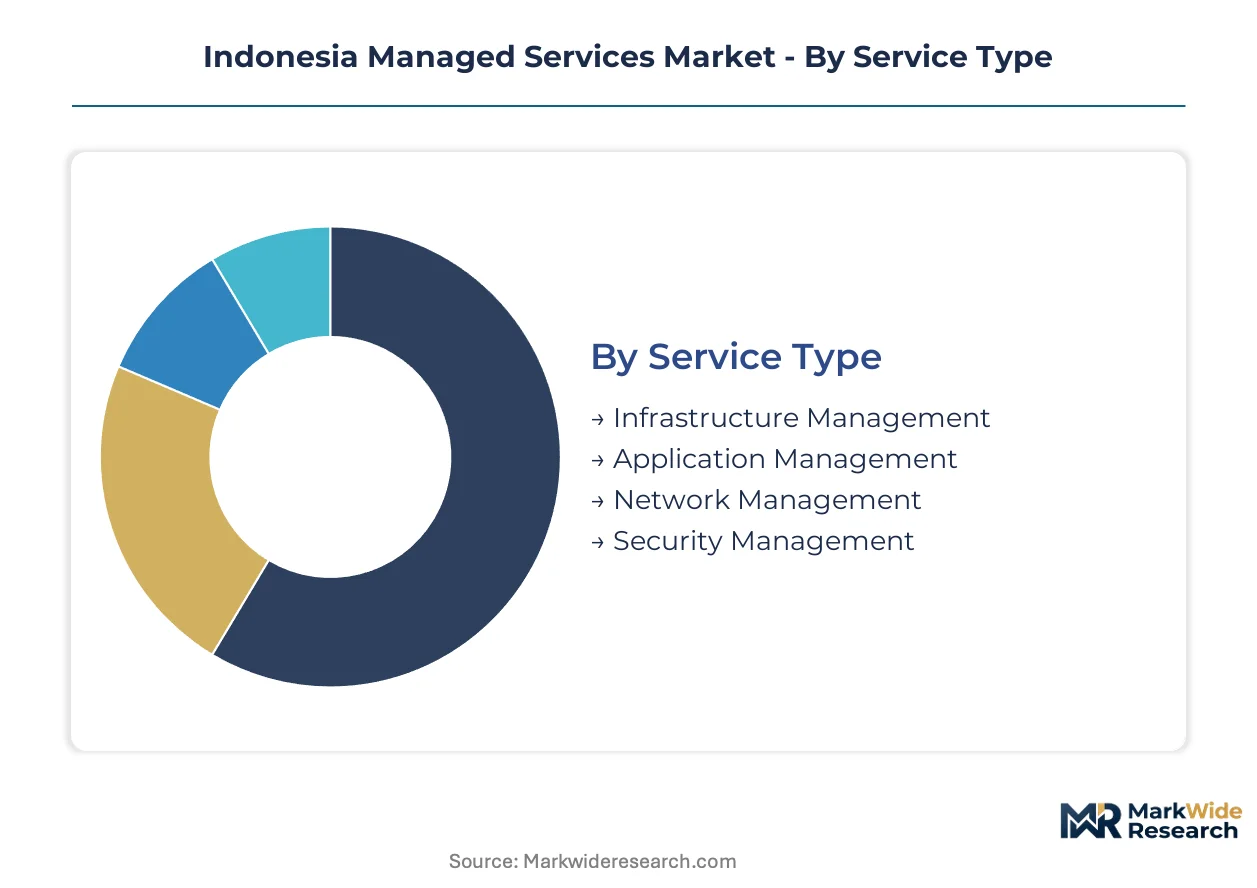
Managed services procurement in Indonesia fragments across buyer sophistication, regulatory exposure, and infrastructure maturity. Each segmentation dimension reveals distinct pricing power, contract tenure, and vendor qualification thresholds that shape competitive positioning.
Service Type:
Domestic demand concentrates in services tied to OJK and BIS compliance mandates, while export-oriented segments remain minimal given Indonesia's inward-facing data sovereignty framework.
- Infrastructure Management:Server, storage, and compute resource administration under 99.9% uptime SLAs. State-owned enterprises in Jakarta's financial district drive contract volumes as legacy datacenter refresh cycles accelerate under Ministry of Communication and Informatics localization directives.
- Security Management:Continuous threat monitoring, incident response, and compliance audit support for regulated entities. Indonesian banks facing mandatory BIS cybersecurity audits bundle these services into broader infrastructure contracts rather than sourcing point solutions, concentrating demand among pre-certified providers.
- Application Management:ERP and core banking system maintenance with patch management and performance tuning.
- Network Management:WAN optimization and SD-WAN deployment with fiber backhaul dependency.
Infrastructure Management commands the established base. The steepest expansion runs through Security Management.
End User:
Cost tier stratification separates capital-constrained buyers seeking operational expenditure predictability from enterprises with captive IT budgets and compliance-driven procurement.
- Large Enterprises:Hybrid architecture mandates spanning legacy core systems and cloud-native workloads. These buyers dominate contract values in Jakarta, though procurement cycles extend due to multi-stakeholder governance and extended vendor due diligence.
- SMEs:Cloud-first buyers bypassing on-premises capital expenditure through subscription-based service tiers. Manufacturing firms in Surabaya and Bandung unbundle after-sales support from hardware procurement, contracting specialized providers directly for predictable cost structures.
- Government:State-linked entities with localization mandates and extended tender cycles.
- Healthcare:Hospitals and clinics responding to breach disclosure rules with nascent managed security demand.
Large Enterprises command the established base. The steepest expansion runs through SMEs.
Deployment Model:
Volume concentration reflects infrastructure maturity gradients between Java-based enterprises and underpenetrated eastern provinces with fiber backhaul constraints.
- Hybrid:Integrated on-premises and cloud infrastructure with orchestration layer management. Large enterprises with legacy core systems retain this architecture to balance data sovereignty compliance with modernization imperatives, slowing full cloud migration.
- Cloud-Based:Fully outsourced infrastructure with consumption-based pricing. Mid-sized enterprises accelerate adoption to bypass capital-intensive builds, though certified talent scarcity in secondary cities constrains implementation velocity.
- On-Premises:Traditional captive infrastructure with remote monitoring overlays.
- Managed Hosting:Dedicated physical infrastructure with provider-operated facilities.
Hybrid commands the established base. Cloud-Based gains share fastest.
Industry Vertical:
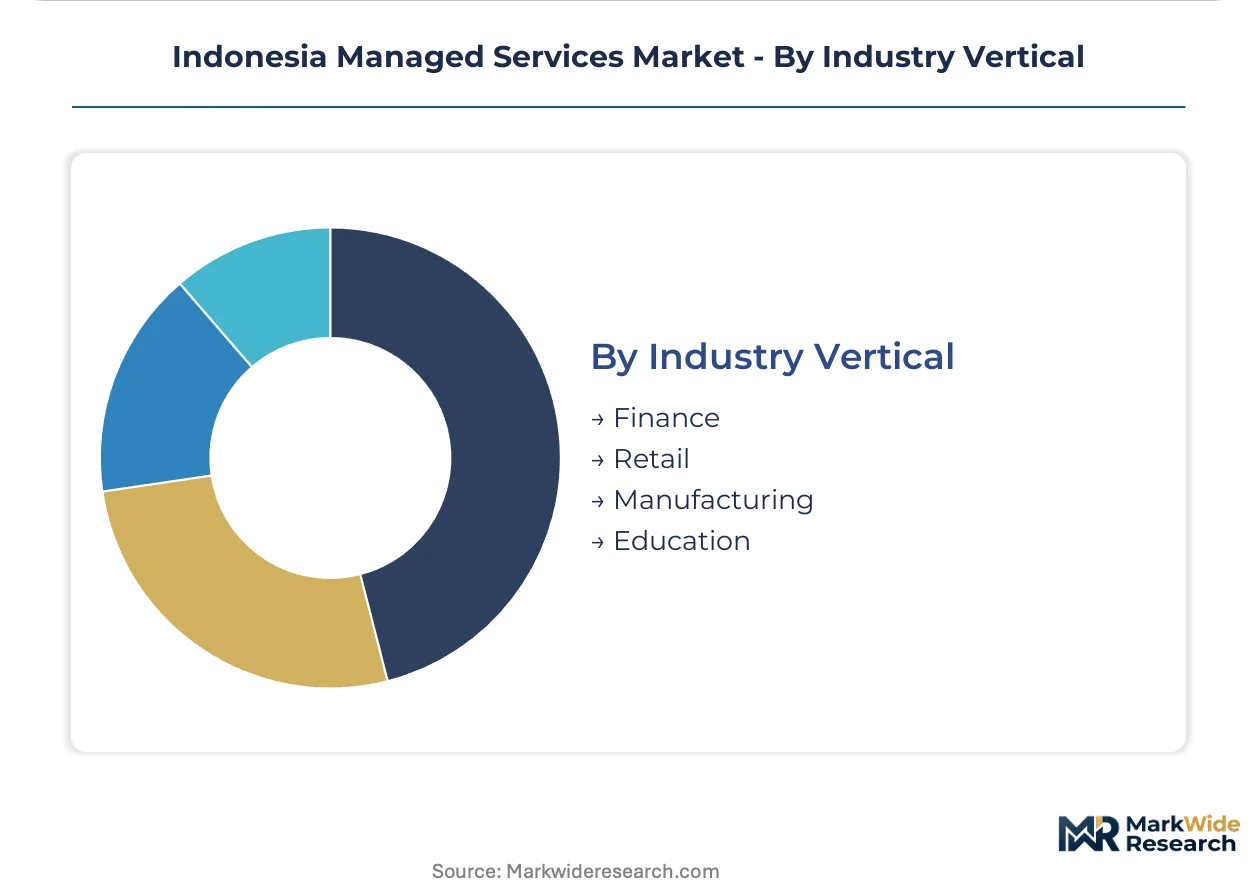
Application intensity varies by vertical regulatory exposure and digital transformation maturity, with finance and retail leading contract sophistication.
- Finance:Core banking, payment infrastructure, and regulatory reporting systems under OJK technology mandates. Jakarta-based banks expand managed security contracts as BIS cybersecurity standards tighten, prioritizing providers with pre-certified compliance architectures.
- Manufacturing:Operational technology integration and supply chain system management. Firms in Surabaya and Bandung drive SME-tier demand for predictable operational expenditure structures.
- Retail:E-commerce platform management and customer data infrastructure.
- Education:Learning management systems and campus network administration with limited procurement sophistication.
Finance commands the established base. Manufacturing climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian managed service providers export compliance-ready infrastructure solutions to Singaporean financial institutions seeking secondary disaster recovery sites outside primary jurisdictions.
Java
Jakarta's financial district concentrates demand for managed security services as OJK banking technology regulations mandate third-party audit trails. State-owned enterprises accelerate cloud migration under Ministry of Communication and Informatics data sovereignty directives. Surabaya manufacturing clusters drive SME-tier procurement for predictable operational expenditure structures.
Sumatra
Medan logistics hubs generate network management demand for supply chain system integration across Malacca Strait trade corridors. BIS cybersecurity framework compliance requirements elevate certified provider qualification thresholds. Palembang energy sector facilities anchor industrial IoT monitoring contracts with fiber backhaul dependency constraints.
Sulawesi
Makassar port modernization creates nascent demand for operational technology management and customs infrastructure digitization. National data localization mandates restrict cross-border data flows and elevate domestic hosting requirements. Nickel processing industrial parks near Morowali drive specialized connectivity procurement despite limited fiber density.
Kalimantan
Balikpapan energy sector operations require hybrid architecture management spanning legacy SCADA systems and cloud-native analytics platforms. Ministry of Communication and Informatics directives enforce domestic data residency for critical infrastructure operators. Samarinda coal logistics firms represent emerging mid-market buyers bypassing capital-intensive on-premises builds.
Bali and Eastern Indonesia
Denpasar tourism technology infrastructure generates managed hosting demand for reservation platforms and payment gateways. Breach disclosure rules hardening accountability standards create managed security opportunities among hospitality chains. Kupang and Ambon remain underpenetrated markets where first-mover providers establishing local delivery presence capture early contract flow.
Indonesia Managed Services Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and state-linked heritage dimensions. Market structure tilts toward consolidation around telecommunications-affiliated providers with captive fiber infrastructure and established government relationships. Three archetypes dominate: state-linked incumbents leveraging policy access, independent fiber specialists competing on latency performance, and hyperscale cloud operators with compliance-ready regional infrastructure. Dominant competitive moves include strategic partnerships with domestically certified operators and portfolio diversification into predictive analytics tooling.
Within the state-linked tier, Telkomsigma anchors government and banking contracts nationwide through its telecommunications heritage. PT Aplikanusa Lintasarta occupies a position exemplifying fiber backhaul density as a competitive differentiator for low-latency connectivity promises. Amazon Web Services Indonesia represents the compliance-ready hyperscale archetype with regional cloud infrastructure positioned for regulated sector uptake.
| Leading Market Players |
|---|
| PT Cyberindo Mega Persada |
| PT Aplikanusa Lintasarta |
| Telkomsigma |
| PT Biznet Gio Nusantara |
| Amazon Web Services Indonesia |
| Zettagrid Indonesia |
| Eranyacloud |
| PT XL Axiata |
| PT VADS Indonesia |
| Others |
Pricing and Supply Chain Analysis
Datacenter scale economies in Jakarta's financial district compress unit costs for certified providers while elevating price floors for uncertified competitors seeking BIS compliance. Capacity utilization above eighty percent at established facilities enables aggressive subscription pricing that smaller operators cannot match without sacrificing margin.
Pricing Analysis
Current-generation AI-driven security operations centers command premium subscription tiers against prior-generation rule-based monitoring and nascent next-generation autonomous response platforms. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified providers from uncertified regional specialists and commodity remote monitoring shops. Cost compression in the economy tier is intensifying because fiber backhaul expansion outside Java lags demand. Mid-sized enterprises in Surabaya and Bandung exhibit highest price sensitivity, while Jakarta-based banks facing OJK mandates show lowest sensitivity to security management premiums.
Supply Chain Analysis
Just-in-time talent deployment dominates Indonesian managed services, with providers maintaining bench capacity of certified BIS engineers rather than strategic stockpiles of hardware. Hardware sourcing concentrates in Singapore, Malaysia, and China for server and networking equipment, with domestic assembly limited to rack integration. Software licensing draws from US hyperscalers, European security vendors, and domestic compliance tool developers. Single-source vulnerability in submarine cable connectivity through the Sunda Strait elevates redundancy costs. Distribution runs through direct enterprise sales teams for large accounts and telecommunications reseller channels for SME penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesian managed services operate as a regulatory-entrenchment defensive moat, where BIS certification timelines and OJK audit requirements create switching costs that cement incumbent positions. Data sovereignty mandates deepen this structural advantage for domestically certified operators.
For Market Incumbents: Consolidate fiber backhaul assets in Eastern Indonesia to preempt emerging connectivity plays before submarine cable expansion reaches Kupang and Ambon. Acquire certified engineering teams in secondary cities where talent scarcity constrains competitor scaling. Vertical integration into predictive analytics tooling addresses margin pressure from automation-driven service commoditization.
For New Entrants and Emerging Players: Lead with healthcare vertical specialization in breach-disclosure compliance, a segment where incumbent presence remains thin and procurement sophistication is rising. Target manufacturing clusters in Bandung with consumption-based cloud management offerings that bypass capital-intensive on-premises builds. Partner with established telecommunications providers for fiber access rather than building captive infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers with pre-certified BIS compliance architectures serving Jakarta's banking sector. Long-term viability rests on localization mandate alignment and captive fiber assets. Acquisition candidates should demonstrate proven delivery presence in at least two Indonesian sub-regions beyond Java. The signal to watch is Ministry of Communication and Informatics directive expansion into additional verticals beyond finance and critical infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early BIS compliance investment secures eligibility for OJK-mandated banking contracts before competitors complete audit cycles. |
| Fiber Infrastructure Partnership | Alliances with state-linked telecommunications operators unlock government and state-owned enterprise procurement channels. |
| Predictive Analytics Integration | Automation tooling embedded in maintenance workflows differentiates premium service tiers from commodity remote monitoring. |
| Eastern Indonesia Delivery Presence | First-mover facilities in underpenetrated markets capture contract flow ahead of submarine cable connectivity expansion. |
| Healthcare Vertical Specialization | Breach disclosure rule compliance expertise positions providers for nascent hospital and clinic security demand. |
Research Methodology
The analysis maps infrastructure management, security management, application management, and network management segments, each validated through chief technology officers, IT procurement officers, platform engineers, and channel partners. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, telecommunications regulatory submissions, and customs import records. Bottom-up contract value aggregation and top-down market sizing triangulated to reconcile segment outputs.
Consistency checks against external benchmarks validated projections across the modeling period. Segmentation dimensions modeled include service type, end user scale, deployment architecture, and industry vertical regulatory exposure. CAGRs derived from historical trajectory analysis and adoption curve positioning. Forecast inputs incorporated BIS cybersecurity framework implementation timelines and Ministry of Communication and Informatics localization directive expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained OJK enforcement intensity and fiber infrastructure investment continuity would require recalibration. Forecasts reflect assumptions regarding certification pipeline throughput and submarine cable deployment schedules. Revision becomes warranted when BIS audit capacity constraints or regulatory directive scope expansion crosses thresholds that alter competitive qualification dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Portal Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market