
 United States Management Consulting Services Market | 2026-2036
United States Management Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Management Consulting Services Market Analytics
Artificial intelligence is consolidating the economics of traditional advisory delivery across the United States management consulting landscape. McKinsey & Company leverages its proprietary analytics platforms to anchor premium strategy engagements with Fortune 500 clients. Deloitte Consulting competes through end-to-end implementation capabilities that extend from advisory into technology deployment. Accenture dominates cloud transformation and digital operations, positioning its consulting arm as a technology-first alternative to legacy advisory models.
Management consulting services encompass structured advisory engagements where independent experts diagnose organizational problems, design operational improvements, and oversee implementation across strategy, finance, technology, and human capital domains. These services rely on codified methodologies, proprietary data assets, and partner-level expertise delivered through time-based or outcome-linked fee structures. Operations Consulting and Financial Advisory command the deepest margin pools as clients prioritize cost restructuring and capital optimization over generic strategy decks. Strategy Consulting retains premium positioning at the top of the engagement pyramid, while Project-Based and Retainer models split the market between episodic transformation needs and ongoing advisory relationships.
The SEC, FTC, and IRS collectively shape demand through disclosure mandates, merger review thresholds, and tax restructuring rules that force clients into specialized advisory relationships. HIPAA compliance requirements in healthcare and the Sarbanes-Oxley Act's internal control provisions sustain recurring regulatory advisory revenue streams. Stakeholders must weigh whether to build captive consulting capabilities or deepen vendor relationships as regulatory complexity outpaces internal expertise development.
Market Dynamics
Generative AI platforms are compressing the value chain of traditional advisory work, forcing established firms to restructure their talent models and pricing architectures around technology-augmented delivery rather than hourly partner leverage.
Growth Catalysts
- SEC Climate Disclosure Mandates:Public companies must secure external assurance for Scope 1, 2, and 3 emissions reporting, creating sustained demand for carbon accounting and scenario analysis expertise.
- Healthcare Operational Transformation:Hospital systems facing CMS value-based care penalties are engaging consultants for clinical workflow redesign and revenue cycle optimization.
- Cloud Migration Complexity:Multi-hybrid infrastructure deployments across financial services and retail are generating implementation advisory contracts that bundle strategy with technical execution.
Market Restraints
- Talent Wage Inflation:Data scientists and AI implementation specialists command compensation premiums that compress project margins, particularly in middle-market engagements.
- Client In-House Capabilities:Fortune 100 corporations have built internal strategy functions and analytics centers of excellence that displace traditional external advisory relationships.
- Sarbanes-Oxley Compliance Saturation:Mature internal control frameworks at large public companies have reduced the recurring audit-related consulting revenue that sustained firms through the 2000s.
Strategic Opportunities
- Mid-Market Digital Transformation:Manufacturing and logistics firms with $500 million to $2 billion revenue represent an underserved segment lacking internal technology leadership.
- IRA Clean Energy Tax Credits:Project developers require specialized advisory to navigate transferability mechanics and domestic content calculations for renewable energy investments.
- AI Governance Frameworks:Enterprises deploying large language models need policy architecture, risk assessment protocols, and workforce transition planning that generalist IT consultants cannot provide.
Industry Challenges
- Knowledge Codification:Senior partners struggle to capture tacit expertise into scalable digital assets that junior staff can deploy without direct supervision.
- Client Expectation Compression:Buyers demand fixed-fee or outcome-linked pricing while project scope expands due to organizational complexity and stakeholder alignment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Management Consulting Services Market |
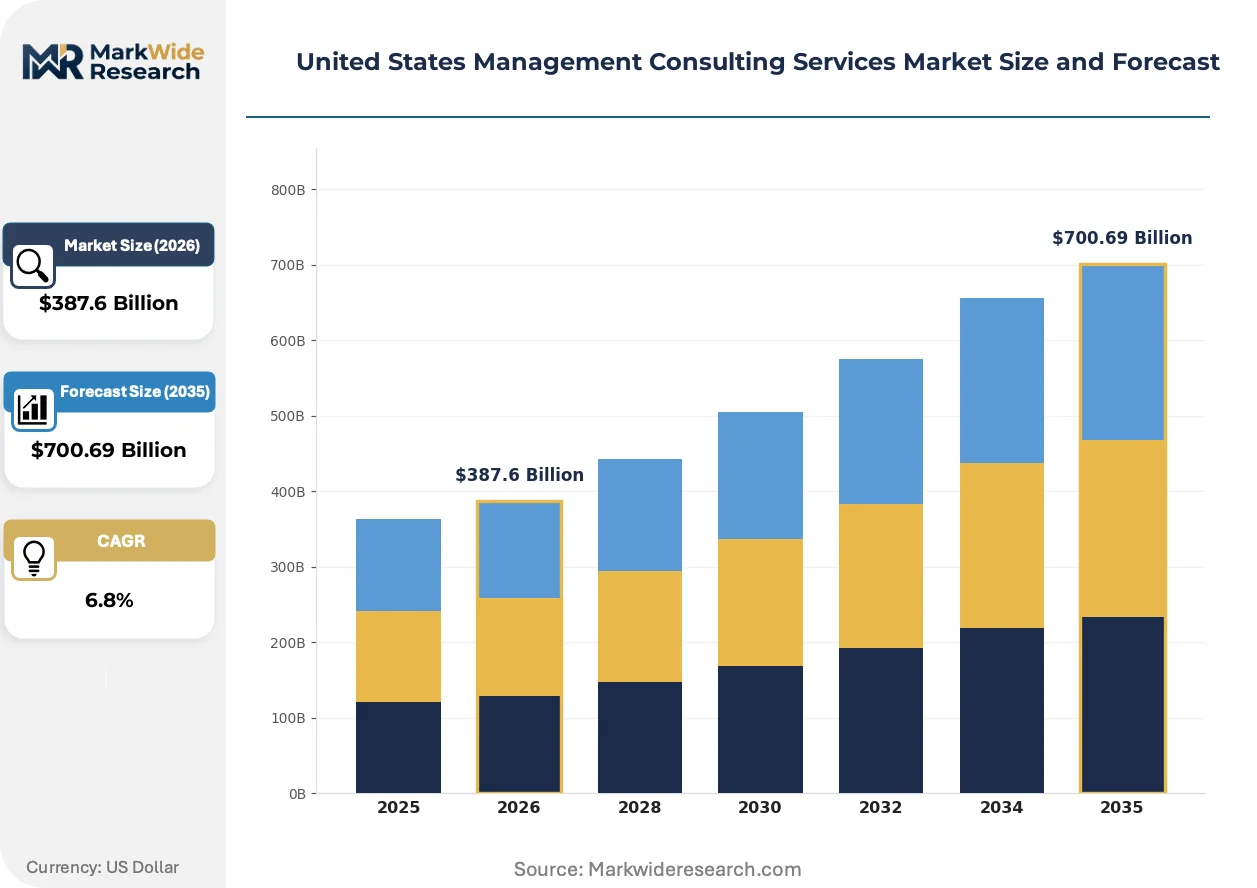
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Operations Consulting, Financial Advisory, HR Consulting Industry Vertical: Healthcare, Technology, Retail, Manufacturing Client Type: Corporations, Non-Profits, Government Agencies, Startups Engagement Model: Project-Based, Retainer, Advisory, Outsourcing |
| Companies Covered | McKinsey & Company, Boston Consulting Group, Bain & Company, Deloitte Consulting, Accenture, PwC Advisory Services, EY Advisory, KPMG Advisory, Oliver Wyman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Management Consulting Services Market Evolving Landscape
Advisory delivery models are fragmenting along technology intensity lines, with pure strategy work separating from implementation-heavy engagements and AI-native competitors capturing the middle market through productized offerings.
Proprietary AI copilots trained on firm-specific knowledge bases and client engagement histories are overtaking traditional associate-heavy research and analysis workflows. Mid-tier consultancies deploy these tools to match Big Four output quality with smaller teams. The structural consequence is a compression of entry-level hiring and a pivot toward technology-enabled senior generalist models.
The SEC's enhanced climate disclosure rules are mandating third-party attestation for emissions data, forcing advisory firms to build or acquire specialized assurance capabilities. Industrial and energy sector clients face the steepest compliance burdens. California-based technology companies are responding fastest, integrating climate risk into enterprise risk management frameworks ahead of federal deadlines.
Enterprise buyers are unbundling strategy advisory from implementation, selecting boutique firms for diagnostic work and systems integrators for execution. Healthcare providers and public sector agencies lead this behavior shift. The separation is most pronounced in Texas and Florida, where state-level procurement rules favor discrete vendor selection over single-source relationships.
United States Management Consulting Services Market Segmentation
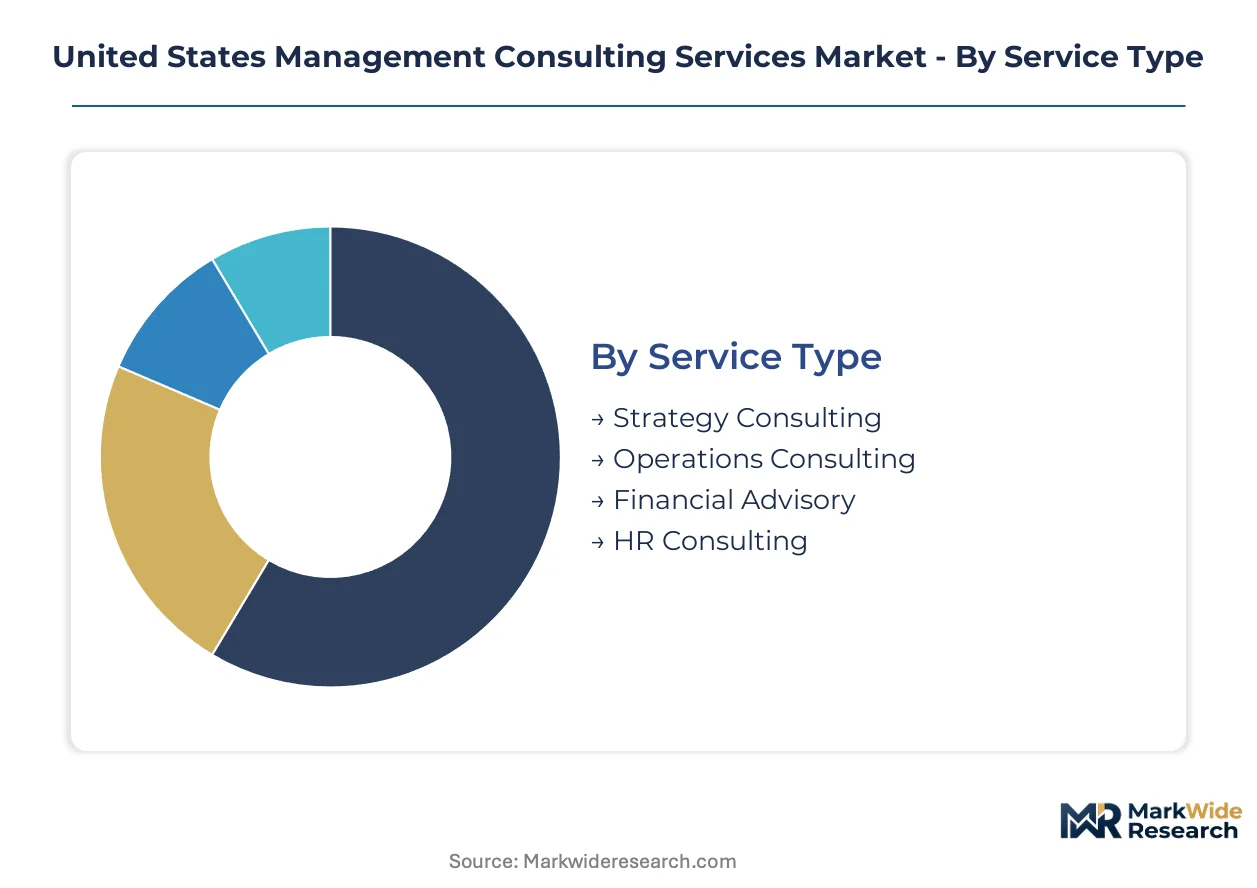
Management consulting services fragment along four distinct dimensions that shape vendor selection, pricing architecture, and engagement duration. Buyers prioritize service type based on transformation urgency, while industry vertical dictates regulatory compliance requirements and specialized expertise needs.
Service Type:
Buyers select service categories based on the maturity of their internal capabilities and the capital intensity of required interventions.
- Strategy Consulting:C-suite advisory on market entry, M&A, and portfolio restructuring delivered through partner-led teams. Fortune 500 technology and financial services firms in New York and California sustain premium engagements despite expanding internal strategy functions.
- Operations Consulting:Process redesign, supply chain optimization, and cost restructuring across manufacturing and healthcare systems. Hospital networks facing CMS value-based care penalties drive sustained demand for clinical workflow and revenue cycle expertise.
- Financial Advisory:Capital structure optimization, transaction support, and restructuring advisory. Private equity sponsors and middle-market corporates engage for due diligence and carve-out execution.
- HR Consulting:Workforce transformation, compensation benchmarking, and talent acquisition strategy. Technology sector clients prioritize AI governance frameworks and reskilling program design.
Operations Consulting leads on scale; Strategy Consulting leads on momentum.
Industry Vertical:
Regulatory complexity and technology disruption intensity determine vertical-specific advisory spend levels.
- Healthcare:HIPAA compliance, clinical integration, and value-based care transformation. Hospital systems across Texas, Florida, and California engage for operational turnaround and merger integration support.
- Technology:Cloud migration, AI governance, and platform economics advisory. SEC climate disclosure mandates and dual-listing structures create specialized assurance needs.
- Retail:Omnichannel transformation, inventory optimization, and private label strategy. Direct-to-consumer brands seek pricing architecture and supply chain redesign.
- Manufacturing:Industry 4.0 implementation, reshoring analysis, and IRA clean energy tax credit navigation. Midwest industrial clusters drive project-based engagements.
Healthcare captures the deepest engagement value; Technology climbs the fastest.
Client Type:
Procurement sophistication and stakeholder complexity separate client segments by engagement model preferences.
- Corporations:Public and private enterprises with revenue exceeding $500 million. Internal procurement functions favor outcome-linked pricing and multi-year transformation partnerships.
- Non-Profits:Healthcare systems, universities, and foundations with mission-driven governance. Board-level oversight extends decision timelines and requires stakeholder alignment protocols.
- Government Agencies:Federal, state, and municipal entities with formalized RFP processes. Texas and Florida state procurement rules favor discrete vendor selection over single-source relationships.
- Startups:Venture-backed companies scaling from product-market fit to operational infrastructure. Rapid engagement cycles and equity-compensation structures differentiate advisory relationships.
Corporations dominate current spend; Startups show steepest expansion trajectory.
Engagement Model:
Risk allocation preferences and scope certainty determine model selection across client maturity stages.
- Project-Based:Defined deliverables with fixed or milestone-linked fees for transformation programs. Healthcare providers and public sector agencies unbundle strategy from implementation using discrete procurement.
- Retainer:Ongoing advisory access with monthly or quarterly fee structures. Financial services and private equity firms sustain relationships for transaction readiness and market monitoring.
- Advisory:Board-level and executive coaching engagements with time-based billing. Governance and succession planning support for family-owned enterprises and founder-led technology companies.
- Outsourcing:Managed service delivery of finance, HR, or technology functions. Mid-market manufacturers lacking internal leadership adopt bundled advisory and execution arrangements.
Project-Based engagements command greatest volume; Retainer relationships gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors the United States management consulting services market through its concentration of Fortune 500 headquarters and financial services infrastructure. The Northeast corridor sustains premium advisory demand across strategy, regulatory compliance, and transaction support functions.
California
Technology sector expansion drives advisory spend across cloud migration, AI governance, and platform economics. SEC climate disclosure mandates compel Silicon Valley enterprises to secure external assurance for Scope 1, 2, and 3 emissions reporting. San Francisco Bay Area consultancies command premium fees for dual-listing structures and enterprise risk integration.
Texas
Energy transition projects and healthcare system consolidation generate sustained demand for operational transformation advisory. State procurement rules favor discrete vendor selection over single-source relationships, fragmenting engagement models. Dallas and Houston clusters specialize in clinical workflow redesign and revenue cycle optimization for hospital networks facing CMS value-based care penalties.
Illinois
Manufacturing reshoring analysis and Industry 4.0 implementation drive project-based engagements across Midwest industrial corridors. IRA clean energy tax credit navigation requires specialized advisory for domestic content calculations and transferability mechanics. Chicago-based firms serve middle-market manufacturers with bundled advisory and execution arrangements.
Florida
Healthcare operational turnaround and merger integration support dominate advisory relationships as hospital systems expand regionally. State-level procurement protocols mirror Texas in mandating competitive vendor separation. Miami and Tampa clusters attract private equity sponsors seeking due diligence and carve-out execution for middle-market corporates.
Massachusetts
Life sciences commercialization and biotech platform strategy sustain specialized advisory engagements across Greater Boston. HIPAA compliance requirements and clinical integration challenges generate recurring regulatory advisory revenue. Cambridge and Boston clusters concentrate expertise in AI governance frameworks and workforce reskilling program design for technology sector clients.
United States Management Consulting Services Market Competitive Landscape
Global majors compete with regional champions across service type and client sophistication tiers, producing a stratified market structure with concentrated leadership at the premium end and fragmentation below. Strategy and operations consulting segments exhibit divergent consolidation patterns, with pure-play strategy houses maintaining tight oligopoly positions while implementation-heavy practices face technology-enabled disruption. Three archetypes dominate: full-service integrators bundling advisory through execution, pure-play strategy specialists commanding partner-led premium pricing, and technology-native competitors productizing mid-market offerings. Competitive intensity centers on M&A for specialized capabilities and talent acquisition for AI implementation expertise.
Within the pure-play strategy tier, McKinsey & Company, Boston Consulting Group, and Bain & Company occupy positions defined by partner leverage models and proprietary methodology development. These firms exemplify the premium archetype through Fortune 500 anchor relationships and C-suite advisory access. Their positioning contrasts with technology-first alternatives and mid-market specialists pursuing different competitive vectors.
| Leading Market Players |
|---|
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Deloitte Consulting |
| Accenture |
| PwC Advisory Services |
| EY Advisory |
| KPMG Advisory |
| Oliver Wyman |
| Others |
Value Network & Pricing Analysis
Mid-market manufacturers demanding outcome-linked pricing for digital transformation engagements are compressing project margins across the United States management consulting services landscape, forcing advisory firms to restructure talent deployment toward technology-augmented delivery models and away from partner-heavy hourly billing.
Pricing Analysis
Specialized AI implementation expertise and data science talent command compensation premiums that pass through to client fees, particularly in middle-market engagements where Fortune 100 internal capabilities have displaced traditional advisory relationships. Three-tier pricing structure across premium, standard, and economy levels separates McKinsey-tier strategy work from Big Four implementation bundles and productized mid-market offerings. Cost compression in the standard tier is intensifying because generative AI platforms commoditize research and analysis workflows. Private equity sponsors show least price sensitivity for transaction readiness retainers; mid-market manufacturers exhibit greatest sensitivity for operational turnaround projects.
Supply Chain Analysis
Direct-to-corporate channels anchor premium strategy engagements with Fortune 500 headquarters in New York and California, while partner networks and technology alliances extend reach into middle-market manufacturing clusters across the Midwest and healthcare systems in Texas and Florida. Talent supply concentrates in the United States, United Kingdom, and India, with offshore delivery centers in Bangalore and Gurgaon supporting implementation-heavy workstreams. Raw material inputs encompass proprietary analytics platforms, cloud infrastructure subscriptions, and specialized regulatory databases. Single-source vulnerability sits with elite partner talent pools whose mobility between firms disrupts client relationship continuity. Distribution runs through managing partner networks, industry-specialist practices, and technology vendor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the United States management consulting services market rests on technology-augmented delivery models that compress junior staff ratios and premium-tier positioning that captures regulatory complexity premiums.
For Market Incumbents: Extend proprietary AI copilot deployment across research and analysis workflows to match Big Four output quality with smaller teams, while deepening vertical specialization in IRA clean energy tax credit navigation and SEC climate disclosure assurance to defend against boutique competitors and technology-native disruptors. For New Entrants and Emerging Players: Mid-market manufacturers with $500 million to $2 billion revenue represent the most penetrable buyer archetype, lacking internal technology leadership and underserved by premium-tier incumbents. Target this segment through productized AI governance frameworks and bundled advisory-execution arrangements, leveraging outcome-linked pricing to differentiate from hourly billing incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized regulatory advisory boutiques possessing SEC climate assurance capabilities or IRA tax credit expertise. Long-term viability favors firms that have codified tacit partner knowledge into scalable digital assets. Watch for inflection signals in mid-market digital transformation procurement volumes as indicators of technology-native competitor share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary AI Platform Development | McKinsey and Deloitte deploy analytics copilots to compress associate-heavy workflows and defend margin structure. |
| Vertical Specialization Acquisition | Big Four advisory practices acquire climate assurance boutiques to meet SEC Scope 3 attestation mandates. |
| Mid-Market Productization | Technology-native competitors package AI governance frameworks for $500M-$2B revenue manufacturers. |
| Talent Model Restructuring | Firms pivot from entry-level hiring toward technology-enabled senior generalist deployment. |
| Outcome-Linked Pricing Expansion | Healthcare providers and public sector agencies unbundle strategy from implementation using fixed-fee procurement. |
Research Methodology
Bottom-up client engagement modeling reconciled against top-down advisory firm revenue tracking forms the analytical core of this study. Primary interviews with managing partners, healthcare system CFOs, private equity operating partners, and technology sector procurement officers combined with secondary validation from SEC filings, CMS Medicare cost reports, and GPO contract databases. Top-down triangulation incorporated Big Four advisory revenue disclosures and specialized boutique firm capacity estimates.
Historical trendline analysis across service type, industry vertical, client segment, and engagement model dimensions established baseline growth patterns. Segmentation modeling tracked Strategy Consulting, Operations Consulting, Financial Advisory, and HR Consulting across Healthcare, Technology, Retail, and Manufacturing verticals with Corporate, Non-Profit, Government Agency, and Startup client types. CAGRs derived from regression analysis of advisory spend intensity against client revenue growth and regulatory complexity indices. Forecast inputs encompassed SEC rulemaking timelines, IRA credit phase-out schedules, and AI adoption S-curves.
Underlying measurement precision varies by segment; Operations Consulting and Financial Advisory carry tighter precision than nascent AI Governance advisory. Forecasts reflect assumptions regarding regulatory implementation pace and technology adoption thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Supplier Management Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Proactive Services Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market