
 Employee Fraud Detection Market | 2026-2036
Employee Fraud Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Fraud Detection Market Analysis
Data science talent scarcity is rotating enterprise priorities toward vendor-managed detection platforms rather than in-house builds. SAS Institute Inc. leverages decades of statistical modeling depth to anchor financial services deployments across North America. NICE Actimize competes on specialized anti-money laundering overlap with employee surveillance workflows. Securonix, Inc. differentiates through cloud-native architecture that reduces client-side infrastructure burdens.
Employee fraud detection encompasses software systems that monitor internal transactions, access patterns, and behavioral signals to identify theft, embezzlement, or policy violations before material losses occur. These platforms typically ingest structured enterprise data—ERP logs, payment rails, identity management events—at throughput rates exceeding millions of events per second, applying statistical models to flag deviations from established baselines. Cloud-based deployment is capturing the fastest expansion as regulated industries reconcile data residency requirements with elastic compute needs. User behavior analytics concentrates margin pools due to higher implementation complexity and recurring tuning services. Rule-based systems retain substantial installed base in manufacturing and healthcare where interpretability outweighs predictive precision.
The EU AI Act imposes risk-classification obligations on automated employee monitoring systems, compelling vendors to document training data provenance and human oversight protocols. In the United States, SEC examination priorities and FFIEC guidance push broker-dealers and banks toward auditable anomaly detection workflows. India's Digital Personal Data Protection Act constrains how domestic employers deploy behavioral analytics, creating compliance-layer demand for localized deployment architectures. Stakeholders must weigh jurisdictional fragmentation against platform standardization when configuring multi-country rollouts.
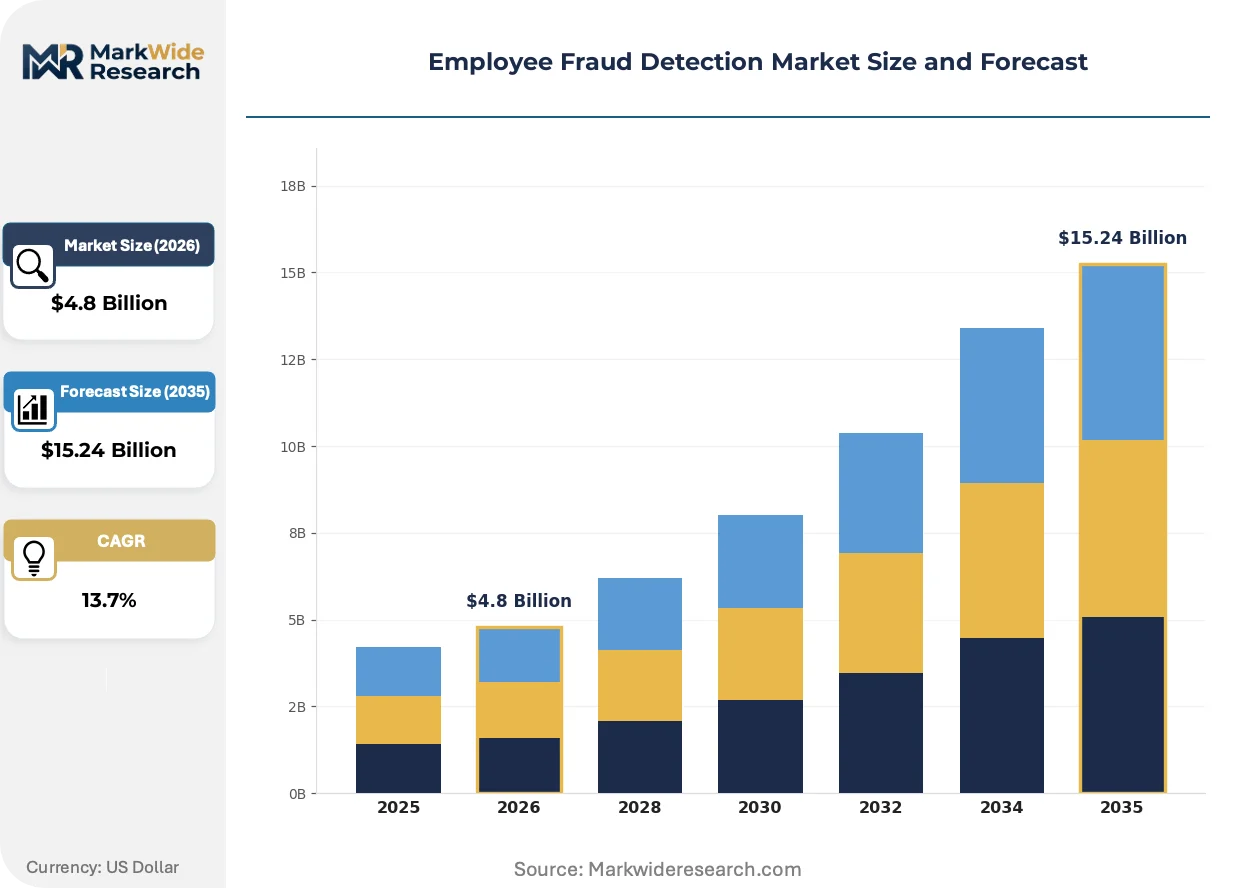
Market Dynamics
The EU AI Act's risk-classification obligations for automated monitoring systems are forcing vendors to rearchitect platforms for algorithmic accountability, compressing deployment timelines and elevating documentation costs across multi-jurisdictional rollouts.
Growth Catalysts
- FFIEC guidance on anomaly detection:US broker-dealers and banks face examination priorities that mandate auditable insider threat workflows, accelerating procurement of integrated surveillance platforms.
- Cloud-native architecture adoption:Elastic compute capabilities allow financial institutions to process millions of ERP and payment rail events per second without fixed infrastructure commitments.
- India's Digital Personal Data Protection Act:Localization mandates for behavioral analytics create demand for on-premise deployment architectures among domestic employers.
Market Restraints
- Data residency compliance costs:Multi-country operators must maintain separate infrastructure footprints to satisfy India's data localization and EU GDPR cross-border transfer rules.
- Behavioral model drift:Statistical baselines require continuous recalibration as workforce patterns shift, consuming specialized data science labor that remains scarce.
- Interpretability requirements in manufacturing:Rule-based detection retains installed base where predictive precision yields to explainable decision logic for audit trails.
Strategic Opportunities
- Germany's supply chain transparency mandates:Industrial conglomerates face new documentation requirements that expand addressable market for vendor-managed detection platforms.
- Convergence of UEBA with anti-money laundering:Unified transaction monitoring across employee and customer channels reduces redundant infrastructure for financial institutions.
- Managed detection services:Talent scarcity rotates enterprise priorities toward vendor-operated platforms that bundle tuning and model maintenance.
Industry Challenges
- Integration complexity with legacy ERP:Manufacturing and healthcare incumbents operate decades-old systems that resist standardized API connectivity for event ingestion.
- Certification timeline compression:EU AI Act conformity assessments demand extensive training data provenance documentation that extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Fraud Detection Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Detection Method: Data Analytics, Predictive Modeling, Anomaly Detection, User Behavior Analytics Industry Vertical: Finance, Retail, Healthcare, Manufacturing Technology: Machine Learning, Artificial Intelligence, Rule-Based Systems, Blockchain Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | NICE Actimize, SAS Institute Inc., SAP SE, NetGuardians, Inc., Verafin Inc., Clari5, Ekran System, Securonix, Inc., Exabeam, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Fraud Detection Market Emerging Trajectories
Automated employee surveillance is pivoting from rule-based flagging toward adaptive statistical modeling, with regulatory pressure and infrastructure economics jointly determining which architectures gain traction across institutional buyers.
User behavior analytics is fragmenting the detection market by enabling granular individual profiling that rule engines cannot replicate. Large financial institutions in the United States are deploying these platforms at scale, compressing margins for legacy signature-based systems that lack predictive depth.
The EU AI Act imposes mandatory human oversight protocols and training data documentation on high-risk automated monitoring applications. Vendors serving European financial institutions must now maintain audit trails for algorithmic decision logic, elevating compliance engineering headcount and extending implementation timelines.
Subscription pricing for cloud-deployed detection is displacing perpetual license models among mid-market buyers. Managed service providers in Germany and India are capturing this transition by bundling platform access with continuous model tuning, compressing customer procurement cycles from twelve months to ninety days.
Employee Fraud Detection Market Segmentation
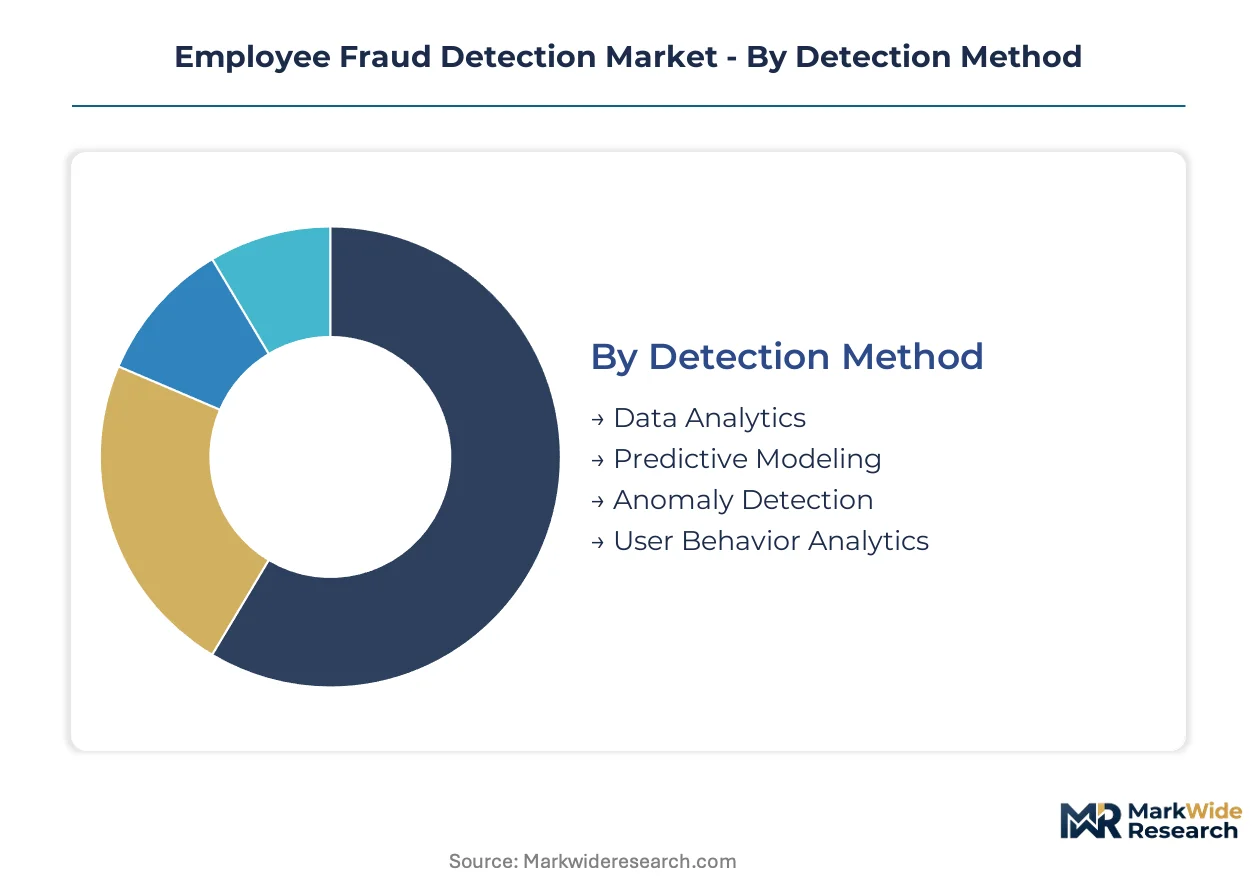
Segmentation in employee fraud detection reveals how procurement priorities diverge across regulatory environments and infrastructure maturity. Buyers select architectures based on data residency constraints, legacy system burdens, and the scarcity of internal data science capacity.
Detection Method:
Demand for detection methods splits sharply between jurisdictions with strict algorithmic accountability rules and those prioritizing deployment speed over interpretability.
- User Behavior Analytics:Statistical models profile individual employee patterns across ERP logs, access events, and communication metadata to identify deviation from established baselines. Financial institutions in the United States deploy these platforms at scale under FFIEC examination priorities, consuming specialized implementation labor that vendors now bundle as managed services.
- Anomaly Detection:Unsupervised algorithms flag statistical outliers in transaction streams without predefined rules, enabling discovery of novel fraud patterns. India's Digital Personal Data Protection Act constrains behavioral analytics deployment, creating compliance-layer demand for localized architectures that process data within domestic boundaries.
- Data Analytics:Descriptive dashboards aggregate historical fraud incidents for pattern review and audit documentation.
- Predictive Modeling:Supervised learning techniques score future fraud probability based on labeled training datasets.
User Behavior Analytics holds the largest share; momentum sits with Anomaly Detection as cloud-native architectures reduce infrastructure barriers.
Industry Vertical:
Vertical adoption correlates with regulatory examination intensity and the materiality of insider threat exposure in core operations.
- Finance:Broker-dealers and banks face SEC examination priorities and FFIEC guidance mandating auditable insider threat workflows. Institutions process millions of ERP and payment rail events per second, driving procurement of elastic compute architectures that reconcile data residency with throughput requirements.
- Healthcare:HIPAA audit trails and decades-old legacy systems create integration complexity that favors rule-based detection with explainable decision logic. Manufacturing incumbents in Germany face supply chain transparency mandates that expand procurement of vendor-managed platforms with embedded documentation capabilities.
- Retail:High-volume transaction environments with seasonal workforce fluctuations require rapid model recalibration.
- Manufacturing:Industrial conglomerates prioritize interpretability for audit trails over predictive precision in fraud detection workflows.
Finance commands the dominant revenue position; healthcare is expanding most quickly as HIPAA enforcement tightens documentation requirements.
Technology:
Technology selection reflects tension between predictive performance and the EU AI Act's risk-classification obligations for automated monitoring systems.
- Machine Learning:Cloud-native architectures enable elastic processing of structured enterprise data at throughput rates exceeding legacy infrastructure capacity. Germany's industrial conglomerates deploy these platforms under supply chain transparency mandates, bundling continuous model tuning with platform access to compress procurement cycles.
- Rule-Based Systems:Hardcoded logic flags known fraud signatures with complete interpretability for audit documentation. Manufacturing and healthcare retain substantial installed base where regulatory scrutiny demands explainable decision trails over statistical sophistication.
- Artificial Intelligence:Deep learning approaches process unstructured data sources including communications and document content.
- Blockchain:Immutable audit trails provide tamper-evident documentation for regulatory examination and dispute resolution.
Rule-Based Systems retain the largest installed base; Machine Learning is gaining share fastest as cloud economics reduce infrastructure commitment requirements.
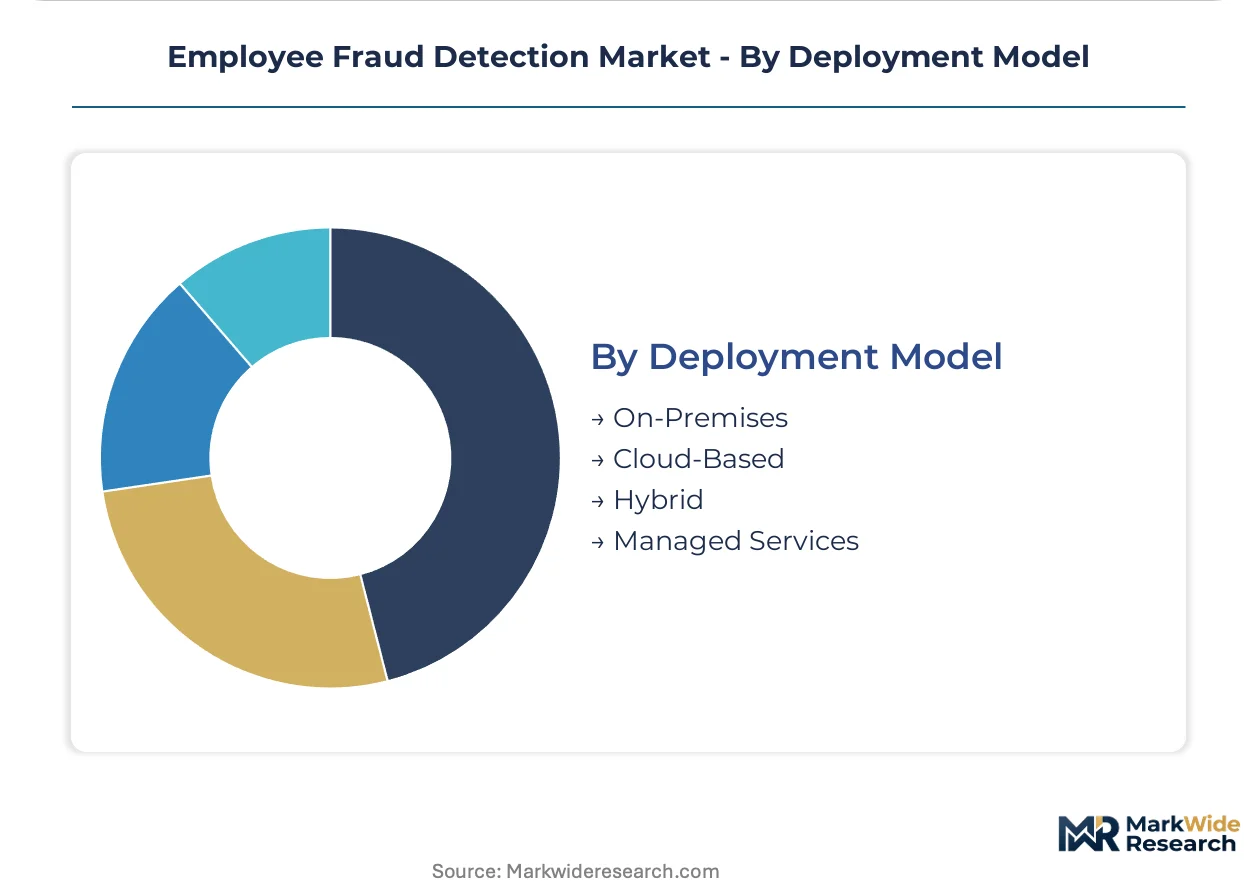
Deployment Model:
Deployment preferences rotate toward vendor-operated platforms as enterprise data science talent scarcity intensifies.
- Cloud-Based:Elastic compute capabilities allow regulated industries to reconcile data residency requirements with variable processing demand. Mid-market buyers in Germany and India adopt subscription pricing that compresses procurement cycles from twelve months to ninety days.
- Managed Services:Vendors assume responsibility for model tuning, drift correction, and compliance documentation under EU AI Act training data provenance requirements. Data science talent scarcity rotates enterprise priorities toward vendor-operated platforms that bundle technical maintenance with regulatory alignment.
- On-Premises:Domestic infrastructure satisfies India's data localization mandates and EU GDPR cross-border transfer constraints.
- Hybrid:Split architectures process sensitive data on-premise while leveraging cloud elasticity for non-sensitive analytical workloads.
On-Premises maintains substantial share in regulated jurisdictions; Managed Services is climbing the fastest as talent scarcity deepens vendor dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where regulatory examination intensity justifies premium platform investments, while India and emerging markets compete on localization cost efficiency rather than feature depth.
United States
Financial institutions in New York and Chicago drive demand for cloud-native insider threat platforms capable of processing millions of payment rail events per second. SEC examination priorities and FFIEC guidance mandate auditable anomaly detection workflows that elevate procurement budgets. Broker-dealers along the Northeast Corridor deploy these systems under continuous regulatory scrutiny.
Germany
Industrial conglomerates in Bavaria and North Rhine-Westphalia expand procurement of vendor-managed detection platforms to satisfy supply chain transparency mandates. EU AI Act risk-classification obligations force rearchitecture of automated monitoring systems for algorithmic accountability. Frankfurt's financial services cluster adopts subscription pricing models that compress traditional procurement cycles.
India
Domestic employers in Maharashtra and Karnataka face compliance-layer demand for localized deployment architectures under the Digital Personal Data Protection Act. Data localization constraints behavioral analytics processing within domestic boundaries, favoring on-premise infrastructure over cloud elasticity. Bangalore's technology services sector develops captive detection capabilities for export to regulated foreign clients.
United Kingdom
Financial services firms in the City of London reconcile GDPR cross-border transfer rules with elastic compute needs through hybrid deployment models. FCA supervisory expectations align with SEC precedent on insider threat program documentation. The Southeast England technology corridor hosts emerging managed detection service providers targeting mid-market buyers.
Japan
Metropolitan Tokyo's banking consortiums balance statistical sophistication with interpretability requirements for internal audit acceptance. METI industrial security guidelines encourage behavioral analytics adoption without mandating specific technical architectures. Osaka-based manufacturing groups retain substantial rule-based detection installed base where explainable decision logic outweighs predictive performance.
Employee Fraud Detection Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with statistical modeling depth concentrated among established analytics vendors while cloud-native challengers compete on deployment velocity and infrastructure economics. The market structure reflects a tiered competitive field where decades-long financial services relationships anchor incumbent positions alongside emerging specialists in user behavior analytics. Three strategic archetypes dominate: legacy statistical platform providers, cloud-native security specialists, and vertically integrated enterprise software conglomerates. Competitive moves concentrate on M&A activity to acquire behavioral modeling capabilities and strategic partnerships to embed detection modules within broader enterprise resource planning workflows.
Within the statistical modeling tier, SAS Institute Inc. and NICE Actimize occupy positions shaped by long-standing financial services deployments across North American institutions. Securonix, Inc. exemplifies the cloud-native challenger archetype with architecture designed to reduce client-side infrastructure burdens. These three companies collectively represent the competitive spectrum from established analytical depth to elastic infrastructure delivery, anchoring strategic positioning without exhausting the vendor field.
| Leading Market Players |
|---|
| NICE Actimize |
| SAS Institute Inc. |
| SAP SE |
| NetGuardians, Inc. |
| Verafin Inc. |
| Clari5 |
| Ekran System |
| Securonix, Inc. |
| Exabeam, Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity-reservation contracts with cloud infrastructure providers lock in compute access for vendor-managed detection platforms while anchoring subscription pricing visibility for financial institutions across North America and Germany. These arrangements compress procurement cycles and transfer infrastructure risk from enterprise buyers to platform operators.
Pricing Analysis
The customization-premium spread separates configured-to-order UEBA deployments from standard rule-based packages, with financial institutions in the United States paying substantial premiums for continuous model tuning services. Subscription SaaS-tiered pricing dominates as mid-market buyers in Germany and India adopt ninety-day procurement cycles over traditional twelve-month negotiations. Price differentiation hinges on certification level for EU AI Act compliance and geographic delivery cost for localized data residency architectures. Cost compression in standard-tier offerings is intensifying as cloud-native challengers reduce infrastructure commitment requirements. Mid-market manufacturing buyers exhibit highest price sensitivity; broker-dealers under SEC examination scrutiny show least.
Supply Chain Analysis
Inbound logistics costs for GPU clusters and specialized compute hardware through Shanghai-Ningbo and Busan trade lanes constrain deployment velocity for on-premise detection architectures in India and Japan. Component sourcing concentrates in Taiwan, South Korea, and the United States for advanced semiconductors essential to machine learning inference. Raw material dependencies span NVIDIA accelerators, high-bandwidth memory modules, and enterprise-grade storage arrays. Single-source vulnerability around leading-edge GPU supply creates procurement risk for vendors scaling cloud-native platforms. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
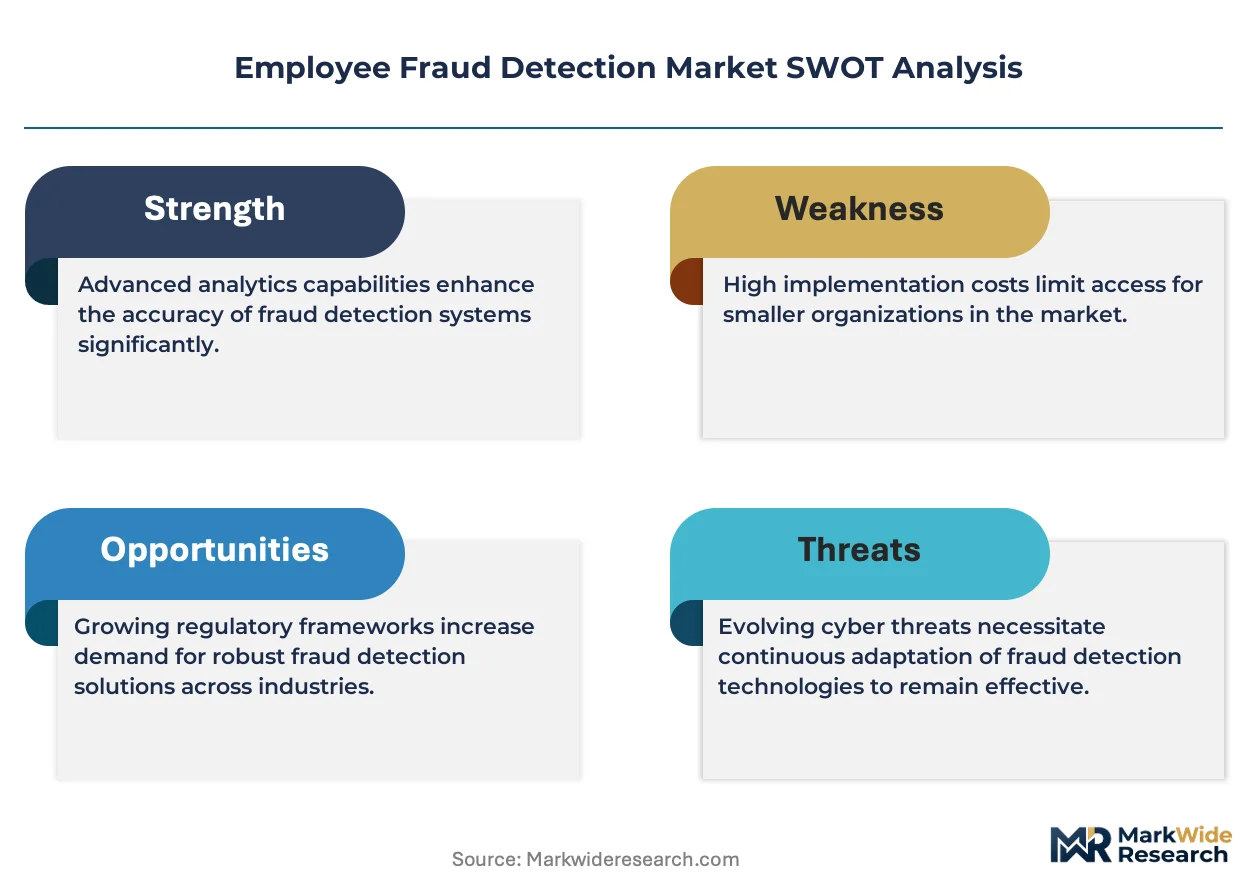
The employee fraud detection market is experiencing high-growth disruption as EU AI Act risk-classification obligations force platform rearchitecture and elevate compliance engineering costs across European deployments.
For Market Incumbents: Compound statistical modeling depth with managed service bundling to defend against cloud-native challengers eroding margin pools in mid-market segments. Incumbents should deepen backward integration into behavioral analytics R&D while accelerating certification investments for EU AI Act conformity assessments that extend sales cycles.
For New Entrants and Emerging Players: Anchor in India's localized deployment demand under the Digital Personal Data Protection Act, where domestic employers require on-premise architectures that global hyperscalers cannot easily satisfy. New entrants should target mid-market healthcare providers in the United States with HIPAA-compliant UEBA offerings and pursue channel partnerships with legacy ERP integration specialists.
For Investors and Strategic Acquirers: Cloud-native security specialists with embedded compliance documentation capabilities represent the most attractive acquisition target archetype for portfolio exposure to regulatory-driven procurement acceleration. Long-term viability over the next decade hinges on algorithmic accountability infrastructure becoming table stakes across jurisdictions. Investors should monitor EU AI Act enforcement intensity as the primary inflection indicator for platform rearchitecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies UEBA with anti-money laundering workflows for broker-dealers under FFIEC guidance. |
| Strategic Partnership | Embeds detection modules within SAP and Oracle ERP ecosystems serving German industrial conglomerates. |
| Acquisition of Specialist Firm | Captures behavioral modeling talent scarce in open labor markets across North America. |
| Geographic Expansion | Establishes localized data centers in Maharashtra and Karnataka for India's data residency mandates. |
| Product Launch | Introduces subscription-tiered managed detection services compressing procurement cycles to ninety days. |
Methodological Framework
A spread of perspectives from chief information security officers, compliance officers at broker-dealers, vendor solutions architects, and data protection consultants converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC examination priority disclosures, EU AI Act regulatory texts, RBI and SEBI circulars on insider threat programs, and FFIEC guidance documents. Bottom-up deployment sizing and top-down market consolidation patterns were triangulated against hyperscaler infrastructure expansion announcements.
Segmentation dimensions modeled span detection method, industry vertical, technology architecture, and deployment model across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves and regulatory enforcement intensity scoring. Forecast inputs incorporated cloud infrastructure capacity expansion timelines and data science labor market tightness indices.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and stable cloud compute pricing; material deviation would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act implementation guidance and major data protection jurisprudence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Data Masking Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Global Reputation Protection Software Market
Security Software
Global Visitor Management System Market
Security Software
Source Code Escrow Market
Security Software
Door Phone Market
Security Software
US Hardware Encryption Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
AD-Blocking Software Market
Security Software
Stalkerware Market
Security Software
Antivirus Software Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Data Masking Technology Market
Security Software
Identity Verification Software Market
Security Software
GDPR Software and Tools Market