
 Communication Encryption Software Market | 2026-2036
Communication Encryption Software Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Encryption Software Market Analysis
Premium encryption suites with quantum-resistant algorithms and sovereign cloud hosting is decoupling from commodity VPN offerings with standard AES-256 implementations. Microsoft Corporation leverages its Azure confidential computing infrastructure to anchor enterprise-grade deployments across regulated industries. Cisco Systems specializes in network-layer encryption that dominates telecommunications carrier networks. Thales Group controls hardware security module integration, differentiating its portfolio from software-only competitors.
Communication encryption software encompasses cryptographic protocols, key management systems, and secure channel technologies that protect data in transit across networks using standards such as TLS 1.3, post-quantum lattice algorithms, and elliptic-curve cryptography. Its primary commercial purpose is ensuring confidentiality, integrity, and authentication for organizational communications against interception and tampering. Cloud-based deployment is expanding fastest as SMEs abandon capital-intensive on-premises infrastructure, while BFSI verticals sustain premium spending on hybrid architectures that balance regulatory custody requirements with operational flexibility. Secure email solutions occupy mature margin pools in enterprise segments, whereas data protection modules are capturing growth in healthcare and government verticals facing escalated breach penalties.
The National Institute of Standards and Technology in the United States, the European Union Agency for Cybersecurity, and the UK's National Cyber Security Centre are mandating quantum-safe migration timelines and supply-chain security attestations that reshape procurement criteria. France's ANSSI and Germany's BSI enforce additional national certification schemes that fragment vendor compliance burdens across European markets. Stakeholders must monitor which regulatory body sets the most stringent interoperability standard first, as that jurisdiction will likely export its framework through cross-border data agreements.
Market Dynamics
Post-quantum cryptography migration timelines are compressing vendor R&D cycles and forcing premature obsolescence of legacy certificate infrastructure across enterprise IT estates.
Growth Catalysts
- Zero-trust architecture mandates:Federal agencies in the United States are requiring continuous verification protocols that drive replacement of perimeter-based VPN systems with granular encryption at the application layer.
- GDPR Article 32 enforcement:European data protection authorities are imposing breach penalties that compel financial services firms to deploy end-to-end encryption for all customer communications.
- Healthcare data protection modules:Escalated penalties for PHI exposure are accelerating procurement of encryption solutions by hospital networks and telemedicine platforms.
Market Restraints
- Hardware security module concentration:Specialist foundries in Germany and France control HSM fabrication capacity, creating supply bottlenecks for quantum-resistant key storage.
- Legacy system integration costs:Mainframe-dependent banks face prohibitive capex to retrofit 1970s-era transaction processing cores with modern TLS 1.3 handshakes.
- Regulatory fragmentation:Divergent national certification schemes from France's ANSSI and Germany's BSI multiply compliance burdens for cross-border European deployments.
Strategic Opportunities
- Sovereign cloud hosting:EU member states are mandating data localization that creates demand for encryption solutions with jurisdictional key escrow controls.
- Lattice-based algorithm convergence:NIST-standardized post-quantum schemes are integrating with existing elliptic-curve infrastructure to enable hybrid cryptographic transitions.
- SME SaaS migration:Small and mid-sized enterprises abandoning on-premises infrastructure represent underpenetrated demand for managed encryption services.
Industry Challenges
- Quantum cryptanalysis talent scarcity:The shortage of mathematicians trained in lattice-based and hash-based signature schemes delays product development timelines.
- Certificate lifecycle automation:Enterprises struggle to deploy automated certificate management at scale, leaving expired credentials as persistent breach vectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Encryption Software Market |
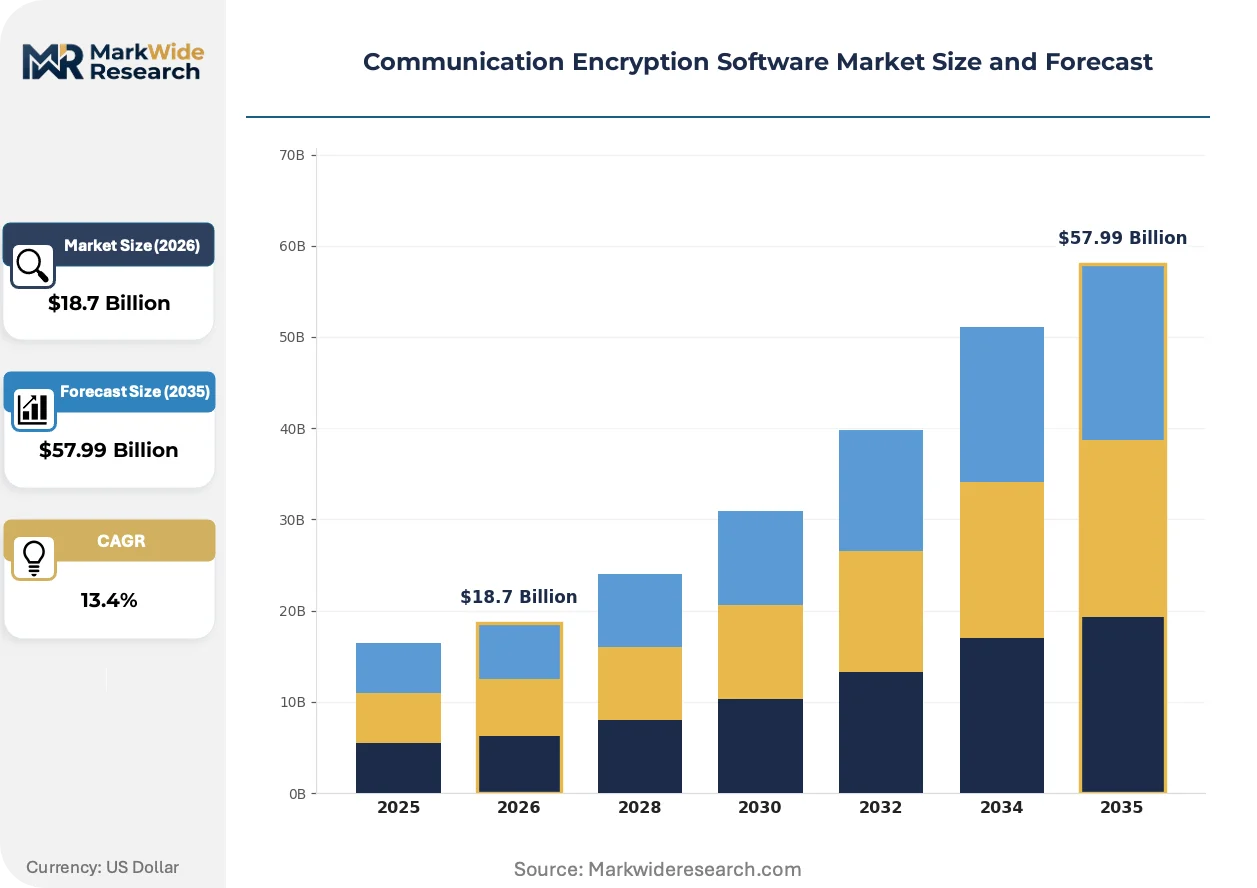
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service Solution Type: VPN, End-to-End Encryption, Secure Email, Data Protection Industry Vertical: Government, BFSI, Healthcare, Telecommunications End User: SMEs, Enterprises, Individuals, Educational Institutions |
| Companies Covered | Microsoft Corporation, IBM Corporation, Cisco Systems, Thales Group, Sophos Ltd., Check Point Software Technologies, Trend Micro Incorporated, Proofpoint, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Encryption Software Market Emerging Trajectories
Encryption markets are bifurcating between commodity transport security and premium confidential computing environments that embed cryptographic protection within processor silicon.
Confidential computing enclaves are integrating memory encryption with remote attestation to enable multi-tenant cloud processing of regulated workloads. Healthcare providers and government agencies are adopting these architectures fastest, driven by contractual liability for data exposure. The technology is compressing margins for traditional hypervisor-based isolation by eliminating the trusted computing base.
The EU AI Act's risk classification framework is mandating cryptographic provenance logging for high-risk automated decision systems. Deployers must maintain tamper-evident audit trails that chain model inputs, outputs, and parameter updates. Financial services and public sector procurement in France, Germany, and the Netherlands are requiring these capabilities as pre-qualification criteria.
Consumption patterns among mid-market buyers are fragmenting away from perpetual licenses toward usage-metered encryption services. Channel partners are replacing direct enterprise sales with embedded security modules in productivity suites. This shift is most visible in North American and UK markets where IT consolidation favors platform-integrated procurement over best-of-breed point solutions.
Communication Encryption Software Market Segmentation
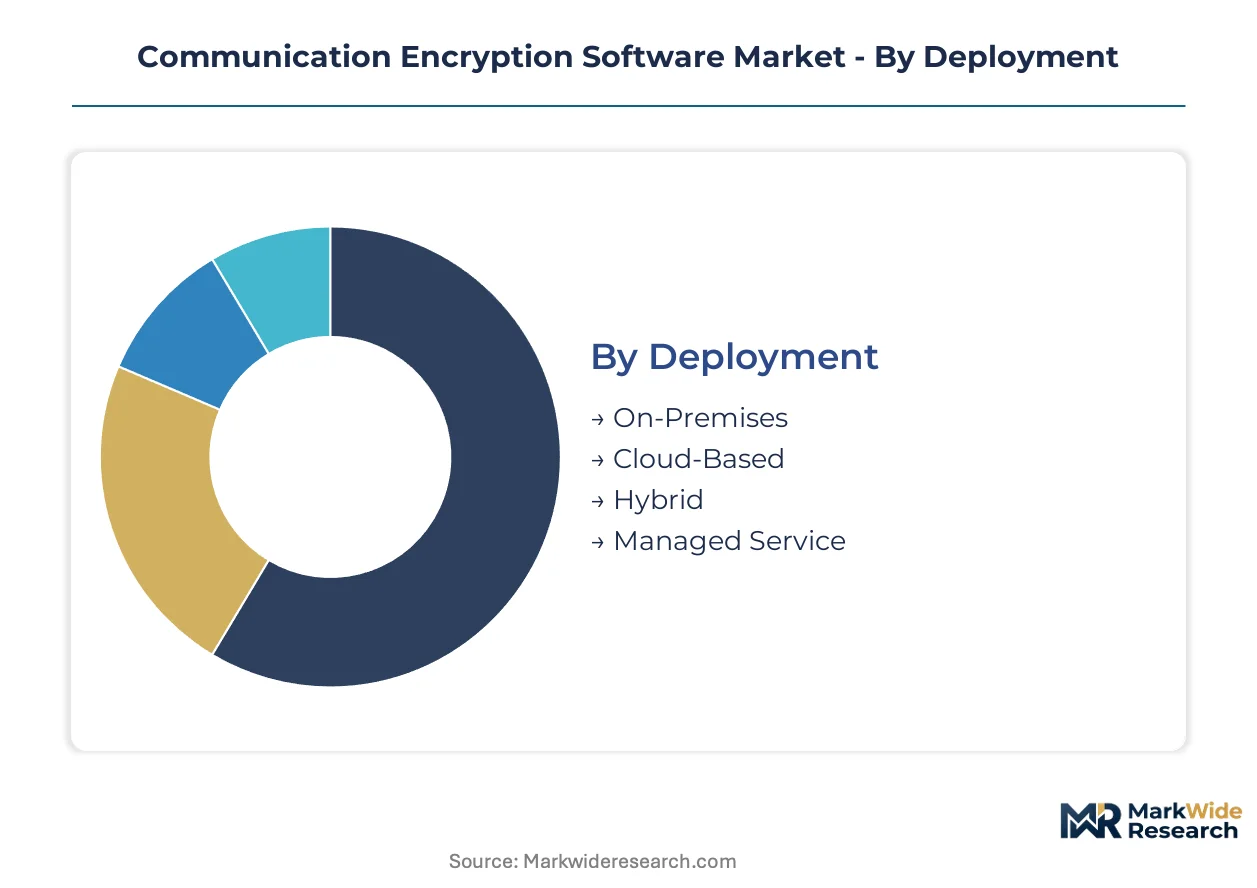
Encryption procurement patterns diverge sharply across deployment models, solution architectures, and buyer sophistication levels. Understanding these fault lines reveals where premium pricing commands traction versus where commoditization erodes margins.
Deployment:
Customization intensity spans from fully managed services with jurisdictional key escrow to standardized on-premises appliances requiring internal cryptographic expertise.
- On-Premises:Hardware-rooted encryption with localized key custody satisfies financial services firms facing strict data residency mandates. Mainframe-dependent banks in Germany and France sustain demand despite integration complexity with legacy transaction cores.
- Cloud-Based:Consumption-metered encryption services eliminate capital expenditure for mid-market buyers. Healthcare networks and telemedicine platforms across the United States are migrating fastest as breach penalties escalate.
- Hybrid:Split architectures balance regulatory custody requirements with operational flexibility. BFSI verticals deploy these configurations to maintain sovereign control over master keys while offloading compute-intensive operations.
- Managed Service:Third-party key lifecycle administration appeals to SMEs lacking internal cryptographic talent. Channel partners embed these offerings within broader security suites.
Leading the category by volume: Cloud-Based. Growing fastest: Managed Service.
Solution Type:
Margin structures correlate with threat model sophistication, from perimeter VPN commoditization to application-layer confidentiality with hardware-backed attestation.
- VPN:Network-layer tunneling protocols face margin compression as zero-trust mandates displace perimeter-based architectures. Telecommunications carriers sustain volume through wholesale carrier-grade deployments.
- End-to-End Encryption:Granular application-layer protection satisfies federal zero-trust directives in the United States. Financial services firms deploy these protocols for customer communication channels facing GDPR Article 32 enforcement.
- Secure Email:Mature encryption standards dominate enterprise segments with established compliance frameworks. Healthcare providers and government agencies maintain steady procurement for PHI and classified correspondence.
- Data Protection:Module-based encryption captures expansion in healthcare and government verticals facing escalated breach penalties. Lattice-based algorithm integration is compressing development timelines.
Volume concentration: Secure Email. Steepest expansion trajectory: Data Protection.
Industry Vertical:
Regulatory stringency determines pricing power, with sovereign certification requirements fragmenting procurement criteria across national markets.
- Government:Classified communication systems mandate hardware security module integration with quantum-resistant algorithm readiness. France's ANSSI and Germany's BSI certification schemes create compliance complexity for cross-border deployments.
- BFSI:End-to-end encryption for customer channels accelerates under GDPR penalty pressure. Hybrid architectures predominate as institutions balance custody requirements with cloud operational flexibility.
- Healthcare:PHI protection modules see accelerated procurement as breach penalties tighten. Hospital networks adopt confidential computing enclaves for multi-tenant processing of regulated workloads.
- Telecommunications:Carrier-grade network encryption sustains volume through infrastructure refresh cycles. 5G core network virtualization is driving replacement of legacy hardware encryption appliances.
Revenue concentration: BFSI. Gaining share fastest: Healthcare.
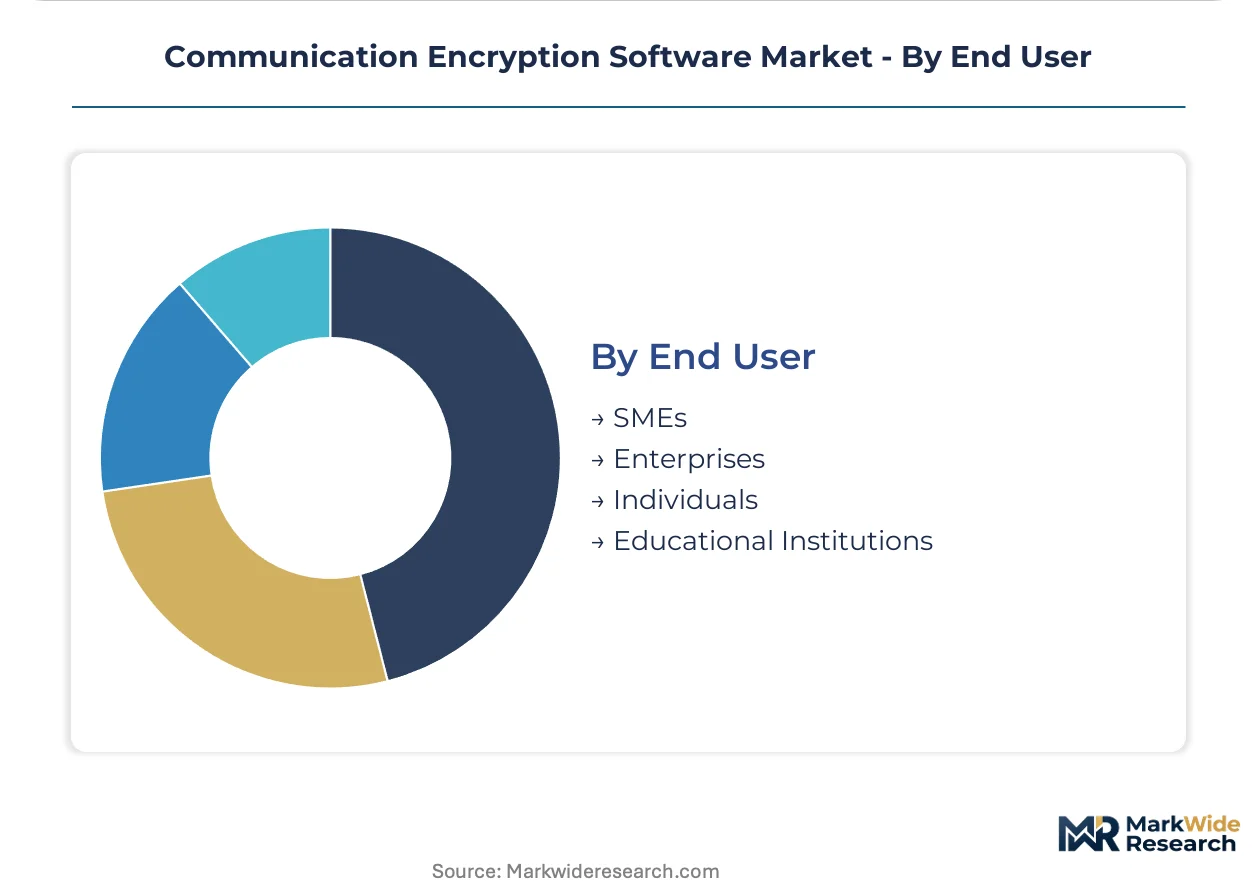
End User:
Buyer sophistication and procurement consolidation patterns separate enterprise platform integration from point-solution fragmentation.
- SMEs:Abandoning on-premises infrastructure in favor of embedded security modules within productivity suites. Usage-metered services replace perpetual licenses in North American and UK markets.
- Enterprises:Premium confidential computing deployments with sovereign cloud hosting requirements. Procurement favors platform-integrated solutions over best-of-breed point products.
- Individuals:Consumer-grade encryption through messaging applications with default security protocols. Free-tier offerings limit monetization outside privacy-conscious professional segments.
- Educational Institutions:Research data protection and student information system encryption under tightening state-level breach notification laws. Budget constraints favor managed service consumption models.
Procurement volume leader: Enterprises. Expanding most quickly: SMEs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the densest concentration of encryption software engineering talent, with venture-backed startups clustering around Stanford and Berkeley research corridors. Federal procurement offices in Washington D.C. and Virginia suburbs drive enterprise demand through classified systems contracts. London's financial district sustains premium pricing for sovereign cloud deployments.
United States
Zero-trust architecture mandates from federal agencies accelerate replacement of perimeter VPN systems with application-layer encryption. The National Institute of Standards and Technology compresses post-quantum cryptography migration timelines through standardized algorithm specifications. Boston's Route 128 corridor hosts specialized firms developing lattice-based signature schemes for government contracts.
Germany
Mainframe-dependent banks in Frankfurt sustain demand for hardware-rooted encryption despite legacy integration complexity. The Federal Office for Information Security enforces additional national certification schemes that fragment vendor compliance burdens. Munich's industrial automation cluster drives procurement of confidential computing modules for manufacturing data protection.
France
ANSSI certification requirements create procurement barriers for non-sovereign cloud encryption solutions. The EU AI Act's risk classification framework mandates cryptographic provenance logging for high-risk automated decision systems. Paris-based defense contractors anchor demand for quantum-resistant hardware security module integration.
United Kingdom
The National Cyber Security Centre mandates supply-chain security attestations that reshape procurement criteria for financial services firms. GDPR Article 32 enforcement compels end-to-end encryption deployment across customer communication channels. London's fintech corridor concentrates demand for hybrid architectures balancing regulatory custody with cloud flexibility.
Japan
Telecommunications carriers in Tokyo sustain volume through 5G core network virtualization driving replacement of legacy hardware encryption appliances. METI guidelines on critical infrastructure protection accelerate confidential computing adoption for multi-tenant regulated workloads. Osaka's healthcare technology cluster procures PHI protection modules under tightening breach notification laws.
Communication Encryption Software Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the encryption software market. Consolidation pressures concentrate around platform-integrated suites that displace point-solution vendors through embedded procurement. Three archetypes dominate: cloud infrastructure anchors with confidential computing silicon, network-layer specialists with carrier-grade tunneling protocols, and hardware security module integrators with sovereign certification depth. Dominant competitive moves include strategic partnerships with regulated industry consortia and technology licensing for post-quantum algorithm transitions.
Within the cloud infrastructure tier, Microsoft Corporation exemplifies platform-integrated deployment across regulated verticals. Cisco Systems occupies a position among network-layer specialists serving telecommunications carrier refreshes. Thales Group anchors the hardware security module segment with European sovereign certification capabilities. These three firms represent divergent strategic postures on quantum-resistant migration timelines and jurisdictional key escrow architectures.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems |
| Thales Group |
| Sophos Ltd. |
| Check Point Software Technologies |
| Trend Micro Incorporated |
| Proofpoint |
| Dell Technologies |
| Others |
Supply Flow & Price Mechanics
Specialist foundry capacity for hardware security module fabrication in Germany and France feeds directly into premium pricing tiers for quantum-resistant key storage, while commodity VPN software with standard AES-256 implementations competes on marginal cost in volume segments.
Pricing Analysis
Outcome-based pricing anchored to breach prevention and regulatory compliance outcomes dominates enterprise procurement. Pricing stratifies across confidential computing environments with sovereign cloud hosting, hybrid architectures balancing custody with flexibility, and standardized SaaS tiers for mid-market buyers. Cost compression in VPN commoditization is intensifying because zero-trust mandates displace perimeter-based network tunneling. SMEs exhibit highest price sensitivity, abandoning perpetual licenses for usage-metered consumption, while government agencies and BFSI verticals absorb premium positioning for hardware-backed attestation and jurisdictional key escrow controls.
Supply Chain Analysis
Dual-sourcing requirements for hardware security module qualification concentrate procurement between Thales Group facilities in France and Utimaco operations in Germany, with secondary qualification expanding to Cambridge Consultants in the United Kingdom. Cryptographic silicon draws from TSMC's advanced foundry nodes in Taiwan, Rambus design centers in the United States, and ARM TrustZone IP licensing from the United Kingdom. Single-source vulnerability in European sovereign certification expertise creates supply chain risk for vendors seeking ANSSI or BSI approval. Distribution runs through direct enterprise sales for classified government systems, embedded channel partnerships for productivity suite integration, and managed security service providers for SME consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware security module foundry capacity constraints in European specialist facilities prop pricing power for vendors with sovereign certification depth, creating supply-constrained market dynamics favoring incumbents with established fabrication relationships.
For Market Incumbents: Deploy confidential computing silicon integration as the primary defensive lever against cloud infrastructure anchors encroaching on enterprise encryption deployments. Consolidate position through backward integration into hardware security module design capabilities, neutralizing supply bottlenecks that threaten fulfillment timelines for government contracts. Counter lattice-based algorithm commoditization by deepening sovereign cloud hosting partnerships with EU member states mandating data localization. For New Entrants and Emerging Players: Launch via managed security service provider channels targeting SME segments abandoning on-premises infrastructure for usage-metered consumption models. Penetrate healthcare data protection modules fastest, where breach penalty escalation outpaces incumbent response capacity. Exploit white space in confidential computing enclaves for multi-tenant regulated workloads, where hospital networks and telemedicine platforms seek alternatives to hypervisor-based isolation. For Investors and Strategic Acquirers: NIST post-quantum cryptography standardization finalization is the leading indicator that quantum-resistant migration timelines will compress vendor R&D cycles and trigger consolidation around algorithm-integrated platforms. Position for five-to-ten-year viability by targeting acquisition candidates with lattice-based signature scheme expertise and existing ANSSI or BSI certification depth. Monitor EU AI Act enforcement patterns as the signal for cryptographic provenance logging becoming mandatory pre-qualification criteria in public sector procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Algorithm Integration | NIST-standardized lattice schemes compress product development timelines for government contract eligibility. |
| Sovereign Cloud Partnership | EU data localization mandates create captive demand for jurisdictional key escrow controls in member states. |
| Hardware Security Module Acquisition | European foundry capacity concentration rewards vendors with captive fabrication and certification expertise. |
| Managed Service Channel Embedding | SME SaaS migration favors encryption modules distributed through productivity suite integration partners. |
| Confidential Computing Enclave Development | Healthcare providers adopt memory-encrypted processing for multi-tenant PHI workloads under penalty pressure. |
Methodological Framework
Document review covered NIST cryptographic standardization publications, ENISA threat landscape assessments, and ANSSI certification scheme documentation, complemented by interviews with chief information security officers at financial services firms, government procurement officers for classified systems, healthcare IT directors managing PHI protection, and channel partners embedding encryption within productivity suites. Secondary validation drew from SEC filings of publicly traded cybersecurity vendors, hyperscaler confidential computing capex disclosures, and EU regulatory impact assessments for the AI Act and GDPR enforcement patterns. Bottom-up demand modeling across deployment modes and verticals was triangulated with top-down market sizing from technology spending surveys.
Segment-level projections across on-premises, cloud-based, hybrid, and managed service deployments incorporate organization size stratification, vertical regulatory intensity, and regional certification fragmentation. Quantum-resistant migration timeline assumptions, zero-trust architecture mandate compliance curves, and breach penalty escalation trajectories fed directly into adoption rate modeling across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints.
Regulatory timeline acceleration, post-quantum algorithm standardization delays, and hardware security module supply disruption are the dominant revision risks to forecast assumptions. Deviation in NIST migration deadline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Cloud IAM Market
Security Software
Bot Mitigation Market
Security Software
Global Enterprise Key Management Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Network Camera and Video Analytics Market
Security Software
Ultra-Secure Smartphone Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Europe Video Management System Market
Security Software
Robocall Mitigation Market
Security Software
Messaging Security Market
Security Software
Internet Filter Software Market
Security Software
Patch and Remediation Software Market
Security Software
Cloud Identity and Access Management Software Market
Security Software
Global Password Management Software Market
Security Software
Anti-Money Laundering (AML) Software Solution Market