
 Dairy-Free Evaporated Milk Market | 2026-2036
Dairy-Free Evaporated Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy-Free Evaporated Milk Market Outlook
The EU Green Deal is restructuring procurement criteria across European food manufacturing, compelling bakeries and dessert producers to source plant-based evaporated milk alternatives. Califia Farms leverages its oat milk extraction technology to sustain premium positioning in commercial kitchens. Oatly anchors European supply through its established Malmö production infrastructure, while Alpro competes via broad retail distribution across British and German supermarkets.
Dairy-free evaporated milk denotes a heat-reduced, shelf-stable liquid concentrate derived from plant sources such as oats, almonds, or coconuts, typically containing 60-80% less moisture than standard plant milks to achieve viscosity comparable to conventional evaporated dairy. Manufacturers employ vacuum evaporation at 50-70°C to preserve protein stability and prevent Maillard browning in oat-based formulations. The oat milk product type leads volume due to neutral flavor compatibility with coffee creamer and dessert applications, while coconut milk concentrates command margin premiums in baking segments where fat content drives texture outcomes. Online retail channels are expanding fastest among distribution pathways, though supermarkets still occupy the dominant share of household purchases.
EMA food contact guidelines and EFSA novel food assessments govern ingredient approval timelines for new plant bases entering European commerce, while REACH chemical safety protocols mandate full supply chain transparency on processing aids. These frameworks elevate compliance costs for entrants but simultaneously validate product integrity for institutional buyers. Stakeholders must monitor evolving EFSA rulings on enzymatic processing methods to anticipate which extraction technologies will secure regulatory clearance.
Market Dynamics
EU Green Deal procurement mandates are restructuring bakery and dessert manufacturing supply chains, compelling reformulation toward plant-based evaporated milk alternatives and accelerating shelf-stable alt-dairy adoption across European commercial kitchens.
Growth Catalysts
- REACH Chemical Disclosure:Tightening additive transparency requirements validate product integrity for institutional buyers and elevate compliance barriers that favor established oat and coconut concentrate suppliers.
- Bakery Reformulation:European dessert producers are absorbing greater volumes of plant-based evaporated milk as fat-content-driven texture requirements in baking applications pull coconut milk concentrates.
- Vacuum Evaporation Technology:Processing at 50-70°C preserves protein stability in oat-based formulations, enabling viscosity parity with conventional evaporated dairy in coffee creamer applications.
Market Restraints
- Input Cost Volatility:Oat protein and coconut fat supply fluctuations create margin pressure for concentrate manufacturers dependent on tropical commodity sourcing.
- EFSA Novel Food Timelines:Extended safety assessments for new plant bases delay ingredient approval and compress first-mover windows for emerging extraction technologies.
- Technical Viscosity Limits:Almond and rice concentrates fail to achieve the 60-80% moisture reduction threshold without protein destabilization, restricting application range.
Strategic Opportunities
- German Industrial Bakery Segment:Underpenetrated contract manufacturing demand for shelf-stable alt-dairy in private-label dessert production offers volume expansion potential.
- Online Retail Channel Innovation:Direct-to-consumer subscription models for specialty baking concentrates bypass supermarket slotting fee structures.
- EU Green Deal Procurement Mandates:Public sector foodservice contracts now require plant-based alternatives, creating institutional demand pull for certified evaporated milk suppliers.
Industry Challenges
- Enzymatic Processing Expertise Gap:Shortage of technicians trained in low-temperature protein extraction methods constrains capacity scaling for oat concentrate producers.
- EMA Food Contact Certification Timelines:Extended safety validation for novel processing aids delays product launches and ties up working capital in regulatory review.
- Legacy Dairy Equipment Retrofit Costs:Stainless steel compatibility issues with acidic plant formulations force capital-intensive production line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy-Free Evaporated Milk Market |
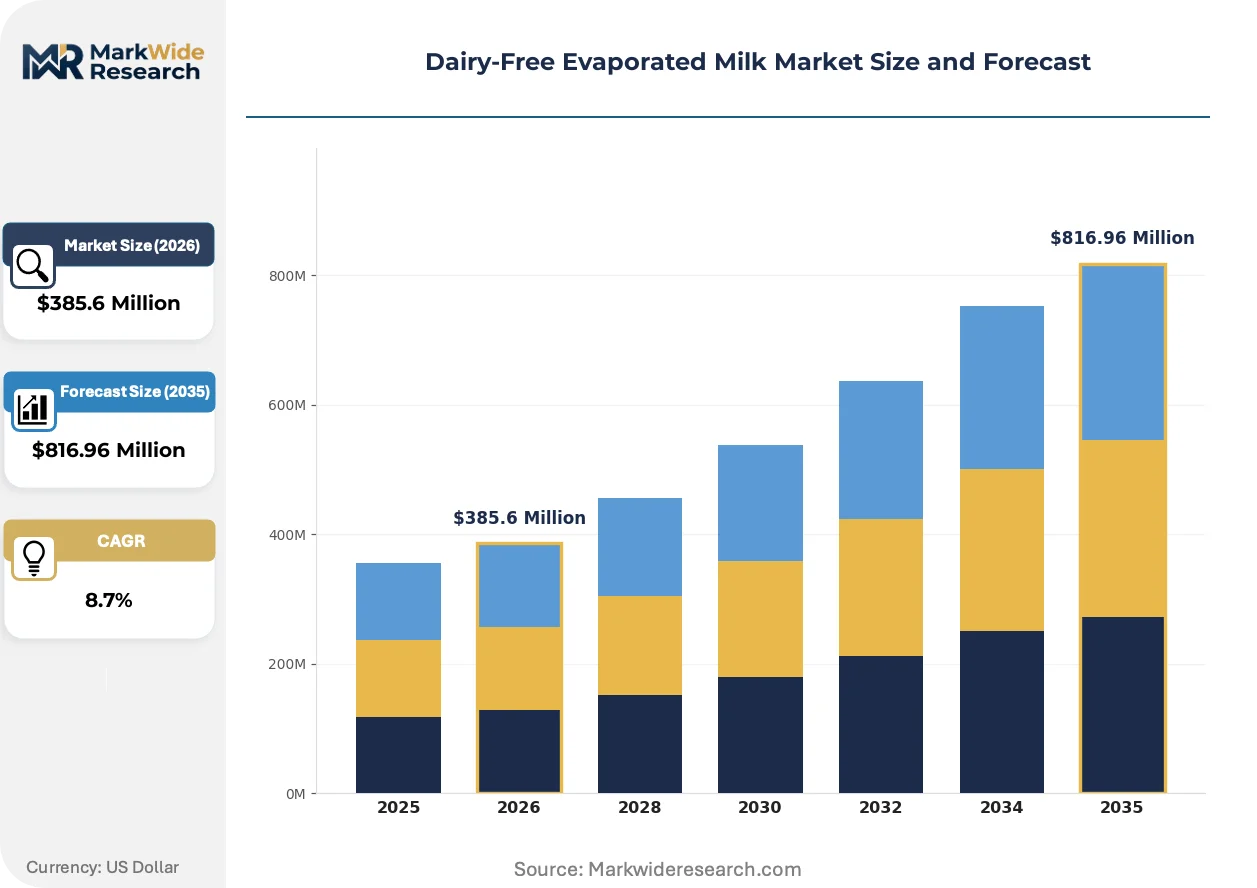
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Milk, Almond Milk, Soy Milk, Oat Milk Application: Baking, Cooking, Coffee Creamer, Desserts End User: Households, Food Service, Bakeries, Restaurants Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores |
| Companies Covered | So Delicious Dairy Free, Pacific Foods, Oatly, Elmhurst 1925, Ripple Foods, Califia Farms, Alpro, Forager Project, Silk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy-Free Evaporated Milk Market Strategic Shifts
Vacuum evaporation systems and enzymatic extraction methods are reshaping how plant-based concentrates achieve functional parity with dairy, while regulatory disclosure requirements and channel fragmentation redistribute competitive advantage across the value chain.
Membrane filtration technology is modularizing concentrate production by enabling smaller-batch, multi-feedstock processing that preserves distinct protein profiles across oat, almond, and coconut bases. Mid-sized European co-manufacturers are adopting these systems to serve fragmented bakery demand without dedicated single-product lines. This modularization compresses minimum efficient scale thresholds and opens contract manufacturing entry points previously controlled by integrated dairy alternatives producers.
REACH chemical safety protocols now mandate full supply chain transparency on processing aids and enzymatic catalysts used in plant milk concentration. Industrial buyers in Germany and the United Kingdom are auditing supplier disclosures as a procurement gate, rejecting concentrates with incomplete additive documentation. ECHA enforcement inspections in 2024 elevated compliance costs but simultaneously created differentiation for suppliers with pre-validated chemical safety dossiers.
Restaurant and café procurement patterns are fragmenting away from broadline distributors toward specialized plant-based ingredient brokers who bundle evaporated concentrates with technical formulation support. This channel shift compresses switching costs for commercial kitchens testing multiple alt-dairy suppliers. The United Kingdom exhibits the clearest demand rotation, where independent bakeries now source concentrates through ingredient-tech platforms rather than traditional foodservice distributors.
Dairy-Free Evaporated Milk Market Segmentation
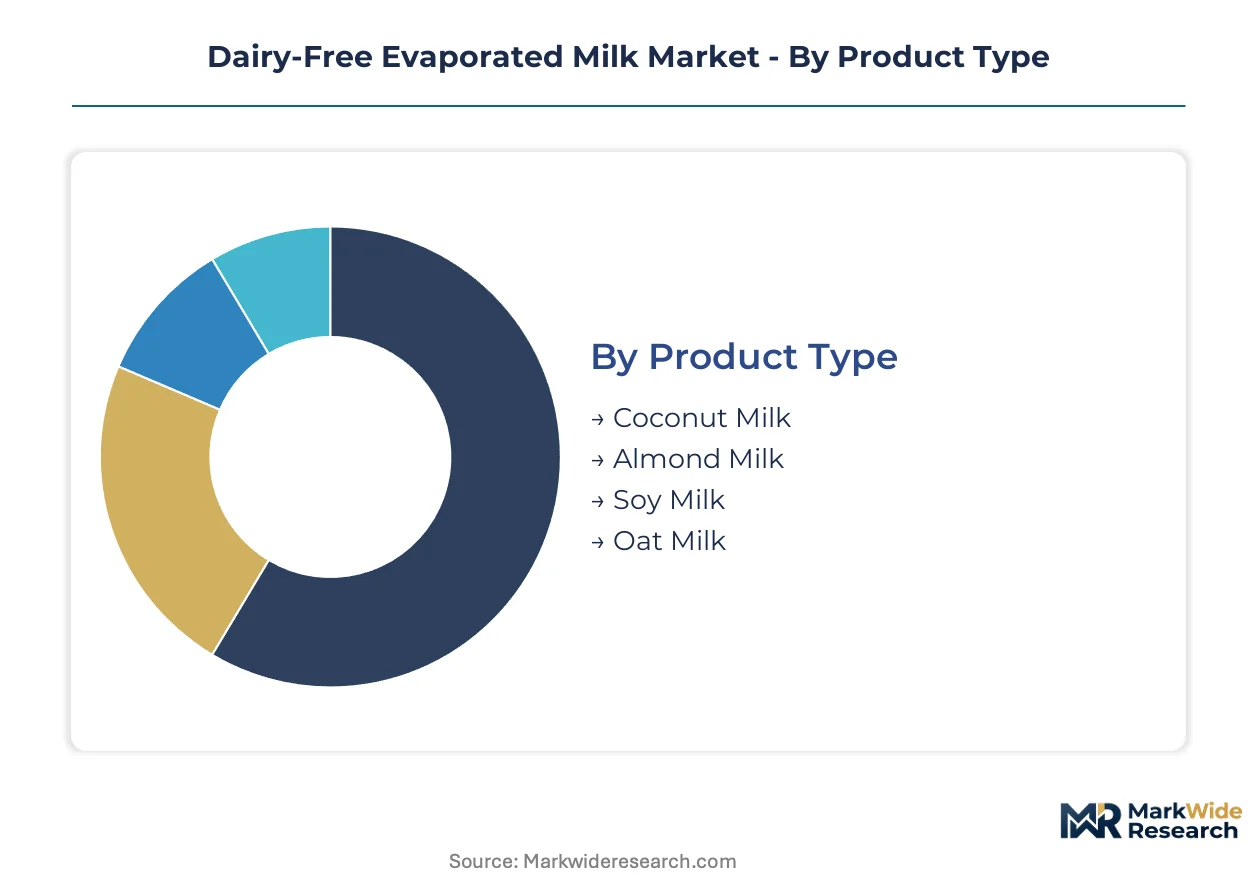
Plant-based evaporated milk manufacturers align product specifications with precise functional requirements across baking, beverage, and foodservice applications. Segmentation reveals how formulation choices and channel strategies determine competitive positioning in European markets.
Product Type:
Reformulation cycles in commercial kitchens drive product type selection, with viscosity targets and fat-content requirements determining which plant base replaces conventional evaporated dairy.
- Oat Milk:Vacuum evaporation at 50-70°C preserves protein stability in this neutral-flavored concentrate, achieving viscosity parity with dairy evaporated milk. German and British coffee creamer manufacturers absorb the largest volumes due to oat's compatibility with hot beverage applications and clean-label positioning.
- Coconut Milk:High saturated fat content delivers superior texture outcomes in European dessert production where mouthfeel is critical. Fat-driven baking applications in France and Italy command margin premiums for this segment despite tropical sourcing volatility.
- Almond Milk:Protein destabilization limits moisture reduction to 50-60% without viscosity breakdown, restricting application range primarily to light cooking sauces.
- Soy Milk:Established processing infrastructure and isoflavone stability under heat treatment sustain niche demand in institutional foodservice contracts.
Oat milk sits at the top of the volume ranking, with coconut milk climbing the fastest on bakery reformulation demand.
Application:
Cost tier differentiation separates commodity cooking applications from premium bakery and dessert segments where functional performance commands price premiums.
- Baking:Fat-content specifications in European dessert manufacturing pull concentrated volumes, with coconut and oat bases competing on texture outcomes in laminated dough and custard applications.
- Desserts:Premium positioning in gelato and pastry cream production requires 60-80% moisture reduction thresholds that only oat and coconut concentrates reliably achieve.
- Coffee Creamer:Neutral flavor compatibility and foaming stability drive oat concentrate adoption in café chains across Germany and the United Kingdom.
- Cooking:Volume-sensitive sauce and soup applications favor lower-cost soy and almond concentrates with less stringent viscosity requirements.
Baking commands the largest revenue pool, while desserts expand most quickly on premium reformulation trends.
End User:
Customer type fragmentation creates distinct procurement patterns, from supermarket retail to specialized ingredient-tech platforms serving independent foodservice operators.
- Bakeries:Industrial dessert producers in Germany absorb shelf-stable alt-dairy in private-label manufacturing, with REACH-compliant documentation serving as a procurement gate.
- Restaurants:Independent UK bakeries source through plant-based ingredient brokers who bundle concentrates with technical formulation support, bypassing traditional distributors.
- Food Service:EU Green Deal procurement mandates now require plant-based alternatives in public sector contracts, creating institutional demand pull.
- Households:Supermarket dominance persists despite online retail channel expansion for specialty baking concentrates.
Bakeries anchor volume demand, with restaurants gaining share fastest through channel fragmentation toward specialized brokers.
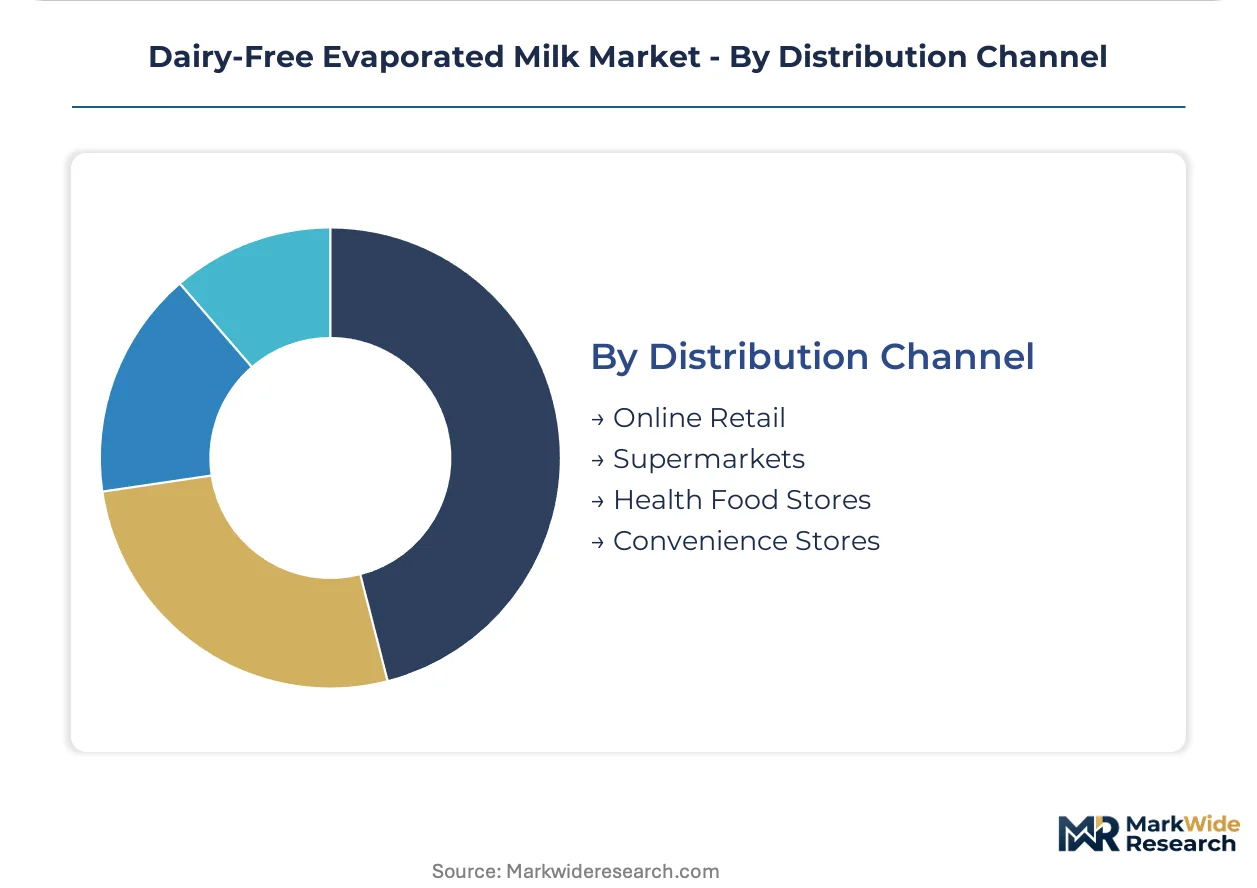
Distribution Channel:
Supply concentration in established retail networks competes with direct-to-consumer models that circumvent slotting fee structures.
- Supermarkets:Alpro and Oatly leverage broad retail distribution across British and German supermarkets to maintain household purchase dominance.
- Online Retail:Subscription models for specialty baking concentrates bypass supermarket slotting fees, expanding fastest among distribution pathways.
- Health Food Stores:Niche positioning for organic-certified concentrates serves allergen-sensitive consumers in urban centers.
- Convenience Stores:Limited SKU availability restricts this channel primarily to single-serve coffee creamer formats.
Supermarkets retain volume leadership, with online retail climbing fastest on subscription model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food chemists and plant protein engineers concentrate in Germany's industrial baking corridor and Britain's ingredient-tech hubs, anchoring European reformulation expertise for shelf-stable alt-dairy applications.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia absorb bulk volumes of oat-based concentrates for private-label dessert manufacturing. REACH chemical disclosure protocols now serve as procurement gates, rejecting suppliers with incomplete additive documentation. Stuttgart's food-tech cluster houses vacuum evaporation specialists serving mid-sized co-manufacturers.
United Kingdom
Independent bakeries across London and the Midlands source coconut and oat concentrates through specialized plant-based ingredient brokers rather than traditional distributors. EFSA novel food assessments govern approval timelines for emerging extraction technologies. Manchester's food innovation district incubates direct-to-consumer subscription models for specialty baking concentrates.
France
Premium dessert producers in Île-de-France command margin premiums for coconut milk concentrates where fat-driven texture outcomes determine competitive positioning. EU Green Deal procurement mandates now require plant-based alternatives in public sector foodservice contracts. Lyon's gastronomy cluster drives technical formulation support demand from commercial kitchens testing alt-dairy suppliers.
Italy
Gelato and pastry cream manufacturers in Emilia-Romagna and Lombardy require 60-80% moisture reduction thresholds that only oat and coconut concentrates reliably achieve. EMA food contact guidelines extend safety validation timelines for novel processing aids. Bologna's food machinery corridor supplies membrane filtration systems enabling smaller-batch, multi-feedstock concentrate production.
Netherlands
Ingredient traders in the Randstad region coordinate tropical commodity sourcing for coconut fat supply chains serving European concentrate manufacturers. ECHA enforcement inspections elevated compliance costs for processing aid documentation. Wageningen's food research cluster advances enzymatic extraction methods for low-temperature protein stability in oat formulations.
Dairy-Free Evaporated Milk Market Competitive Environment
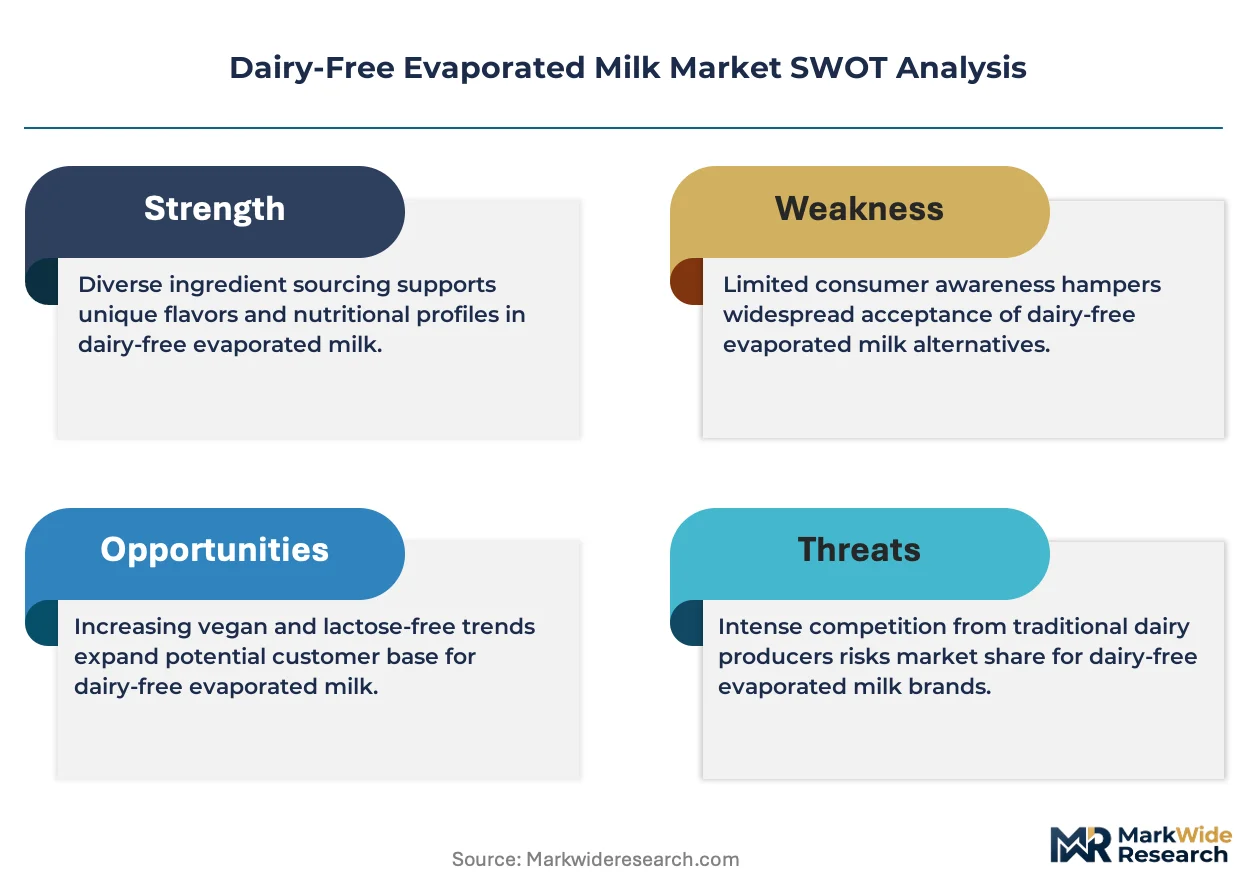
Capital-heavy producers with integrated extraction infrastructure compete with asset-light brand builders who outsource concentration to third-party co-manufacturers. The vendor base organizes around three archetypes: oat specialists leveraging Scandinavian processing heritage, coconut concentrate traders controlling tropical supply chains, and diversified plant-dairy portfolios spanning multiple bases. Competitive moves concentrate on securing EFSA pre-validated chemical safety dossiers and retrofitting legacy dairy equipment for acidic plant formulations.
Within the oat-specialist tier, Oatly anchors European supply through its Malmö production infrastructure while Califia Farms leverages extraction technology to sustain premium positioning in commercial kitchens. Alpro competes via broad retail distribution across British and German supermarkets, representing the diversified portfolio archetype with multi-base capabilities.
| Leading Market Players |
|---|
| So Delicious Dairy Free |
| Pacific Foods |
| Oatly |
| Elmhurst 1925 |
| Ripple Foods |
| Califia Farms |
| Alpro |
| Forager Project |
| Silk |
| Others |
Value Chain & Pricing Dynamics
Oat futures pricing and coconut oil commodity benchmarks cascade through European dairy-free evaporated milk supply chains, compressing margin structures for concentrate manufacturers while amplifying pricing power for integrated processors with captive tropical sourcing. This input-cost architecture stratifies finished goods across premium coconut-fat concentrates, mid-tier oat-based formulations, and economy-positioned almond alternatives.
Pricing Analysis
Bundled technical formulation services now command 15-25% premiums over unbundled commodity concentrates in commercial bakery procurement. Three-tier pricing structure across premium, standard, and economy levels reflects REACH compliance documentation depth, with fully-audited suppliers capturing institutional contracts. Cost compression in the economy tier is intensifying because Asian commodity traders are flooding spot markets with unbranded coconut concentrates. Private-label dessert manufacturers in Germany exhibit highest price sensitivity, while French premium gelato producers absorb premium tiers without volume negotiation.
Supply Chain Analysis
Container freight rates from Southeast Asian coconut processing hubs to Rotterdam anchor landed cost structures for fat-intensive concentrates. Supply concentrates in Indonesia, the Philippines, and Sri Lanka for coconut fat feedstocks, while oat protein draws from Swedish and Finnish agricultural cooperatives. Single-source vulnerability in tropical commodity sourcing exposes margin stability to climate-induced harvest volatility. Distribution runs through specialized plant-based ingredient brokers in the United Kingdom and broadline foodservice distributors in Germany, with direct-to-consumer subscription models bypassing traditional retail slotting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost differentials between established European suppliers and emerging Asian concentrate exporters create geographic-arbitrage opportunities for procurement restructuring, with German industrial bakeries already shifting sourcing toward pre-validated domestic co-manufacturers.
For Market Incumbents: Acquire membrane filtration equipment fleets to modularize production across multi-feedstock configurations without dedicated single-product lines. Secure EFSA pre-validated chemical safety dossiers before ECHA enforcement escalates documentation requirements. Capacity addition in Stuttgart's food-tech corridor defends against mid-sized co-manufacturers compressing minimum efficient scale thresholds. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models for specialty baking concentrates to circumvent supermarket slotting fee barriers. Target underpenetrated contract manufacturing demand in German private-label dessert production, where REACH-compliant documentation serves as a procurement gate. Ingredient-tech platform partnerships in the United Kingdom offer the most penetrable channel for bypassing traditional foodservice distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized European co-manufacturers possessing modular vacuum evaporation infrastructure and pre-validated REACH documentation. Long-term viability hinges on enzymatic processing expertise scarcity constraining capacity scaling for oat concentrate producers. Watch EFSA rulings on novel extraction technologies as the inflection indicator for first-mover windows in emerging plant bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Protein Supply | Captive sourcing from Scandinavian agricultural cooperatives insulates margin structures from commodity volatility. |
| EFSA Pre-Validation Investment | Pre-validated chemical safety dossiers differentiate suppliers as REACH enforcement elevates compliance costs. |
| Membrane Filtration Modularization | Smaller-batch multi-feedstock systems compress minimum efficient scale thresholds for mid-sized co-manufacturers. |
| Direct-to-Consumer Subscription Launch | Specialty baking concentrate subscriptions bypass supermarket slotting fees and capture household premium willingness. |
| Enzymatic Processing R&D Partnership | Wageningen's food research cluster advances low-temperature protein stability methods for oat formulation parity. |
Study Parameters
Multiple input streams — technical interviews with vacuum evaporation equipment specialists, procurement discussions with German industrial bakery purchasing directors, and regulatory consultations with ECHA compliance officers — were reconciled against secondary validation from EU Green Deal policy documentation, REACH chemical safety protocols, and EFSA novel food assessment records. Bottom-up volume modeling across product type, application, and distribution channel dimensions was triangulated with top-down market sizing from customs trade data and foodservice distribution channel audits.
Historical volume trajectories were cross-referenced against expert panel inputs from oat milk extraction technologists and coconut concentrate traders to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type differentiation, application viscosity requirements, end-user procurement patterns, and distribution channel fragmentation. CAGRs were derived from regression analysis of reformulation adoption curves in European commercial kitchens, with EFSA approval timelines and EU Green Deal procurement mandate implementation serving as industry-specific forecast modifiers.
Several conditions sit outside the modeled scope, including abrupt EFSA rulings banning specific enzymatic processing methods, tropical commodity supply disruptions from climate events, and tariff restructuring on Southeast Asian coconut fat imports. Forecasts reflect documented assumptions about reformulation adoption elasticity and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context, particularly regarding REACH compliance cost absorption capacity and tropical sourcing relationship depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Chickpea Milk Market